
 Africa Vegetable Seed Market | 2026-2036
Africa Vegetable Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Vegetable Seed Market Outlook
Smallholder buyer fragmentation across Sub-Saharan Africa is broadening as farmer cooperatives and contract farming schemes multiply. East-West Seed anchors its position through deep distribution networks in Southeast Africa. Bayer AG leverages its vegetable seed R&D pipeline to compete in high-value crop segments. Seed Co Limited dominates Southern African markets with strong brand recognition among commercial growers.
Africa vegetable seed comprises genetically stable or hybridized propagules bred for specific agro-ecological zones, with germination rates, vigor indices, and disease resistance markers as core quality parameters. These seeds supply fresh produce markets, processing industries, and export chains across the continent. Hybrid seeds command premium positioning due to yield consistency and pest resistance, while open-pollinated varieties retain cost advantages for resource-constrained smallholders. Agro-dealer channels still occupy the largest share of distribution volume, though direct sales to organized farmer groups are gaining share.
Kenya's Seed and Plant Varieties Act, South Africa's Plant Breeders' Rights framework, and the African Union's Seed Harmonization Protocol collectively govern variety certification, intellectual property, and cross-border trade. These regulatory layers shape market access timelines and compliance costs for international seed companies entering African markets. Stakeholders must monitor regulatory convergence progress and adapt variety portfolios to shifting phytosanitary requirements.
Market Dynamics
Climate-resilient hybrid varieties are absorbing procurement budgets across East African cooperatives as drought tolerance becomes a non-negotiable trait in seed selection criteria. This biological pivot is restructuring supplier relationships and variety registration priorities continent-wide.
Growth Catalysts
- Kenya's Seed and Plant Varieties Act:The revised certification timelines are accelerating variety release for drought-tolerant tomatoes and peppers in the Rift Valley. Commercial growers now access improved genetics eighteen months faster than prior regulatory cycles.
- Irrigation infrastructure:Ethiopia's central highlands and Nigeria's northern vegetable belts are expanding pump-fed production. Water security is converting rain-dependent smallholders into year-round seed customers.
- Farmer cooperative consolidation:Aggregated procurement across Kenyan and Tanzanian cooperatives is creating volume commitments that justify certified hybrid adoption. Collective bargaining power is displacing informal seed sourcing.
Market Restraints
- Phytosanitary compliance costs:Cross-border seed movement under the African Union's Seed Harmonization Protocol requires duplicate testing in destination countries. Kenyan exporters face additional laboratory verification in Uganda and Tanzania.
- Parental line concentration:Hybrid vegetable germplasm for tropical-adapted brassicas and solanaceous crops originates from limited European and Asian breeding programs. African seed companies remain dependent on licensed parental material.
- Currency volatility:Ethiopian birr and Nigerian naira depreciation against dollar-denominated royalty payments is compressing margins for licensed hybrid distribution. Importers absorb exchange risk or pass through to smallholder pricing.
Strategic Opportunities
- Anglophone West Africa corridor:Ghana and Senegal's organized vegetable sectors remain underpenetrated by certified hybrid suppliers. Ghana's greenhouse tomato expansion offers premium seed positioning.
- Digital agro-dealer networks:Mobile-enabled inventory tracking and farmer financing integration is emerging in Kenya. Platforms bundling seed credit with agronomic advice are capturing cooperative procurement.
- Export-oriented processing clusters:Ethiopia's industrial park tomato paste facilities and Senegal's French bean export channels require uniform maturity windows. Contract farming specifications are mandating single-source hybrid programs.
Industry Challenges
- Seed quality assurance staffing:National seed authorities in Tanzania and Uganda lack sufficient field inspectors for grow-out testing. Variety maintenance and rogueing protocols suffer from human resource gaps.
- Cold chain fragmentation:Hybrid seed viability depends on temperature-controlled storage from port to agro-dealer. Last-mile refrigeration gaps in rural Zambia and Malawi reduce effective germination rates below certified standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Vegetable Seed Market |
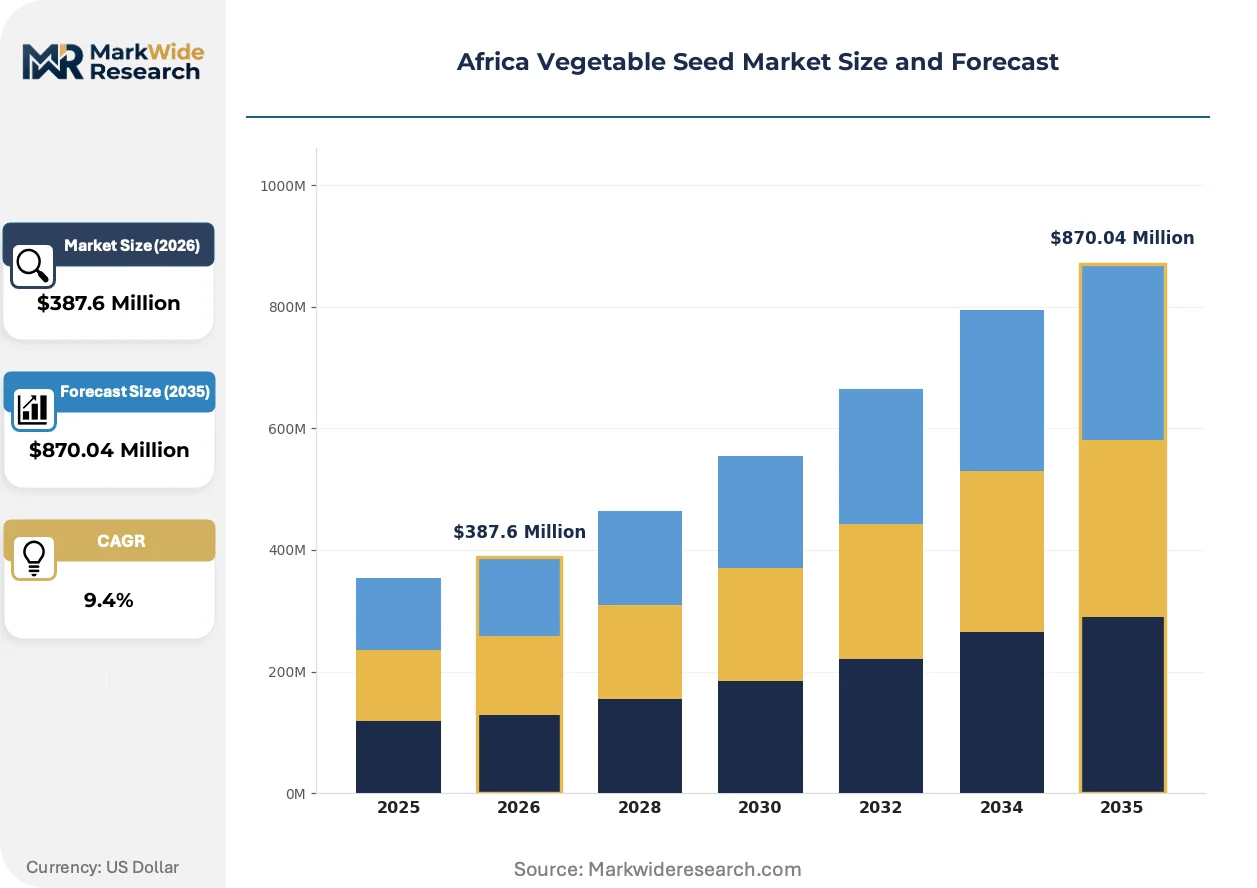
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $870.04 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Hybrid Seeds, Open-Pollinated Seeds, Heirloom Seeds, GMO Seeds Crop Variety: Tomatoes, Peppers, Cucumbers, Carrots Distribution Channel: Retail Stores, Online Platforms, Agro-Dealers, Direct Sales Packaging Type: Bulk Bags, Small Packs, Retail Packs, Eco-Friendly Packaging |
| Companies Covered | Rijk Zwaan, East-West Seed, Syngenta AG, Seed Co Limited, Starke Ayres, Bayer AG, Corteva Agriscience, Shalom Agriculture, Sakata Seed Southern Africa, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Vegetable Seed Market Strategic Shifts
Biological breeding tools and digital distribution infrastructure are converging to compress variety development cycles and reconfigure last-mile access. These shifts are altering who controls genetic improvement and how farmers encounter new varieties.
Marker-assisted selection is absorbing conventional phenotypic screening for disease resistance traits in tomato and pepper breeding pipelines. East African seed companies are licensing SNP-based selection platforms to accelerate bacterial wilt resistance stacking. This molecular pivot is compressing five-year breeding cycles into thirty-six-month variety release timelines.
Kenya's Seed and Plant Varieties Act amendments are mandating distinctness-uniformity-stability documentation for all commercial varieties. The regulatory burden is favoring capitalized breeders with dedicated trial station networks. Smaller seed enterprises are retreating from proprietary variety development toward licensed distribution arrangements.
Cooperative procurement officers are consolidating seed orders through digital platforms that aggregate demand across multiple farmer groups. Agro-dealer intermediaries in Tanzania are losing volume to direct manufacturer-cooperative contracts. This channel compression is most visible in Kenya's Mount Kenya vegetable belt where organized groups exceed five hundred members.
Africa Vegetable Seed Market Segmentation
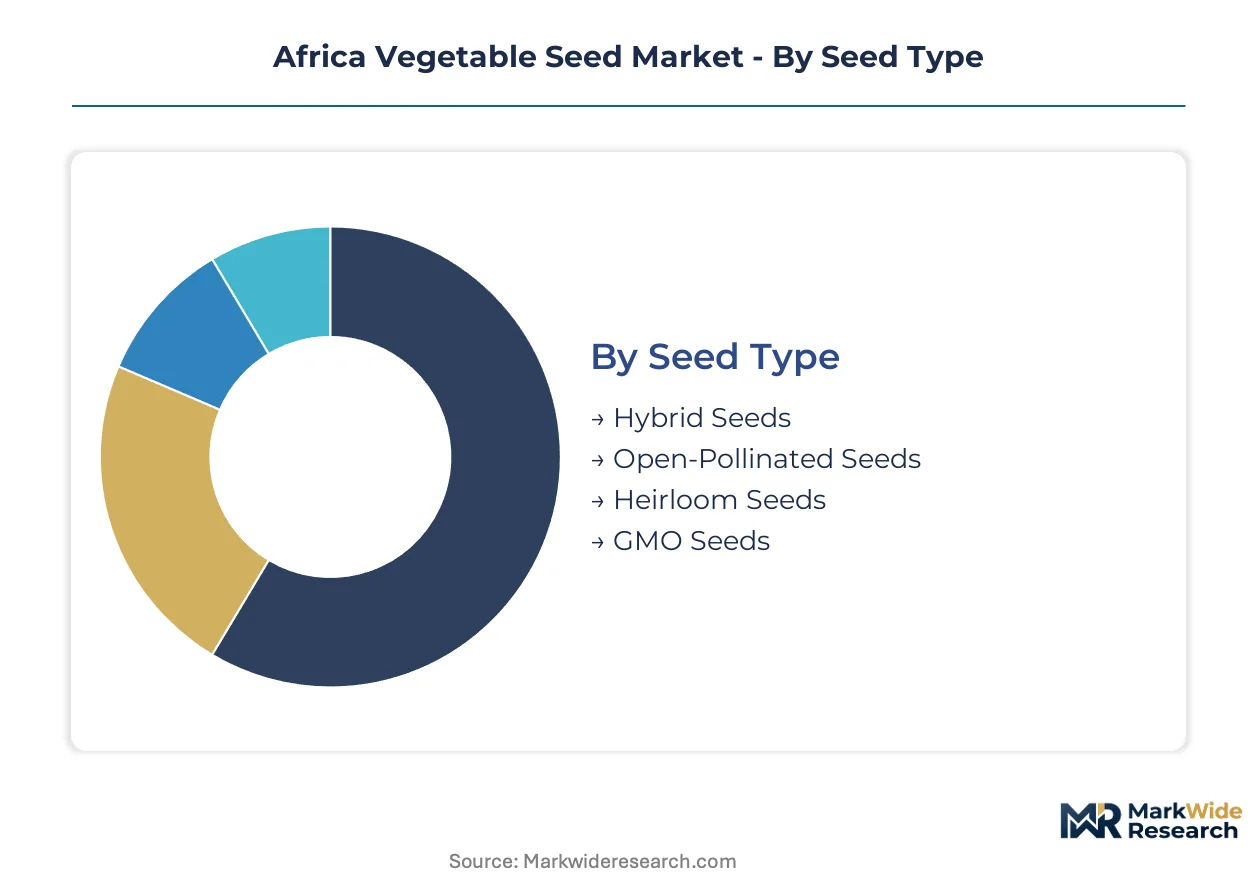
Vegetable seed procurement patterns across Africa diverge sharply between commercial growers seeking yield consistency and smallholders prioritizing cost accessibility. Understanding these segment boundaries clarifies where hybrid premiums command adoption versus where open-pollinated varieties retain dominance.
Seed Type:
Hybrid seeds capture the premium tier through yield guarantees and disease resistance, while open-pollinated varieties anchor volume sales among price-sensitive smallholders.
- Hybrid Seeds:Cross-pollinated varieties bred for specific agro-ecological zones with standardized germination rates and vigor indices. Demand concentrates in Kenya's Rift Valley commercial tomato operations where drought tolerance justifies royalty premiums. Farmer cooperatives in Ethiopia's central highlands are consolidating procurement around certified hybrid programs.
- Open-Pollinated Seeds:Genetically stable varieties produced through natural pollination with lower input costs and farmer-saved seed potential. Nigeria's northern vegetable belts depend on these for rain-fed pepper production where irrigation infrastructure remains sparse. Seed saving practices sustain informal distribution networks.
- Heirloom Seeds:Traditional landrace varieties preserved for specific culinary attributes and local adaptation. Niche demand persists in Senegal's French bean export corridors seeking distinct flavor profiles.
- GMO Seeds:Transgenic varieties with stacked insect resistance and herbicide tolerance traits. Regulatory barriers under Kenya's Seed and Plant Varieties Act restrict commercial deployment despite field trial activity.
Mature deployment sits with Open-Pollinated Seeds across smallholder systems. Newer deployment is concentrated in Hybrid Seeds within organized cooperative procurement.
Crop Variety:
Tomato and pepper genetics absorb the majority of breeding investment, reflecting their centrality to fresh produce markets and processing infrastructure.
- Tomatoes:Determinate and indeterminate varieties bred for processing paste consistency or fresh market shelf life. Ethiopia's industrial park paste facilities mandate uniform maturity windows that only single-source hybrid programs deliver. Kenya's greenhouse sector is climbing the fastest for premium cherry tomato seed demand.
- Peppers:Capsicum varieties spanning bell, habanero, and bird's eye types with heat tolerance stacking. Nigeria's northern belts are expanding irrigated production of Scotch bonnet varieties for regional sauce processing.
- Cucumbers:Parthenocarpic greenhouse varieties and open-field slicer types with downy mildew resistance. Ghana's emerging protected agriculture sector is testing hybrid gherkin seeds for European pickle export.
- Carrots:Nantes and Imperator types with nematode resistance and cylindrical root uniformity. Tanzania's highland vegetable cooperatives are trialing hybrid carrot programs for Dar es Salaam supermarket supply.
Processing contract specifications favor Tomato seed deployment. Fresh market volatility sustains Pepper seed diversity across informal channels.
Distribution Channel:
Channel selection tracks farmer organization level, with aggregated cooperatives bypassing traditional agro-dealer intermediaries.
- Agro-Dealers:Rural retail networks stocking multiple brands with limited technical advice. These outlets dominate Zambia and Malawi last-mile access despite cold chain gaps that compromise hybrid viability.
- Direct Sales:Manufacturer-to-cooperative contracts with volume pricing and embedded agronomic support. Kenya's Mount Kenya vegetable belt exceeds five hundred member groups consolidating orders through digital platforms.
- Retail Stores:Urban agricultural supply shops serving peri-urban hobby farmers and small-scale commercial operators. Nairobi and Addis Ababa outlets carry premium hybrid selections.
- Online Platforms:Mobile-enabled ordering with inventory tracking and credit bundling. Tanzanian agro-dealers are losing volume to manufacturer-direct digital procurement.
Physical infrastructure maturity rests with Agro-Dealers. Digital integration is expanding fastest through Direct Sales channels.
Packaging Type:
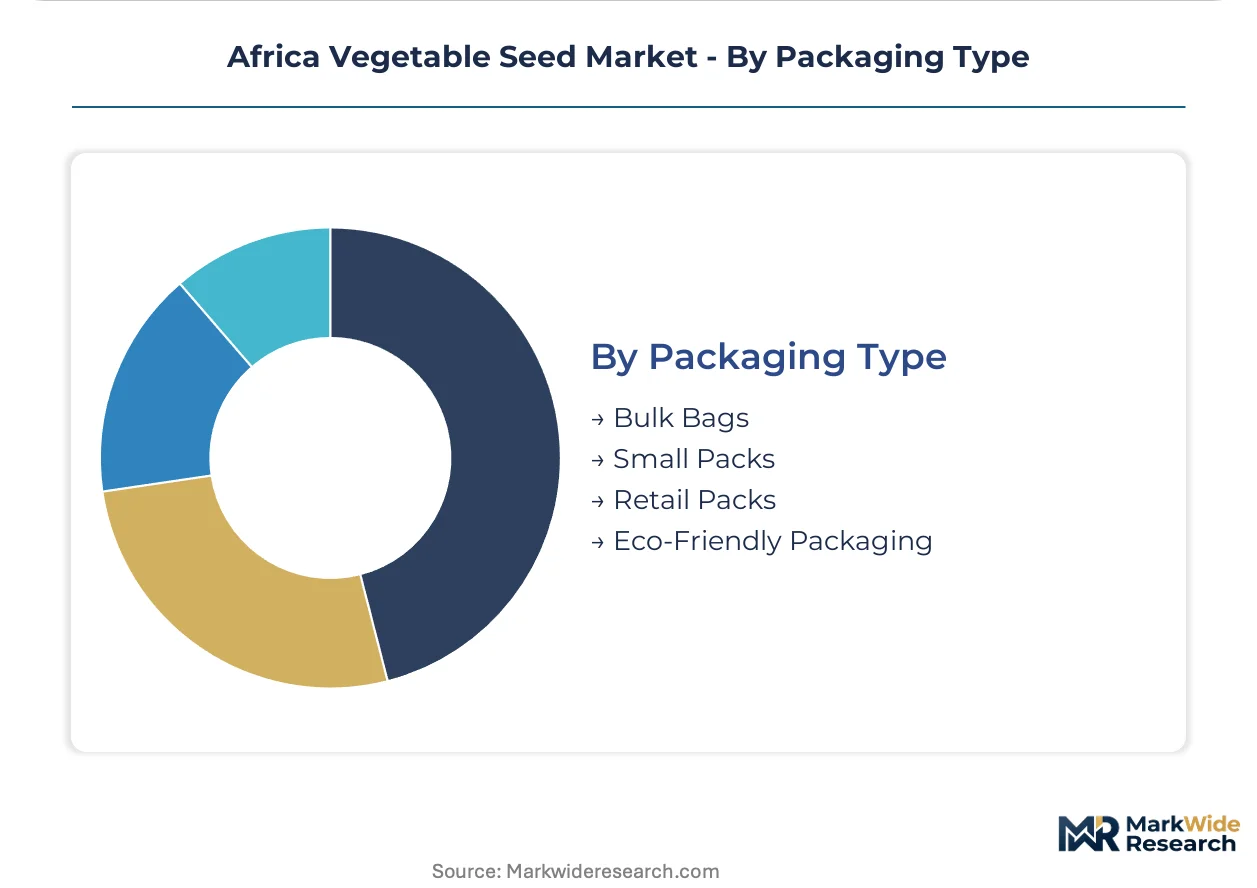
Packaging economics reflect purchase scale, from bulk institutional procurement to smallholder trial quantities.
- Bulk Bags:Institutional quantities for commercial growers and cooperative aggregation. Large-scale tomato operations in Ethiopia's central highlands receive climate-controlled bulk shipments direct from licensed distributors.
- Small Packs:Trial quantities enabling smallholder experimentation with new varieties. Kenyan cooperative officers distribute these for grow-out validation before committing to bulk procurement.
- Retail Packs:Branded consumer-facing units with germination rate guarantees. Urban garden centers in Lagos and Accra stock these for peri-urban producers.
- Eco-Friendly Packaging:Biodegradable materials responding to European export chain sustainability requirements. Senegal's French bean exporters are mandating these for contract farming seed inputs.
Volume concentration remains with Bulk Bags for commercial operations. Sustainability specifications are driving fastest expansion in Eco-Friendly Packaging adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for certified vegetable seed clusters in East Africa's Rift Valley and West Africa's northern irrigation belts. Nigeria and Ethiopia absorb the largest procurement volumes for tomato and pepper genetics. Regulatory harmonization under the African Union's Seed Harmonization Protocol is reshaping cross-border distribution corridors.
Kenya
Commercial tomato operations in the Rift Valley drive hybrid seed procurement at scale. Kenya's Seed and Plant Varieties Act compresses variety release timelines for drought-tolerant genetics. The Mount Kenya vegetable belt hosts cooperative groups exceeding five hundred members consolidating direct manufacturer orders.
Nigeria
Northern vegetable belts around Kano and Kaduna are expanding irrigated pepper production for regional processing. The National Agricultural Seeds Council governs variety certification and import phytosanitary requirements. Scotch bonnet cultivation clusters are converting rain-fed smallholders into year-round certified seed customers.
Ethiopia
Central highland irrigation schemes are scaling tomato paste production for industrial park facilities. The Ethiopian Agricultural Authority administers variety registration under regional harmonization protocols. The Awash Valley commands bulk hybrid shipments direct from licensed distributors with climate-controlled logistics.
Tanzania
Highland vegetable cooperatives around Arusha and Moshi are trialing hybrid carrot programs for Dar es Salaam supermarket supply. The Tanzania Official Seed Certification Institute faces field inspector shortages that delay grow-out testing. Digital platforms are displacing traditional agro-dealer intermediaries in cooperative procurement.
Senegal
French bean export corridors near Saint-Louis mandate eco-friendly packaging for contract farming seed inputs. The national seed service operates under ECOWAS harmonization standards for cross-border trade. Greenhouse tomato expansion around Dakar offers premium positioning for certified hybrid suppliers.
Africa Vegetable Seed Market Competitive Environment
Dutch and Japanese breeding houses anchor the premium tier; Southern African distributors hold regional volume positions. The vendor base splits between integrated multinationals with proprietary R&D pipelines and licensed distributors dependent on imported parental material. Three archetypes dominate: molecular breeding specialists, regional distribution aggregators, and cooperative-facing direct sales operators. Strategic moves concentrate on digital platform integration and cold chain partnerships for last-mile viability.
Within the premium breeding tier, Rijk Zwaan and Syngenta AG exemplify molecular platform licensors compressing trait development cycles. East-West Seed occupies a position as the Southeast African distribution anchor with deep cooperative networks. Bayer AG sits within the integrated life sciences archetype leveraging crop science R&D spillover into vegetable genetics.
| Leading Market Players |
|---|
| Rijk Zwaan |
| East-West Seed |
| Syngenta AG |
| Seed Co Limited |
| Starke Ayres |
| Bayer AG |
| Corteva Agriscience |
| Shalom Agriculture |
| Sakata Seed Southern Africa |
| Others |
Value Chain & Pricing Dynamics
Farmer cooperative consolidation across Kenya's Mount Kenya belt and Ethiopia's central highlands is compressing price negotiation leverage toward volume-based contract structures. Hybrid seed premiums now track irrigation infrastructure access and phytosanitary certification tiers rather than brand positioning alone.
Pricing Analysis
Volume procurement by organized cooperatives commands standard-tier pricing, while fragmented smallholder purchases absorb premium markups through agro-dealer intermediaries. Price differentiation centers on germination rate guarantees and drought-tolerance trait stacking under Kenya's Seed and Plant Varieties Act certification. Pricing pressure intensifies in Nigerian naira and Ethiopian birr corridors as currency depreciation against dollar-denominated royalty payments forces margin compression. Smallholders in rain-fed systems exhibit highest price sensitivity; commercial greenhouse operators in Kenya's Rift Valley accept premium positioning for genetic consistency.
Supply Chain Analysis
Dual-sourcing mandates from Ethiopian industrial park processors and Senegalese French bean exporters require qualified suppliers in both European and Asian breeding centers. Parental line germplasm draws from Netherlands, Japan, and Israel breeding programs; cold chain logistics rest on South African and Kenyan distribution hubs. Single-source vulnerability concentrates around licensed hybrid distribution agreements with limited African field multiplication capacity. Distribution runs through climate-controlled bulk shipments to cooperative aggregation points, with last-mile agro-dealer networks filling rural access gaps in Zambia and Malawi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marker-assisted selection platforms are displacing conventional phenotypic breeding pipelines, compressing variety development cycles from five years to thirty-six months. This molecular pivot favors capitalized breeders with dedicated trial station networks under Kenya's revised distinctness-uniformity-stability documentation requirements.
For Market Incumbents: To counter digital platform disintermediation of traditional agro-dealer channels, anchor position through backward integration into cold chain logistics partnerships and cooperative-facing direct sales teams. Prioritize licensing SNP-based selection platforms to accelerate bacterial wilt resistance stacking in tomato and pepper genetics. For New Entrants and Emerging Players: Enter via Ghana's underpenetrated greenhouse tomato sector and Senegal's French bean export corridors where certified hybrid supplier presence remains sparse. Bundle mobile-enabled inventory tracking with farmer financing integration to capture cooperative procurement officers consolidating orders across multiple farmer groups. For Investors and Strategic Acquirers: The window for entry favors regional distribution aggregators with established phytosanitary compliance capabilities and cooperative network relationships. Acquisition targets should demonstrate licensed parental material access and cold chain infrastructure. Watch regulatory convergence progress under the African Union's Seed Harmonization Protocol as inflection indicator for cross-border scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Marker-Assisted Selection Platform Licensing | Compresses breeding cycles for bacterial wilt resistance in East African tomato programs. |
| Cold Chain Partnership Development | Secures hybrid viability from port to agro-dealer in Zambia and Malawi last-mile networks. |
| Cooperative Direct Sales Channel Buildout | Captures volume procurement shifting from Tanzanian agro-dealer intermediaries to manufacturer contracts. |
| Phytosanitary Compliance Infrastructure Investment | Accelerates variety release timelines under Kenya's Seed and Plant Varieties Act certification pathways. |
| Drought-Tolerance Trait Stacking R&D | Addresses non-negotiable selection criteria emerging across East African cooperative procurement budgets. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across seed company breeding directors, national seed authority field inspectors, cooperative procurement officers, and agro-dealer network managers. Kenya Seed and Plant Varieties Act documentation, African Union Seed Harmonization Protocol progress reports, and Ethiopia Agricultural Authority variety registration databases provided regulatory trajectory validation. Bottom-up procurement volume estimates from farmer cooperative aggregation records were triangulated against top-down breeder shipment data.
Data-stream reconciliation across seed type, crop variety, distribution channel, and packaging format dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume and value trajectories modeling cooperative consolidation rates, irrigation infrastructure expansion, and regulatory harmonization progress. Forecast inputs incorporated phytosanitary compliance cost trajectories and currency volatility assumptions for naira and birr corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated regulatory divergence or prolonged currency depreciation. Deviation in African Union Seed Harmonization Protocol implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Arnica Montana Market
Seeds
Europe Cannabis Seeds Market
Seeds
Africa Peas Market
Seeds
Russia Forage Seed Market
Seeds
Thailand Seed Market
Seeds
Sesame Seeds Market
Seeds
China Rice Seed Market
Seeds
Europe Sesame Seed Market
Seeds
Global Maize Seed Market
Seeds
Europe Vegetable Seed Market
Seeds
Spain Forage Seed Market
Seeds
Cover Crop Seed Varieties Market
Seeds
Myanmar Seed Market
Seeds
Faba Beans Market
Seeds
Europe Amaranth Market
Seeds
Fruit Tomatoes Seed Market