
 North America Wheat Market | 2026-2036
North America Wheat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wheat Market Analytics
Consolidation among artisan bakeries and regional pasta manufacturers is repositioning procurement patterns across the North American wheat value chain. Cargill leverages its elevator network and origination infrastructure to secure premium Hard Red Spring supply from the Northern Plains. Archer Daniels Midland Company sustains large-scale milling operations optimized for high-volume bakery and brewing contracts. Ardent Mills differentiates through specialty flour portfolios targeting clean-label and organic bakery segments.
North America wheat encompasses cultivated Triticum aestivum and Triticum durum varieties graded by protein content, kernel hardness, and falling number, with primary commercial purpose as a milled input for baked goods, pasta, animal nutrition, and malt beverages. Hard Red Winter occupies the largest volume share due to its versatility in commercial bread production, while Hard Red Spring commands premium pricing from protein-seeking millers and pasta manufacturers. Durum Wheat maintains concentrated demand in North Dakota and Canada for semolina extraction, with Soft Red Winter serving regional cake and pastry applications across the eastern Corn Belt.
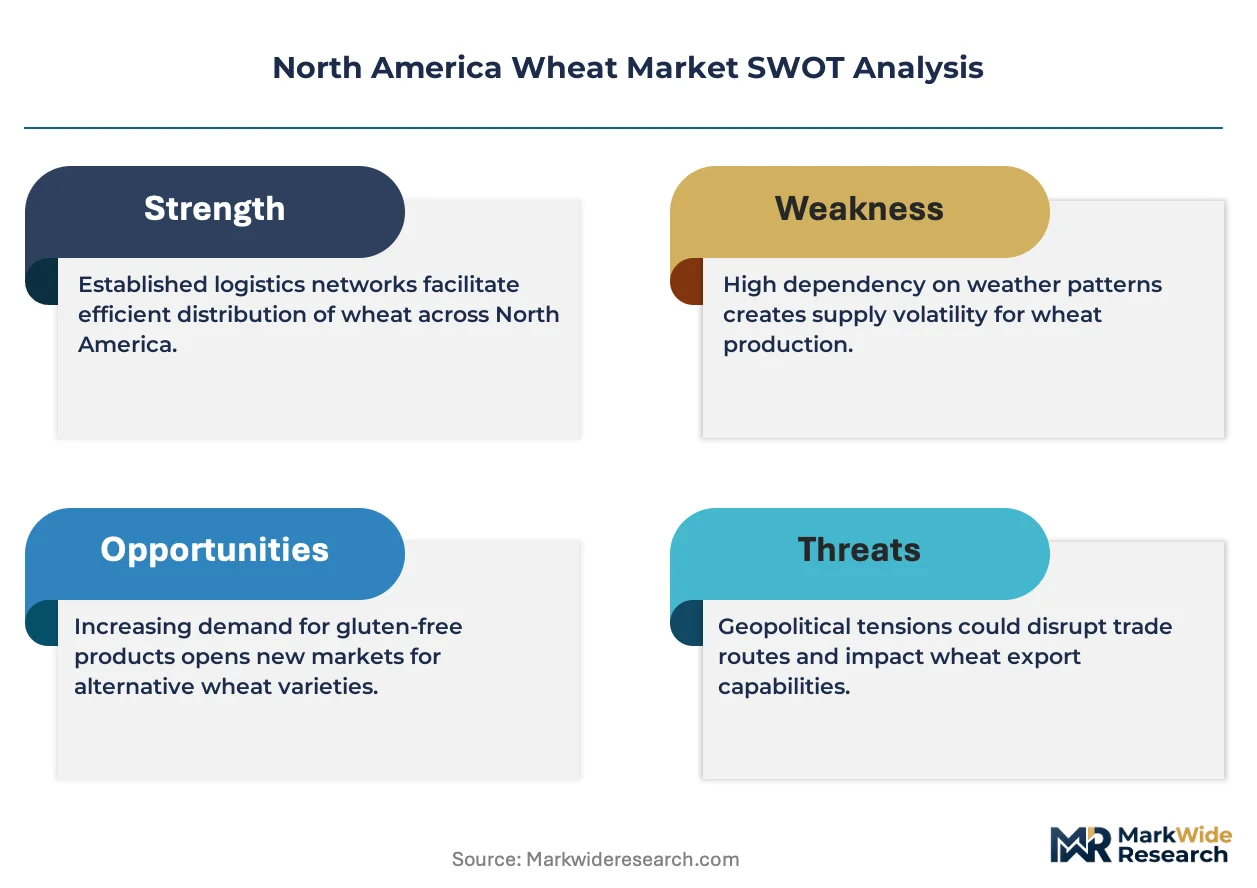
The USDA administers crop insurance and conservation programs that directly influence farmer planting decisions and varietal selection across the United States, while the Canadian Grain Commission sets grading standards that govern cross-border trade flows and export eligibility. The EPA's renewable fuel standards and state-level low-carbon fuel programs indirectly shape wheat acreage competition with corn and soybean rotations. Stakeholders must monitor how drought-resistant seed genetics and evolving clean-label certification requirements will reshape varietal premiums and elevator procurement criteria.
Market Dynamics
Precision agriculture adoption across the Northern Plains is compressing planting economics and accelerating varietal specialization, as farmers respond to USDA crop insurance recalibrations that now reward protein premiums and drought-resistant genetics.
Growth Catalysts
- USDA Conservation Reserve Program:Incentive structures for cover-crop integration are expanding wheat acreage in marginal Corn Belt zones previously dominated by continuous corn rotations.
- Artisan bakery consolidation:Regional pasta manufacturers and specialty bakers are locking multi-year Hard Red Spring contracts, creating guaranteed offtake for protein-dominant varieties.
- Sensor-enabled variable-rate fertilization:Nitrogen application optimization is lifting average protein content in Kansas and Oklahoma Hard Red Winter zones, qualifying more bushels for premium milling tiers.
Market Restraints
- Input cost volatility:Ammonium nitrate and diesel price swings are compressing margins for no-till wheat operations in the Southern Plains.
- Canadian Grain Commission grading friction:Cross-border protein measurement discrepancies are delaying elevator receipts and export eligibility for Northern Plains growers.
- Hybrid corn substitution:Improved drought-tolerant corn genetics are capturing rotational acreage in eastern Nebraska and Iowa fringe zones.
Strategic Opportunities
- Canadian prairie organic transition:Saskatchewan and Manitoba growers are certifying acreage for EU-bound organic durum contracts at 40% price premiums to conventional.
- Renewable diesel feedstock pivot:Cover-crop wheat straw is attracting biofuel processor offtake agreements in Iowa and Illinois.
- Blockchain-enabled origin verification:Elevator networks are piloting immutable traceability for clean-label bakery customers demanding varietal provenance documentation.
Industry Challenges
- Certified crop advisor shortage:Precision agriculture implementation is bottlenecked by insufficient trained agronomists in Montana and the Dakotas.
- Legacy elevator automation:Protein testing equipment at rural receiving stations requires capital replacement to handle rising specialty-contract volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wheat Market |
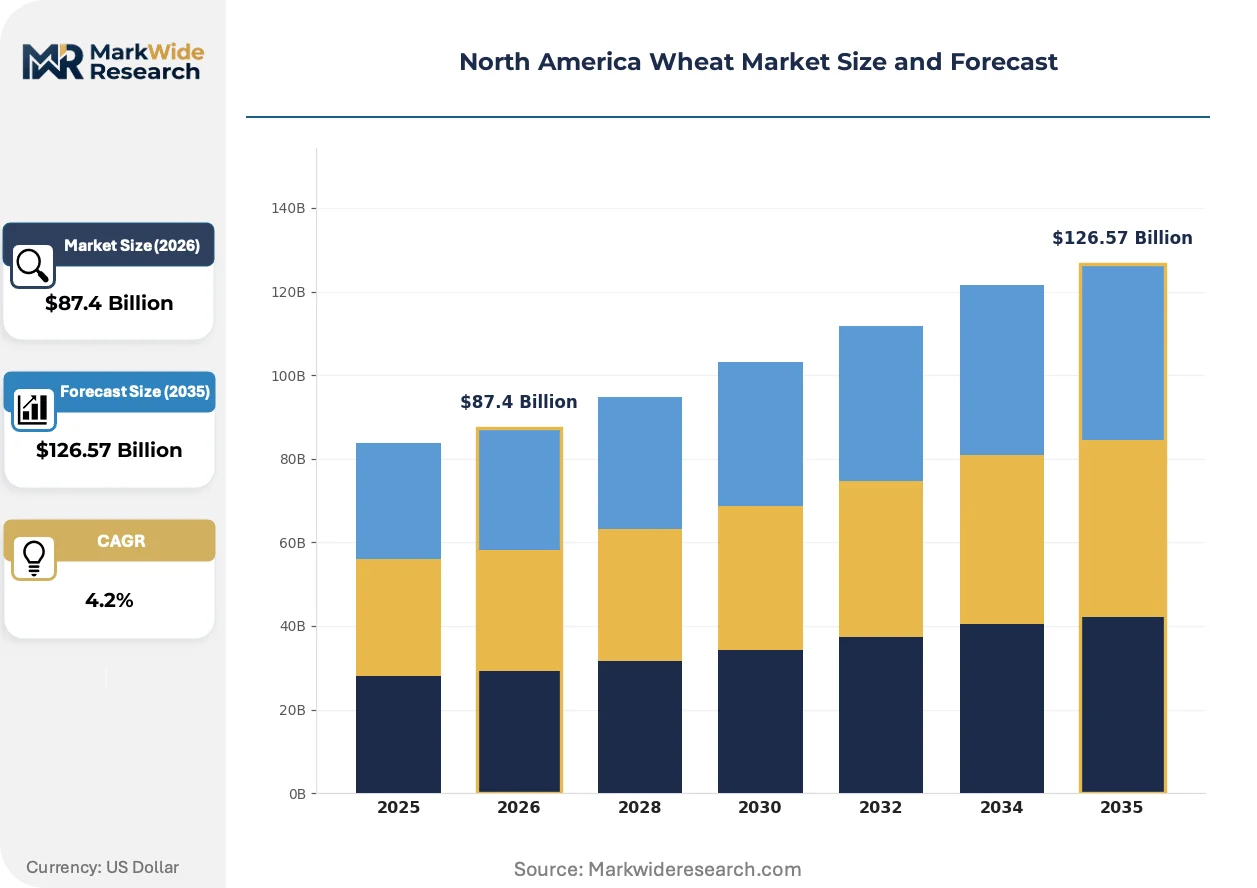
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $126.57 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Durum Wheat, Hard Red Winter, Soft Red Winter, Hard Red Spring End Use: Baking, Pasta Production, Animal Feed, Brewery Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales Grade: Number 1, Number 2, Number 3, Feed Grade |
| Companies Covered | Ardent Mills, Archer Daniels Midland Company, Cargill, CHS, Grain Craft, Miller Milling, General Mills, The Andersons, Bunge North America, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wheat Market Evolving Landscape
Digital agronomy and protein-based contract structures are fragmenting traditional commodity flows, creating parallel supply chains for identity-preserved wheat that bypass conventional grade-pooling mechanisms.
Hyperspectral imaging at combine harvest is decentralizing quality assessment by enabling real-time protein and moisture mapping before grain leaves the field. Progressive growers in North Dakota and Minnesota are adopting handheld NIR units to segregate loads at harvest, directing high-protein lots to premium pasta contracts while dumping standard grades into commodity channels. This capability is decentralizing elevator bargaining power and compressing price discovery timelines.
USDA's updated crop insurance frameworks now incorporate enterprise units by practice type, rewarding farmers who split operations between conventional and certified organic wheat. The Risk Management Agency's revised revenue protection formulas are accelerating organic transition in Kansas and Colorado. Specialty millers in the Mountain West are responding by pre-paying transition premiums to lock three-year organic supply.
Bakeries are unbundling flour procurement from legacy distributor relationships, establishing direct elevator contracts for single-origin Hard Red Spring with specified falling numbers. Large artisan chains in Minneapolis and Denver are bypassing regional millers to source directly from North Dakota cooperatives, specifying harvest date and storage conditions. This disintermediation is most visible in metropolitan markets where clean-label positioning commands shelf price premiums.
North America Wheat Market Segmentation
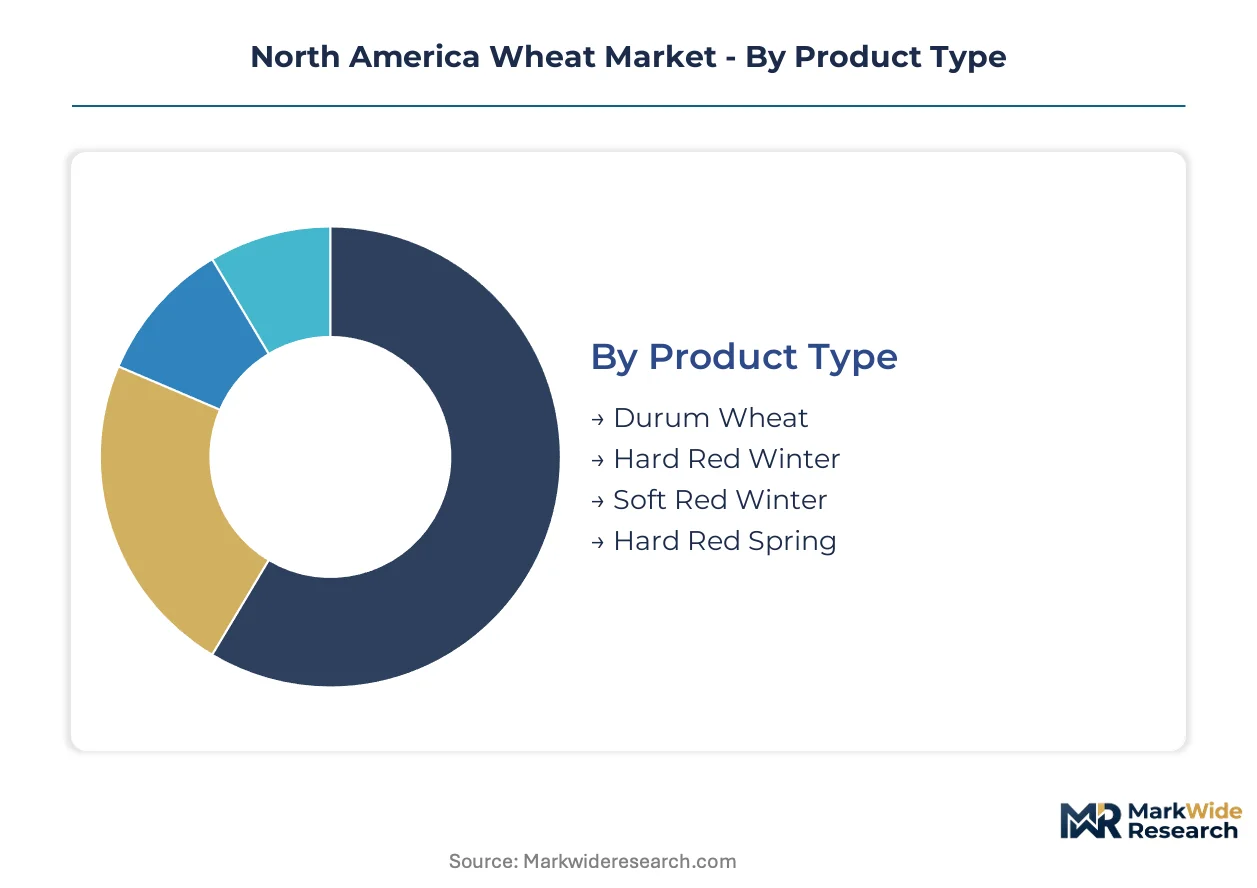
Varietal specialization and protein-based grading systems fragment wheat flows into parallel supply chains. Each segment carries distinct certification burdens from USDA crop insurance frameworks and Canadian Grain Commission standards that govern cross-border eligibility.
Product Type:
USDA crop insurance recalibrations and Canadian Grain Commission grading protocols impose certification burdens unevenly across varieties, with protein documentation requirements most stringent for premium milling grades.
- Hard Red Spring:High-protein Triticum aestivum variety with kernel hardness exceeding 60% and protein content ranging 13-16%. Demand concentrates in Minneapolis and Denver artisan bakeries sourcing directly from North Dakota cooperatives with specified falling numbers. USDA's revised revenue protection formulas reward protein premiums, accelerating farmer specialization in the Northern Plains.
- Hard Red Winter:Versatile bread wheat dominating commercial bakery contracts across Kansas and Oklahoma. Sensor-enabled variable-rate fertilization is lifting average protein content, qualifying more bushels for premium milling tiers previously reserved for spring varieties.
- Durum Wheat:Triticum durum with semolina extraction properties concentrated in North Dakota and Saskatchewan for pasta manufacturing. Canadian Grain Commission grading friction around protein measurement creates cross-border documentation delays.
- Soft Red Winter:Lower protein variety serving regional cake and pastry applications across the eastern Corn Belt. USDA Conservation Reserve Program incentives are expanding acreage in marginal Ohio and Indiana zones.
Leading the category by volume: Hard Red Winter. Growing fastest: Hard Red Spring.
End Use:
Customer procurement patterns split the market by volume scale and margin structure, with large-scale manufacturers demanding grade-pooled efficiency while specialty buyers pay premiums for identity-preserved supply.
- Baking:Commercial bread production absorbs the largest volume share, with regional pasta manufacturers and artisan bakeries locking multi-year Hard Red Spring contracts for guaranteed protein-dominant supply.
- Pasta Production:Semolina extraction demands concentrate in North Dakota and Minnesota, where progressive growers use handheld NIR units to segregate high-protein lots at harvest for premium contracts.
- Animal Feed:Feed Grade wheat competes with corn in rations across the Southern Plains, where ammonium nitrate price volatility compresses margins for no-till operations.
- Brewery:Malt beverage manufacturers source specific varieties with diastatic power requirements, with large-scale brewing contracts flowing through Archer Daniels Midland Company milling infrastructure.
Volume leadership sits with Baking. Steepest expansion trajectory: Pasta Production.
Distribution Channel:
Channel selection determines price discovery transparency and origin documentation capabilities, with direct relationships enabling blockchain traceability pilots for clean-label bakery customers.
- Wholesale:Elevator networks and regional millers handle grade-pooled commodity flows, with Cargill leveraging origination infrastructure to secure premium supply across the Northern Plains.
- Direct Sales:Minneapolis and Denver artisan chains bypass regional millers to contract directly with North Dakota cooperatives, specifying harvest date and storage conditions for single-origin flour.
- Retail:Packaged flour sales through grocery channels serve home bakers and small commercial operations, with Ardent Mills specialty portfolios targeting clean-label positioning.
- E-commerce:Emerging channel for identity-preserved varieties with varietal provenance documentation, though legacy elevator automation bottlenecks limit specialty-contract volume handling.
Wholesale dominates volume. Direct Sales climbs fastest as bakery disintermediation accelerates.
Grade:
Grade classification governs export eligibility and premium capture, with protein testing equipment at rural receiving stations requiring capital replacement to handle rising specialty-contract volumes.
- Number 1:Highest milling grade with test weight above 60 lbs/bu and minimal foreign material. Required for EU-bound organic durum contracts commanding 40% premiums to conventional in Saskatchewan and Manitoba.
- Number 2:Standard milling grade absorbing the majority of commercial bakery and brewing contracts, with falling number specifications varying by end-use processor.
- Number 3:Discounted grade diverted to domestic feed or ethanol markets when protein or damage thresholds fail premium tiers.
- Feed Grade:Lowest classification excluded from human food channels, competing with corn in livestock rations across drought-affected Southern Plains zones.
Number 2 grade leads volume. Number 1 grade expands most quickly on organic transition premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artisan bakery demand concentrates in Minneapolis and Denver, where specialty millers source single-origin Hard Red Spring directly from Northern Plains cooperatives. Protein premiums and clean-label positioning drive procurement patterns across metropolitan markets. USDA and Canadian Grain Commission frameworks govern cross-border trade flows and varietal certification requirements.
United States
Hard Red Spring demand from artisan bakeries and regional pasta manufacturers locks multi-year contracts with North Dakota cooperatives. USDA's revised revenue protection formulas reward protein premiums and drought-resistant genetics, accelerating farmer specialization. Minneapolis anchors direct sourcing relationships where bakery chains specify harvest dates and falling numbers.
Canada
Saskatchewan and Manitoba growers certify organic acreage for EU-bound durum contracts at substantial premiums to conventional grades. Canadian Grain Commission protein measurement standards create documentation friction at cross-border elevator receipts. Prairie elevator networks pilot blockchain traceability for clean-label bakery customers demanding varietal provenance.
Mexico
Semolina extraction demand from domestic pasta manufacturers imports Hard Red Spring and Durum varieties from US and Canadian origins. Mexico's national agricultural regulator oversees grain import standards and phytosanitary certification requirements. Northern border states concentrate milling infrastructure serving both domestic food manufacturers and re-export arrangements.
North America Wheat Market Competitive Landscape
US-based integrated grain handlers anchor one tier; Canadian cooperative specialists and regional millers hold differentiated positions in specialty and organic segments. Market structure tilts toward consolidation at the origination and milling stages, with elevator networks and large-scale millers commanding procurement leverage. Three archetypes dominate: integrated grain-trading conglomerates with origination infrastructure, specialty millers targeting clean-label bakery portfolios, and cooperative networks securing premium varietal supply through direct farmer relationships. Competitive moves center on backward integration into elevator assets and portfolio diversification into organic and identity-preserved varieties.
Within the integrated grain-trading tier, Cargill and Archer Daniels Midland Company exemplify scale-driven origination and milling operations. Cargill leverages elevator network density across the Northern Plains to secure premium Hard Red Spring supply, while Archer Daniels Midland Company sustains large-scale milling infrastructure optimized for high-volume bakery and brewing contracts. Ardent Mills occupies the specialty-miller archetype, differentiating through clean-label and organic flour portfolios targeting artisan bakery consolidation.
| Leading Market Players |
|---|
| Ardent Mills |
| Archer Daniels Midland Company |
| Cargill |
| CHS |
| Grain Craft |
| Miller Milling |
| General Mills |
| The Andersons |
| Bunge North America |
| Others |
Value Network & Pricing Analysis
Backward integration into elevator networks and origination infrastructure anchors supply position and pricing power for integrated grain traders across the North American wheat value chain. Cargill's dense Northern Plains elevator footprint enables premium Hard Red Spring capture, while direct cooperative relationships allow specialty millers to bypass commodity pooling and command protein-based premiums.
Pricing Analysis
Volume-margins split sharply across commodity and specialty tiers. Hard Red Winter flows through grade-pooled wholesale channels at spot-indexed rates, while Hard Red Spring and organic durum command contract-based long-term offtake with 40% premiums to conventional grades. Price differentiation centers on protein certification and organic status validated by USDA-accredited bodies. Pricing pressure intensifies in feed-grade segments where corn substitution erodes wheat's competitive position in livestock rations. Commercial bakeries exhibit highest price sensitivity due to thin margins on standard flour, whereas artisan chains absorb premiums for traceable single-origin supply.
Supply Chain Analysis
Domestic-content mandates under USDA crop insurance frameworks and Canadian Grain Commission standards reshape sourcing by requiring certified origin documentation for premium milling eligibility. Supply concentrates in the United States Northern Plains, Canada Prairie provinces, and Kansas-Oklahoma Hard Red Winter belts. The chain draws from ammonium nitrate fertilizer inputs, certified seed genetics, and diesel-dependent logistics networks. Tariff exposure at cross-border protein measurement points creates documentation friction delaying elevator receipts. Distribution runs through cooperative elevator networks, regional millers, and direct bakery contracts with blockchain traceability pilots emerging for clean-label verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where USDA's revised revenue protection formulas and Canadian Grain Commission grading standards erect barrier-to-entry moats favoring players with certified infrastructure and documented traceability systems.
For Market Incumbents: To counter artisan bakery disintermediation and direct cooperative sourcing, anchor position through backward integration into identity-preserved elevator assets in North Dakota and Minnesota, while accelerating organic certification capacity to capture transition premiums from Saskatchewan and Manitoba growers. For New Entrants and Emerging Players: Launch via direct sales partnerships with Denver and Minneapolis artisan chains seeking specified falling numbers and harvest-date documentation, targeting the underdeveloped e-commerce channel for identity-preserved varieties with varietal provenance transparency. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty miller acquisitions by integrated grain traders seeking clean-label portfolio diversification. Long-term viability favors players with captive organic supply and blockchain-enabled traceability infrastructure. Watch Canadian Grain Commission grading harmonization talks as inflection signal for cross-border premium capture expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elevator Networks | Cargill's Northern Plains density secures premium Hard Red Spring origination before competitors. |
| Organic Certification Capacity Expansion | Ardent Mills' clean-label portfolios capture USDA-subsidized transition premiums from Kansas growers. |
| Blockchain Traceability Pilot Programs | North Dakota cooperatives satisfy Minneapolis artisan chains demanding immutable varietal provenance. |
| Direct Bakery Contract Structuring | Bypassing regional millers enables falling-number specifications and harvest-date premiums. |
| Cross-Border Protein Harmonization Investment | Resolving Canadian Grain Commission measurement friction unlocks Saskatchewan durum export eligibility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with grain elevator operators, specialty miller procurement directors, certified crop advisors, and artisan bakery supply chain managers. USDA Risk Management Agency crop insurance databases, Canadian Grain Commission grading statistics, and North American export customs documentation provided volume and flow validation. Bottom-up acreage and yield estimates triangulated against top-down milling capacity and end-use consumption surveys.
Data-stream reconciliation across farmer planting intention surveys, elevator receipt records, and bakery procurement contracts shaped the analytical framework. Segmentation dimensions modeled include varietal type, protein grade tier, end-use application, distribution channel structure, and regional production cluster. CAGRs derived from trend extrapolation of planted acreage, yield improvement trajectories, and protein premium capture rates across the projection horizon. Forecast inputs incorporated precision agriculture adoption curves and organic transition incentive structures.
Drought frequency intensification, fertilizer input cost volatility, and regulatory grading standard revisions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding farmer response to insurance incentive structures and bakery procurement pattern continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Rolled Oats Market
Grains
Grain Dryers Market
Grains
Grain-Based Flours Market
Grains
Millets Market
Grains
Barley Grass Market
Grains
Italy Rice Market
Grains
Organic Rice Market
Grains
South Africa Maize Market
Grains
United States Rice Market
Grains
South America Wheat Market
Grains
Dried Spent Grain Market
Grains
Argentina Maize Market
Grains
Oatmeal Market
Grains
Soybean Market
Grains
Green Banana Flour Market
Grains
Millet Flour Market