
 Flax Seed Market | 2026-2036
Flax Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Flax Seed Market Analysis
The split between cold-pressed flax oil for nutraceuticals and solvent-extracted meal for animal feed is realigning procurement priorities across the value chain. Archer-Daniels-Midland Company leverages its North American crush capacity to anchor supply for industrial oil buyers. Cargill Incorporated sustains origination dominance across the Canadian prairies through direct farmer contracts. Bunge Limited competes on global export logistics, positioning its port assets to control trans-Pacific shipment flows.
Flax seed denotes the dried, mature seed of Linum usitatissimum L., typically containing 35-45% oil by weight and 20-25% protein, with alpha-linolenic acid comprising 50-60% of the fatty acid profile. Cold-pressing preserves heat-sensitive lignans and omega-3 content for human consumption, while expeller and solvent extraction serve feed and industrial applications. Ground seeds lead the product type category due to direct incorporation into bakery and functional food formulations. Flax oil generates premium margins in nutraceutical channels where ALA content drives label claims. The food industry end user remains mature in Western markets but extends into Asian bakery applications.
Health Canada and the FDA both maintain standards for omega-3 content claims and GRAS status that determine which flax derivatives enter human food channels. The EU's EFSA evaluates novel food applications and health claims, creating compliance barriers for non-European suppliers. REACH and EU pesticide residue limits further filter import eligibility. Stakeholders must monitor evolving novel food rulings in Asia-Pacific jurisdictions where regulatory convergence with Western standards remains incomplete.
Market Dynamics
Cold-press extraction technology is bifurcating the value chain into premium nutraceutical channels and commodity feed applications, forcing processors to choose certification tiers early in capital planning.
Growth Catalysts
- Omega-3 enrichment mandates:Health Canada and FDA labeling standards for ALA content claims are pulling flax oil into functional food formulations across North American retail channels.
- Novel Food Regulation alignment:EFSA's evolving novel food rulings are creating compliance pathways for Canadian and Australian suppliers seeking EU human-grade certification.
- Prairie origination contracts:Direct farmer contracting across Saskatchewan and Manitoba is securing traceable supply for cold-press processors serving premium nutraceutical buyers.
Market Restraints
- Input cost volatility:Flax seed prices swing with prairie weather patterns and competing canola acreage decisions, compressing crush margins for solvent-extracted meal producers.
- Supply concentration risk:Over 70% of exportable volume originates from three Canadian provinces, exposing buyers to single-origin disruption from drought or trade friction.
- Regulatory friction:REACH registration requirements and EU pesticide residue limits filter out smaller processors lacking dedicated compliance infrastructure.
Strategic Opportunities
- Asian bakery penetration:Japanese and South Korean food manufacturers are reformulating wheat products with ground flax for fiber claims, opening import demand beyond traditional Western markets.
- Regulatory tailwind:India's FSSAI is evaluating omega-3 health claim frameworks that would mirror Western standards, pre-positioning suppliers for market entry.
- Technology convergence:Near-infrared spectroscopy combined with blockchain traceability is enabling real-time oil quality verification across containerized shipments.
Industry Challenges
- Certification timeline compression:EFSA novel food approvals and organic equivalency agreements require 18-36 month documentation cycles that outpace product development schedules.
- Capex intensity for cold-press scale-up:Human-grade extraction equipment demands stainless steel infrastructure and HACCP-certified facilities that triple per-tonne investment versus solvent systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flax Seed Market |
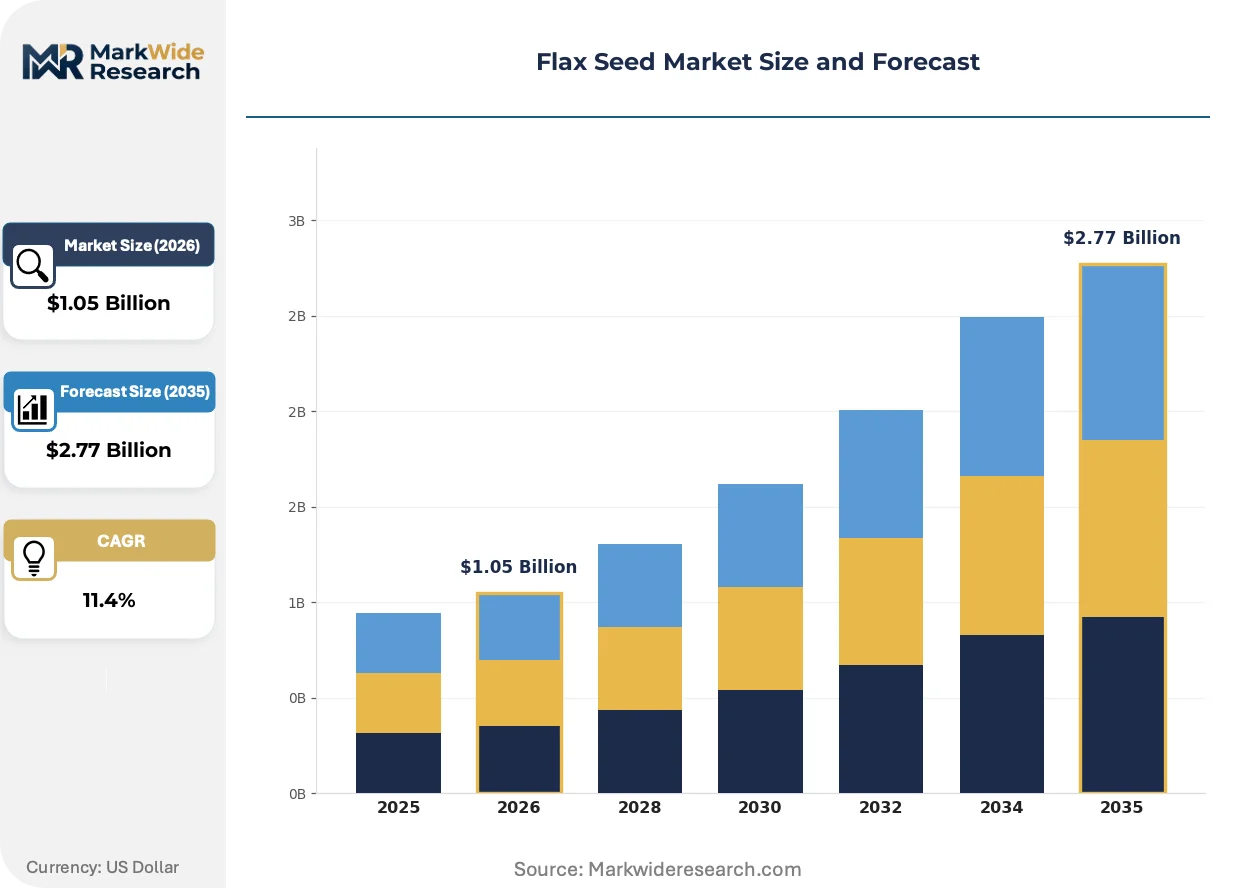
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Seeds, Ground Seeds, Flax Oil, Flax Meal End User: Food Industry, Nutraceuticals, Animal Feed, Personal Care Distribution Channel: Online Retail, Hypermarkets, Specialty Stores, Direct Sales Packaging Type: Bags, Bottles, Bulk Packaging, Sachets |
| Companies Covered | Louis Dreyfus Company B.V., SunOpta Inc., Archer-Daniels-Midland Company, Nature's Crops International Ltd., The Scoular Company, Cargill Incorporated, CHS Inc., Barentz International B.V., Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flax Seed Market Emerging Trajectories
Extraction technology and regulatory science are converging to create tiered supply chains where certification grade, not just oil yield, determines market access and margin capture.
Supercritical CO2 extraction is modularizing the mid-scale processing segment. Regional cooperatives in Saskatchewan and North Dakota are deploying containerized units that bypass centralized crush facilities. This distributed architecture is compressing logistics costs for organic-certified batches while preserving heat-sensitive lignan profiles that solvent methods degrade.
EFSA's 2023 updated guidance on novel food safety assessments is tightening toxicological data requirements for flax-derived ingredients. European importers now demand full supply chain documentation from seed lot to finished oil. Canadian exporters are responding by integrating third-party audit protocols into prairie contracting structures.
Direct-to-manufacturer sourcing is displacing commodity broker channels for premium cold-press oil. Nutraceutical formulators in Germany and the Netherlands are establishing multi-year offtake agreements with named prairie crushing facilities. This relationship-based procurement is most visible in omega-3 supplement supply chains where ALA potency consistency drives batch qualification protocols.
Flax Seed Market Segmentation
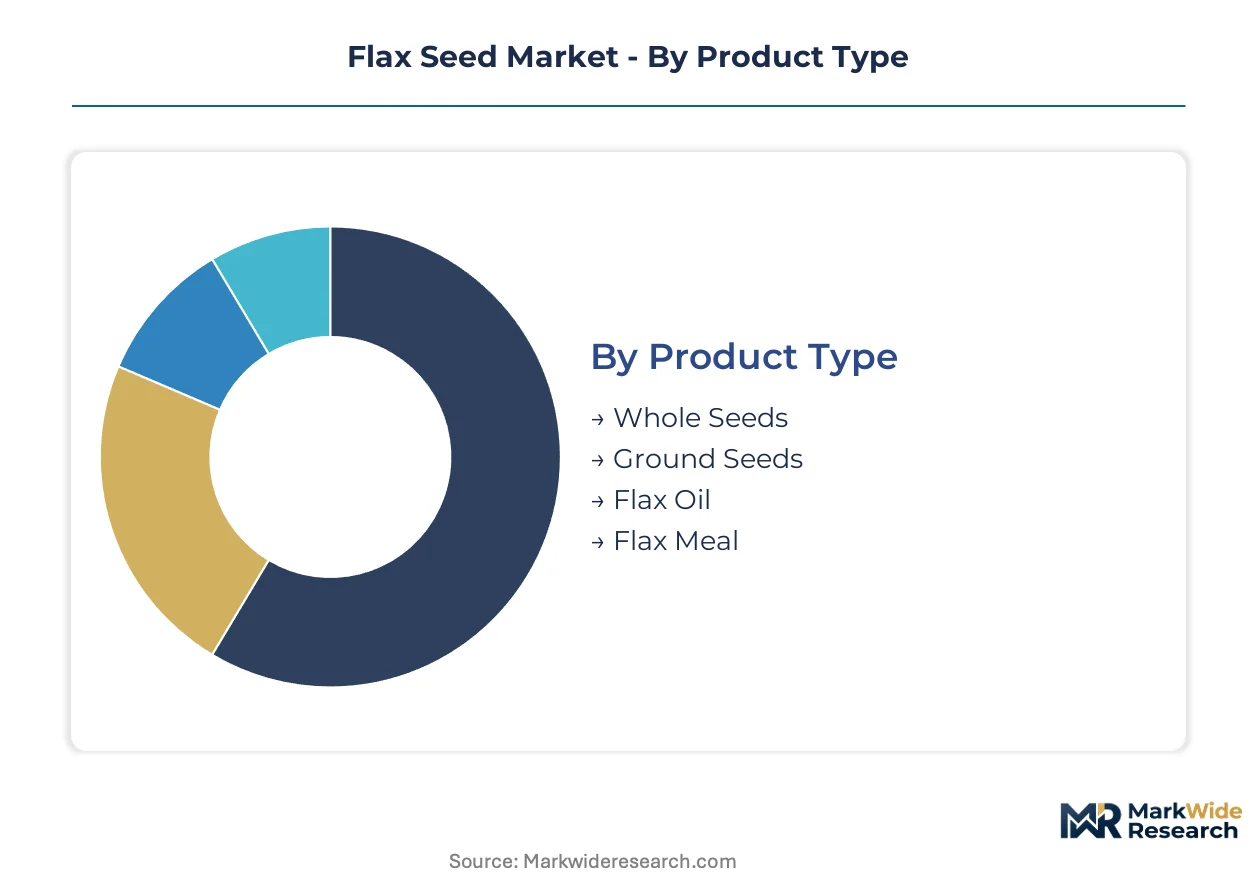
Segmentation in the flax seed market reflects divergent processing investments and certification tiers. Cold-press extraction capacity concentrates in ground seeds and flax oil, while solvent-extracted meal serves commodity feed channels with minimal overlap in procurement infrastructure.
Product Type:
Integration depth separates segments requiring standalone processing infrastructure from those embedded within multi-oilseed crush facilities.
- Ground Seeds:Mechanical milling preserves lignan and fiber integrity for direct incorporation into bakery formulations. North American nutraceutical buyers prioritize organic-certified ground product for omega-3 supplement blending, though supply contracts remain concentrated in Saskatchewan prairie origination.
- Flax Oil:Cold-pressed grades command human-grade certification premiums through Health Canada and FDA GRAS pathways; solvent-extracted variants feed industrial applications. German and Dutch supplement formulators now specify ALA potency minimums in multi-year offtake agreements with named crushing facilities.
- Whole Seeds:Minimal processing preserves germination viability for replanting and specialty food applications.
- Flax Meal:Solvent-extracted protein concentrate serves ruminant feed rations with omega-3 enrichment claims for dairy operations.
Ground seeds lead volumes today; flax oil is gaining share fastest.
End User:
Cost tier stratification separates premium nutraceutical channels from commodity feed economics.
- Nutraceuticals:Omega-3 supplement and functional food manufacturers demand cold-pressed oil with documented ALA profiles exceeding 50% fatty acid content. EFSA novel food rulings and Health Canada label standards create compliance moats that filter smaller suppliers from human-grade channels.
- Food Industry:Bakery and cereal manufacturers incorporate ground seeds for fiber positioning in reformulated wheat products. Japanese and South Korean millers are expanding import quotas for organic-certified ground flax as fiber claims penetrate Asian retail shelves.
- Animal Feed:Dairy and poultry operations use solvent-extracted meal for omega-3 enriched egg and milk production.
- Personal Care:Cosmetic formulators utilize refined flax oil for emollient properties in skin and hair applications.
Nutraceuticals capture premium pricing; food industry applications are expanding most quickly.
Distribution Channel:
Volume concentration favors bulk procurement while specialty channels serve fragmented premium demand.
- Direct Sales:Multi-year supply agreements between prairie crushing facilities and European nutraceutical formulators bypass commodity brokers entirely. These relationship-based contracts specify ALA consistency protocols and third-party audit requirements that containerized shipments with blockchain traceability now support.
- Specialty Stores:Organic and natural product retailers stock cold-pressed oil and ground seeds with full supply chain documentation. Canadian exporters are integrating EFSA-aligned audit protocols into prairie contracting structures to satisfy European importer demands.
- Hypermarkets:Mass retail channels move packaged ground seeds and whole seeds for home baking applications.
- Online Retail:E-commerce platforms serve direct-to-consumer supplement sales with subscription-based replenishment models.
Direct sales anchor premium volume; specialty stores are climbing the fastest.
Packaging Type:
Supply concentration in prairie origination dictates bulk logistics dominance while finished goods require protective formats.
- Bulk Packaging:Intermodal containers and rail tankers move solvent-extracted meal and crude oil from Saskatchewan crush facilities to export terminals. Bunge Limited and similar operators leverage port assets to control trans-Pacific shipment flows.
- Bottles:Amber glass and opaque PET formats protect cold-pressed oil from oxidation during retail shelf life. Nutraceutical channel requirements for nitrogen flushing and oxygen barrier properties drive packaging specification divergence from commodity formats.
- Bags:Multi-wall paper and woven polypropylene contain ground seeds and whole seeds for food manufacturing.
- Sachets:Single-serve portions serve hospitality and airline catering channels with portion-controlled convenience.
Bulk packaging leads volumes today; bottles are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian agronomists and prairie farm managers anchor the industry's talent base, with crushing facility engineers and cold-press technicians concentrated in Saskatchewan and Manitoba processing corridors.
Canada
Direct farmer contracting across Saskatchewan and Manitoba secures traceable supply for cold-press processors serving German and Dutch nutraceutical formulators. Health Canada maintains ALA content claim standards that determine which flax derivatives enter human food channels. Winnipeg and Regina host the densest clusters of HACCP-certified crushing facilities.
United States
North Dakota cooperatives deploy containerized supercritical CO2 extraction units that bypass centralized crush facilities for organic-certified batches. The FDA's GRAS pathway for flax oil determines entry into functional food formulations across retail channels. Fargo-Moorhead corridor facilities specialize in nitrogen-flushed oil packaging for nutraceutical shelf stability.
Germany
Supplement formulators in Hamburg and Frankfurt specify ALA potency minimums in multi-year offtake agreements with named prairie crushing facilities. EFSA's novel food safety assessments tighten toxicological data requirements for flax-derived ingredients. The Port of Hamburg controls trans-Atlantic import flows for containerized organic shipments.
Netherlands
Rotterdam-based traders demand full supply chain documentation from seed lot to finished oil under EFSA-aligned audit protocols. REACH registration requirements filter out smaller processors lacking dedicated compliance infrastructure. The Europoort terminal complex handles bulk solvent-extracted meal transshipment to Asian feed compounders.
India
Gujarat and Rajasthan millers reformulate wheat products with imported ground flax for fiber claims in urban retail channels. FSSAI is evaluating omega-3 health claim frameworks that would mirror Western standards. Anand and Rajkot processing hubs specialize in bakery ingredient blending for domestic FMCG distribution.
Flax Seed Market Vendor Landscape
Top-tier vendors anchor North American origination and export logistics, while mid-scale cooperatives and regional traders occupy specialized certification tiers. The structure consolidates around crush capacity ownership and port asset control. Three archetypes dominate: integrated agribusiness conglomerates with multi-oilseed platforms, prairie-focused origination specialists with direct farmer networks, and European trading houses with regulatory compliance infrastructure. Competitive moves concentrate on backward integration into prairie contracting and technology licensing for cold-press scale-up.
Among North American agribusiness conglomerates, Archer-Daniels-Midland Company exemplifies integrated crush capacity deployment, while Cargill Incorporated occupies a position in prairie origination dominance through direct farmer contracts. Bunge Limited represents the export logistics archetype, anchoring trans-Pacific shipment flow control through port assets.
| Leading Market Players |
|---|
| Louis Dreyfus Company B.V. |
| SunOpta Inc. |
| Archer-Daniels-Midland Company |
| Nature's Crops International Ltd. |
| The Scoular Company |
| Cargill Incorporated |
| CHS Inc. |
| Barentz International B.V. |
| Bunge Limited |
| Others |
Supply Flow & Price Mechanics
EFSA's Novel Food Regulation gates qualified supply for European nutraceutical buyers while simultaneously anchoring premium-tier pricing access for certified Canadian processors. Prairie origination contracts now bundle traceability documentation with cold-press extraction capacity, compressing margins for uncertified competitors.
Pricing Analysis
Unbundled commodity spot trading for solvent-extracted meal competes against bundled long-term offtake agreements that wrap cold-pressed oil with blockchain traceability and third-party audit documentation. Price differentiation rests on certification grade and ALA potency consistency, with German and Dutch formulators paying premiums for named-facility supply. Cost compression in the solvent-extracted tier is intensifying as canola acreage competition squeezes prairie seed availability. Animal feed compounders show highest price sensitivity; nutraceutical formulators accept premium positioning for documented supply chain integrity.
Supply Chain Analysis
Dual-sourcing requirements from European importers now mandate multi-supplier qualification across Saskatchewan, Manitoba, and North Dakota crushing facilities. Geographic supply concentrates in Canada, with secondary origination from the United States and limited Australian organic volumes. Raw material dependencies center on prairie flax seed availability, nitrogen fertilizer inputs, and stainless steel processing infrastructure. Single-origin vulnerability from prairie drought patterns represents the dominant structural risk. Distribution runs through Winnipeg and Regina rail terminals to Vancouver and Montreal port assets for trans-Atlantic and trans-Pacific shipment flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market stems from cold-press technology adoption that shifts volume toward premium nutraceutical tiers while solvent-extracted feed economics face input cost compression.
For Market Incumbents: Anchor prairie origination dominance through multi-year farmer contracting that locks traceable supply ahead of EFSA novel food approval timelines. Expand HACCP-certified cold-press capacity in Saskatchewan processing corridors to capture German and Dutch formulator demand. Defend against containerized supercritical CO2 cooperative units in North Dakota by integrating blockchain traceability into existing audit protocols. For New Entrants and Emerging Players: Supercritical CO2 extraction technology offers a technology-first wedge into organic-certified batches bypassing centralized crush infrastructure. Target Japanese and South Korean bakery reformulation demand for fiber-claim ground flax where import quotas are expanding fastest. Pursue direct-to-manufacturer sourcing relationships with Asian millers seeking documented supply chain integrity outside commodity broker channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale prairie cooperatives lacking dedicated EFSA compliance infrastructure but possessing organic-certified origination networks. Long-term viability centers on regulatory alignment with Western novel food standards across the Asia-Pacific adoption curve. Watch India's FSSAI omega-3 health claim framework evaluation as the inflection signal for market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prairie Origination | Direct farmer contracting secures traceable supply for EFSA novel food qualification pathways. |
| Cold-Press Capacity Scale-Up | Stainless steel HACCP infrastructure captures premium nutraceutical margins from German formulators. |
| Blockchain Traceability Integration | Real-time oil quality verification satisfies Rotterdam-based importer documentation demands. |
| Asian Bakery Channel Expansion | Japanese and South Korean fiber-claim reformulations open import demand beyond Western markets. |
| Regulatory Compliance Infrastructure | REACH registration and EFSA-aligned audit protocols filter competition from smaller processors. |
Methodological Framework
Coverage spans Canada, the United States, Germany, the Netherlands, and India, with primary inputs from each region's stakeholder base. The research combines interviews with prairie farm managers, crushing facility engineers, nutraceutical procurement leads, and EFSA regulatory consultants with secondary validation from Health Canada standards documentation, FDA GRAS filings, EU pesticide residue databases, and customs trade records. Bottom-up volume modeling triangulates against top-down value estimates from export terminal throughput data.
Rate-of-change decomposition separates volume drivers from price realization factors across the projection horizon. Segmentation dimensions include product type, end user category, distribution channel, and regional regulatory cluster. CAGRs derive from historical prairie acreage trends, crush capacity utilization patterns, and nutraceutical formulation adoption curves. Industry-specific forecast inputs incorporate EFSA novel food approval timelines and FSSAI regulatory evaluation progress.
The model holds under stable prairie weather patterns and continued EFSA-Health Canada regulatory convergence; deviation in drought severity or trade friction would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
India Forage Seed Market
Seeds
Asia-Pacific Seed Market
Seeds
Rapeseed Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
United States Garden Seeds Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Sri Lanka Seed Market
Seeds
Organic Seed Market
Seeds
Fruit Tomatoes Seed Market
Seeds
South America Vegetable Seed Market
Seeds
Hemp Seeds Market
Seeds
Psyllium Market
Seeds
Nepal Seeds Market
Seeds
Sweet Corn Seeds Market
Seeds
Garden Seeds Market
Seeds
China Forage Seed Market