
 South America Seed Market | 2026-2036
South America Seed Market Size, Share, and Industry Trends Forecast 2026-2036
South America Seed Market Analytics
Trait licensing and subscription-based germplasm access is consolidating how seed companies monetize genetic improvement in South America. Bayer AG leverages its digital farming platform to bundle seed traits with predictive agronomy tools across Brazilian soybean belts. Corteva Agriscience anchors its regional position through deep proprietary breeding networks in Argentina's Pampas region. Syngenta Group competes by sustaining one of the broadest vegetable seed portfolios directed at Andean horticulture zones.
Seed comprises a fertilized plant ovule containing an embryo, stored nutrients, and a protective seed coat, with commercial viability measured by germination rate, genetic purity percentage, and vigor index under controlled moisture and temperature regimes. Its primary purpose is to establish crop stands with uniform emergence, yield predictability, and resistance to biotic and abiotic stressors. Cereal seeds occupy the dominant value share given the vast soybean and maize rotations across the continent, while vegetable seeds command premium pricing due to shorter breeding cycles and specialized hybrid development. Agricultural production as an end use absorbs the majority of volume, with cooperatives and distributors forming the critical channel infrastructure for reaching remote farming operations.
Brazil's CTNBio oversees transgenic and gene-edited crop approvals, while Argentina's SENASA enforces phytosanitary certification for cross-border seed movement; both frameworks determine which trait platforms achieve commercial scale. The Mercosur technical regulation on seed quality harmonization further shapes market access by setting minimum germination and varietal purity thresholds across member states. Stakeholders must monitor how evolving gene-editing classification protocols in Brasília and Buenos Aires will redraw competitive boundaries between conventional hybrid and new breeding technology portfolios.
Market Dynamics
Gene-editing classification protocols in Brasília and Buenos Aires are redrawing competitive boundaries between conventional hybrid breeding and new breeding technology portfolios across South American seed markets.
Growth Catalysts
- CTNBio Streamlining:Brazil's national biosafety regulator has compressed approval timelines for gene-edited crops, accelerating commercialization of drought-tolerant soybean germplasm.
- Mechanized Farming Concentration:Large-scale operations in Mato Grosso and Paraná states generate procurement volumes that justify premium trait licensing investments.
- Mercosur Harmonization:The technical regulation on seed quality establishes minimum germination thresholds across Argentina, Brazil, Paraguay, and Uruguay, reducing cross-border friction.
Market Restraints
- Input Cost Volatility:Phosphorus and nitrogen fertilizer price swings compress farm operating margins, forcing seed expenditure trade-offs during planting seasons.
- Phytosanitary Certification Friction:Argentina's SENASA enforces rigorous cross-border seed movement protocols that delay delivery windows to Brazilian distributors.
- Genetic Uniformity Risk:Narrow germplasm bases in commercial soybean lines heighten vulnerability to emerging pathogen races across the Pampas and Cerrado.
Strategic Opportunities
- Andean Horticulture Expansion:Vegetable seed portfolios targeting Colombia's high-altitude production zones command premium pricing due to specialized hybrid development cycles.
- Digital Bundling Convergence:Predictive agronomy platforms integrated with germplasm access are capturing cooperative procurement decisions in Brazil's soybean belts.
- Gene-Editing Tailwinds:Regulatory clarity on edited versus transgenic classification in Buenos Aires is opening pathways for CRISPR-derived disease resistance traits.
Industry Challenges
- Trait Licensing Complexity:Stacked intellectual property arrangements across multiple germplasm providers create contractual negotiation bottlenecks for regional distributors.
- Certification Timeline Compression:Variety registration protocols in Brasília require multi-season field trials that delay market entry for novel drought-tolerance genetics.
- Specialized Breeding Talent Scarcity:Quantitative genetics expertise concentrated in Argentina's Rosario and Buenos Aires clusters limits expansion of proprietary breeding networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Seed Market |
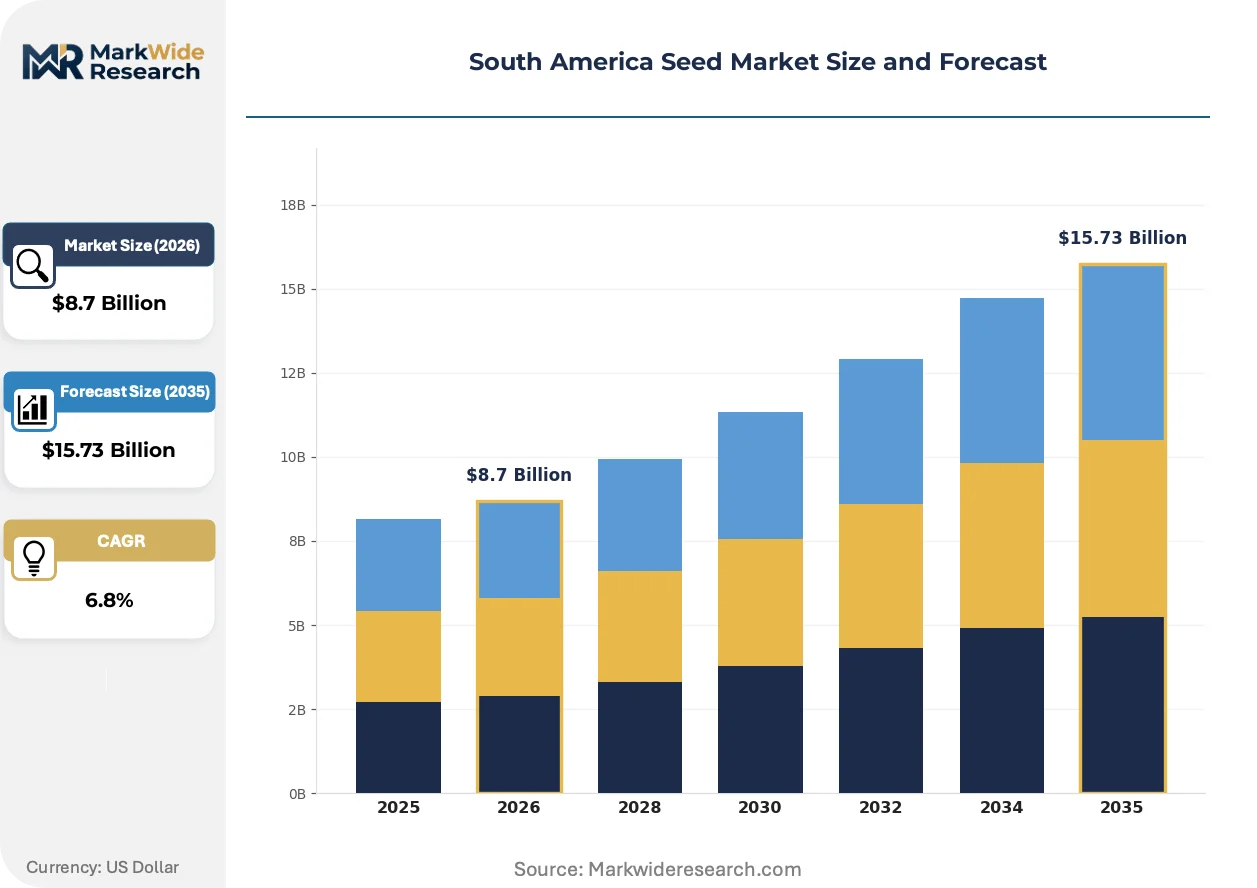
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereal Seeds, Vegetable Seeds, Flower Seeds, Legume Seeds End Use: Agricultural Production, Home Gardening, Landscape, Horticulture Packaging Type: Pouches, Bulk Bags, Paper Bags, Plastic Containers Distribution Channel: Retail Stores, Online Platforms, Agricultural Cooperatives, Distributors |
| Companies Covered | Advanta Seeds, BASF, Bayer AG, Sakata Seed Corporation, Bioceres Crop Solutions, Corteva Agriscience, Groupe Limagrain, KWS, Syngenta Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Seed Market Evolving Landscape
Biotechnology integration and regulatory recalibration are restructuring how genetic improvement reaches South American farmers, with digital platforms intermediating access to advanced germplasm.
CRISPR-based gene editing is electrifying trait development pipelines by enabling precise drought-tolerance modifications without transgenic regulatory burdens. Brazilian cooperatives in Mato Grosso are adopting edited soybean varieties at accelerating rates. This compression of breeding cycles is displacing decade-long conventional hybridization timelines for abiotic stress traits.
Argentina's SENASA is tightening phytosanitary certification requirements for cross-border seed shipments, extending inspection protocols at Paraná River ports. The industrial consequence is inventory holding cost accumulation for distributors serving Brazilian border states. Vegetable seed exporters to Andean markets are responding by establishing in-country conditioning facilities to bypass transit delays.
Cooperative procurement consolidation is reshaping distribution economics across Brazil's soybean belt. Traditional independent retailers in Paraná are losing volume to centralized buying alliances that negotiate directly with trait licensors. This channel compression is most visible in Mato Grosso, where three cooperatives now control majority germplasm procurement for mechanized operations.
South America Seed Market Segmentation
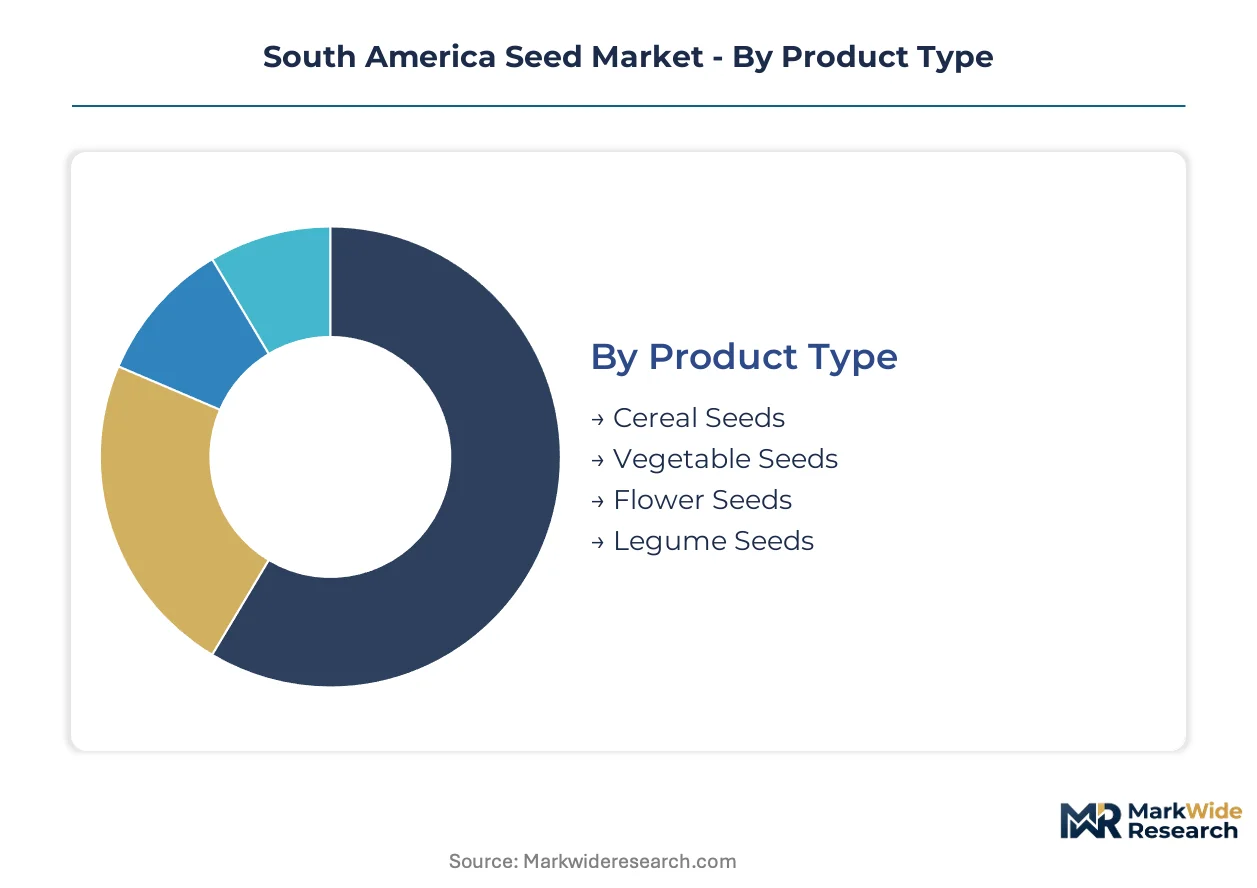
South American seed procurement patterns diverge sharply between commodity grain belts and specialized horticulture zones. Understanding these segment boundaries clarifies where trait licensing investments concentrate versus where premium pricing power materializes.
Product Type:
Supply concentration in soybean and maize germplasm development has tilted breeding investment toward specific crop categories.
- Cereal Seeds:Encompasses maize, soybean, wheat, and rice germplasm with commercial viability measured by germination rate and genetic purity percentage. Demand concentrates in Brazil's Mato Grosso and Paraná states where large-scale mechanized farming operations dominate procurement volumes for commodity grain rotations.
- Vegetable Seeds:Comprises hybrid tomato, pepper, onion, and brassica varieties requiring specialized breeding cycles for disease resistance and shelf-life extension. Colombia's high-altitude Andean production zones command premium pricing due to shorter breeding cycles and climate-specific hybrid development requirements.
- Flower Seeds:Ornamental varieties for commercial landscaping and cut flower production with varietal purity thresholds enforced under Mercosur technical regulations.
- Legume Seeds:Common bean, chickpea, and lentil germplasm serving protein crop rotations in Argentina's Pampas region.
Cereal seeds absorb the bulk of installed capacity; vegetable seeds are expanding most quickly.
End Use:
Cost tier differentiation separates volume-driven commodity applications from value-added specialized cultivation.
- Agricultural Production:Commercial farming operations establishing crop stands with uniform emergence and yield predictability across Brazil's Cerrado and Argentina's Pampas.
- Home Gardening:Small-scale residential cultivation with procurement through retail channels and online platforms in urban centers.
- Landscape:Municipal and commercial turf establishment requiring certified germplasm with documented vigor index performance under controlled moisture regimes.
- Horticulture:Intensive greenhouse and open-field vegetable production in Colombia's Bogotá savanna and Ecuador's highland valleys.
Agricultural production commands dominant volume share; horticulture delivers the steepest margin expansion.
Packaging Type:
Customer type and operational scale dictate packaging format selection across the distribution network.
- Pouches:Small-unit retail packaging for vegetable and flower seeds targeting home gardening segments with moisture-barrier specifications.
- Bulk Bags:Large-volume flexible containers for cereal seed shipments to mechanized farming cooperatives in Mato Grosso.
- Paper Bags:Traditional breathable packaging for conventional hybrid varieties with printed germination rate certifications.
- Plastic Containers:Rigid packaging for pelleted and primed vegetable seeds requiring protection from mechanical damage during transit.
Bulk bags handle the majority of tonnage movement; plastic containers are gaining share fastest in vegetable seed logistics.
Distribution Channel:
Geographic reach and technical service requirements shape channel configuration across remote farming territories.
- Retail Stores:Independent agricultural supply outlets in Paraná losing volume to consolidated cooperative procurement alliances.
- Online Platforms:Digital marketplaces integrating predictive agronomy tools with germplasm access across Brazilian soybean belts.
- Agricultural Cooperatives:Centralized buying alliances in Mato Grosso now controlling majority germplasm procurement for mechanized operations through direct trait licensor negotiations.
- Distributors:Regional wholesalers navigating Argentina's SENASA phytosanitary certification delays at Paraná River ports.
Agricultural cooperatives capture the largest procurement volumes; online platforms are climbing the fastest as digital bundling converges with germplasm sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil dominates continental production while Argentina anchors germplasm innovation. Consumption concentrates in mechanized farming belts where trait licensing economics justify premium seed expenditure. Cross-border seed flows face persistent regulatory friction at Mercosur boundaries.
Brazil
Mato Grosso and Paraná states generate the majority of continental procurement volume for soybean and maize germplasm. CTNBio has compressed approval timelines for gene-edited crops, accelerating commercialization of drought-tolerant varieties. São Paulo-based cooperatives now negotiate directly with trait licensors, bypassing traditional independent retailers.
Argentina
The Pampas region sustains deep proprietary breeding networks for wheat and soybean germplasm development. SENASA enforces rigorous phytosanitary certification protocols that delay seed shipments across Paraná River ports. Rosario and Buenos Aires clusters concentrate quantitative genetics expertise that limits expansion of regional breeding capacity.
Colombia
High-altitude Andean production zones command premium pricing for specialized vegetable hybrid development. The country's national agricultural regulator oversees variety registration protocols that require multi-season field trials. Bogotá savanna greenhouse operations drive demand for disease-resistant tomato and pepper germplasm with extended shelf-life traits.
Chile
Central Valley fruit and vegetable seed multiplication facilities serve as a counter-seasonal supply hub for Northern Hemisphere markets. The country's phytosanitary authority enforces strict varietal purity thresholds for export certification. Metropolitan Santiago distributors coordinate logistics for Andean horticulture zones seeking bypass routes around Argentine transit delays.
Uruguay
Mercedes and Paysandú departments concentrate soybean seed conditioning infrastructure for regional export. Mercosur technical regulation harmonization reduces cross-border friction for certified germplasm movement into Brazilian border states. Montevideo-based distributors leverage streamlined customs protocols to capture spillover demand from Paraná River logistics bottlenecks.
South America Seed Market Competitive Landscape
Capital-heavy integrated breeders compete with asset-light trait licensors across South American germplasm markets. Bayer AG and Corteva Agriscience anchor the consolidated tier through captive breeding networks and digital platform bundling. Mid-scale regional specialists occupy positions between global licensors and local distributors. Competitive dynamics center on M&A consolidation of proprietary germplasm bases and strategic partnerships for gene-editing technology access.
Within the integrated breeding tier, Bayer AG represents the convergence of digital agronomy platforms with germplasm distribution across Brazilian soybean belts. Corteva Agriscience exemplifies deep proprietary breeding network deployment anchored in Argentina's Pampas region. Syngenta Group occupies a position emphasizing broad vegetable seed portfolios directed at Andean horticulture zones. These three entities illustrate how scale-driven trait licensing and specialized hybrid development create distinct competitive vectors.
| Leading Market Players |
|---|
| Advanta Seeds |
| BASF |
| Bayer AG |
| Sakata Seed Corporation |
| Bioceres Crop Solutions |
| Corteva Agriscience |
| Groupe Limagrain |
| KWS |
| Syngenta Group |
| Others |
Value Network & Pricing Analysis
Gene-edited germplasm commercialization compresses breeding cycle economics while concentrating proprietary trait development in Brazil's Mato Grosso and Paraná clusters. CTNBio's streamlined approval pathways simultaneously reduce regulatory cost burdens and accelerate premium pricing capture for drought-tolerant soybean varieties.
Pricing Analysis
Margin tightening in standard hybrid tiers reflects phosphorus and nitrogen fertilizer cost volatility compressing farm operating budgets. Three-tier pricing structure across premium gene-edited, standard certified hybrid, and economy conventional varieties stratifies by genetic purity percentage and bundled digital agronomy access. Pricing pressure intensifies in economy tiers as cooperatives consolidate procurement volumes for direct licensor negotiation. Small-scale independent retailers exhibit highest price sensitivity; large mechanized operations in Mato Grosso demonstrate lowest sensitivity due to yield predictability premiums.
Supply Chain Analysis
Elite germplasm development rests on proprietary breeding networks concentrated in Argentina's Pampas region and Brazil's Cerrado research stations. Phosphorus-based seed treatment chemistries, polyethylene packaging resins, and precision conditioning equipment feed into production economics. Single-source vulnerability concentrates in Argentina's SENASA-certified conditioning facilities facing Paraná River port delays. Distribution runs through agricultural cooperatives in Mato Grosso, independent retailers in Paraná, and cross-border distributors navigating Mercosur harmonization protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantitative genetics expertise scarcity in Rosario and Buenos Aires clusters props premium pricing for proprietary breeding capacity. Supply constraints in specialized hybrid development sustain margin structures across the analysis window.
For Market Incumbents: Hedge genetic uniformity risk by diversifying germplasm bases against emerging pathogen races in the Cerrado. Backward integration into seed conditioning infrastructure in Uruguay's Mercedes department bypasses Argentine transit bottlenecks. CTNBio regulatory recalibration on gene-editing classification demands accelerated R&D allocation to CRISPR-derived trait pipelines. For New Entrants and Emerging Players: Digital marketplace platforms integrating predictive agronomy with germplasm access represent the most penetrable channel wedge. Colombia's high-altitude Andean vegetable zones offer white-space opportunity given specialized hybrid development requirements and premium pricing tolerance. Direct cooperative procurement alliances in Paraná bypass established retail networks. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated breeding-to-distribution platforms with captive germplasm libraries. Mid-scale regional specialists with proprietary networks in Argentina's Pampas present acquisition target archetypes. The signal to watch is CTNBio approval velocity for stacked trait packages as inflection indicator for platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Gene-Editing Trait Pipeline Advancement | CTNBio streamlining accelerates drought-tolerant soybean commercialization timelines in Mato Grosso. |
| Digital Platform Integration | Predictive agronomy bundling captures cooperative procurement decisions across Brazilian soybean belts. |
| Proprietary Breeding Network Expansion | Rosario cluster quantitative genetics capacity anchors germplasm innovation in Argentina's Pampas. |
| Cross-Border Conditioning Facility Investment | Uruguay's Mercedes infrastructure bypasses SENASA phytosanitary delays at Paraná River ports. |
| Cooperative Procurement Alliance Formation | Centralized buying alliances in Paraná displace independent retailer volume through direct licensor access. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with seed company breeding directors, cooperative procurement managers, CTNBio regulatory affairs leads, and SENASA certification officers combined with CTNBio approval databases, Mercosur technical regulation harmonization protocols, and Argentine-Brazilian customs movement records. Bottom-up germplasm volume estimates and top-down market value triangulation validated segmentation outputs.
Granularity-level modeling deployed crop-specific germplasm demand curves across cereal, vegetable, flower, and legume categories. End-use segmentation captured agricultural production, home gardening, landscape, and horticulture applications. Distribution channel dynamics modeled cooperative, retail, online, and distributor pathways. CAGRs derived from trend extrapolation of mechanized farming expansion rates and gene-editing adoption curves. Forecast inputs incorporated CTNBio approval velocity assumptions and SENASA certification timeline compression scenarios.
Inputs from CTNBio and SENASA regulatory databases were available through the study window; gaps in proprietary breeding network capacity metrics introduce uncertainty bands around germplasm supply forecasts. Forecasts reflect documented assumptions on gene-editing classification stability and Mercosur harmonization enforcement consistency. Pathogen race emergence velocity and fertilizer cost volatility warrant ongoing watch as forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Guar Market
Seeds
Cucumber Seeds Market
Seeds
Russia Forage Seed Market
Seeds
Africa Seed Market
Seeds
Africa Chia Seeds Market
Seeds
South America Vegetable Seed Market
Seeds
Philippines Hybrid Rice Seed Market
Seeds
Cherry Tomato Seeds Market
Seeds
Middle East and Africa Cannabis Seeds Market
Seeds
Global Alfalfa Seed Market
Seeds
Pumpkin Seeds Market
Seeds
Rapeseed Market
Seeds
Punnet Market
Seeds
Global Packaged Chia Seeds Market
Seeds
Asia-Pacific Forage Seed Market
Seeds
Global Sunflower Market