
 North America Chia Seeds Market | 2026-2036
North America Chia Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
North America Chia Seeds Market Analytics
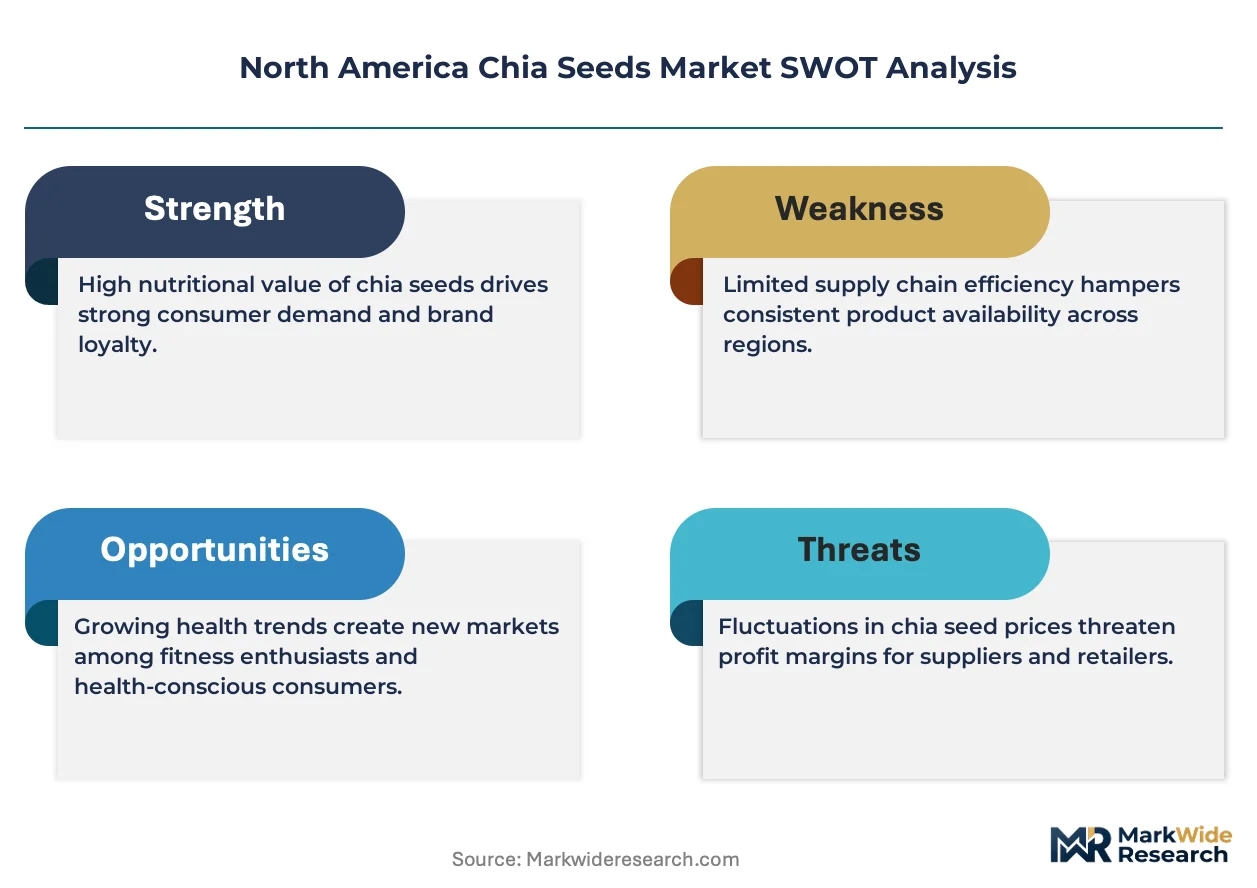
The FDA's updated Nutrition Facts label mandate is broadening the cost-of-entry calculus for chia seed suppliers seeking shelf placement in U.S. retail channels. Glanbia PLC leverages its dairy and nutrition ingredient infrastructure to anchor bulk chia supply contracts with North American nutraceutical clients. Nutiva, Inc. specializes in certified organic sourcing protocols that differentiate its portfolio within premium health store networks. Navitas Organics controls superfood category positioning through sustained investment in consumer education around plant-based omega profiles.
Chia seeds are the edible seeds of Salvia hispanica, a flowering plant in the mint family, containing approximately 34-40% oil by weight with alpha-linolenic acid comprising roughly 60% of total fatty acid content; they function primarily as a hydrophilic thickening agent, natural emulsifier, and nutrient-dense ingredient in food, supplement, and personal care formulations. The organic product type commands premium shelf positioning and tighter supply chains relative to conventional grades, while nutraceutical end users represent the fastest-expanding demand pool as brands reformulate around plant-based omega sourcing. Bulk packaging dominates ingredient-scale procurement from food service and manufacturing buyers, though sachet formats gain traction in direct-to-consumer subscription channels.
The USDA's National Organic Program and Canada's CFIA Safe Food for Canadians Regulations jointly shape cross-border trade compliance, certification costs, and label claim substantiation for chia seed distributors operating throughout North America. Health Canada maintains distinct natural health product licensing requirements that filter which omega-3 and fiber claims manufacturers may advance on Canadian retail packaging. Stakeholders must monitor evolving organic equivalency agreements and state-level hemp-cannabis labeling precedents that could reshape seed ingredient classification thresholds.
Market Dynamics
The FDA's updated Nutrition Facts label mandate is compressing formulation timelines for chia seed suppliers seeking U.S. retail placement, forcing simultaneous compliance with added sugar disclosures and fiber claim substantiation.
Growth Catalysts
- Clean-label reformulation:Nutraceutical brands across California's functional food corridor are accelerating chia incorporation into omega-3 supplements to meet FDA fiber disclosure requirements.
- Plant-based protein diversification:Food service operators in Texas and Florida are expanding chia deployment as egg replacers and hydrophilic thickeners in bakery applications.
- Organic certification premiums:USDA National Organic Program standards are creating pricing power for certified suppliers serving premium health store networks in the Pacific Northwest.
Market Restraints
- Input cost volatility:Drought conditions in Mexico's primary chia cultivation zones are creating supply uncertainty for North American importers dependent on contracted volumes.
- Regulatory friction:Health Canada's distinct natural health product licensing requirements filter which omega-3 claims Canadian manufacturers may advance, fragmenting cross-border packaging strategies.
- Substitution threat:Flaxseed and hemp seed suppliers are capturing price-sensitive buyers in conventional retail channels with comparable omega-3 profiles at lower unit costs.
Strategic Opportunities
- Direct-to-consumer subscription channels:Sachet-format chia products are gaining traction among wellness-focused households in Colorado and Oregon bypassing traditional retail markup structures.
- Personal care ingredient expansion:Cosmetic formulators in New Jersey and Illinois are piloting chia oil emulsifiers for natural skincare lines targeting clean beauty certifications.
- State-level hemp-cannabis labeling precedents:Evolving classification thresholds in California and Washington may reshape seed ingredient regulatory frameworks, creating first-mover advantages for compliant suppliers.
Industry Challenges
- Organic equivalency documentation:Cross-border trade compliance between USDA and CFIA certification systems requires specialized regulatory affairs personnel, constraining mid-scale distributor expansion.
- Legacy ERP integration:Bulk ingredient procurement platforms serving food manufacturers demand API-compatible traceability systems that smaller chia cooperatives lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Chia Seeds Market |
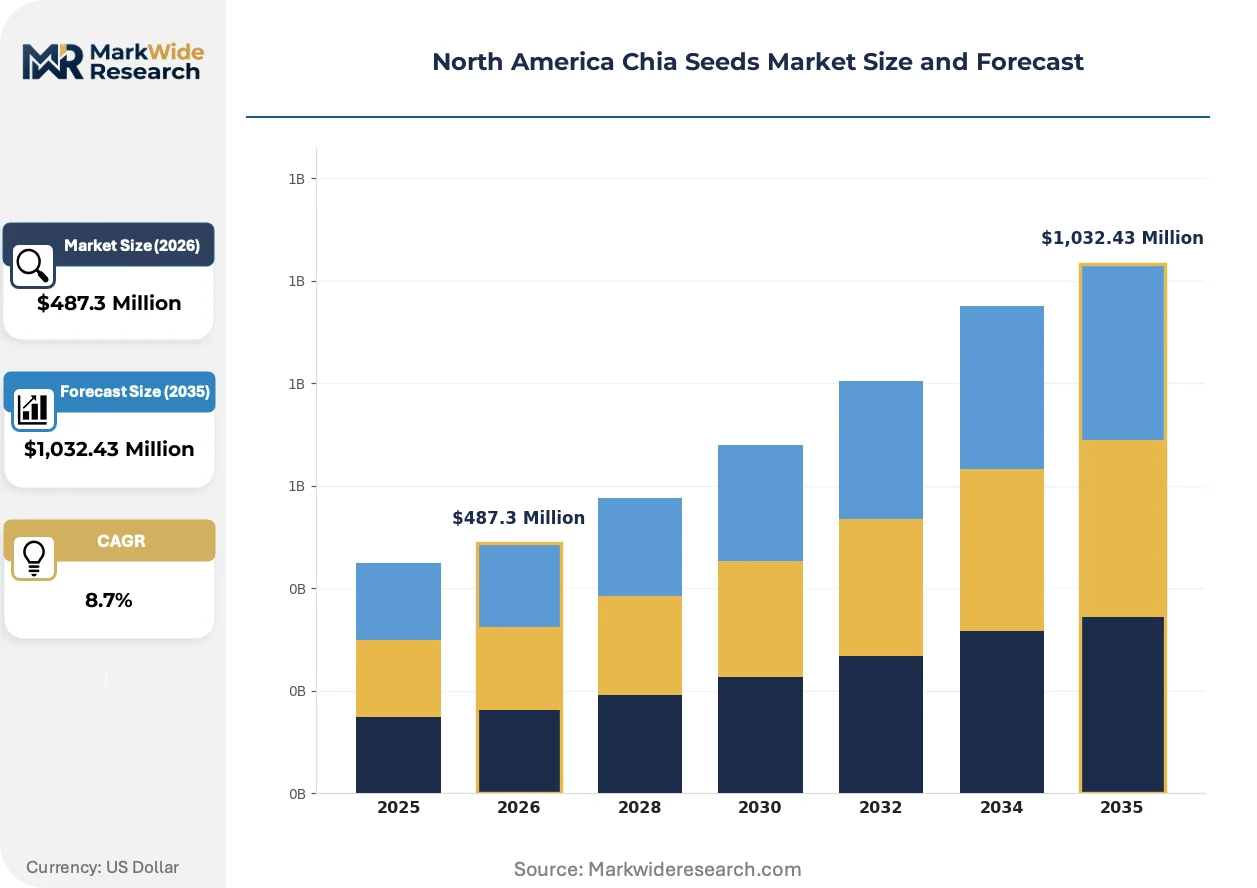
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, White, Black Packaging Type: Bags, Jars, Bulk, Sachets End User: Retail, Food Service, Nutraceuticals, Cosmetics Sales Channel: Online, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Glanbia PLC, Salba Smart Natural Products, Spectrum Organic Products LLC, BENEXIA, Mamma Chia LLC, Nutiva, Inc., Navitas Organics, NOW Foods, Inc., Garden of Life, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Chia Seeds Market Evolving Landscape
Formulation science and procurement digitization are converging to reshape how chia seeds move from cultivation through finished goods manufacturing, with particular intensity in contract manufacturing relationships.
Microencapsulation technology for chia oil is modularizing delivery formats across beverage and confectionery applications. Mid-sized functional food labs in Austin and Denver are adopting spray-dried chia powder systems at pilot scale. This modularizing capability is compressing minimum order quantities and enabling rapid prototype-to-production cycles for plant-based brands.
The FDA's 2020-2026 Nutrition Facts label implementation timeline is tightening fiber claim substantiation requirements for U.S. packaged goods. Manufacturers must now document added sugar contributions separately from naturally occurring sugars, elevating chia's appeal as a clean-label fiber source. California and New York formulation houses are responding by pre-qualifying suppliers with validated analytical certificates.
Subscription-based replenishment models are displacing conventional retail stocking for chia consumers in metropolitan markets. Direct-to-consumer brands in Seattle and Toronto are unbundling bulk purchases into personalized portion formats. This channel shift is most visible among millennial and Gen-Z households prioritizing convenience over unit cost optimization in plant-based ingredient sourcing.
North America Chia Seeds Market Segmentation
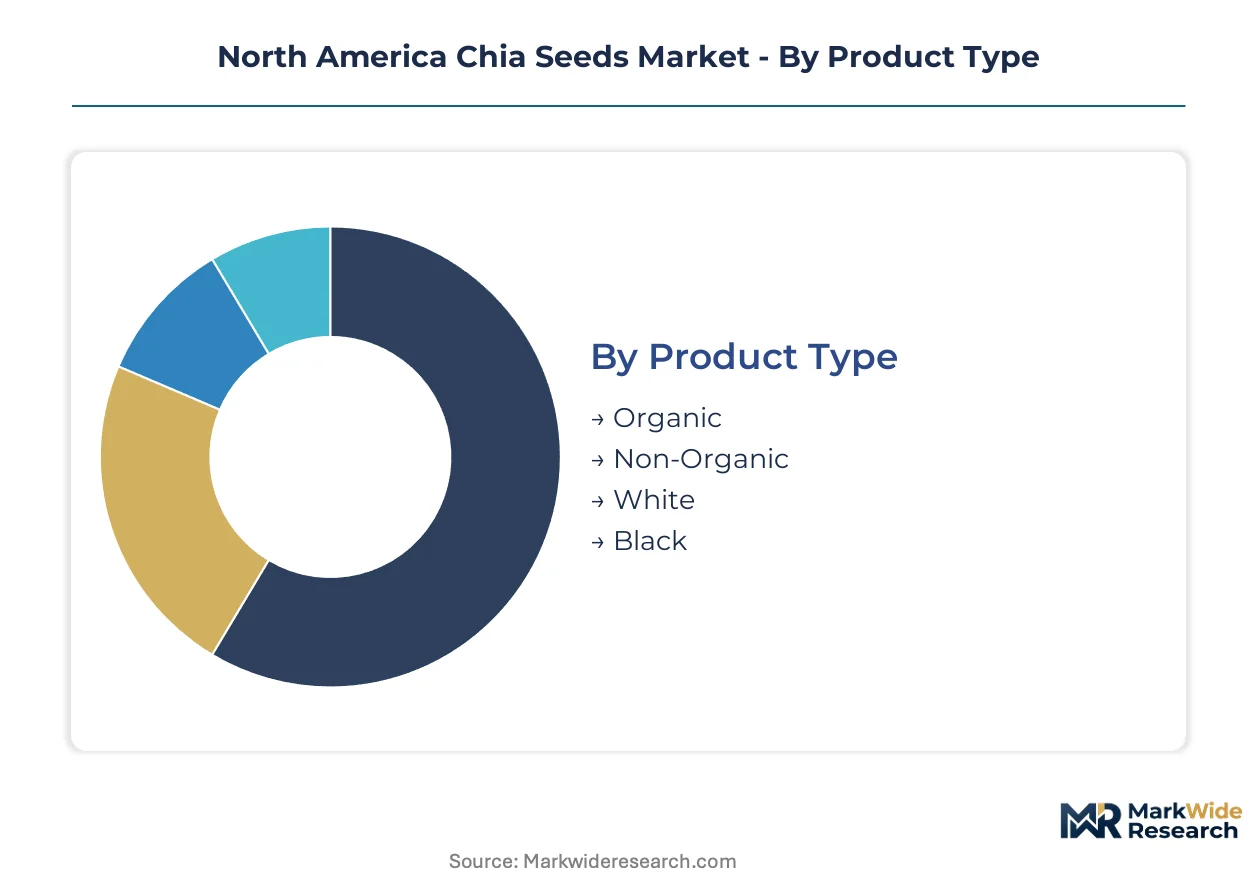
Chia seed suppliers across North America must navigate divergent technical specifications and channel requirements. Each segmentation dimension carries distinct margin profiles and regulatory burdens that reshape procurement strategies.
Product Type:
Organic and non-organic grades operate as parallel supply chains with different certification overhead, while color variants serve distinct formulation aesthetics.
- Organic:USDA National Organic Program certification mandates third-party verification of cultivation practices and prohibits synthetic inputs. Premium health store networks in California and the Pacific Northwest concentrate demand here, with FDA fiber disclosure requirements accelerating brand reformulation toward clean-label organic sourcing.
- Non-Organic:Conventional cultivation without certification overhead allows price positioning 15-25% below organic equivalents. Price-sensitive food manufacturers in Texas and Florida prioritize this grade for high-volume bakery and beverage applications where organic claims carry limited consumer value.
- White:Visually neutral seed coat enables seamless incorporation into light-colored formulations without pigment interference. Protein bar manufacturers and plant-based dairy alternatives in Colorado formulation labs specify this grade for aesthetic consistency.
- Black:Traditional varietal with higher anthocyanin content and stronger visual presence in finished goods. Smoothie bowl operators and artisanal bakeries across Los Angeles and Toronto favor this grade for Instagram-visible product differentiation.
Non-Organic leads volumes today; Organic is gaining share fastest.
Packaging Type:
Format selection tracks customer scale and channel economics, from commodity-scale bulk to precision-portioned direct-to-consumer units.
- Bags:Flexible multi-layer laminates dominate retail shelf placement with resealability and moisture barrier properties. Supermarket chains across the Midwest and Northeast standardize on 12-16 ounce standing pouches for household replenishment cycles.
- Jars:Rigid PET or glass containers command premium positioning in health store environments with superior shelf stability and reuse potential. Canadian retailers particularly favor this format for compliance with CFIA Safe Food for Canadians Regulations on tamper-evident packaging.
- Bulk:25-50 pound food-grade totes serve ingredient-scale procurement from contract manufacturers and food service distributors. Texas and Florida bakery commissaries drive demand here with just-in-time delivery requirements and minimal handling overhead.
- Sachets:Single-serve 10-15 gram packets enable subscription-based replenishment and trial sampling. Wellness-focused households in Seattle and Portland bypass traditional retail markups through direct-to-consumer channels deploying this format.
Bulk dominates manufacturing procurement; Sachets expand most quickly in subscription channels.
End User:
Application depth varies from superficial topping use to embedded functional ingredient systems with substantiated health claims.
- Retail:Packaged goods for household consumption through supermarkets, health stores, and online platforms. Private label programs at major U.S. grocery chains are expanding chia granola and chia-fortified oatmeal SKUs.
- Food Service:Ingredient-scale supply to restaurants, cafes, and institutional kitchens with menu integration as toppings or texture modifiers. California's functional food corridor clusters near Los Angeles and San Francisco drive specification intensity here.
- Nutraceuticals:Omega-3 and fiber supplements with substantiated health claims requiring analytical documentation. FDA's updated Nutrition Facts label mandate is compressing formulation timelines for suppliers seeking shelf placement in this channel.
- Cosmetics:Chia oil emulsifiers and hydrators for natural skincare formulations targeting clean beauty certifications. New Jersey and Illinois cosmetic formulators are piloting pilot-scale adoption here.
Retail anchors current revenue; Nutraceuticals show steepest expansion trajectory.
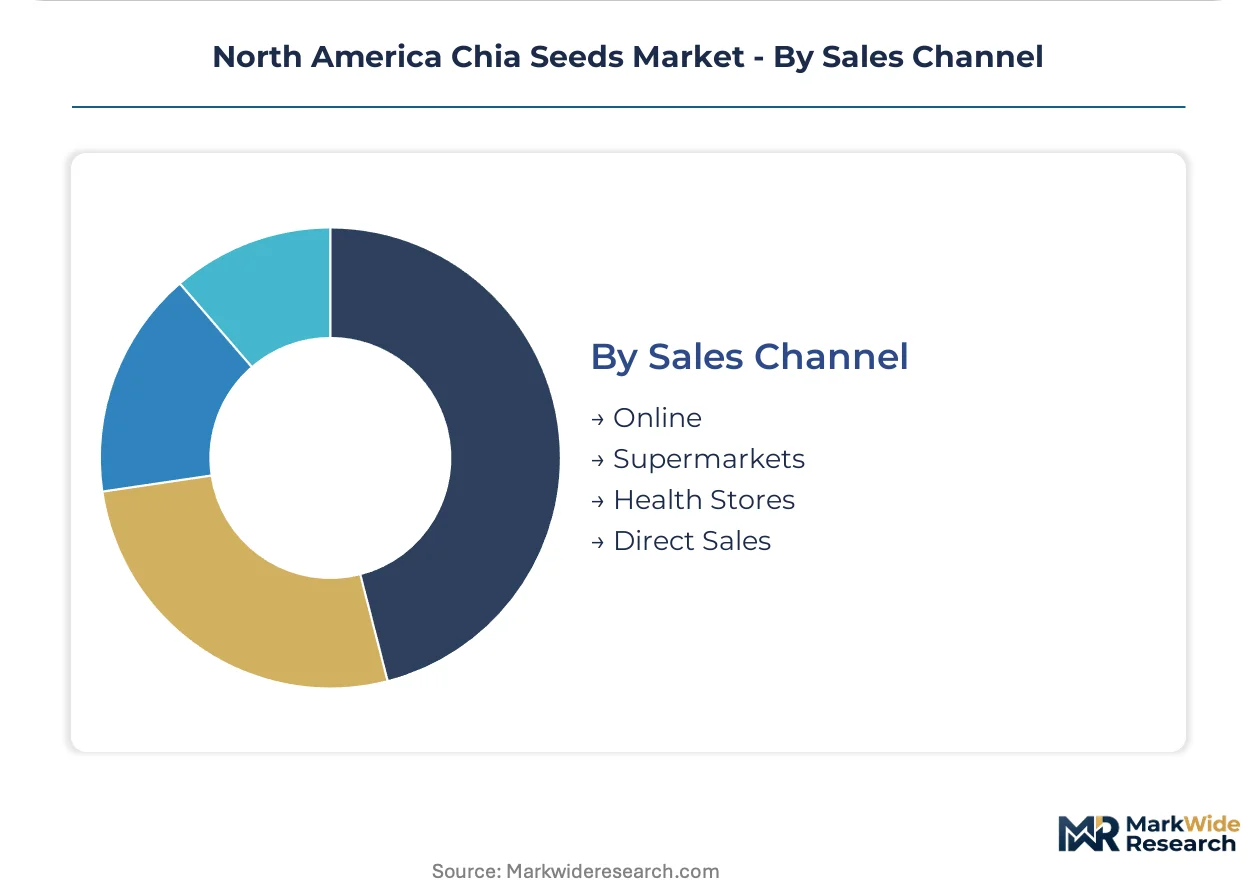
Sales Channel:
Channel selection determines margin capture and customer data access, with digital-native models displacing conventional retail in metropolitan markets.
- Online:Direct-to-consumer platforms and marketplace listings enabling subscription replenishment and personalized portion formats. Millennial and Gen-Z households in Colorado and Oregon prioritize convenience over unit cost optimization here.
- Supermarkets:Mass-market retail placement requiring slotting fees and promotional support for visibility in center-store or natural foods sections. National grocery chains dominate volume but compress supplier margins.
- Health Stores:Specialty retail with educated staff and premium positioning for certified organic and superfood-category products. Nutiva and Navitas Organics maintain strong presence here through sustained consumer education investment.
- Direct Sales:B2B ingredient supply contracts with food manufacturers, contract packers, and nutraceutical brands bypassing retail markup. Glanbia PLC leverages dairy and nutrition infrastructure to anchor bulk supply relationships here.
Supermarkets generate largest absolute volumes; Online climbs fastest among channel alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists and plant-based food scientists cluster in California's functional food corridor, anchoring North American chia seed demand concentration.
United States
California's Los Angeles and San Francisco metro areas host dense concentrations of plant-based formulation labs driving specification intensity for hydrophilic thickeners. FDA's updated Nutrition Facts label mandate compresses supplier timelines for fiber claim substantiation. Texas and Florida bakery commissaries expand chia deployment as egg replacers in high-volume applications.
Canada
Health Canada's distinct natural health product licensing requirements filter omega-3 and fiber claims on retail packaging, fragmenting cross-border strategies. CFIA Safe Food for Canadians Regulations shape tamper-evident packaging preferences favoring jar formats. Toronto and Vancouver wellness markets show strong subscription channel traction for sachet-format products.
Mexico
Drought conditions in primary chia cultivation zones create supply uncertainty for North American importers dependent on contracted volumes. SADER agricultural oversight intersects with organic export certification requirements. Northern border states concentrate processing infrastructure serving cross-border ingredient trade.
North America Chia Seeds Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supplier base organizes around three strategic archetypes: nutrition ingredient conglomerates leveraging dairy infrastructure, certified organic specialists commanding premium health store networks, and direct-to-consumer wellness brands unbundling bulk formats. Competitive moves center on backward integration into cultivation partnerships and API-compatible traceability system deployment for manufacturing procurement platforms.
Within the nutrition conglomerate tier, Glanbia PLC anchors bulk supply relationships through dairy and nutrition ingredient infrastructure. Among certified organic specialists, Nutiva, Inc. and Navitas Organics occupy positions differentiated by sourcing protocols and sustained consumer education investment. NOW Foods, Inc. represents the accessible-tier vector bridging mass-market retail placement with analytical documentation capabilities.
| Leading Market Players |
|---|
| Glanbia PLC |
| Salba Smart Natural Products |
| Spectrum Organic Products LLC |
| BENEXIA |
| Mamma Chia LLC |
| Nutiva, Inc. |
| Navitas Organics |
| NOW Foods, Inc. |
| Garden of Life, LLC |
| Others |
Value Network & Pricing Analysis
Specialized organic certification auditors and Salvia hispanica agronomists concentrate in Mexico's northern border states and California's Central Valley, creating labor-cost differentials that widen spreads between USDA-certified organic and conventional chia grades. FDA fiber disclosure mandates amplify these tier premiums as brands scramble for compliant clean-label sourcing.
Pricing Analysis
Packaged retail formats versus bulk ingredient procurement splits the market into distinct pricing architectures. Three-tier pricing structure across premium organic, standard conventional, and economy-grade conventional levels tracks certification status and analytical documentation depth. Price differentiation rests on USDA National Organic Program verification and validated omega-3 content certificates. Cost compression in economy conventional tiers intensifies as flaxseed suppliers capture price-sensitive bakery manufacturers. Food service operators in Texas and Florida exhibit highest price sensitivity; nutraceutical brands in California show lowest sensitivity due to claim-substantiation requirements.
Supply Chain Analysis
Workforce availability for organic certification compliance and chia oil extraction concentrates in Mexico, Argentina, and Paraguay as primary cultivation geographies. Raw material flows draw from Salvia hispanica seedstock, food-grade packaging laminates, and cold-press processing equipment. Single-source vulnerability runs through drought-exposed Mexican growing regions that anchor North American import volumes. Distribution runs through bulk ingredient procurement platforms serving contract manufacturers and direct-to-consumer subscription channels bypassing traditional retail markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America chia seeds market functions as a regulatory compounder where FDA Nutrition Facts label mandates continuously elevate compliant supplier valuations through fiber claim substantiation requirements.
For Market Incumbents: Anchor bulk supply relationships through backward integration into certified organic cultivation partnerships in Mexico's SADER-monitored growing regions. Deepen API-compatible traceability system deployment to defend against flaxseed substitution threats in conventional retail channels. Prioritize CFIA equivalency documentation to capture cross-border Canadian nutraceutical contracts.
For New Entrants and Emerging Players: Enter via direct-to-consumer subscription channels in Seattle and Portland where sachet-format unbundling bypasses established retail slotting fee barriers. Target personal care ingredient supply to New Jersey and Illinois cosmetic formulators piloting chia oil emulsifiers. Deploy microencapsulation technology partnerships as differentiated go-to-market positioning.
For Investors and Strategic Acquirers: Nutrition ingredient conglomerates with dairy infrastructure are the most active acquirer in this space, seeking captive omega-3 sourcing for supplement portfolios. Acquisition target archetypes include certified organic specialists with validated analytical documentation and established health store distribution. Watch organic equivalency agreement negotiations between USDA and CFIA as inflection indicator for cross-border margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captures USDA organic certification premiums and insulates against Mexican drought supply shocks. |
| Microencapsulation Technology Deployment | Enables beverage and confectionery applications for California formulation labs seeking clean-label thickeners. |
| API-Compatible Traceability Investment | Unlocks bulk procurement contracts with food manufacturers demanding ERP-integrated ingredient documentation. |
| Direct-to-Consumer Channel Launch | Bypasses supermarket slotting fees and captures millennial subscription replenishment in Colorado and Oregon. |
| Personal Care Ingredient Expansion | Accesses clean beauty certification demand from New Jersey and Illinois cosmetic formulators piloting chia oil emulsifiers. |
Research Methodology
Bottom-up nutraceutical and food service modeling reconciled against top-down cultivation and import tracking forms the analytical core of this study. Primary interviews with organic certification specialists, FDA regulatory affairs consultants, contract manufacturing procurement managers, and health store category buyers combined with secondary validation from USDA National Organic Program databases, FDA guidance documents, CFIA Safe Food for Canadians regulatory filings, and customs trade records. Triangulation between demand-side consumption patterns and supply-side production volumes ensures cross-verified market sizing.
Historical trendline analysis of organic certification growth rates, functional food ingredient adoption curves, and direct-to-consumer channel penetration established baseline trajectory assumptions. Segmentation modeling spans product type, packaging format, end-use application, and sales channel dimensions across the projection horizon. CAGRs derive from regression analysis against FDA regulatory implementation timelines and plant-based formulation lab expansion patterns in named metropolitan clusters.
Inputs from USDA and CFIA regulatory databases were available through the study window; gaps in real-time Mexican cultivation yield data introduce uncertainty bands around supply-side assumptions. Forecasts reflect documented assumptions regarding organic equivalency agreement stability and drought frequency in primary growing regions. Material deviation in FDA enforcement intensity or CFIA natural health product licensing timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
India Seed Market
Seeds
Europe Seed Market
Seeds
Cucumber Seeds Market
Seeds
Global Forage Seeds Market
Seeds
Brazil Forage Seed Market
Seeds
Africa Seed Market
Seeds
Myanmar Maize Seed Market
Seeds
Caraway Seeds Market
Seeds
Global Onion Seed Market
Seeds
South America Chia Seeds Market
Seeds
Tallow Tree Seed Market
Seeds
Global Seed Market
Seeds
Asia-Pacific Grain Seed Market
Seeds
Global Oilseed Market
Seeds
North America Maize Seed Treatment Market
Seeds
Global Vegetable Seed Market