
 Asia-Pacific Chia Seed Market | 2026-2036
Asia-Pacific Chia Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Chia Seed Market Outlook
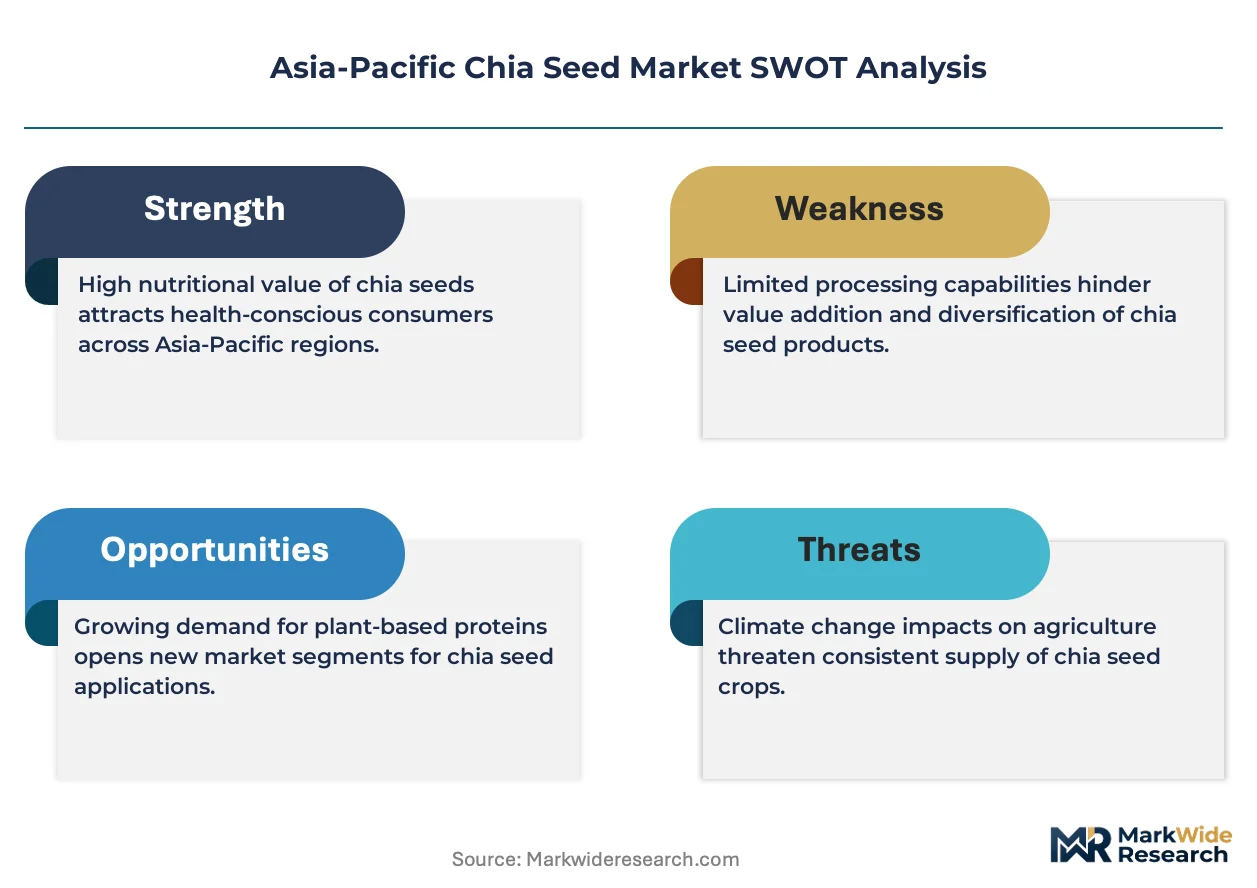
Single-serve pouch configurations is rebalancing buyer choice across health-conscious urban consumers who prioritize portion control and on-the-go consumption. The Chia Co leverages its Australian cultivation base to sustain premium positioning in domestic and export channels. Navitas Organics anchors its presence through organic certification depth across North Asian import markets. Benexia specializes in high-omega-3 oil extraction, differentiating its technical portfolio from commodity seed traders.
Chia seeds are the dried, edible fruits of Salvia hispanica, containing approximately 30-35% oil by weight with alpha-linolenic acid concentrations exceeding 60% of total fatty acids, primarily serving as a functional food ingredient for texture modification and nutritional fortification in processed consumer goods. Whole seeds dominate volume throughput due to extended shelf stability and minimal processing requirements, while chia oil commands concentrated margin pools from cosmetic and pharmaceutical offtake agreements. Ground seeds and chia flour are gaining formulation share in bakery and dairy applications where particle-size reduction improves hydration kinetics and mouthfeel integration.
FSANZ maintains stringent maximum residue limits for imported chia, while India's FSSAI enforces labeling and contaminant thresholds that shape market access protocols for foreign suppliers. China's SAMR and national food safety standards additionally govern import registration and additive restrictions for chia-containing products. Stakeholders must monitor evolving allergen classification debates and organic equivalence agreements between Australia and target export jurisdictions to preempt supply chain disruptions.
Market Dynamics
Clean-label formulation mandates under Australia's FSANZ code are compressing ingredient approval timelines and forcing functional food manufacturers to validate chia sourcing documentation earlier in product development cycles.
Growth Catalysts
- FSANZ Code Amendments:Australia's tightened maximum residue limits for imported chia are accelerating domestic cultivation investments and shortening foreign supplier onboarding windows for compliant brands.
- Functional Beverage Formulation:Southeast Asian drink manufacturers are expanding chia procurement for texture modification in ready-to-drink wellness products targeting urban convenience channels.
- India's FSSAI Threshold Harmonization:India's alignment of contaminant standards with Codex Alimentarius is reducing technical barriers for Australian and New Zealand exporters entering metropolitan supermarket networks.
Market Restraints
- Input Cost Volatility:Irrigation water pricing fluctuations in Australian growing regions are compressing farm-gate margins and destabilizing forward contract pricing for processors.
- Supply Concentration Risk:Western Australia's dominance in commercial chia cultivation creates geographic vulnerability to seasonal rainfall variability and localized pest pressure.
- Technical Limitation:Chia oil's oxidative instability above 25°C restricts ambient distribution reach and necessitates cold-chain infrastructure that many Southeast Asian distributors lack.
Strategic Opportunities
- Vietnam's Underpenetrated Retail:Modern trade expansion in Ho Chi Minh City and Hanoi creates first-mover positioning for organic chia brands before local formulation standards crystallize.
- Cosmetic Application Convergence:Chia oil's high alpha-linolenic acid content is converging with K-beauty ingredient trends in South Korean skincare manufacturing.
- China's SAMR Registration Pathway:Simplified import registration for chia-containing health foods under revised national food safety standards is opening direct-to-consumer e-commerce channels.
Industry Challenges
- Organic Equivalence Verification:Australia's bilateral organic equivalence agreements with target export jurisdictions require continuous auditor recertification that stretches compliance team bandwidth.
- Legacy System Integration:Smallholder cooperatives in Indian sourcing regions lack traceability software compatibility with multinational buyer ERP platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Chia Seed Market |
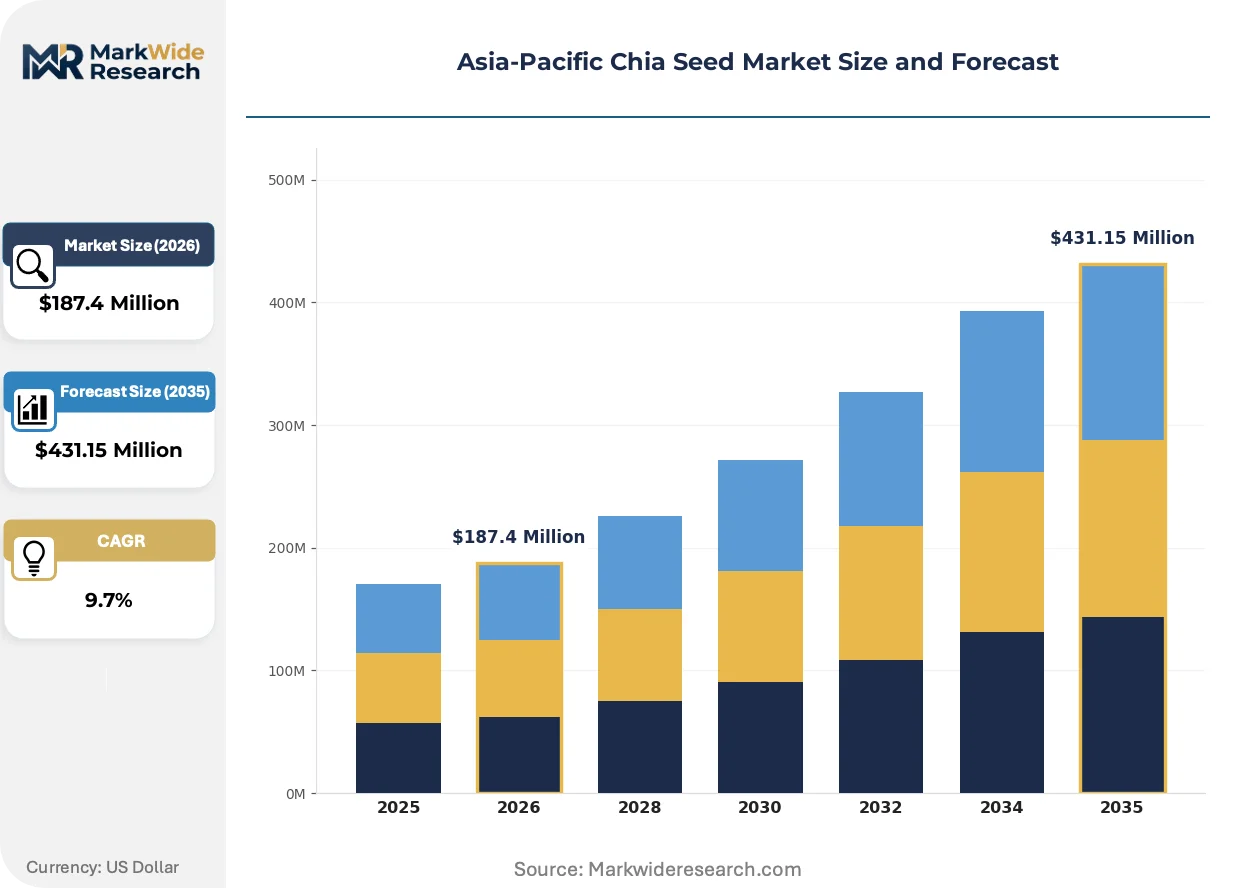
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Seeds, Ground Seeds, Chia Oil, Chia Flour Application: Beverages, Bakery, Dairy, Snacks Packaging Type: Bags, Jars, Bulk Containers, Pouches Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Health Stores |
| Companies Covered | Garden of Life, Chia Tai Seeds, The Chia Co, Bob's Red Mill, Spectrum Essentials, Navitas Organics, Benexia, Glanbia Nutritionals, Nutiva, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Chia Seed Market Strategic Shifts
Formulation science advances and regulatory transparency requirements are compressing product development cycles while fragmenting procurement authority across sustainability, compliance, and R&D functions simultaneously.
Microencapsulation of chia oil using plant-based wall materials is converging with clean-label bakery applications to extend shelf stability without synthetic antioxidants. Australian ingredient houses are piloting this technology for export to Japanese confectionery manufacturers. The structural consequence is compressing traditional chia flour's formulation share in premium baked goods.
FSANZ's 2023 allergen classification review for Salvia hispanica is forcing importers to pre-emptively label precautionary statements on chia-containing products. Australian retailers are demanding batch-level allergen testing documentation from suppliers. The infant nutrition segment is most affected, with several brands reformulating away from chia pending final determinations.
Urban Indian consumers are consolidating weekly grocery purchases through quick-commerce platforms that prioritize single-serve and portion-controlled formats. Health-food brands are reconfiguring packaging specifications for 10-minute delivery slots in Bengaluru and Mumbai. This behavioral shift is most visible in the breakfast and snacking verticals where chia pudding cups command premium placement.
Asia-Pacific Chia Seed Market Segmentation
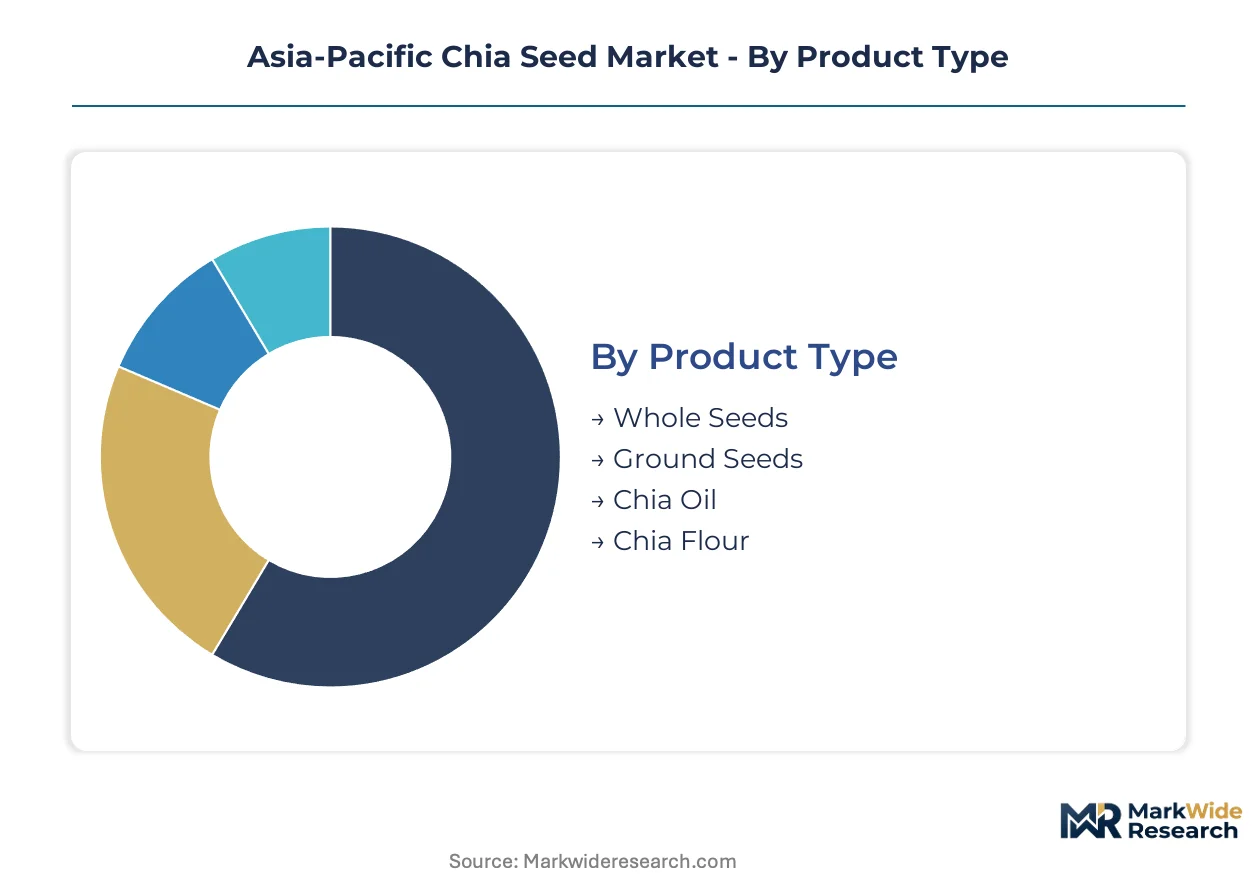
Segmentation in the Asia-Pacific chia seed market reveals how capital deployment and regulatory compliance vary sharply across product formats and channel strategies. Manufacturers must align processing investments with specific end-use specifications and distribution infrastructure requirements.
Product Type:
Capital intensity peaks with oil extraction infrastructure, while minimal processing formats require only cleaning and sorting equipment.
- Whole Seeds:Raw chia seeds retain natural mucilage coatings and require only mechanical cleaning, gravity separation, and moisture-controlled storage. Australian processors serving FSANZ-compliant brands dominate volume throughput, though India's FSSAI import thresholds are compressing foreign supplier margins. Whole seeds absorb the bulk of installed capacity; chia oil is expanding most quickly.
- Ground Seeds:Milled to 200-400 micron particle size for improved hydration kinetics in bakery and dairy matrices. Southeast Asian functional beverage manufacturers are accelerating procurement as clean-label texture modifiers replace synthetic hydrocolloids.
- Chia Oil:Cold-pressed extraction yields 25-30% oil by weight with alpha-linolenic acid exceeding 60% of fatty acid profile. Cosmetic manufacturers in South Korea and pharmaceutical offtakers in Japan command concentrated margin pools.
- Chia Flour:Defatted seed cake milled to sub-100 micron for gluten-free bakery applications. Australian ingredient houses are piloting microencapsulation to extend oxidative stability without synthetic additives.
Whole seeds dominate throughput economics; oil extraction commands premium unit economics despite cold-chain constraints.
Application:
Formulation complexity and shelf-stability requirements fragment procurement specifications across end-use verticals.
- Beverages:Ready-to-drink wellness products in Vietnam and Thailand leverage chia's gel-forming properties for texture and visual differentiation. Single-serve formats are climbing the fastest as quick-commerce platforms consolidate urban purchasing.
- Bakery:Ground seeds and chia flour integrate into gluten-free and high-fiber bread matrices. Japanese confectionery manufacturers are sourcing microencapsulated chia oil to replace synthetic antioxidants in premium positioning.
- Dairy:Yogurt and plant-based milk alternatives utilize whole seeds for visual texture and nutritional fortification. Australian health-food retail corridors concentrate demand for organic-certified inputs.
- Snacks:Energy bars and granola clusters incorporate whole or lightly crushed seeds for crunch and omega-3 claims. India's urban supermarket networks are expanding shelf space for branded chia-inclusive products.
Beverage applications are gaining share fastest; bakery maintains the deepest formulation penetration.
Packaging Type:
Packaging capital requirements scale with barrier properties and portion-control precision demanded by target channels.
- Bags:Multi-layer laminates with oxygen and moisture barriers dominate wholesale and retail bulk formats. Australian export processors favor 5-25kg configurations for B2B food manufacturing clients.
- Jars:Glass and rigid plastic containers serve premium health-store positioning and gift-oriented segments. Higher unit packaging costs compress margins at price-sensitive retail tiers.
- Bulk Containers:Food-grade totes and drums for industrial bakery and dairy manufacturing inputs. Western Australian cultivation concentration aligns with export-oriented bulk logistics infrastructure.
- Pouches:Single-serve and portion-controlled formats are expanding most quickly as Indian quick-commerce platforms and Southeast Asian convenience channels prioritize 10-minute delivery slots.
Bulk containers move the greatest tonnage; pouches are scaling fastest with channel fragmentation.
Distribution Channel:
Channel selection determines compliance documentation depth and working capital intensity for inventory positioning.
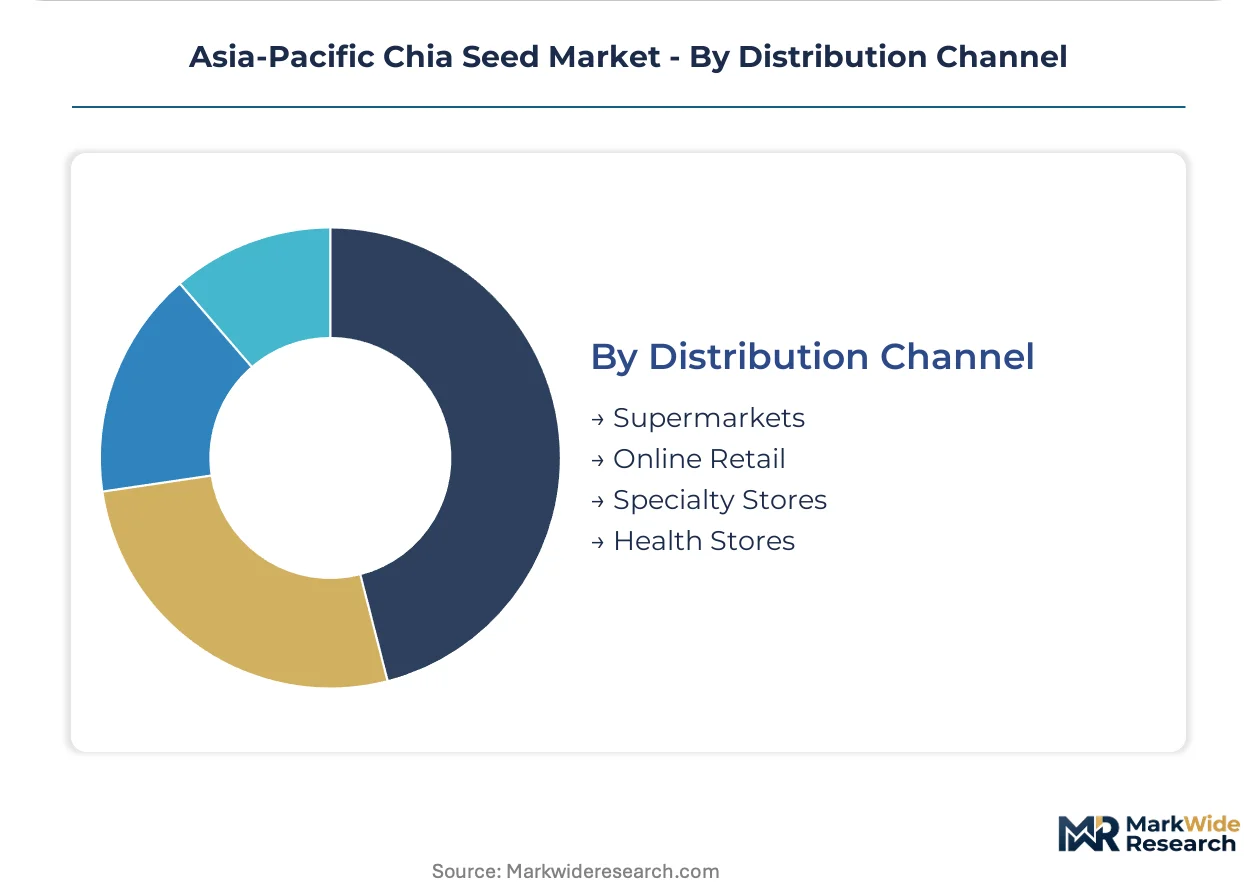
- Supermarkets:Australia's metropolitan health-food retail corridors and India's expanding urban supermarket networks concentrate branded chia procurement. FSANZ and FSSAI labeling mandates force pre-market documentation investment.
- Online Retail:China's SAMR-simplified import registration is opening direct-to-consumer e-commerce for chia-containing health foods. Cross-border logistics require batch-level traceability systems.
- Specialty Stores:Independent health-food retailers in Australia and New Zealand sustain premium positioning for organic-certified and single-origin products. Limited shelf space intensifies brand competition.
- Health Stores:Pharmacy-adjacent and wellness-focused retailers in South Korea and Japan emphasize chia oil's cosmetic and nutraceutical applications. K-beauty ingredient trends are accelerating oil format penetration.
Supermarkets anchor volume throughput; online retail is scaling fastest with regulatory streamlining.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's Wheatbelt region hosts concentrated chia cultivation infrastructure that supplies both domestic FSANZ-compliant brands and export-oriented processors serving Southeast Asian markets.
Australia
Metropolitan health-food retail corridors in Sydney and Melbourne drive premium organic chia procurement for clean-label product lines. FSANZ's tightened maximum residue limits under the 2023 code amendments are accelerating domestic cultivation investments around Esperance and Geraldton. Western Australia's grain handling infrastructure is expanding cold-storage capacity to preserve oil-grade seed quality for Japanese cosmetic offtake agreements.
China
SAMR's simplified import registration pathway for chia-containing health foods is opening direct-to-consumer e-commerce channels through cross-border logistics hubs in Hangzhou and Shenzhen. Shanghai-based ingredient distributors are consolidating procurement authority for bakery and beverage manufacturing clients across the Yangtze River Delta. The national food safety standards now permit chia in expanded food categories beyond traditional health-food classifications.
India
Urban supermarket networks in Bengaluru, Mumbai, and Delhi-NCR are expanding shelf space for branded chia-inclusive breakfast and snacking products. FSSAI's alignment of contaminant thresholds with Codex Alimentarius is reducing technical barriers for Australian and New Zealand exporters. Quick-commerce platforms are reconfiguring packaging specifications toward single-serve pouch formats for 10-minute delivery slots in metropolitan corridors.
Japan
Confectionery manufacturers in Nagoya and Osaka are sourcing microencapsulated chia oil to replace synthetic antioxidants in premium baked goods positioning. METI's functional food labeling system rewards omega-3 content claims that chia oil satisfies for cosmetic and nutraceutical applications. Kobe's port infrastructure handles bulk chia seed imports for redistribution to pharmaceutical offtakers in the Kansai industrial belt.
South Korea
K-beauty ingredient trends are accelerating chia oil penetration into skincare manufacturing clusters around Seoul and Incheon. MFDS cosmetic ingredient registration requirements favor documented alpha-linolenic acid concentrations that chia oil suppliers must verify through third-party testing. Gangnam district health stores anchor premium positioning for organic-certified chia products targeting affluent urban consumers.
Asia-Pacific Chia Seed Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific chia seed market. The vendor base clusters around three strategic tiers: multinational nutrition platforms with broad ingredient portfolios, regional cultivation-to-brand integrated operators, and specialized oil extraction technology houses. Consolidation pressure is intensifying as FSANZ compliance costs favor scaled documentation systems. Dominant competitive moves include backward integration into Australian cultivation assets and strategic partnerships with Southeast Asian beverage formulators seeking clean-label texture modifiers.
Among cultivation-integrated operators, The Chia Co and Chia Tai Seeds exemplify the regional pure-play archetype with Australian and Thai sourcing bases respectively. Navitas Organics anchors the North Asian import-focused tier through organic certification depth. Benexia occupies a specialized position in high-omega-3 oil extraction, differentiating its technical portfolio from commodity seed traders serving bulk food manufacturing clients.
| Leading Market Players |
|---|
| Garden of Life |
| Chia Tai Seeds |
| The Chia Co |
| Bob's Red Mill |
| Spectrum Essentials |
| Navitas Organics |
| Benexia |
| Glanbia Nutritionals |
| Nutiva |
| Others |
Value Chain & Pricing Dynamics
Backward integration into Western Australian cultivation assets anchors both supply security and pricing power for processors serving FSANZ-compliant brands. This upstream control over seed production compresses procurement costs for oil extraction facilities while insulating contract pricing from spot market volatility in imported chia.
Pricing Analysis
Premium pricing attaches to short lead-time deliveries for organic-certified whole seeds, while spot inventory of conventional grades trades at compressed differentials. Pricing stratifies across premium, standard, and economy tiers based on certification depth and volume scale. Cost compression in the standard tier is intensifying because irrigation water pricing fluctuations in Australian growing regions are destabilizing farm-gate margins. Smallholder cooperatives in Indian sourcing regions exhibit the highest price sensitivity, whereas Japanese cosmetic offtakers demonstrate minimal sensitivity due to formulation lock-in requirements.
Supply Chain Analysis
Regional distribution centers in Perth, Singapore, and Shanghai orchestrate hub-and-spoke patterns for chia seed redistribution across Asia-Pacific markets. Supply concentrates in Australia, Thailand, and Argentina for commercial cultivation, with India and China serving as secondary processing hubs. The chain draws from irrigation water, specialized cleaning equipment, and cold-storage infrastructure as critical inputs. Single-source vulnerability from Western Australia's dominance in commercial cultivation creates geographic exposure to seasonal rainfall variability. Distribution runs through B2B ingredient houses for food manufacturing clients and direct-to-retail channels for branded finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSANZ compliance cost escalation is forcing weaker commodity traders out of the Asia-Pacific chia seed market, creating consolidation opportunities for scaled operators with documentation systems already deployed.
For Market Incumbents: Anticipate regulatory divergence between Australian and Indian contaminant thresholds by pre-certifying dual-standard inventory pools. Prioritize captive supply of Western Australian cultivation assets to defend margin position against Argentine exporters. Invest in batch-level traceability software to preempt retailer documentation demands.
For New Entrants and Emerging Players: Begin with Vietnam's underpenetrated modern trade channels in Ho Chi Minh City and Hanoi before local formulation standards crystallize. Target single-serve pouch formats for Indian quick-commerce platforms where incumbent packaging specifications lag. Pursue white-label supply agreements with Southeast Asian functional beverage manufacturers seeking clean-label texture modifiers.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational nutrition platforms seeking Australian cultivation assets and FSANZ compliance infrastructure. Long-term viability favors operators with integrated oil extraction capabilities serving cosmetic and pharmaceutical offtake agreements. Watch for MFDS cosmetic ingredient registration acceleration in South Korea as the signal indicating chia oil demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive supply from Western Australian farms secures FSANZ-compliant seed pools for oil extraction. |
| Microencapsulation Technology Deployment | Australian ingredient houses pilot plant-based wall materials for Japanese confectionery antioxidant replacement. |
| Dual-Standard Certification Investment | Pre-certification for both FSANZ and FSSAI thresholds reduces market access friction for export processors. |
| Quick-Commerce Packaging Reconfiguration | Single-serve pouch formats align with Indian platform 10-minute delivery slots in Bengaluru and Mumbai. |
| Cosmetic Ingredient Registration | MFDS documentation for alpha-linolenic acid concentrations unlocks K-beauty manufacturing cluster access. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, supplemented by primary interviews with chia processors, FSANZ compliance officers, and health-food retail category buyers. FSANZ code amendments, FSSAI import threshold notifications, and SAMR registration pathway revisions provided regulatory boundary conditions. Bottom-up triangulation across cultivation volume estimates and top-down validation through export value reconciliation ensured cross-source consistency.
Data-stream reconciliation combined shipment manifests from Australian grain handling infrastructure with processor capacity utilization rates across the projection horizon. Segmentation dimensions modeled include product format, application vertical, packaging type, and distribution channel, with regulatory jurisdiction overlay capturing FSANZ, FSSAI, and SAMR compliance tier effects. CAGRs derived from fitted growth curves applied to base-year estimates, with input from functional beverage formulation trend analysis and cosmetic ingredient demand signals from South Korean skincare manufacturing.
Underlying measurement precision varies by segment; whole seed volume estimates carry tighter precision than chia oil cosmetic application projections due to fragmented offtake reporting. Forecasts reflect assumptions regarding regulatory stability, irrigation water pricing trajectories, and organic equivalence agreement continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
North America Seeds Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Okra Seed Market
Seeds
Africa Chia Seeds Market
Seeds
Europe Flaxseeds Market
Seeds
Europe Vegetable Seed Market
Seeds
Global Grain Seed Market
Seeds
Asia-Pacific Onion Seed Market
Seeds
China Vegetable Seed Market
Seeds
Sprouted Grains and Seeds Market
Seeds
Africa Peas Market
Seeds
Asia-Pacific Rice Seed Market
Seeds
Myanmar Maize Seed Market
Seeds
Global Sunflower Market
Seeds
Asia-Pacific Grain Seed Market
Seeds
Canary Seeds Market