
 Safflower Seeds Market | 2026-2036
Safflower Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Safflower Seeds Market Analytics
Direct procurement from farm-gate aggregators is reshaping how safflower seeds reach oil extraction facilities across North America and Asia. Archer Daniels Midland Company leverages its elevator network to secure identity-preserved safflower lots with traceable oleic acid profiles. Cargill Incorporated anchors its position through backward integration into Montana and Alberta seed production. Gansu Yasheng Industrial Group dominates the Gansu Corridor with captive breeding programs for drought-tolerant cultivars.
Safflower seeds are the dried fruits of Carthamus tinctorius, an annual thistle containing 15–45% oil by weight with linoleic or oleic acid dominance depending on cultivar, primarily crushed for culinary oil, bird feed, or industrial lubricant feedstock. Oilseeds sustain the largest value share due to expanding high-oleic demand from snack food manufacturers seeking heat-stable frying media. Organic grade competes on premium positioning in European and North American retail channels where clean-label requirements tighten. Supermarkets and wholesale channels split volume, with the former capturing branded consumer packs and the latter handling bulk ingredient flows to food processors.
USDA grading standards and FDA food safety regulations govern oilseed commerce in the United States, while India's FSSAI mandates maximum aflatoxin thresholds for edible-grade safflower. China's SAMR enforces GB/T 1537 for safflower oil purity, restricting import access for non-compliant origins. Stakeholders must monitor evolving oleic acid content specifications across major importing jurisdictions to align breeding investments with downstream contract requirements.
Market Dynamics
Contract farming networks in India's Punjab and Haryana states are compressing procurement cycles, forcing crushers to secure identity-preserved lots before harvest through advance payment structures tied to oleic acid specifications.
Growth Catalysts
- India's PLI scheme for oilseed cultivation:Production-linked incentives are expanding contract farming acreage in Rajasthan and Madhya Pradesh, linking smallholders directly to crushing facilities with guaranteed offtake.
- High-oleic snack food manufacturing:Heat-stable frying media demand from packaged food processors is pulling premium cultivar adoption across North American and Asian breeding programs.
- China's GB/T 1537 purity standards:Tightening edible oil quality mandates are filtering import origins, creating captive demand for compliant domestic Gansu Corridor production.
Market Restraints
- Water input volatility:Safflower's drought tolerance masks yield sensitivity to irrigation timing, exposing Montana and Alberta dryland operations to precipitation variance.
- Substitute oilseed competition:Sunflower and canola crushing infrastructure overlaps with safflower, allowing processors to pivot feedstock based on relative margin spreads.
- USDA grading friction:Identity-preserved lot segregation requirements add elevator handling costs that compress farm-gate prices for non-contract volumes.
Strategic Opportunities
- Organic retail channel expansion:Clean-label positioning in European supermarkets commands shelf-space premiums for certified organic safflower oil in 500ml consumer packs.
- Industrial lubricant feedstock pivot:High-linoleic cultivar streams are diverting into biodegradable hydraulic fluid formulations as petroleum-base stock substitution accelerates.
- Drought-tolerant breeding convergence:CRISPR-assisted selection is compressing cultivar development cycles for arid-zone expansion into Central Asian production zones.
Industry Challenges
- Aflatoxin certification timelines:India's FSSAI maximum threshold testing creates lot-holding delays at port terminals, squeezing working capital for export-oriented traders.
- Legacy oilseed handling infrastructure:Elevator systems designed for wheat and corn require retrofitting for safflower's lower test weight and oil staining characteristics.
- Skill gaps in oleic acid profiling:Near-infrared spectroscopy interpretation for identity-preserved lot verification remains concentrated among a limited pool of certified technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safflower Seeds Market |
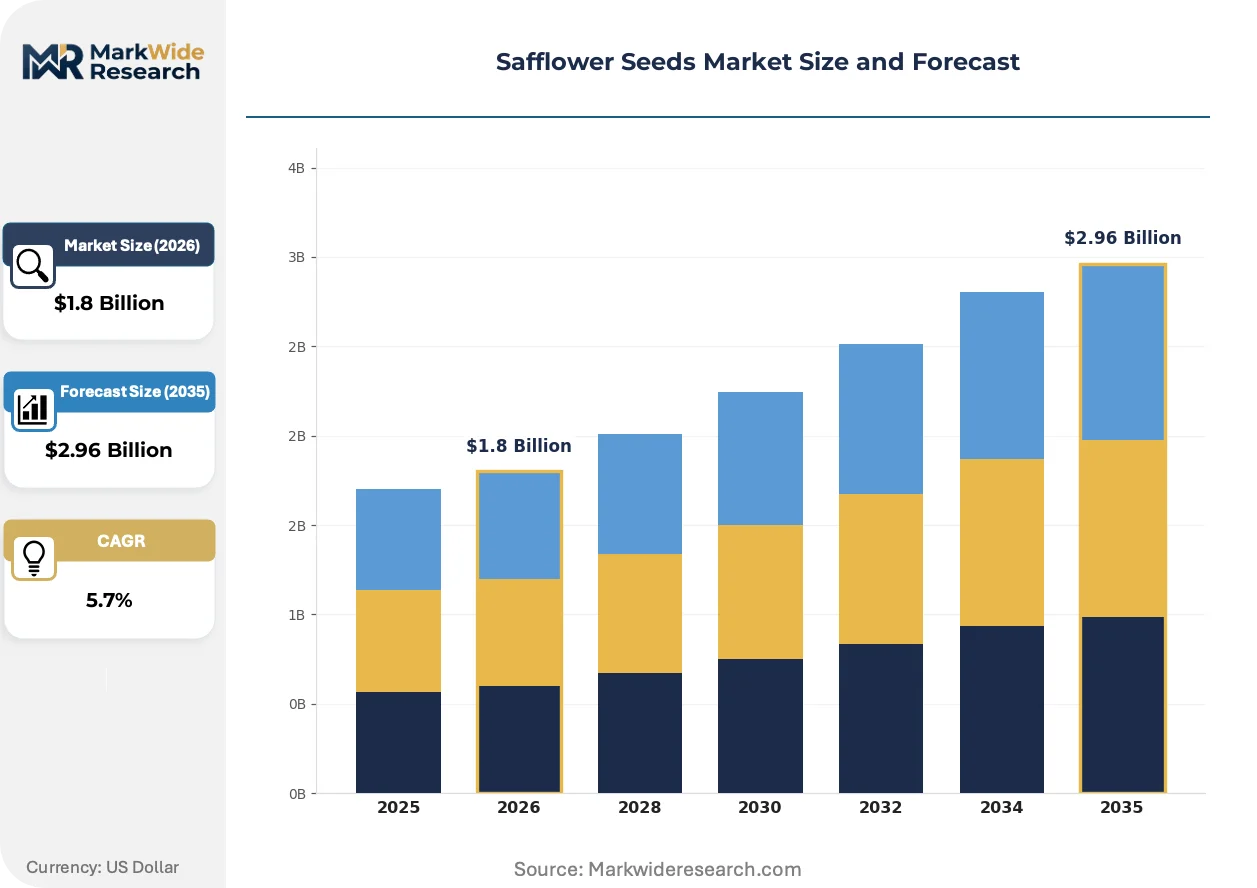
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edible Seeds, Oilseeds, Ornamental Seeds, Animal Feed Grade: Superb, Standard, Commercial, Organic Distribution Channel: Direct Sales, Online Retail, Wholesale, Supermarkets End Use Industry: Food Processing, Agriculture, Cosmetics, Pharmaceuticals |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Olam International Limited, Colorado Mills LLC, Richardson International Limited, United Oilseeds Producers Ltd., Gansu Yasheng Industrial Group Co., Ltd., Bunge Limited, Jiuquan Hongda Seed Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safflower Seeds Market Evolving Landscape
Genomic selection tools and downstream quality verification systems are compressing the breeding-to-contract cycle, while procurement digitization reshapes how crushers secure supply commitments.
CRISPR-assisted marker selection is hybridizing conventional backcrossing with rapid phenotyping protocols, enabling breeders to stack oleic acid traits with drought tolerance in half the traditional timeline. Seed companies in the US Great Plains are deploying these platforms to meet processor specifications for 75%+ oleic content. The technology is hybridizing varietal development programs, collapsing the gap between research station releases and commercial field adoption.
China's SAMR enforcement of GB/T 1537 safflower oil purity standards is tightening import documentation requirements, forcing origin exporters to deploy third-party laboratory verification at loading ports. Crushing facilities in Shandong and Hebei provinces are rejecting non-compliant lots, redirecting trade flows toward Gansu Corridor domestic supply. The regulation is compressing spot market liquidity for uncertified origins while expanding long-term contract premiums for verified supply.
Food processors are consolidating procurement through direct farm-gate aggregator relationships, bypassing traditional commodity merchant intermediaries. Snack manufacturers in India's Gujarat and Maharashtra states are signing advance purchase agreements with Punjab farming cooperatives, locking in oleic acid profiles before planting. This behavior concentrates in contract farming clusters where crushing capacity sits within 150 kilometers of production zones, eliminating elevator storage arbitrage.
Safflower Seeds Market Segmentation
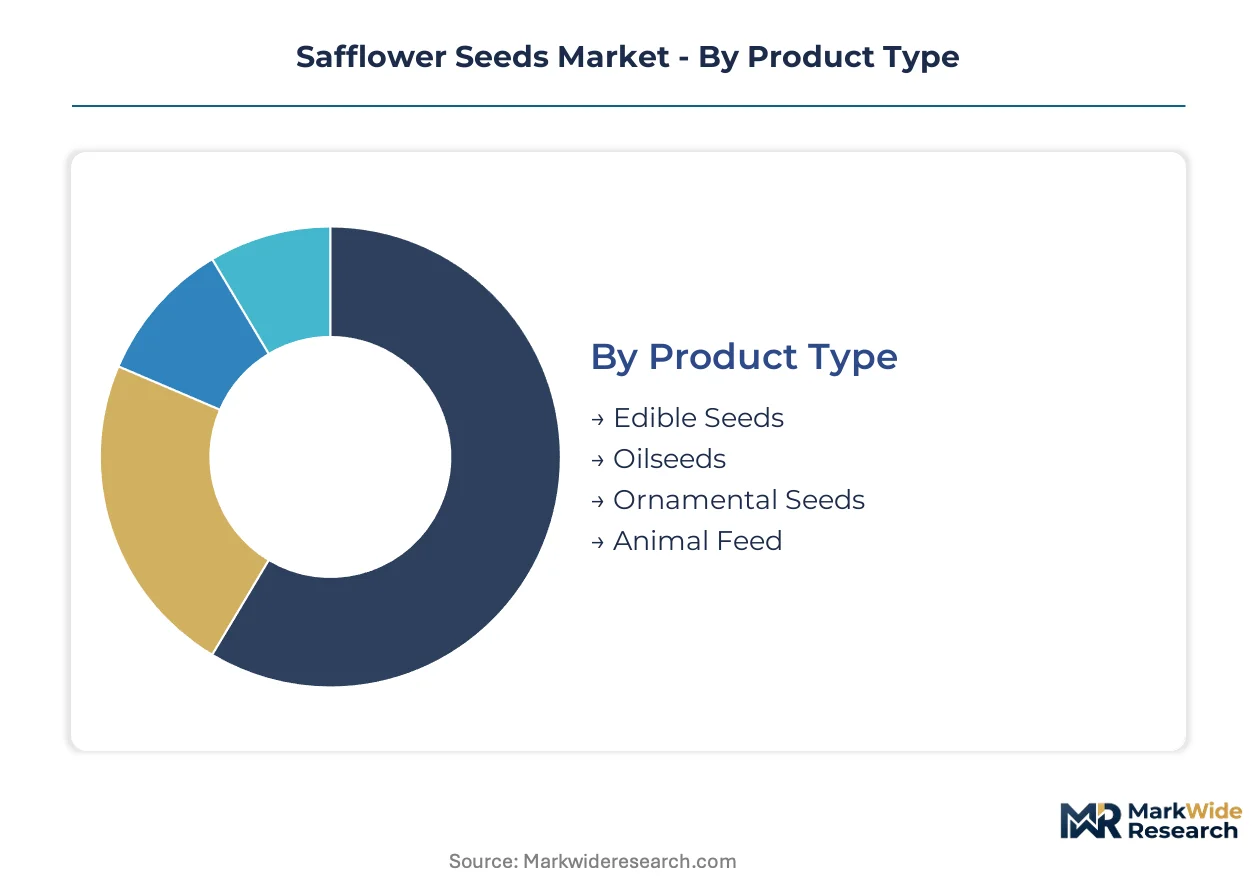
Safflower seed procurement cycles vary dramatically by segment, with oilseed crushing contracts locking in months before harvest while ornamental seed retail turns inventory weekly. Breeders and processors must align working capital and quality verification systems to these divergent velocity profiles.
Product Type:
Oilseeds rotate through procurement and crushing cycles fastest, while ornamental varieties sit longest in inventory awaiting seasonal demand spikes.
- Oilseeds:These dried fruits contain 15–45% oil by weight with linoleic or oleic acid dominance depending on cultivar selection. India's Punjab and Haryana contract farming networks concentrate demand here, with advance payment structures tied to oleic acid specifications compressing procurement timelines. Heat-stable frying media demand from snack food manufacturers pulls premium cultivar adoption across North American breeding programs.
- Edible Seeds:Whole safflower seeds processed for direct human consumption as snacks or salad toppings, typically hulled and roasted to improve palatability. China's GB/T 1537 purity standards filter import access for this grade, creating captive demand for compliant domestic Gansu Corridor production where Yasheng Industrial operates captive breeding programs.
- Ornamental Seeds:Varieties selected for flower color intensity and garden performance rather than oil content. Retail garden centers in European markets stock these for spring planting seasons.
- Animal Feed:Lower-oil cultivars and processing byproducts directed to poultry and livestock rations. Montana and Alberta dryland operations supply this segment when oilseed premiums fail to cover identity-preserved handling costs.
Oilseeds dominate installed base. Ornamental seeds are where expansion concentrates.
Grade:
Certification tiers stratify pricing power, with organic commanding shelf-space premiums while commercial grade competes on volume throughput.
- Organic:Certified production excluding synthetic pesticides and fertilizers, commanding retail premiums in European and North American supermarkets where clean-label requirements tighten. India's FSSAI maximum aflatoxin thresholds create additional certification friction for export-oriented organic traders.
- Superb:Highest oil content and purity specifications, typically exceeding 40% oil by weight with strict moisture and foreign matter limits. Contract farming networks in India's Rajasthan and Madhya Pradesh are expanding acreage under this grade through PLI scheme incentives.
- Standard:Mid-tier specification meeting general food processing requirements without identity-preserved traceability. Crushing facilities in Shandong and Hebei provinces source this grade for bulk refining operations.
- Commercial:Basic grade for industrial applications and animal feed where oil content thresholds are relaxed. Elevator handling costs compress farm-gate prices for non-contract volumes in this tier.
Standard grade dominates installed base. Organic is climbing the fastest.
Distribution Channel:
Channel selection determines margin capture, with direct sales preserving quality premiums while wholesale sacrifices markup for volume velocity.
- Direct Sales:Farm-gate procurement bypassing traditional commodity merchant intermediaries, enabled by food processor consolidation into direct aggregator relationships. Snack manufacturers in India's Gujarat and Maharashtra states sign advance purchase agreements with Punjab farming cooperatives under this model.
- Wholesale:Bulk ingredient flows to food processors through elevator networks and commodity merchants. Archer Daniels Midland leverages its elevator infrastructure to secure identity-preserved lots with traceable oleic acid profiles through this channel.
- Supermarkets:Branded consumer packs in 500ml and smaller formats, capturing clean-label premiums in European retail. Cargill anchors position here through backward integration into seed production.
- Online Retail:Direct-to-consumer ornamental seed sales and specialty organic oil shipments, growing fastest in North American garden supply and health food segments.
Wholesale dominates installed base. Direct sales are gaining share fastest.
End Use Industry:
Application maturity varies sharply, with food processing running on decade-old specifications while pharmaceutical applications demand novel extraction protocols.
- Food Processing:Culinary oil extraction for high-oleic frying media and salad oil formulations, representing the largest value share. USDA grading standards and FDA food safety regulations govern commerce in the United States for this segment.
- Agriculture:Seed multiplication programs and cover crop deployment, with drought-tolerant cultivar development accelerating through CRISPR-assisted selection for arid-zone expansion.
- Cosmetics:Linoleic acid-rich oil for skincare formulations, typically sourced from high-linoleic cultivar streams diverted from food-grade channels.
- Pharmaceuticals:Active compound extraction for therapeutic applications, requiring novel purity verification beyond standard food-grade specifications.
Food processing dominates installed base. Pharmaceuticals represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's FSSAI anchors regulatory gravity for edible-grade safflower through maximum aflatoxin thresholds that govern import access and domestic crushing operations. Procurement patterns concentrate in contract farming clusters where advance payment structures tie smallholders to oil extraction facilities.
United States
Montana and Alberta dryland operations supply high-oleic cultivars to North American snack food manufacturers seeking heat-stable frying media. USDA grading standards govern elevator handling of identity-preserved lots with traceable oleic acid profiles. Archer Daniels Midland leverages its elevator network across the Great Plains to secure premium cultivar streams before harvest.
China
SAMR enforcement of GB/T 1537 safflower oil purity standards filters import access and redirects trade flows toward Gansu Corridor domestic production. Gansu Yasheng Industrial Group dominates this corridor with captive breeding programs for drought-tolerant cultivars. Crushing facilities in Shandong and Hebei provinces reject non-compliant lots, expanding long-term contract premiums for verified supply.
India
Punjab and Haryana states concentrate demand through contract farming networks linking smallholders directly to crushing facilities with guaranteed offtake. The PLI scheme for oilseed cultivation expands acreage in Rajasthan and Madhya Pradesh with production-linked incentives. Gujarat and Maharashtra snack manufacturers sign advance purchase agreements with Punjab farming cooperatives, locking in oleic acid profiles before planting.
Canada
Alberta dryland operations supply lower-oil cultivars to animal feed channels when oilseed premiums fail to cover identity-preserved handling costs. Richardson International Limited anchors prairie procurement through backward integration into seed production. Precipitation variance exposes dryland yields to irrigation timing sensitivity, compressing farm-gate prices for non-contract volumes.
Australia
New South Wales and Victoria trial plots test drought-tolerant cultivar expansion into Central Asian production zones through CRISPR-assisted selection protocols. Organic certification tiers command retail premiums in European supermarket channels where clean-label requirements tighten. Near-infrared spectroscopy interpretation for identity-preserved lot verification remains concentrated among limited certified technician pools.
Safflower Seeds Market Competitive Landscape
Integrated agribusiness conglomerates and regional seed specialists split the market between scale-driven procurement networks and cultivar-specific breeding programs. Three archetypes dominate: multinational traders with elevator infrastructure, captive breeding operations in arid corridors, and cooperative-linked processors in contract farming clusters. Competitive moves concentrate on backward integration into seed production and advance payment structures that secure identity-preserved lots before harvest.
Within the multinational trader tier, Archer Daniels Midland Company and Cargill Incorporated exemplify elevator-network dominance, securing traceable oleic acid profiles through infrastructure control. Gansu Yasheng Industrial Group Co., Ltd. occupies a position among captive breeding specialists, anchoring drought-tolerant cultivar development in the Gansu Corridor. These three represent the structural split between North American infrastructure players and China-based breeding operations.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Olam International Limited |
| Colorado Mills LLC |
| Richardson International Limited |
| United Oilseeds Producers Ltd. |
| Gansu Yasheng Industrial Group Co., Ltd. |
| Bunge Limited |
| Jiuquan Hongda Seed Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Gansu Corridor crushing capacity dynamics compress farm-gate premiums for non-contract safflower volumes while elevating long-term offtake pricing power for verified high-oleic supply. Contract farming clusters in Punjab and Haryana states anchor procurement pricing through advance payment structures tied to oleic acid specifications, creating divergence between spot market liquidity and identity-preserved lot premiums.
Pricing Analysis
Montana-to-Alberta price spreads widen during precipitation-deficit seasons as dryland yield variance concentrates supply risk. Three-tier pricing structure across organic, identity-preserved, and commercial grades stratifies margin capture, with FSSAI aflatoxin certification tiers adding friction cost to export-oriented organic streams. Cost compression in standard-grade commercial channels intensifies because sunflower and canola crushing infrastructure allows processor feedstock pivoting based on relative margin spreads. Snack food manufacturers in Gujarat and Maharashtra demonstrate lowest price sensitivity due to heat-stable frying media specification lock-in, while animal feed compounders in Alberta exhibit highest sensitivity when oilseed premiums fail to cover identity-preserved handling thresholds.
Supply Chain Analysis
Advance payment structures and supply-chain finance facilities extend working capital cycles for Punjab smallholders while compressing crusher procurement timelines. Geographic supply concentrates in India, China, and the United States, with Gansu Corridor domestic production drawing from captive breeding programs and Montana-Alberta dryland operations feeding North American crushing infrastructure. Raw material dependencies center on drought-tolerant cultivar seed stock, irrigation water access, and near-infrared spectroscopy calibration standards for oleic acid verification. Single-source vulnerability runs through certified technician pools for identity-preserved lot authentication. Distribution runs through farm-gate aggregator relationships bypassing traditional commodity merchant intermediaries, with elevator networks handling residual non-contract volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-infrared spectroscopy interpretation capability scarcity constrains identity-preserved lot verification throughput, creating bottlenecks at crushing facilities seeking high-oleic supply commitments. Breeding program acceleration through CRISPR-assisted selection outpaces downstream quality verification infrastructure deployment.
For Market Incumbents: Pre-empt technician pool capture through certified training program sponsorship at agricultural universities in Punjab and Haryana, locking in identity-preserved verification capacity before competitor crusher expansion. Anchor backward integration into Gansu Corridor seed production to secure drought-tolerant cultivar streams ahead of SAMR enforcement tightening. Elevator network retrofitting for safflower-specific handling characteristics represents the critical capacity lever against margin compression from wheat-corn infrastructure legacy. For New Entrants and Emerging Players: Build out organic certification infrastructure in Rajasthan and Madhya Pradesh PLI scheme expansion zones, where production-linked incentives reduce acreage conversion cost barriers. Target pharmaceutical-grade linoleic acid extraction as the most penetrable end-use segment, diverting high-linoleic cultivar streams from food-grade channels where incumbent crushing capacity concentrates. Direct-to-snack-manufacturer procurement relationships bypassing wholesale elevator networks offer defensible go-to-market positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among captive breeding operations with long-term processor offtake agreements, where cultivar development cycles align with multi-year contract structures. Long-term viability across the analysis window favors integrated seed-to-oil assets with SAMR-compliant verification infrastructure. Signal to watch: FSSAI aflatoxin threshold revision timelines, which would compress working capital cycles for export-oriented traders and elevate domestic crushing facility valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Production | Cargill's Montana-Alberta acreage control secures traceable oleic acid profiles ahead of harvest. |
| Identity-Preserved Lot Verification Infrastructure | Near-infrared spectroscopy deployment at Punjab crushing facilities compresses procurement cycle timelines. |
| Organic Certification Program Expansion | European supermarket clean-label requirements command shelf-space premiums for certified 500ml consumer packs. |
| Long-term Supply Agreement Structuring | Advance purchase agreements with Gujarat snack manufacturers lock in oleic acid profiles before planting. |
| Drought-Tolerant Cultivar Development | CRISPR-assisted selection accelerates varietal release for arid-zone expansion into Central Asian production zones. |
Research Methodology
Initial hypotheses were tested against primary input from seed company breeding directors, crushing facility procurement managers, contract farming cooperative leaders, and FSSAI compliance officers, and refined through secondary validation against customs records, USDA crop production reports, SAMR GB/T standard enforcement disclosures, and SEC filings from listed agribusiness conglomerates. Bottom-up acreage and yield estimates from Punjab, Haryana, Rajasthan, and Madhya Pradesh state agricultural departments were triangulated against top-down oil extraction capacity assessments across Indian, Chinese, and North American crushing infrastructure.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type (oilseeds, edible seeds, ornamental seeds, animal feed), grade tier (organic, superb, standard, commercial), distribution channel (direct sales, wholesale, supermarkets, online retail), and end-use industry (food processing, agriculture, cosmetics, pharmaceuticals). CAGRs were derived from compounding annual volume and value trajectories. Industry-specific forecast inputs included PLI scheme acreage expansion schedules, SAMR import documentation requirement evolution, and snack food manufacturer heat-stable frying media specification adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by multinational traders would shift outcomes beyond modeled supply concentration parameters. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Brazil Forage Seed Market
Seeds
Hemp Seed Oil Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Wax Gourd Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
South Africa Seed Market
Seeds
Myanmar Maize Seed Market
Seeds
Global Grain Seed Market
Seeds
E. Angustifolium Market
Seeds
Russia Seed Market
Seeds
Agricultural Seeder Market
Seeds
Arnica Montana Market
Seeds
China Forage Seed Market
Seeds
Nepal Seeds Market
Seeds
Flower Seed Market
Seeds
Cucumber Seeds Market