
 Global Rice Seed Market | 2026-2036
Global Rice Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rice Seed Market Outlook
OECD Seed Schemes certification is unwinding competitive access for uncertified suppliers across international rice seed trade. Bayer AG leverages its integrated breeding platforms to sustain germplasm leadership in tropical indica segments. Syngenta Group anchors its position through proprietary hybrid rice technology developed for water-stressed environments. Corteva Agriscience competes via advanced marker-assisted selection pipelines that compress varietal development cycles.
Rice seed comprises the reproductive grain of Oryza sativa or Oryza glaberrima, selected and conditioned for sowing with specifications for germination rate exceeding 80%, varietal purity above 98%, and moisture content below 13% to ensure field establishment and yield consistency. Hybrid seed commands premium positioning due to yield heterosis and proprietary genetic protection, while inbred varieties occupy volume-driven markets where farmer-saved seed practices persist. Direct sales channels to agricultural cooperatives concentrate margin pools, whereas e-commerce platforms extend reach into fragmented smallholder bases across South and Southeast Asia.
India's Central Seed Committee under the Seeds Act, China's Ministry of Agriculture and Rural Affairs variety approval system, and Brazil's MAPA cultivar registration framework collectively govern market access and quality benchmarks. OECD Seed Schemes harmonization reduces technical barriers for certified seed movement between member countries, while national biosafety protocols for gene-edited varieties introduce compliance complexity. Stakeholders must monitor evolving trait approval timelines and germplasm ownership disputes as gene editing and genomic selection accelerate varietal replacement rates.
Market Dynamics
Gene-edited germplasm and accelerated variety registration timelines are compressing product lifecycles across the rice seed value chain. National biosafety frameworks and OECD Seed Schemes harmonization are simultaneously expanding certified seed trade corridors while erecting technical barriers for uncertified suppliers.
Growth Catalysts
- India's Seeds Act mandates:Central Seed Committee certification requirements are phasing out informal seed distribution channels and formalizing demand for certified hybrid varieties.
- Water-stressed germplasm innovation:Drought-tolerant indica lines developed through marker-assisted selection are penetrating rainfed lowland cultivation zones previously dependent on farmer-saved seed.
- E-commerce platform expansion:Direct-to-farmer digital channels are fragmenting traditional cooperative procurement monopolies across Bangladesh and Vietnam.
Market Restraints
- Phosphorus and nitrogen input cost volatility:Fertilizer price spikes are squeezing operating margins for seed companies dependent on demonstration plot programs.
- Parent line concentration in China:Hybrid seed production relies on cytoplasmic male sterile lines controlled by a narrow base of state-backed breeding institutes.
- Gene-edited trait approval friction:Divergent national biosafety protocols between OECD members and non-members are creating regulatory arbitrage risks.
Strategic Opportunities
- Sub-Saharan Africa variety gap:Oryza glaberrima adaptation programs targeting upland ecologies remain underpenetrated by commercial hybrid suppliers.
- Brazilian MAPA fast-track cultivar registration:Streamlined approval timelines for climate-resilient varieties are attracting germplasm licensing investments.
- Blockchain-enabled seed traceability:Distributed ledger verification of varietal purity and origin is emerging as a premium pricing mechanism in export-oriented segments.
Industry Challenges
- Quantitative genetics skill scarcity:Breeding programs face recruitment gaps for computational biologists capable of genomic selection pipeline management.
- Multi-year certification timeline compression:Accelerated variety turnover is straining national DUS testing capacity and creating registration backlogs.
- Farmer-saved seed enforcement complexity:Intellectual property protection for proprietary hybrids confronts informal seed exchange networks in smallholder-dominant regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rice Seed Market |
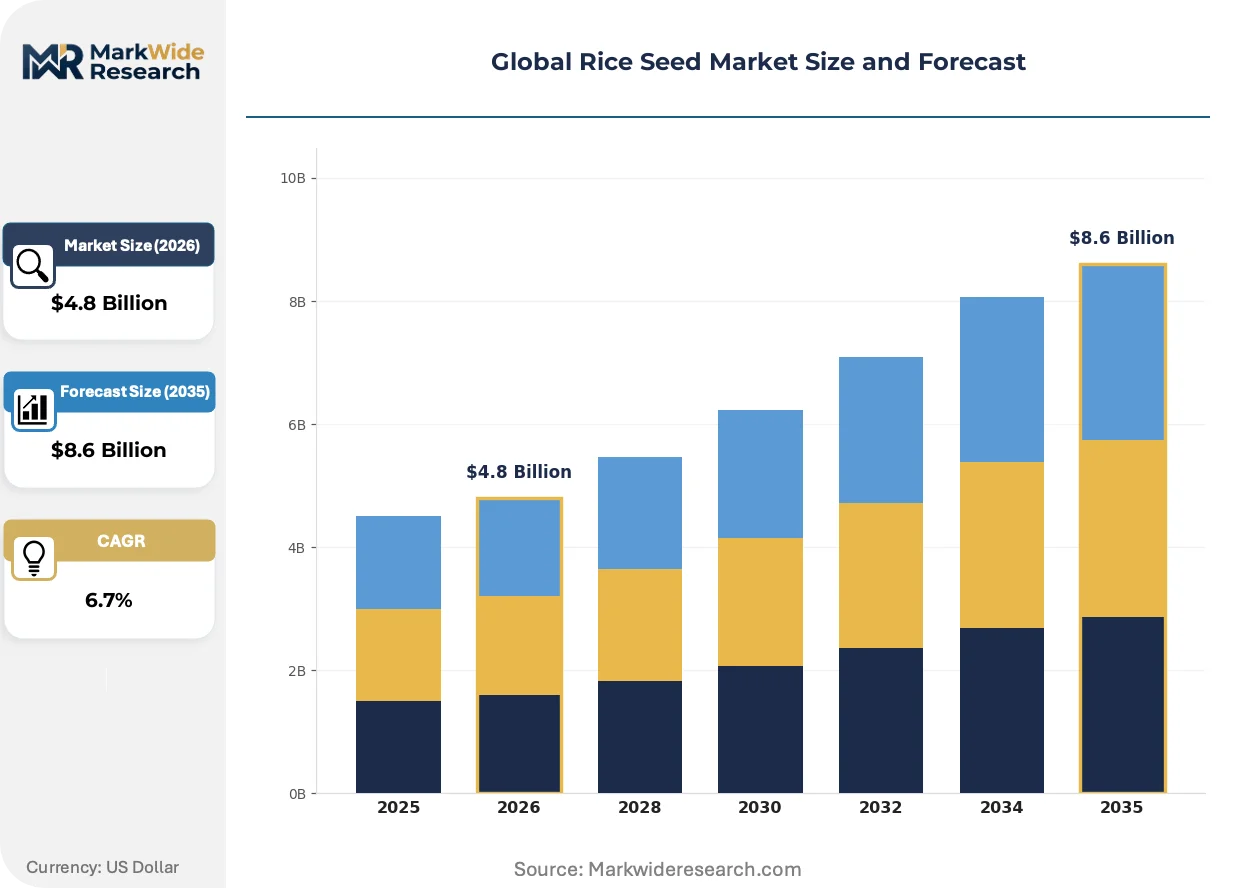
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid, Inbred, Organic, Conventional Distribution Channel: Direct Sales, Retail, E-commerce, Wholesalers End User: Farmers, Agricultural Cooperatives, Seed Companies, Research Institutions Application: Commercial Cultivation, Home Gardening, Research, Training |
| Companies Covered | Bayer AG, Syngenta Group, Corteva Agriscience, Advanta Seeds - UPL, BASF SE, RiceTec Inc., NUZIVEEDU SEEDS LTD, SL Agritech Corporation, Longping High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rice Seed Market Strategic Shifts
Genomic selection platforms and CRISPR-based trait editing are restructuring competitive advantage away from germplasm scale toward predictive breeding velocity. Regulatory divergence on gene-edited classification is simultaneously creating market access arbitrage and compliance complexity.
CRISPR-Cas9 targeted mutagenesis for blast resistance and herbicide tolerance is supplanting conventional transgenic approaches in pre-commercial pipeline development. Tropical breeding stations in the Philippines and Indonesia are adopting edited lines at accelerated evaluation cycles. This molecular precision is compressing varietal development from eight-year to four-year timelines and eroding the germplasm depth advantage of legacy market leaders.
China's Ministry of Agriculture and Rural Affairs has established separate regulatory tracks for gene-edited crops lacking foreign DNA, reducing approval timelines relative to transgenic varieties. This policy bifurcation is redirecting multinational R&D investment toward edited trait platforms. Seed companies are responding by relocating editing capability to joint ventures with Chinese state breeding institutes to secure regulatory proximity.
Cooperative procurement consolidation across Indian Punjab and Haryana is fragmenting into direct manufacturer relationships with progressive farmer associations. Input dealers are losing margin capture as seed companies deploy agronomist-led demonstration networks. This channel disintermediation is most pronounced in hybrid rice segments where yield heterosis justifies premium positioning and technical advisory bundling.
Global Rice Seed Market Segmentation
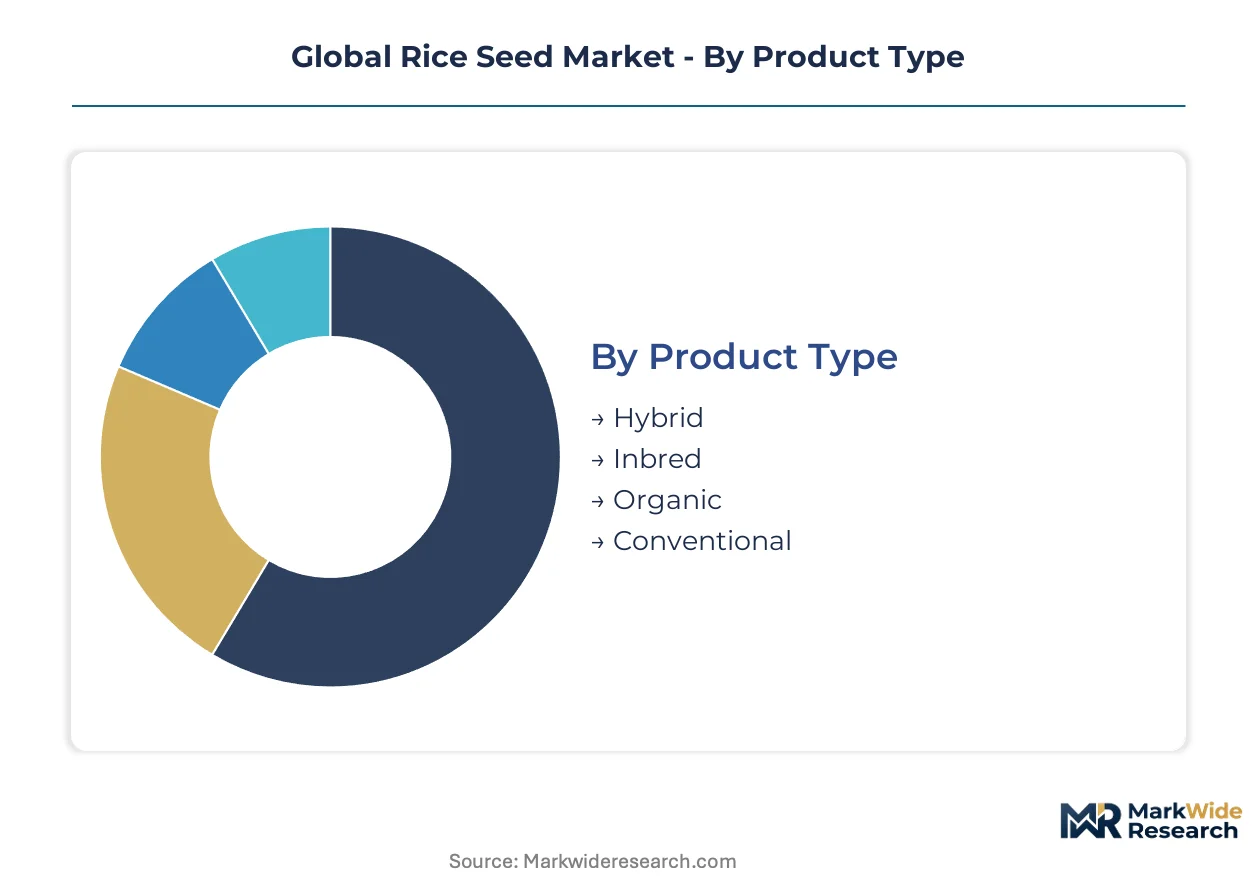
Rice seed segmentation reflects divergent farmer economics across tropical and temperate cultivation zones. Certified hybrid varieties command premium positioning in mechanized farming systems, while informal seed exchange networks sustain inbred demand among resource-constrained smallholders. Distribution channel evolution and end-user procurement centralization are restructuring margin capture across the value chain.
Product Type:
Farmer-saved seed from prior harvests exerts persistent substitution pressure on formal certified segments, particularly where regulatory enforcement remains weak and germplasm intellectual property protection is difficult to police.
- Hybrid:Produced through controlled crosses between genetically diverse parent lines to exploit yield heterosis. Demand concentrates in India's Gujarat and Haryana states, where state-backed procurement systems under the Seeds Act mandate certified inputs for subsidized credit access. Water-stressed germplasm innovation from marker-assisted selection pipelines is accelerating farmer conversion from saved seed.
- Inbred:Open-pollinated varieties maintained through successive generations with stable genetic composition. Penetration remains dominant across Bangladesh's fragmented smallholder base, where informal seed exchange networks and low capital availability limit hybrid adoption despite yield penalties.
- Organic:Certified production excluding synthetic inputs and genetically modified germplasm. Niche positioning in Japan's JAS-certified export rice segment and select European specialty markets.
- Conventional:Standard certified varieties without organic or hybrid designation. Volume positioning in Brazil's MAPA-registered cultivar system for domestic consumption markets.
Hybrid retains volume leadership among certified commercial channels; organic holds the steepest expansion trajectory in premium export-oriented segments.
Distribution Channel:
Channel cost structures stratify sharply between high-touch advisory models and transactional digital platforms, with margin compression forcing portfolio prioritization toward segments capable of bearing technical support overhead.
- Direct Sales:Manufacturer-to-farmer relationships with bundled agronomic advisory. Concentrating in Vietnam's Mekong Delta progressive farmer associations, where yield demonstration networks justify premium positioning.
- Retail:Input dealer and agricultural supply store networks. Dominant across India's Punjab cooperative procurement consolidation, though margin capture is fragmenting toward manufacturer-direct relationships.
- E-commerce:Digital platforms enabling direct-to-farmer transactions. Expanding most quickly in Bangladesh and Indonesia, where mobile penetration and last-mile logistics improvements are bypassing traditional cooperative monopolies.
- Wholesalers:Bulk distribution to regional aggregators and secondary dealers. Volume positioning in China's state-backed seed supply system for national food security reserves.
Retail maintains channel volume leadership; e-commerce is climbing the fastest in smallholder-dominant South and Southeast Asian markets.
End User:
Procurement centralization among progressive farmer associations is displacing traditional cooperative intermediaries, restructuring demand concentration toward entities capable of technical evaluation and bulk negotiation.
- Farmers:Individual cultivators purchasing for personal production. Demand fragmenting across Indonesia's archipelago smallholder base, where digital platform access is enabling direct manufacturer relationships.
- Agricultural Cooperatives:Collective purchasing entities aggregating member demand. Concentrating in India's Haryana and Punjab, though losing margin capture to direct manufacturer relationships with progressive associations.
- Seed Companies:Enterprises producing certified seed for downstream distribution. Brazil's MAPA-registered cultivar system attracts germplasm licensing investments for climate-resilient variety development.
- Research Institutions:Public and private breeding programs evaluating germplasm. China's Ministry of Agriculture and Rural Affairs variety approval system channels state-backed institute demand.
Farmers retain end-user volume leadership; seed companies are gaining share fastest through vertical integration into certified production.
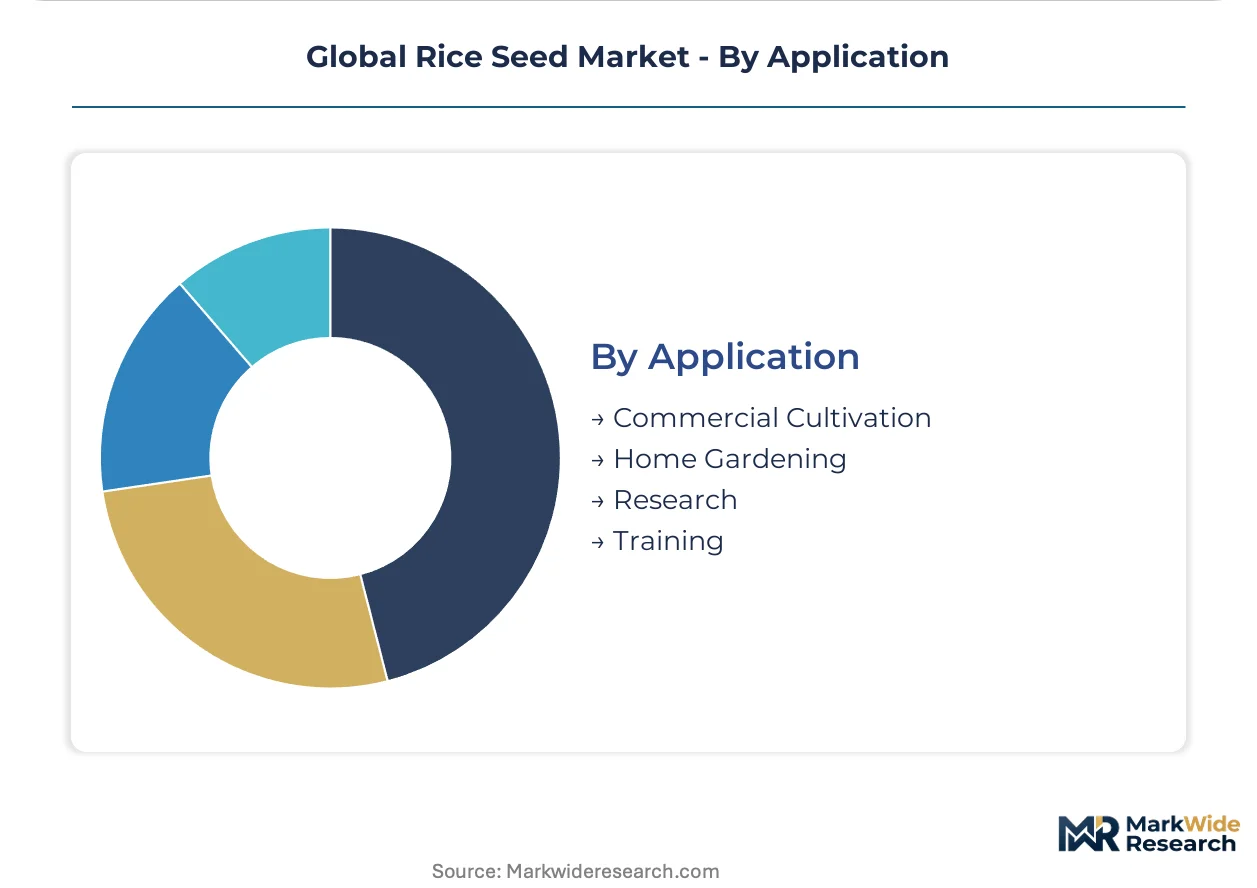
Application:
Research and training applications exhibit supply concentration in OECD Seed Schemes member countries, creating regulatory arbitrage for germplasm movement and varietal evaluation protocols.
- Commercial Cultivation:Production-scale farming for commodity or specialty markets. Dominates volume across Brazil's Cerrado mechanized rice operations and India's eastern coastal plains.
- Home Gardening:Small-scale cultivation for personal consumption. Niche positioning in Japan's suburban specialty varieties and select European heritage germplasm preservation networks.
- Research:Germplasm evaluation, trait discovery, and breeding pipeline development. Concentrating in Philippines and Indonesia tropical breeding stations adopting CRISPR-edited lines at accelerated evaluation cycles.
- Training:Educational demonstration and capacity building. Supported by India's Central Seed Committee certification requirements under formal extension programs.
Commercial cultivation retains application volume leadership; research is expanding most quickly through gene-edited germplasm pipeline acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Seeds Act mandates and China's streamlined gene-edited crop approval tracks are accelerating certified seed formalization across Asia's dominant cultivation belts. Brazil's MAPA fast-track registration and Vietnam's Mekong Delta mechanization are reshaping commercial procurement patterns in parallel.
India
Haryana and Punjab's progressive farmer associations are displacing cooperative procurement monopolies through direct manufacturer relationships. The Central Seed Committee certification requirements under the Seeds Act are phasing out informal distribution channels. Gujarat's state-backed procurement systems mandate certified hybrid inputs for subsidized credit access, concentrating demand conversion from farmer-saved seed.
China
The Ministry of Agriculture and Rural Affairs variety approval system channels state-backed institute demand toward proprietary hybrid development. Separate regulatory tracks for gene-edited crops lacking foreign DNA reduce approval timelines relative to transgenic varieties. Hunan and Jiangsu breeding stations are accelerating evaluation cycles for CRISPR-edited tropical indica lines through joint ventures with multinational germplasm licensors.
Brazil
MAPA's streamlined cultivar registration for climate-resilient varieties attracts germplasm licensing investments from international seed companies. The Cerrado's mechanized rice operations concentrate commercial cultivation volume for domestic consumption markets. Rio Grande do Sul's seed production infrastructure supports certified multiplication under OECD Seed Schemes harmonization protocols.
Vietnam
Mekong Delta progressive farmer associations justify premium hybrid positioning through yield demonstration networks with bundled agronomic advisory. E-commerce platform expansion fragments traditional cooperative procurement monopolies across the delta's fragmented smallholder base. Can Tho and An Giang provinces concentrate direct-to-farmer digital channel penetration.
Indonesia
Tropical breeding stations in Java and Sumatra are adopting CRISPR-edited lines at accelerated evaluation cycles for rainfed lowland zones. Mobile penetration and last-mile logistics improvements enable e-commerce platforms to bypass traditional cooperative intermediaries. The archipelago's fragmented smallholder base is fragmenting demand across direct manufacturer relationships enabled by digital platform access.
Global Rice Seed Market Competitive Environment
Player mix skews toward integrated agrochemical-seed conglomerates with captive breeding infrastructure and proprietary germplasm libraries. Market structure concentrates around three strategic archetypes: multinational platforms with marker-assisted selection pipelines, state-backed national champions controlling cytoplasmic male sterile parent lines, and regional specialists with tropical adaptation expertise. Competitive moves center on germplasm licensing partnerships and backward integration into seed production capacity.
Within the integrated multinational tier, Bayer AG, Syngenta Group, and Corteva Agriscience exemplify archetypes defined by breeding platform scale and proprietary hybrid technology. Bayer's position reflects germplasm leadership in tropical indica segments through integrated breeding infrastructure. Syngenta anchors water-stressed environment specialization via proprietary hybrid rice technology. Corteva occupies a position shaped by advanced marker-assisted selection pipelines that compress varietal development cycles. These three entities represent the dominant competitive anchors against which national champions and regional specialists define differentiated positioning.
| Leading Market Players |
|---|
| Bayer AG |
| Syngenta Group |
| Corteva Agriscience |
| Advanta Seeds - UPL |
| BASF SE |
| RiceTec Inc. |
| NUZIVEEDU SEEDS LTD |
| SL Agritech Corporation |
| Longping High-Tech |
| Others |
Value Chain & Pricing Dynamics
OECD Seed Schemes certification simultaneously gates supply qualification and price differentiation across the rice seed value chain, concentrating margin capture in certified channels while compressing returns for uncertified suppliers competing on commodity terms.
Pricing Analysis
Certification level under OECD Seed Schemes creates the primary spread between premium hybrid varieties and commodity inbred lines. Three-tier pricing structure across certified hybrid, standard certified, and informal farmer-saved seed segments reflects germplasm intellectual property intensity and varietal purity guarantees. Cost compression in standard certified tiers is intensifying because demonstration plot programs face fertilizer input volatility. Smallholder cooperatives in Bangladesh and Indonesia exhibit highest price sensitivity, while progressive farmer associations in Vietnam's Mekong Delta accept premium positioning for bundled agronomic advisory.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes are elevating inbound logistics costs for germplasm imports and parent line transfers. Production concentrates in China, India, and Brazil, with hybrid seed multiplication drawing from cytoplasmic male sterile parent lines controlled by state-backed breeding institutes. Supply chain risk centers on single-source vulnerability for critical parent line genetics concentrated in Chinese institutes. Distribution runs through agricultural cooperatives in India, direct manufacturer relationships in Vietnam, and state-backed reserve systems in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as e-commerce channels fragment traditional cooperative procurement monopolies and gene-edited germplasm pipelines compress varietal development timelines.
For Market Incumbents: Compound germplasm leadership through accelerated marker-assisted selection pipeline investment and backward integration into tropical breeding station capacity. CRISPR-edited trait platforms from emerging joint ventures with Chinese state institutes threaten proprietary hybrid positioning. Priority lever rests on captive control of water-stressed indica germplasm and direct channel relationships with progressive farmer associations displacing cooperative intermediaries. For New Entrants and Emerging Players: Anchor in Sub-Saharan Africa's Oryza glaberrima upland ecology gap, where commercial hybrid penetration remains minimal and farmer-saved seed practices dominate. Brazil's MAPA fast-track cultivar registration for climate-resilient varieties offers the most penetrable regulatory entry point. Go-to-market angle should leverage blockchain-enabled seed traceability as premium pricing mechanism targeting export-oriented segments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gene-edited germplasm pipeline development, favoring scale players with integrated breeding infrastructure over asset-light licensors. Long-term viability over the next decade hinges on regulatory proximity to streamlined approval tracks for edited crops lacking foreign DNA. Acquisition target archetype: regional specialists with tropical adaptation expertise and existing OECD Seed Schemes certification. Signal to watch: divergence in national biosafety protocols creating regulatory arbitrage opportunities for germplasm licensing.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Trait Pipeline Acceleration | Compresses varietal development timelines from conventional eight-year cycles to four-year evaluation windows. |
| Joint Venture with Chinese State Institutes | Secures regulatory proximity to streamlined gene-edited crop approval tracks under Ministry of Agriculture and Rural Affairs. |
| E-commerce Platform Expansion | Bypasses cooperative procurement monopolies in Bangladesh and Indonesia through direct-to-farmer digital channels. |
| Blockchain Seed Traceability Deployment | Enables premium pricing verification for varietal purity and origin in export-oriented segments. |
| Backward Integration into Seed Production | Captures margin pools from certified multiplication under OECD Seed Schemes harmonization protocols. |
Study Parameters
A standing panel of rice breeding program directors, seed company procurement executives, agricultural cooperative managers, and national seed certification officers provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against OECD Seed Schemes documentation, national variety registration databases from India's Central Seed Committee and China's Ministry of Agriculture and Rural Affairs, and customs trade flow records. Bottom-up triangulation across farmer-level demand estimation and top-down supply-side capacity assessment ensured cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, distribution channel, end user, and application, with additional granularity on regulatory framework clusters. CAGRs were derived from trend extrapolation of certified seed formalization rates and hybrid adoption curves. Industry-specific forecast inputs incorporated gene-edited trait approval timeline assumptions and e-commerce penetration trajectories in South and Southeast Asian smallholder markets.
Decision-makers should treat outputs as directional under base assumptions of sustained OECD Seed Schemes harmonization and stable national biosafety protocols; material deviation would warrant model refresh. Specific risk factors that could revise forecasts include abrupt regulatory reclassification of gene-edited varieties, parent line supply disruptions from Chinese institutes, and fertilizer cost spikes affecting demonstration plot program viability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
North America Chia Seeds Market
Seeds
Mustard Seeds Market
Seeds
Wax Gourd Seed Market
Seeds
Myanmar Seed Market
Seeds
Carrot Seed Oil Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
India Rice Seed Market
Seeds
Quinoa Seed Market
Seeds
Europe Forage Seed Market
Seeds
Buckwheat Seed Market
Seeds
Fruit Tomatoes Seed Market
Seeds
India Vegetable Seed Market
Seeds
Genetically Modified Seeds Market
Seeds
Asia-Pacific Cotton Seed Market
Seeds
Organic Sesame Seed Market
Seeds
Middle East and Africa Cannabis Seeds Market