
 United States Vegetable Seed Market | 2026-2036
United States Vegetable Seed Market Size, Share, and Industry Trends Forecast 2026-2036
United States Vegetable Seed Market Analytics
Project finance for vertical farming infrastructure is tilting competitive dynamics toward capital-rich suppliers. Bayer AG leverages its integrated trait platforms to anchor large-scale vegetable production contracts. Sakata Seeds Corporation specializes in heat-tolerant brassica genetics that sustain yields across the Sun Belt. Enza Zaden competes through protected greenhouse variety portfolios that dominate controlled-environment agriculture channels.
Vegetable seeds comprise sexually propagated planting material with specified germination rates, genetic purity thresholds, and pathogen-free certification standards, engineered to produce edible roots, stems, leaves, or fruits for human consumption. Hybrid seeds command the dominant value share due to proprietary trait stacking and yield consistency premiums, while organic seeds represent the fastest-expanding quality grade as certified acreage requirements tighten across downstream supply chains. Commercial farming absorbs the majority volume, though greenhouse cultivation segments extract superior per-unit margins through climate-optimized variety premiums.
The USDA enforces seed labeling and germination standards under the Federal Seed Act, while state departments of agriculture in California and Florida administer additional phytosanitary protocols that shape interstate distribution logistics. The EPA evaluates pesticide-tolerant trait registrations that determine which herbicide-resistant vegetable varieties reach market access. Stakeholders must monitor evolving state-level seed sovereignty legislation and carbon accounting rules that could redirect procurement toward regionally adapted, low-input varieties.
Market Dynamics
The USDA's Plant Variety Protection Act enforcement is accelerating proprietary germplasm investment, concentrating competitive advantage among firms with captive breeding programs and forcing smaller operators toward licensing arrangements or exit.
Growth Catalysts
- Controlled-environment agriculture:Greenhouse operators in California and Arizona are scaling climate-optimized variety procurement, creating pull for heat-tolerant genetics with premium pricing power.
- Organic certification mandates:The National Organic Program's tightened seed sourcing requirements are compelling commercial farms to convert acreage, expanding addressable market for untreated and organic-certified lines.
- Trait stacking platforms:Stacked disease resistance and herbicide tolerance genetics are reducing per-acre chemical inputs, lowering total cultivation costs for specialty crop producers.
Market Restraints
- Input cost volatility:Phosphorus-based fertilizers and freight energy costs are squeezing margin structures for seed multiplication operations across the Sun Belt.
- Supply concentration risk:California's Central Valley dominates domestic vegetable seed production, exposing distribution networks to drought-induced yield variability and water allocation disputes.
- Regulatory friction:The EPA's extended review timelines for novel trait registrations are delaying market access for next-generation herbicide-resistant varieties.
Strategic Opportunities
- Underpenetrated greenhouse corridors:Texas and Florida controlled-environment installations are expanding faster than varietal supply, creating first-mover advantage for adapted genetics.
- Carbon accounting integration:The IRA's agricultural emissions reduction incentives are rewarding low-input seed systems that reduce synthetic fertilizer dependency.
- Direct-to-grower digital channels:E-commerce platforms are disintermediating traditional distributor networks, enabling seed companies to capture margin and build proprietary grower data assets.
Industry Challenges
- Plant pathology expertise scarcity:Diagnostic capability for seed-borne pathogens is concentrating at a handful of university extension programs, constraining quality assurance scaling.
- Multi-year breeding capex cycles:Hybrid development pipelines require sustained capital commitment across 6-10 year trait introgression timelines, straining mid-tier R&D budgets.
- Phytosanitary compliance complexity:Interstate shipment certification requirements vary across state departments of agriculture, fragmenting logistics coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Vegetable Seed Market |
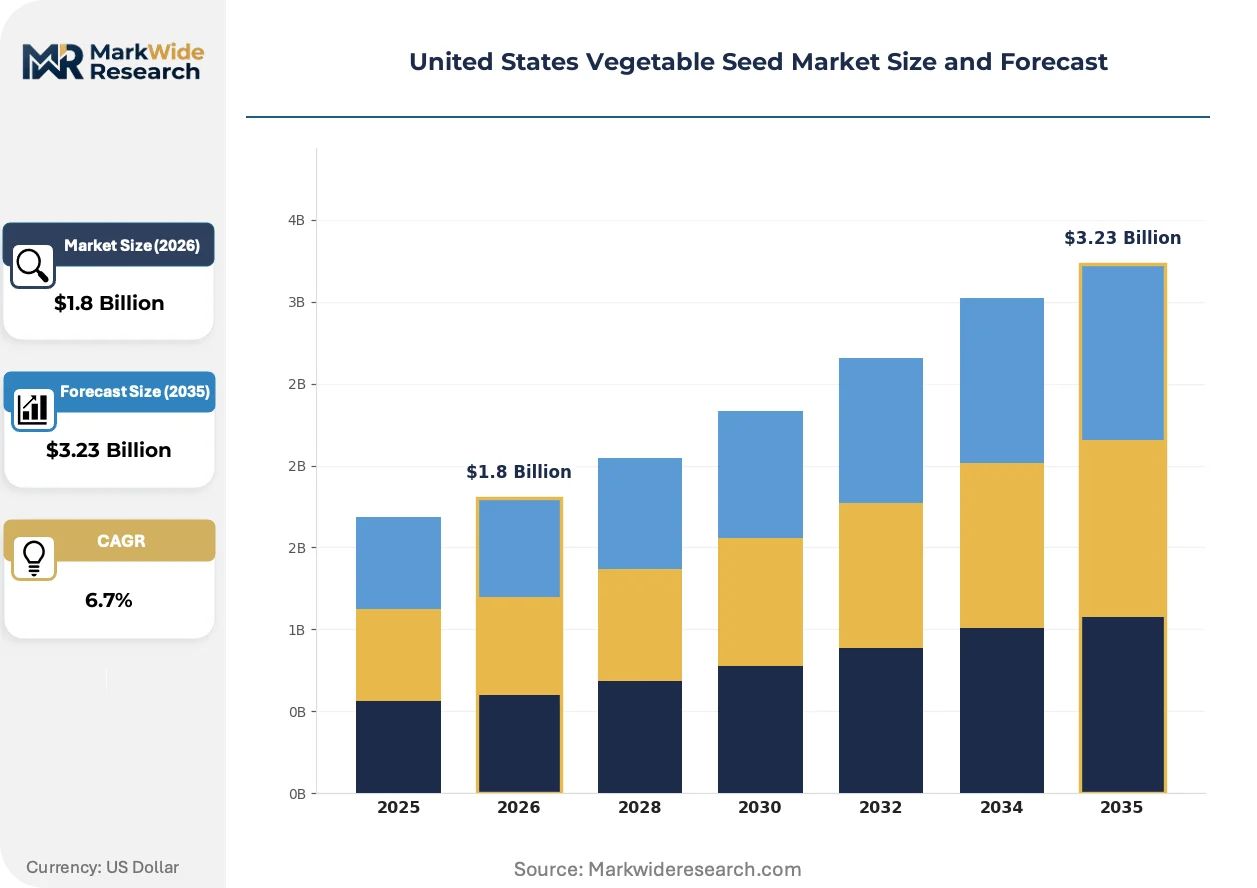
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open-Pollinated Seeds, Heirloom Seeds, Organic Seeds End Use: Home Gardening, Commercial Farming, Greenhouse Cultivation, Research Institutions Distribution Channel: Online Sales, Retail Stores, Direct Sales, Wholesale Distributors Quality Grade: Certified Seeds, Non-Certified Seeds, Conventional Seeds, Premium Seeds |
| Companies Covered | Bayer AG, Enza Zaden, Sakata Seeds Corporation, Bejo Zaden BV, Takii and Co Ltd, Groupe Limagrain, Syngenta Group, BASF SE, Rijk Zwaan Zaadteelt en Zaadhandel B V, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Vegetable Seed Market Evolving Landscape
Gene editing platforms are compressing trait development timelines while precision agriculture integration is reshaping how growers evaluate varietal performance, creating new data layers around seed selection decisions.
CRISPR-Cas9 applications in vegetable breeding are migrating from research-phase gene knockouts to commercial deployment for disease resistance and shelf-life extension. Large-scale tomato and pepper producers in California's Central Valley are piloting edited lines at scale. This technology is migrating from public university research stations to proprietary corporate pipelines, consolidating innovation capacity among well-capitalized breeders.
The USDA's updated enforcement posture under the Plant Variety Protection Act is extending intellectual property coverage to sexually reproduced varieties previously outside patent scope. Breeders are filing certificates at accelerated rates to secure exclusive commercialization rights. Specialty crop seed producers in Florida and Arizona are responding by redirecting licensing revenue toward in-house germplasm development rather than royalty-dependent models.
Subscription-based seed procurement is displacing annual spot purchasing among integrated vegetable operations with multi-year planting schedules. Large-scale producers are locking in varietal access through forward contracts that bundle genetics with agronomic support services. This pattern is most visible in California's Salinas Valley, where lettuce and leafy green specialists are consolidating supplier relationships to secure consistent quality grades for retail contract fulfillment.
United States Vegetable Seed Market Segmentation
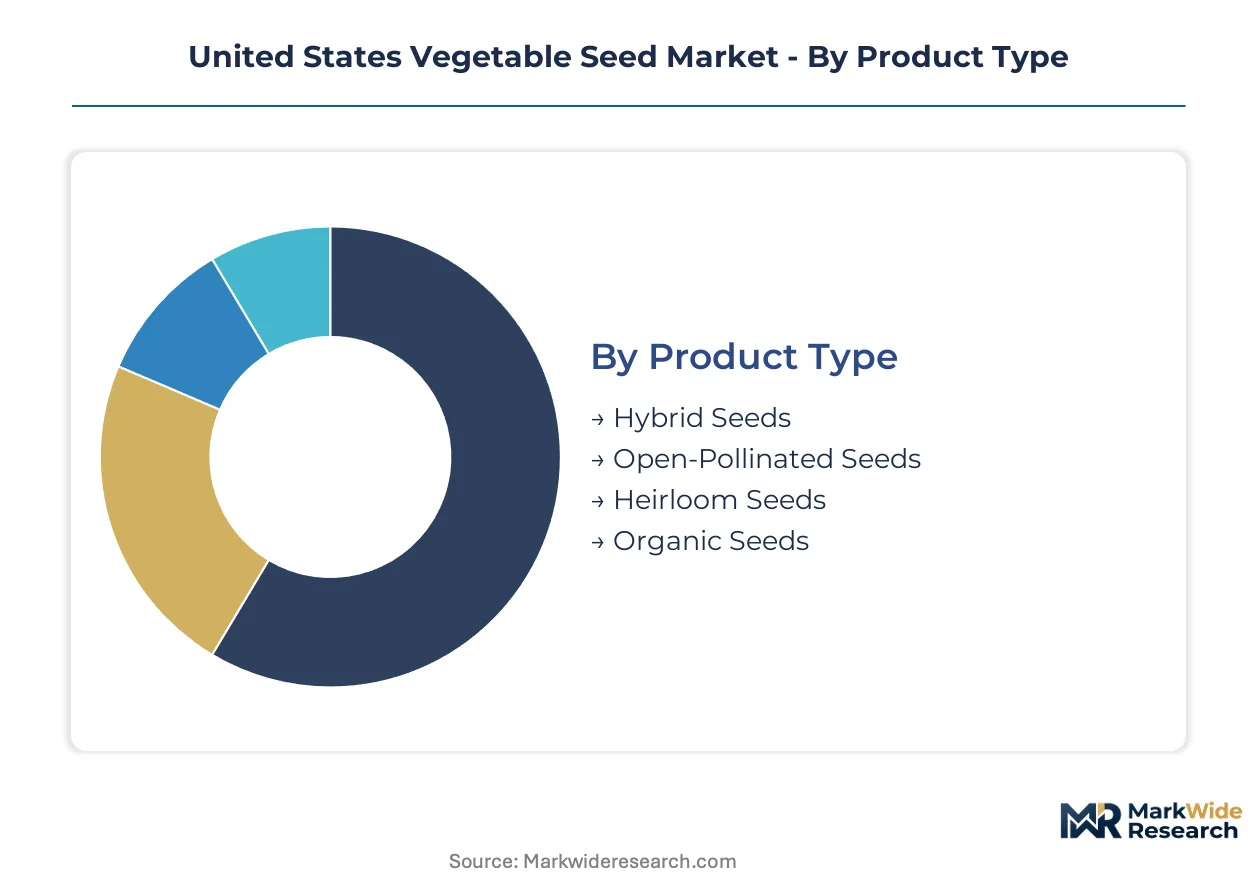
Vegetable seed segmentation reveals how procurement patterns diverge across grower sophistication levels and certification requirements. Each dimension shapes pricing power, distribution channel selection, and the intensity of agronomic support services bundled with genetic material.
Product Type:
After-sales service intensity peaks with hybrid seeds, where multi-year trait performance guarantees and field-level agronomic consulting lock in supplier relationships.
- Hybrid Seeds:Proprietary crosses combining inbred parental lines deliver standardized yield performance and stacked disease resistance. California's Central Valley specialty crop producers command premium volumes, driven by retail contract fulfillment requirements for uniform fruit grading.
- Open-Pollinated Seeds:Genetically stable varieties maintained through natural pollination allow grower seed-saving and regional adaptation. Demand concentrates among organic-certified operations in the Upper Midwest, constrained by lower per-acre yield ceilings relative to hybrid alternatives.
- Heirloom Seeds:Heritage varieties preserved across generational farming operations carry distinct flavor profiles for direct-to-consumer and farmers market channels.
- Organic Seeds:Untreated, certified-organic propagation material satisfies National Organic Program sourcing mandates for certified acreage conversion.
Hybrid seeds hold the largest share; momentum sits with organic seeds as certified acreage requirements tighten.
End Use:
Customer sophistication determines service bundling complexity, with commercial farming operations extracting maximum value from integrated agronomy platforms.
- Commercial Farming:Large-scale specialty crop producers in California's Salinas Valley and Yuma, Arizona lock in varietal access through multi-year supply agreements. These contracts bundle genetics with precision planting recommendations and pest pressure monitoring.
- Greenhouse Cultivation:Controlled-environment operators in Texas and Florida corridors source climate-optimized varieties with premium pricing power, extracting superior per-unit margins through year-round production cycles.
- Home Gardening:Residential growers purchasing through retail and digital channels prioritize convenience and packet sizing over yield optimization.
- Research Institutions:University extension programs and USDA agricultural research stations acquire foundation seed stocks for regional adaptation trials and germplasm conservation.
Commercial farming dominates volume; greenhouse cultivation climbs the fastest on per-acre margin expansion.
Distribution Channel:
Channel selection reflects grower scale and the value placed on immediate inventory access versus technical consultation depth.
- Online Sales:E-commerce platforms disintermediate traditional distributor networks, enabling seed companies to capture margin and build proprietary grower data assets. Direct-to-grower digital channels are expanding fastest among integrated operations with multi-year planting schedules.
- Retail Stores:Farm supply cooperatives and garden centers serve hobbyist and small-scale commercial growers requiring immediate physical inventory access.
- Direct Sales:Breeder-to-grower relationships dominate large-volume hybrid procurement, embedding agronomic support into varietal selection decisions.
- Wholesale Distributors:Regional seed houses aggregate inventory across multiple genetic suppliers, fragmenting supplier-grower relationships.
Direct sales command the value concentration; online channels gain share fastest on data asset accumulation.
Quality Grade:
Certification tier determines germplasm purity guarantees and the regulatory documentation burden accompanying interstate shipment.
- Certified Seeds:USDA-accredited laboratories verify genetic purity, germination rates, and pathogen-free status through standardized testing protocols. California and Florida state departments of agriculture administer additional phytosanitary certification requirements.
- Premium Seeds:Elite genetic lines with enhanced trait packages command price premiums through performance guarantees and exclusive territory licensing.
- Conventional Seeds:Standard-grade propagation material meets baseline Federal Seed Act labeling requirements without enhanced purity certification.
- Non-Certified Seeds:Uncertified propagation material carries limited documentation, serving price-sensitive growers with established supplier relationships.
Certified seeds anchor procurement standards; premium seeds show steepest expansion trajectory on trait-stacking value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a modest trade surplus in vegetable seeds, exporting proprietary hybrid genetics to Mexico and Canada while importing specialized greenhouse varieties from Dutch and Japanese breeders. Water stress and labor shortages are redistributing production capacity across state boundaries. Federal water policy and state-level seed sovereignty legislation are accelerating regional specialization.
California
California's Central Valley and Salinas Valley anchor domestic production of lettuce, tomato, and brassica seeds. The State Water Resources Control Board's groundwater sustainability mandates are forcing seed multiplication operations toward precision irrigation and deficit-tolerant genetics. Fresno and Monterey counties concentrate the nation's largest hybrid seed production facilities, where drought-adapted variety development commands premium R&D investment.
Florida
Florida's winter vegetable corridor generates year-round demand for heat-tolerant pepper and tomato varieties resistant to bacterial spot and TYLCV. The Florida Department of Agriculture and Consumer Services enforces enhanced phytosanitary certification for interstate seed shipments. The Immokalee and Palmetto-Ruskin growing districts host expanding greenhouse operations sourcing climate-optimized genetics from protected-culture specialists.
Arizona
Arizona's Yuma and Maricopa counties supply leafy greens to national retail chains during winter months, driving demand for downy mildew-resistant lettuce seed. The Arizona Department of Water Resources' assured water supply requirements are pushing seed producers toward deficit-irrigation-tolerant germplasm. Controlled-environment agriculture installations around Phoenix and Tucson are outpacing varietal supply, creating procurement bottlenecks for adapted genetics.
Texas
Texas's Winter Garden and Rio Grande Valley regions are expanding vegetable acreage as water constraints shift production from California. The Texas Department of Agriculture administers seed certification programs aligned with Federal Seed Act baseline standards. Emerging greenhouse clusters in the Dallas-Fort Worth metroplex and Lower Rio Grande Valley are attracting seed suppliers seeking first-mover positioning in underpenetrated controlled-environment corridors.
Pacific Northwest
Washington's Skagit Valley and Oregon's Willamette Valley specialize in brassica and onion seed production benefiting from cool, dry harvest conditions that reduce pathogen pressure. The Washington State Department of Agriculture's organic certification infrastructure supports untreated seed multiplication for national organic supply chains. Seed cleaning and conditioning facilities in Mount Vernon and Albany process material for distribution across western specialty crop zones.
United States Vegetable Seed Market Competitive Landscape
On the supply side, the industry is consolidating around integrated trait platforms and captive germplasm pipelines, with mid-tier breeders facing pressure to license or exit. Three strategic archetypes dominate: multinational agrochemical conglomerates with stacked trait portfolios, specialized vegetable breeders with protected greenhouse and field varieties, and regional seed houses serving localized adaptation needs. Competitive dynamics center on M&A-driven germplasm consolidation and backward integration into proprietary breeding infrastructure.
Within the multinational tier, Bayer AG and BASF SE exemplify the agrochemical-integrated model, anchoring large-scale production contracts through bundled input offerings. Specialized vegetable genetics are represented by Enza Zaden and Sakata Seeds Corporation, occupying positions defined by protected variety portfolios and climate-adapted germplasm. These firms sit within a competitive structure where R&D scale and regulatory navigation capability determine access to commercial farming procurement channels.
| Leading Market Players |
|---|
| Bayer AG |
| Enza Zaden |
| Sakata Seeds Corporation |
| Bejo Zaden BV |
| Takii and Co Ltd |
| Groupe Limagrain |
| Syngenta Group |
| BASF SE |
| Rijk Zwaan Zaadteelt en Zaadhandel B V |
| Others |
Value Network & Pricing Analysis
California water allocation disputes create simultaneous pressure on seed multiplication costs and geographic sourcing decisions, compressing margin structures for Sun Belt producers while forcing buyers toward premium drought-tolerant genetics.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the United States vegetable seed market. Three-tier pricing structure across premium, standard, and economy levels separates certified hybrid lines with trait-stacking guarantees from untreated open-pollinated varieties and non-certified propagation material. Cost compression in standard-grade seeds is intensifying because phosphorus-based fertilizer and freight energy inputs are squeezing seed multiplication operations. Home gardening segments show highest price sensitivity, while greenhouse operators extracting year-round production premiums demonstrate lowest sensitivity to varietal cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for vegetable seed operations dependent on phosphorus-based fertilizer imports and specialized conditioning equipment. Domestic production concentrates in California, Florida, and Arizona, with germplasm development pipelines drawing from proprietary corporate breeding stations and USDA agricultural research stations. Supply chain vulnerability rests on single-source dependency for heat-tolerant brassica genetics and drought-adapted tomato lines. Distribution runs through breeder-to-grower direct sales for large-volume hybrid procurement, supplemented by regional seed houses aggregating inventory across multiple genetic suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States vegetable seed market sits in a cyclical recovery phase driven by the IRA's agricultural emissions reduction incentives redirecting procurement toward low-input varieties.
For Market Incumbents: Entrench proprietary germplasm positions by accelerating in-house breeding infrastructure investment and securing Plant Variety Protection Act certificates for sexually reproduced varieties. Bayer AG and BASF SE demonstrate the defensive value of stacked trait platforms that anchor large-scale production contracts. Counter emerging pressure from gene-editing entrants by deepening agronomic service bundling that locks in multi-year supply relationships. For New Entrants and Emerging Players: Pursue underpenetrated greenhouse corridors in Texas and Florida where controlled-environment installations outpace varietal supply. Climate-optimized lettuce and pepper genetics for deficit-irrigation conditions represent the most penetrable white space. Establish first-mover positioning through direct-to-grower digital channels that disintermediate traditional distributor networks and build proprietary data assets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized vegetable breeders with protected greenhouse portfolios and captive heat-tolerant germplasm. Long-term viability hinges on R&D scale and regulatory navigation capability across the projection horizon. Watch EPA review timelines for novel herbicide-resistant trait registrations as the critical inflection signal for next-generation variety market access.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Germplasm Development | Plant Variety Protection Act enforcement accelerates investment in captive breeding pipelines. |
| Climate-Optimized Variety Launch | Heat-tolerant genetics capture premium pricing in Arizona and Florida greenhouse corridors. |
| Direct-to-Grower Digital Channel | E-commerce platforms enable margin capture and proprietary agronomic data accumulation. |
| Trait Stacking Platform Expansion | Stacked disease resistance reduces chemical inputs for California Central Valley specialty crops. |
| Carbon Accounting Integration | IRA incentives reward low-input seed systems that reduce synthetic fertilizer dependency. |
Research Methodology
Desk research of USDA germplasm databases, EPA trait registration filings, and state agricultural department certification records preceded structured interviews with vegetable seed breeders, greenhouse operations managers, and specialty crop procurement directors. Primary fieldwork with California Central Valley growers and Arizona controlled-environment operators combined with secondary validation against Federal Seed Act enforcement patterns and National Organic Program sourcing requirements. Bottom-up variety-level demand modeling triangulated against top-down market sizing from trade flow analysis.
Assumptions around water allocation stability in California and IRA incentive continuity were held fixed, while organic certification mandate stringency and gene-editing regulatory posture were treated as scenario variables across the projection horizon. Segmentation modeling captured product type, end use, distribution channel, and quality grade dimensions with additional granularity on greenhouse versus field production systems. CAGRs derived from trend extrapolation of varietal adoption curves and pricing power evolution in climate-adapted genetics.
Macroeconomic conditions sit as an overlay; deviation in fertilizer commodity prices, freight energy costs, or federal agricultural subsidy levels would shift the trajectory. Forecasts reflect assumptions around regulatory enforcement continuity and breeding pipeline timelines specific to hybrid development cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Cucumber Seeds Market
Seeds
Ghana Seed Extract Market
Seeds
Myanmar Seed Market
Seeds
Mexico Seed Market
Seeds
Thailand Vegetable Seed Market
Seeds
Europe Grain Seed Market
Seeds
China Vegetable Seed Market
Seeds
Apple Seed Oil Market
Seeds
Glycine Soja (Soybean) Seed Extract Market
Seeds
North America Seeds Market
Seeds
India Seed Market
Seeds
Vegetable Seed Protein Market
Seeds
Pasture Seeds Market
Seeds
Global Forage Seeds Market
Seeds
Australia Oilseed Market
Seeds
Asia Pacific Tomato Seed Oil Market