
 Global Alfalfa Seed Market | 2026-2036
Global Alfalfa Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alfalfa Seed Market Foresight
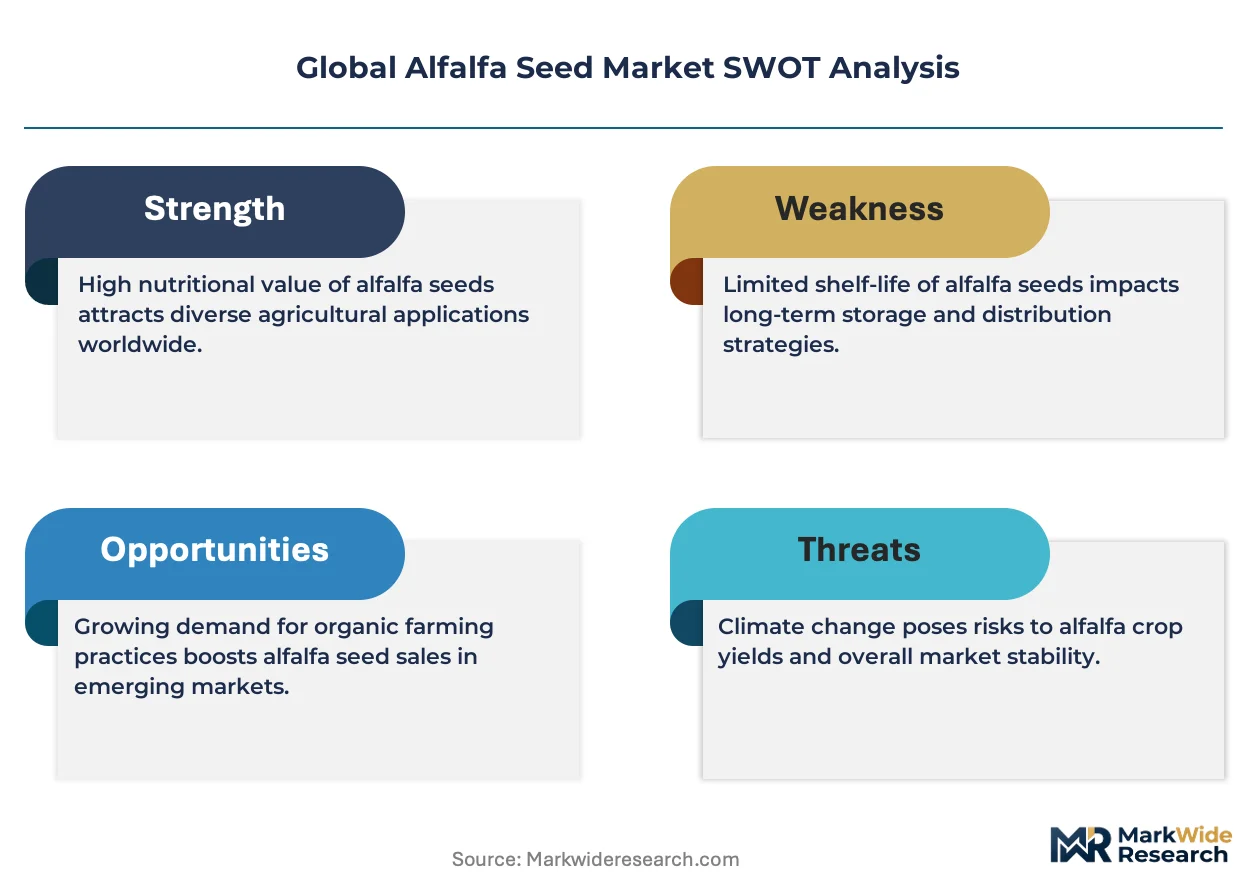
Project finance and contract-growing arrangements for certified seed multiplication is narrowing the competitive field to operators with balance-sheet depth. DLF Seeds leverages its integrated breeding-station network across Denmark and the Netherlands to control germplasm flow from laboratory to farm gate. S&W Seed Company anchors its position through proprietary non-dormant varieties bred for saline-alkali tolerance in Central Asian markets. Corteva Agriscience competes by extending its trait-licensing architecture into forage crops, applying the same molecular-stack discipline it deploys in row-crop genetics.
Alfalfa seed comprises the dried, germinable ovule of Medicago sativa, typically bred for fall dormancy ratings of three to nine and seed purity standards exceeding ninety percent certified germination under AOSA protocols; its industrial purpose centers on establishing perennial legume stands that fix atmospheric nitrogen while producing protein-dense haylage and hay for ruminant feed systems. Herbicide-tolerant seed types now command premium positioning as glyphosate and imazamox resistance traits reduce establishment weed-control costs for dairy operators in water-stressed districts. Organic seed lines remain structurally supply-constrained, with limited certified acreage and multi-year transition requirements creating margin pools for growers who navigate the three-year land-history verification protocols.
The USDA's Plant Variety Protection Office and the OECD Seed Schemes together establish the intellectual-property and certification baselines that govern cross-border germplasm trade, while India's BIS seed-labeling regulations and the EU's F-Gas Regulation on soil fumigants reshape product formulation and packaging requirements in their respective jurisdictions. Stakeholders must monitor how gene-editing regulatory classifications in Brazil, Argentina, and the United States diverge, as these determinations will dictate which trait-development pipelines receive capital allocation and which remain confined to conventional breeding budgets.
Market Dynamics
CRISPR-based trait editing and drought-resistance marker-assisted selection are compressing variety development timelines while concentrating capital among operators with integrated breeding-to-distribution infrastructure.
Growth Catalysts
- India's BIS seed-labeling regulations:Mandatory germination and purity disclosures on certified seed packaging are accelerating formal-channel adoption among Punjab dairy cooperatives seeking traceable forage inputs.
- Saline-alkali tolerance breeding:Proprietary non-dormant varieties bred for Central Asian conditions are opening acreage previously excluded from alfalfa production due to soil chemistry constraints.
- San Joaquin Valley water stress:Dairy operators facing groundwater sustainability mandates are prioritizing water-efficient forage genetics over conventional hay imports.
Market Restraints
- Multi-year organic transition costs:Three-year land-history verification protocols under USDA National Organic Program rules lock out conventional growers seeking organic premium capture.
- Soil fumigant restrictions:EU F-Gas Regulation phase-down of methyl bromide alternatives is elevating seed treatment costs for exporters serving European forage markets.
- Perennial stand establishment risk:Single-season crop failure during the establishment year exposes growers to total capital loss without revenue offset, constraining new entrant participation.
Strategic Opportunities
- Saudi Arabia irrigated zone expansion:Ministry of Environment, Water and Agriculture subsidies for fodder crop self-sufficiency are creating dedicated offtake channels for heat-tolerant certified varieties.
- Gene-editing regulatory convergence:Brazil's CTNBio classification of certain CRISPR applications as non-GMO reduces registration burden versus transgenic trait pipelines.
- Direct-to-farm digital seed distribution:Platform-based procurement bypassing traditional dealer networks is capturing margin compression in Australia's Riverina dairy districts.
Industry Challenges
- Quantitative genetics expertise scarcity:Marker-assisted selection programs require computational breeding specialists whose training pipelines lag commercial demand by approximately five years.
- OECD Seed Scheme certification timelines:Multi-season field testing and post-control plot verification extend variety release cycles, compressing patent-effective commercialization windows.
- Herbicide-tolerant trait stewardship:Glyphosate resistance management protocols impose grower education burdens and refuge planting requirements that complicate scale-up execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alfalfa Seed Market |
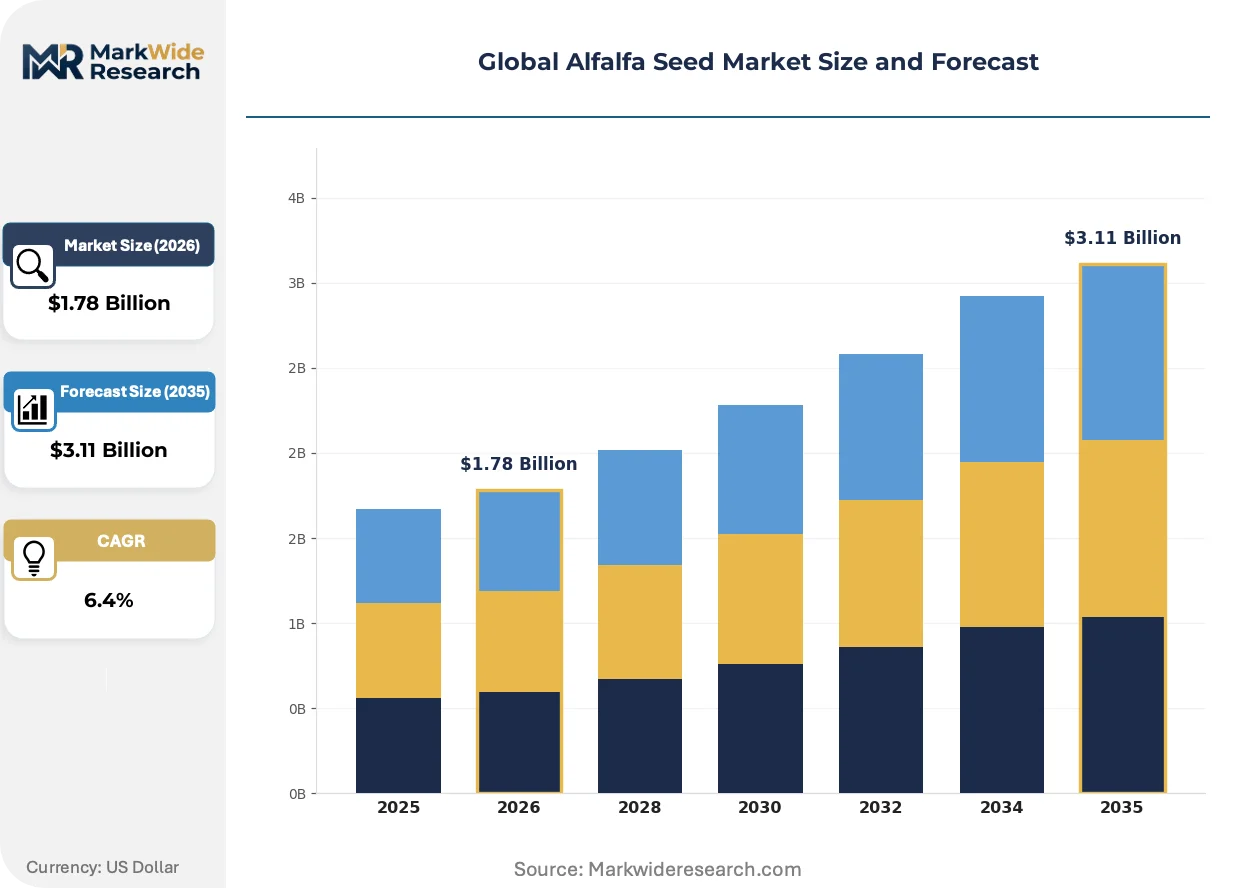
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
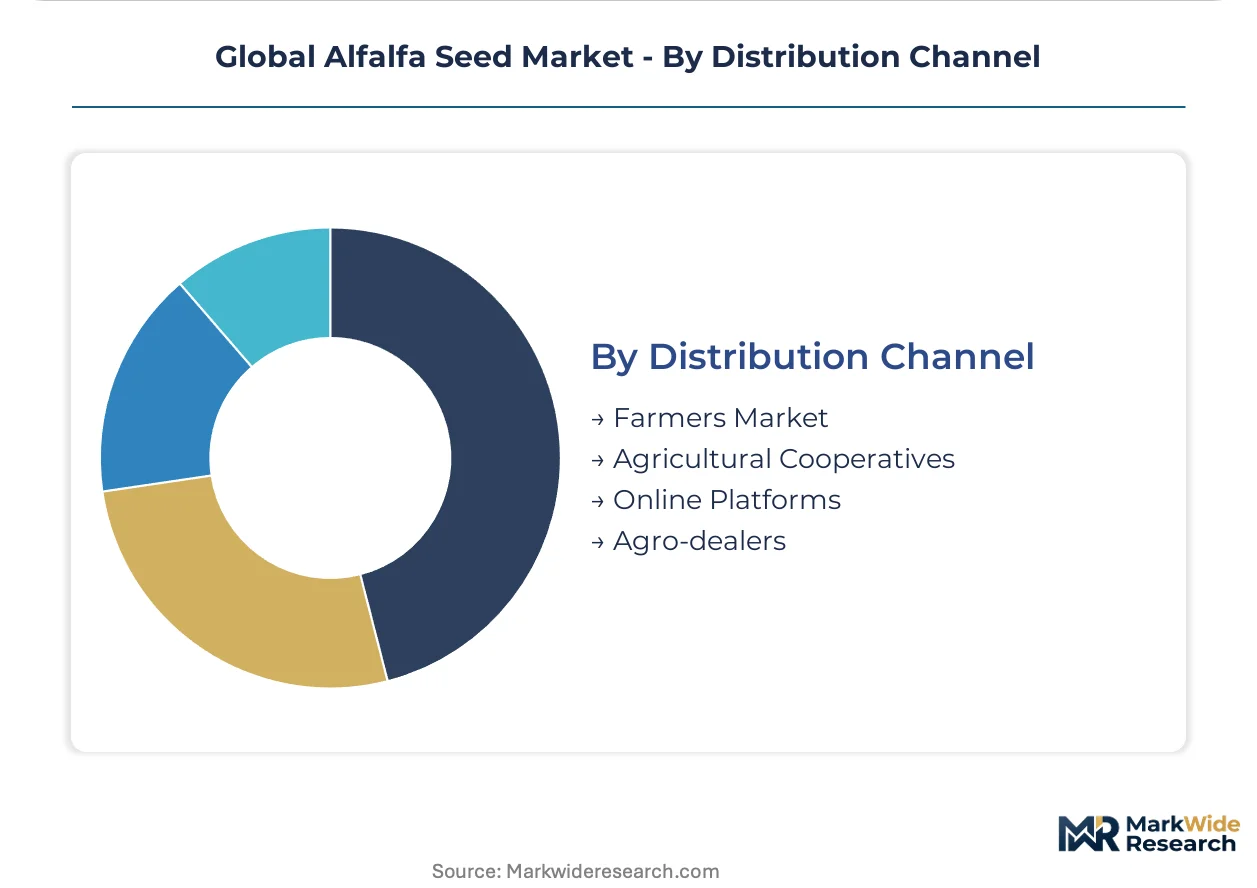
| Segmentation | Seed Type: Conventional, Herbicide-Tolerant, Insect-Resistant, Certified, Organic End Use: Dairy Farming, Livestock Grazing, Biofuel Production, Soil Improvement Form: Pelleted, Coated, Crushed, Bulk, Pre-treated Distribution Channel: Farmers Market, Agricultural Cooperatives, Online Platforms, Agro-dealers |
| Companies Covered | Alforex Seeds, DLF Seeds, Corteva Agriscience, Forage Genetics International, S&W Seed Company, Allied Seed, Royal Barenbrug Group, La Crosse Seed, Dyna-Gro Seed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alfalfa Seed Market Shifts & Advancements
Genomic selection tools and regulatory reclassifications of editing techniques are rewriting variety development economics while procurement digitization restructures traditional seed distribution hierarchies.
Genomic prediction models integrating high-throughput phenotyping data are migrating from experimental breeding stations at Copenhagen University into commercial pipelines at DLF Seeds and S&W Seed Company. Dairy cooperatives in California's Central Valley now specify predicted forage yield and fiber digestibility metrics in procurement tenders. This capability compression is collapsing the historical advantage of decade-long field trial networks over rapid-cycle greenhouse validation.
Argentina's CONABIA regulatory framework for gene-edited crops creates a jurisdictional arbitrage opportunity absent from the EU's process-based GMO classification. Breeders with Argentine multiplication capacity can advance CRISPR-derived drought traits through local field trials while awaiting US USDA-APHIS determinations on equivalent constructs. The divergence is fragmenting global variety release synchronization and forcing regionalized germplasm inventory strategies.
Contract-growing arrangements for certified seed multiplication are displacing spot-market acreage procurement among integrated operators. Dairy processors in Australia's Murray-Darling Basin now specify exclusive variety blocks with guaranteed offtake pricing, transferring yield risk to seed companies while securing varietal purity for branded haylage programs. This channel consolidation is visible most acutely in Tasmania's irrigated seed production districts where processor balance-sheet depth filters out smallholder multipliers.
Global Alfalfa Seed Market Segmentation
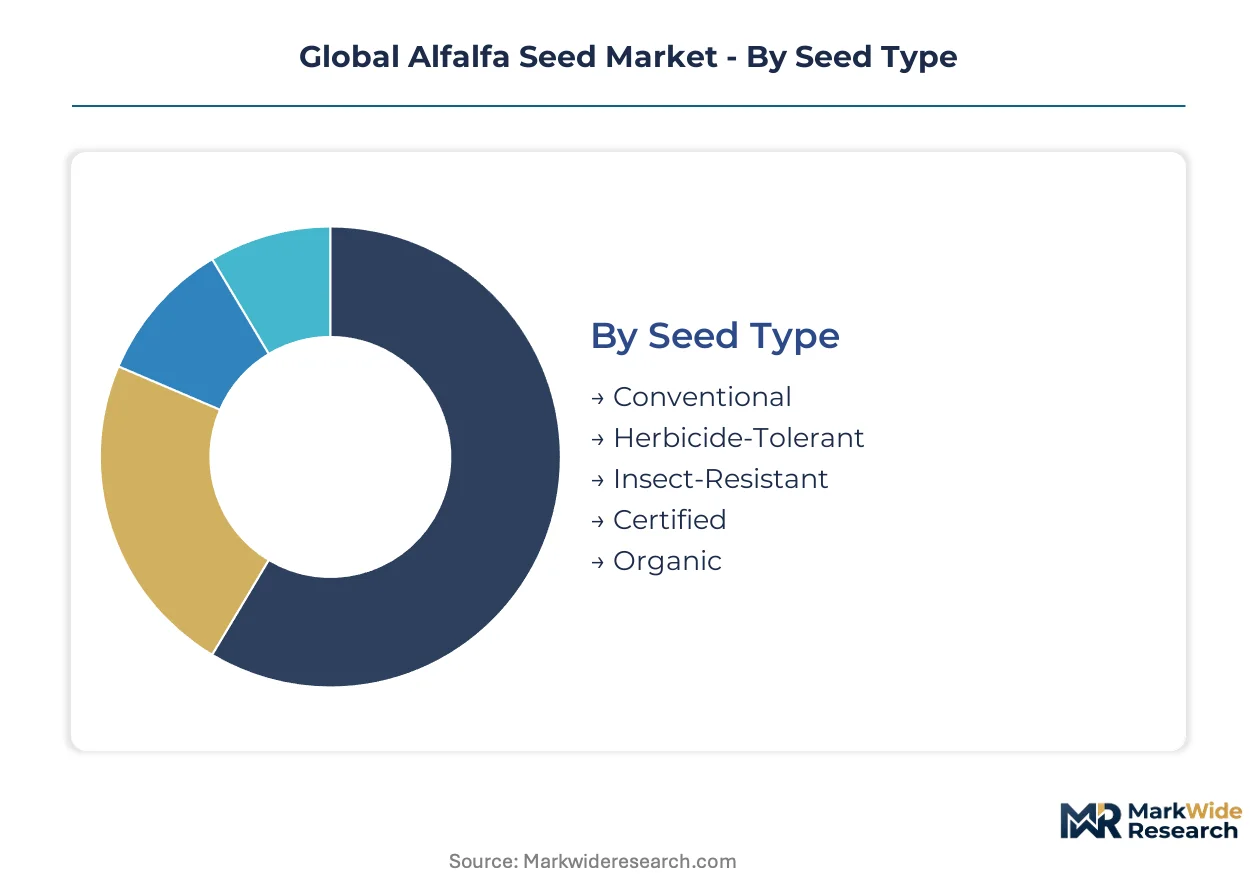
Alfalfa seed segmentation reflects divergent service requirements across certified multiplication channels and direct farm-gate delivery. Dairy processors in California's Central Valley and Australia's Riverina Basin now specify varietal purity guarantees and establishment-year technical support as procurement criteria, elevating after-sales intensity above transactional seed sales.
Seed Type:
After-sales service intensity peaks with herbicide-tolerant and organic lines, where grower education on resistance management and multi-year transition protocols creates recurring advisory relationships.
- Conventional:Standard certified germplasm bred for fall dormancy ratings three to nine under AOSA protocols. Demand concentrates among Punjab dairy cooperatives seeking traceable forage inputs under BIS labeling mandates, with volume procurement tied to cooperative bulk-purchase programs.
- Herbicide-Tolerant:Glyphosate and imazamox resistance traits engineered through marker-assisted selection. Dairy operators in California's San Joaquin Valley prioritize these varieties to reduce establishment-year weed-control costs amid groundwater sustainability constraints.
- Insect-Resistant:Germplasm incorporating pest-tolerance markers for alfalfa weevil and aphid pressure zones. Limited commercial penetration outside established breeding pipelines.
- Certified:OECD Seed Scheme-compliant varieties with field-inspected multiplication records. Saudi Arabia's Ministry of Environment, Water and Agriculture subsidies specify certified germplasm for irrigated fodder expansion zones.
- Organic:Three-year land-history verified seed lines under USDA National Organic Program rules. Supply constraints from limited certified acreage create premium capture opportunities for growers navigating verification protocols.
By volume, Conventional leads. By growth pace, Herbicide-Tolerant is ahead.
End Use:
Cost tier differentiation separates high-input dairy systems from low-intensity grazing operations, with biofuel and soil improvement applications occupying intermediate price bands.
- Dairy Farming:Protein-dense haylage and hay production for ruminant feed systems. California Central Valley processors specify predicted forage yield and fiber digestibility metrics in procurement tenders, compressing traditional field-trial advantages.
- Livestock Grazing:Perennial stand establishment for rotational pasture systems. Australian Riverina Basin operators favor non-dormant varieties with saline-alkali tolerance for extended grazing seasons.
- Biofuel Production:Lignocellulosic feedstock for anaerobic digestion and cellulosic ethanol pathways. Limited dedicated acreage outside integrated dairy-energy operations.
- Soil Improvement:Nitrogen-fixing cover crop applications in arable rotations. Demand clusters in India's Punjab region where rice-wheat systems require legume breaks.
Dairy Farming commands the premium tier. Biofuel Production shows the steepest expansion trajectory where policy supports anaerobic digestion infrastructure.
Form:
Volume concentration favors bulk delivery to large-scale multiplication contractors, while pelleted and coated forms capture margin through precision-planting compatibility.
- Pelleted:Seed encased in inert clay matrix for precision drilling and uniform depth placement. Tasmania's irrigated seed production districts specify pelleted forms for mechanized establishment of exclusive variety blocks.
- Coated:Polymer or nutrient-fortified treatments enhancing germination uniformity. Prevalent in Saudi Arabia's controlled-environment fodder operations where establishment failure carries total capital loss risk.
- Crushed:Processed seed meal for specialized feed or inoculant applications. Niche volume outside multiplication channels.
- Bulk:Uncoated raw seed for large-scale sowing and further processing. Dominates contract-growing arrangements where processor balance-sheet depth filters smallholder participation.
- Pre-treated:Rhizobium inoculation and fungicide application at point of packaging. Required for organic-equivalent lines where synthetic seed treatments are prohibited.
Bulk forms dominate tonnage. Coated varieties are gaining share fastest in water-stressed districts.
Distribution Channel:
Customer type fragmentation separates cooperative-integrated dairy systems from independent operators, with platform-based procurement compressing traditional dealer margins.
- Farmers Market:Direct producer-to-grower sales at regional agricultural exchanges. Limited to small-volume heritage varieties and local adaptation trials.
- Agricultural Cooperatives:Member-owned procurement aggregating certified seed demand. Punjab dairy cooperatives leverage cooperative scale for BIS-compliant traceability documentation.
- Online Platforms:Digital seed distribution bypassing traditional dealer networks. Australia's Riverina Basin shows platform adoption capturing margin compression in branded haylage programs.
- Agro-dealers:Traditional rural retail with technical advisory services. Retains dominance in regions with limited broadband infrastructure and high grower education requirements.
Agricultural Cooperatives lead by volume. Online Platforms are expanding most quickly where processor-direct contracting reduces intermediary layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in alfalfa seed track divergent regulatory classifications for gene-edited germplasm. Argentina and Brazil now run net export positions on CRISPR-derived drought-tolerant lines, while the European Union maintains import dependency on conventional certified stock.
United States
Groundwater sustainability mandates in California's San Joaquin Valley are compressing hay imports and elevating local forage seed procurement. USDA's Plant Variety Protection Office governs intellectual-property baselines for cross-border germplasm trade. Dairy processors in the Central Valley now specify predictive forage metrics in certified seed tenders.
Argentina
CONABIA's regulatory framework for gene-edited crops creates jurisdictional arbitrage for CRISPR-derived drought traits awaiting US determinations. The country's national agricultural biotechnology regulator classifies certain editing applications as non-GMO, reducing registration burdens. Multiplication capacity in the Pampas region serves as a staging ground for germplasm awaiting synchronized global release.
India
BIS seed-labeling mandates are accelerating formal-channel adoption among Punjab dairy cooperatives seeking traceable forage inputs. The Bureau of Indian Standards enforces mandatory germination and purity disclosures on certified packaging. Irrigated zones in Punjab and Haryana concentrate demand for water-efficient legume breaks in rice-wheat rotations.
Saudi Arabia
Ministry of Environment, Water and Agriculture subsidies for fodder crop self-sufficiency are creating dedicated offtake channels for heat-tolerant certified varieties. The national agricultural subsidy program specifies OECD Seed Scheme-compliant germplasm for expansion zones. Controlled-environment fodder operations in Riyadh and the Eastern Province prioritize establishment-risk mitigation through coated seed forms.
Australia
Processor balance-sheet depth in the Murray-Darling Basin is filtering smallholder participation through contract-growing arrangements with guaranteed offtake pricing. The country's national agricultural chemicals regulator oversees seed treatment approvals for export compliance. Tasmania's irrigated seed production districts specify pelleted forms for mechanized establishment of exclusive variety blocks.
Global Alfalfa Seed Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in germplasm development and certified multiplication. The field narrows to operators with integrated breeding-to-distribution infrastructure capable of spanning OECD certification timelines. Three archetypes dominate: multinational trait licensors extending molecular-stack discipline into forage crops, regional breeding-station networks controlling germplasm flow from laboratory to farm gate, and proprietary variety developers targeting saline-alkali tolerance in niche geographies. Competitive moves concentrate on contract-growing arrangements for certified seed multiplication and direct-to-farm digital distribution platforms.
Among integrated breeding-station networks, DLF Seeds occupies a position exemplifying Denmark-to-Netherlands germplasm control. S&W Seed Company represents the proprietary variety developer archetype with non-dormant lines for Central Asian conditions. Corteva Agriscience anchors the multinational trait-licensor tier, extending row-crop molecular disciplines into forage genetics. Each sits within distinct capital-allocation pipelines shaped by regulatory divergence on gene-editing classifications.
| Leading Market Players |
|---|
| Alforex Seeds |
| DLF Seeds |
| Corteva Agriscience |
| Forage Genetics International |
| S&W Seed Company |
| Allied Seed |
| Royal Barenbrug Group |
| La Crosse Seed |
| Dyna-Gro Seed |
| Others |
Supply & Pricing Matrix
The Port of Rotterdam to Jeddah maritime corridor carries coated alfalfa seed shipments whose freight volatility compresses margins for European exporters while amplifying price premiums for heat-tolerant certified varieties in Saudi Arabia's controlled-environment fodder operations. This logistics artery concentrates pricing power among integrated breeding-to-distribution operators capable of absorbing container rate swings through captive multiplication acreage.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where dairy processors in California's Central Valley and Australia's Murray-Darling Basin specify varietal purity guarantees and establishment-year technical support. Price differentiation rests on OECD Seed Scheme certification tier and fall dormancy rating precision, with certified germplasm commanding substantial premiums over conventional bulk seed. Cost compression in the organic segment is intensifying because limited certified acreage and three-year land-history verification protocols constrain supply elasticity. Punjab dairy cooperatives operating under BIS labeling mandates exhibit the highest price sensitivity, while Saudi Arabia's Ministry of Environment, Water and Agriculture subsidy programs demonstrate the lowest.
Supply Chain Analysis
Elite germplasm foundation stock draws from Denmark, the Netherlands, and the United States, where DLF Seeds and Corteva Agriscience maintain proprietary breeding station networks. Raw material inputs hinge on methyl bromide alternative soil fumigants, rhizobium inoculant formulations, and polymer seed coating chemistries. Single-source vulnerability concentrates in Tasmania's irrigated seed production districts, where exclusive variety blocks for Australia's branded haylage programs depend on finite mechanized establishment capacity. Distribution runs through agricultural cooperatives in India's Punjab region and direct-to-farm digital platforms in Australia's Riverina Basin, bypassing traditional agro-dealer layers where processor balance-sheet depth permits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions for gene-edited germplasm creates multiple niche entry points, as Brazil's CTNBio non-GMO classification for certain CRISPR applications diverges from the EU's process-based GMO framework and generates arbitrage opportunities for variety developers.
For Market Incumbents: Harden germplasm control through backward integration into certified multiplication acreage in Argentina's Pampas region, where CONABIA's regulatory framework permits field trials of drought-tolerant CRISPR lines awaiting USDA-APHIS determinations. Deepen OECD Seed Scheme certification investments to compress post-control plot verification timelines and extend patent-effective commercialization windows against emerging platform-based distributors. For New Entrants and Emerging Players: Mid-tier dairy cooperatives in India's Haryana region represent the most penetrable entry point, as BIS seed-labeling mandates accelerate formal-channel adoption among operators seeking traceable forage inputs without incumbent exclusivity contracts. A go-to-market angle anchored on Rhizobium pre-treated organic-equivalent lines addresses supply constraints from limited certified acreage while navigating three-year land-history verification protocols. For Investors and Strategic Acquirers: Regulatory convergence on gene-editing classifications across Brazil, Argentina, and the United States reshapes the acquisition landscape, privileging operators with Argentine multiplication capacity capable of staging CRISPR-derived germplasm for synchronized global release. Long-term viability centers on computational breeding specialists and high-throughput phenotyping infrastructure. The signal to watch is USDA-APHIS determinations on drought-resistance constructs already field-trialed under CONABIA jurisdiction.| Strategic Initiative | Industry Significance |
|---|---|
| Contract-Growing Arrangement Expansion | Guaranteed offtake pricing transfers yield risk to seed companies while securing varietal purity for dairy processors in Australia's Murray-Darling Basin. |
| Direct-to-Farm Digital Platform Launch | Platform-based procurement in Australia's Riverina Basin captures margin compression in branded haylage programs by eliminating dealer intermediaries. |
| Saline-Alkali Tolerance Pipeline Investment | Proprietary non-dormant varieties for Central Asian conditions open acreage previously excluded from alfalfa production due to soil chemistry constraints. |
| CRISPR Trait Stewardship Program | Grower education on glyphosate resistance management protocols addresses refuge planting requirements that complicate scale-up execution in water-stressed districts. |
| Organic Certification Acreage Acquisition | Three-year land-history verified seed lines under USDA National Organic Program rules capture premium pools from structurally supply-constrained organic markets. |
Research Methodology
The analysis maps certified multiplication channels, trait-editing pipelines, and direct-to-farm distribution platforms, each validated through breeding program directors, dairy cooperative procurement officers, and seed treatment regulatory specialists. Primary interviews with OECD Seed Scheme inspectors, germplasm licensing executives, and Central Valley dairy nutritionists combined with secondary validation from USDA Plant Variety Protection Office filings, FAO forage crop databases, and BIS seed-labeling compliance records. Bottom-up acreage estimates and top-down forage demand projections underwent cross-referencing against customs trade data and national agricultural subsidy program disclosures.
Assumptions held fixed include current regulatory classifications of gene-edited crops in major producing jurisdictions and prevailing groundwater sustainability enforcement intensity in California's San Joaquin Valley. Variables tested across the analysis window encompass CRISPR trait registration timelines, methyl bromide alternative availability under EU F-Gas Regulation phase-down schedules, and organic transition cost trajectories. Segmentation modeling incorporated seed type, end-use application, physical form, and distribution channel dimensions alongside a geographic regulatory cluster dimension capturing divergence in gene-editing oversight. CAGRs derived from fitted growth curves applied to validated base-year estimates, with sensitivity analysis around dairy herd expansion rates and fodder self-sufficiency subsidy durability.
Practitioners should monitor CTNBio reclassification proceedings, EU F-Gas Regulation amendment timelines, and Punjab groundwater extraction restrictions for early signals warranting forecast revision. Cross-checking against FAO forage crop statistics and national dairy board production surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Lupin Market
Seeds
Hemp Seeds Market
Seeds
North America Grain Seed Market
Seeds
South Africa Seed Market
Seeds
China Rice Seed Market
Seeds
Southeast Asia Seed Market
Seeds
Safflower Seeds Market
Seeds
Global Forage Sorghum Seed Market
Seeds
Crambe Abyssinica Seed Oil Market
Seeds
Morocco Seed Market
Seeds
Asia-Pacific Cannabis Seeds Market
Seeds
Myanmar Seed Market
Seeds
Asia-Pacific Quinoa Seeds Market
Seeds
China Forage Seed Market
Seeds
Global Fruit and Vegetable Seeds Market
Seeds
Europe Vegetable Seed Market