
 Commercial Seed Market | 2026-2036
Commercial Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Seed Market Intelligence
OECD Seed Scheme certification is collapsing the field of qualified suppliers as governments tighten varietal registration protocols. Bayer Crop Science AG leverages its trait pipeline to sustain leadership in genetically modified germplasm. Corteva Agriscience anchors North American corn and soybean markets through integrated breeding platforms. Limograin competes from its French base with specialized vegetable and cereal genetics.
Commercial seed comprises reproductive plant material bred, conditioned, and sold for agricultural production, typically meeting minimum germination rates of 80-95% and varietal purity standards set by national certification bodies. Its primary commercial purpose is to deliver predictable yield, disease resistance, and agronomic uniformity to farming operations at scale. Cereal seeds occupy the largest volume position globally, reflecting wheat and corn's foundational role in food systems. Genetically modified trait categories command premium positioning in markets with regulatory acceptance, while organic seed lines are gaining share where certification schemes restrict synthetic input use. Hybrid technology dominates margin capture in vegetables and row crops through controlled pollination systems that prevent farmer seed saving.
The US Department of Agriculture's Federal Seed Act, the EU's Plant Reproductive Material Regulation, and India's BIS certification framework collectively shape market access by mandating germination testing, varietal identity verification, and phytosanitary clearance. These requirements raise capital barriers for new entrants while rewarding incumbents with established testing infrastructure and regulatory relationships. Stakeholders must monitor how gene-editing regulatory classifications evolve, as jurisdictions diverge on whether CRISPR-derived varieties face modified-organism approval pathways or conventional breeding treatment.
Market Dynamics
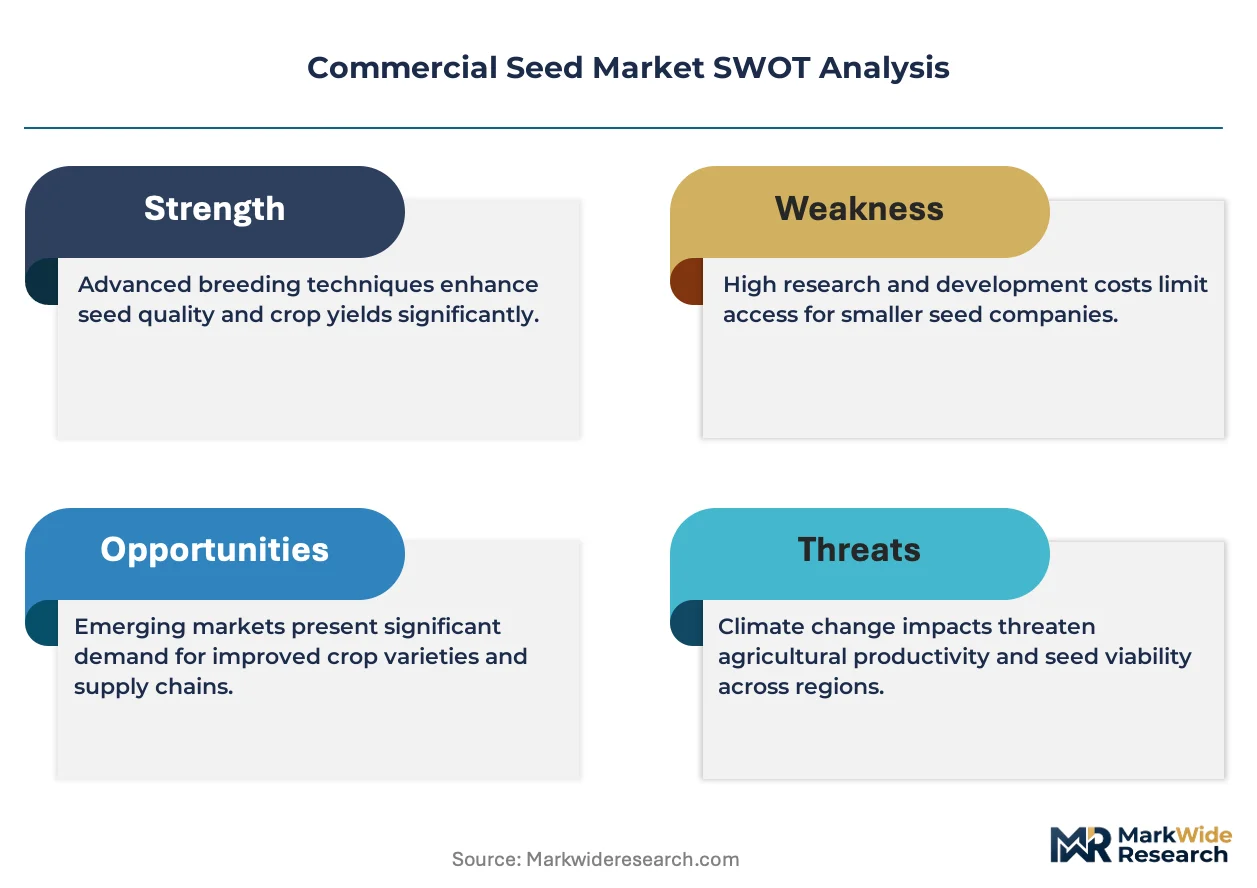
Gene-editing regulatory divergence is fragmenting variety approval pathways, forcing seed developers to maintain parallel dossier strategies across jurisdictions while CRISPR-derived traits await classification clarity.
Growth Catalysts
- EU Plant Reproductive Material Regulation:Mandatory germination testing and varietal identity verification is consolidating demand toward certified suppliers with established laboratory infrastructure.
- Oilseed crop expansion:Commercial farming operations in Brazil's Cerrado frontier are scaling canola and soybean seed procurement to serve crushing capacity additions.
- Hybrid technology:Controlled pollination systems in vegetable and row crops prevent farmer seed saving, capturing recurring revenue through proprietary inbred lines.
Market Restraints
- Phytosanitary compliance costs:India's BIS certification framework requires multi-season field testing that extends variety registration timelines to 4-7 years.
- Input cost volatility:Parent line maintenance and controlled environment pollination facilities concentrate capital requirements among established breeding operations.
- Trait licensing complexity:Stacked transgenic and gene-edited trait packages create royalty stacking that inflates per-unit seed costs for growers.
Strategic Opportunities
- Organic certification schemes:EU organic regulation restrictions on synthetic input use are creating dedicated seed lines for contract growers serving premium food channels.
- Digital phenotyping convergence:Remote sensing and machine learning are compressing variety selection cycles, enabling faster climate-adaptive trait deployment.
- Direct-to-farm distribution:E-commerce platforms and farmgate delivery networks are bypassing traditional cooperative and dealer channels in India's fragmented procurement landscape.
Industry Challenges
- Gene-editing skill scarcity:CRISPR protocol expertise and regulatory dossier preparation capabilities concentrate among a narrow pool of molecular breeding specialists.
- Multi-jurisdictional approval timelines:Divergent national positions on edited-variety classification force redundant safety studies and field trials.
- Climate adaptation capex:Accelerated breeding cycles require expanded greenhouse and speed-breeding facility investment to maintain variety relevance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Seed Market |
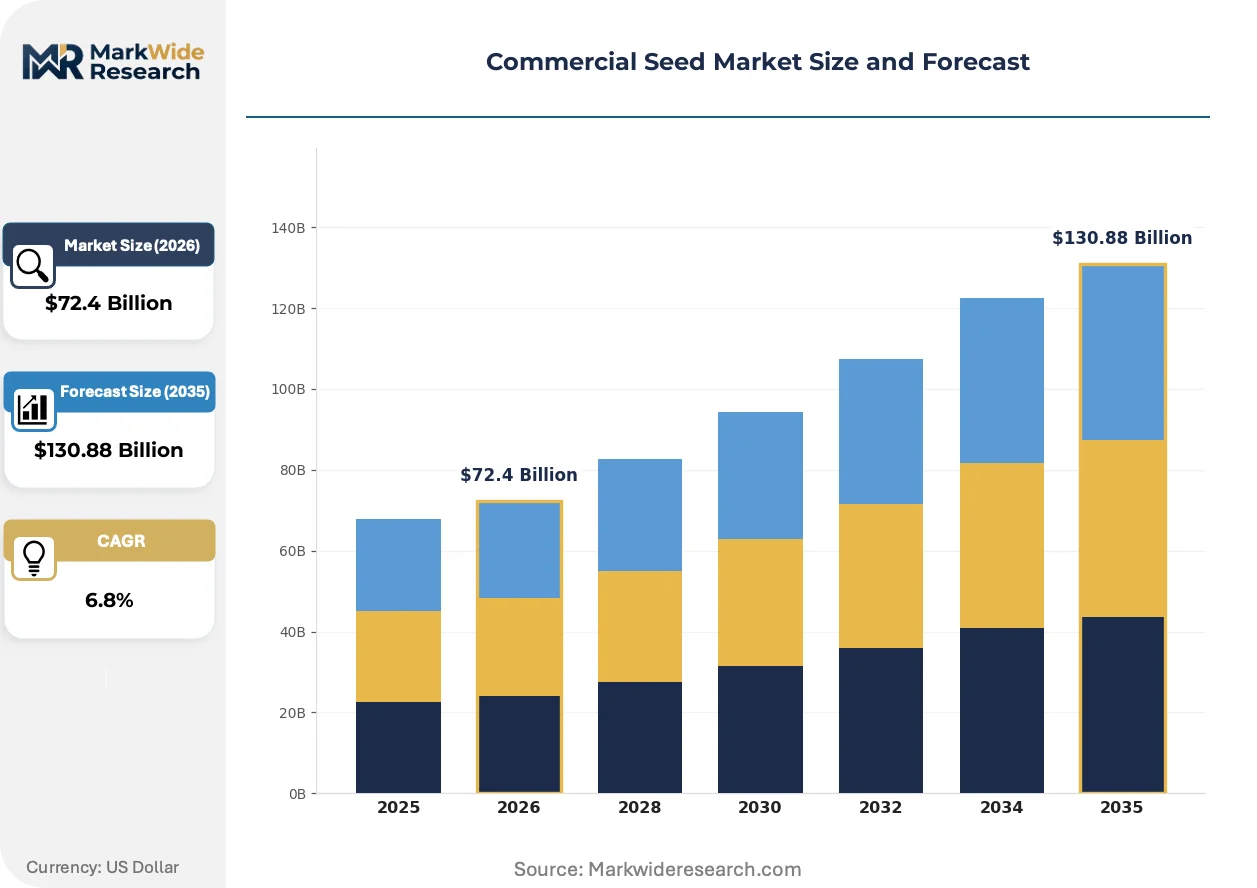
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $130.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereal Seeds, Vegetable Seeds, Oilseed Crops, Forage Seeds, Flower Seeds Trait/Treatment: Hybrid, Genetically Modified, Organic, Disease Resistant, Drought Tolerant End Use/Application: Commercial Farming, Horticulture, Landscaping, Turf Management, Greenhouse Cultivation Packaging Type: Bulk Bags, Pouches, Vacuum-Sealed Packs, Paper Bags, Plastic Containers |
| Companies Covered | Limagrain, BASF SE, Bayer Crop Science AG, Land O'Lakes, Sakata Seed Corporation, Corteva Agriscience, KWS SAAT SE & Co. KGaA, Vilmorin & Cie, Syngenta AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Seed Market Strategic Shifts & Innovations
Biotechnology integration is compressing traditional breeding timelines while digital agriculture tools reshape how genetic material is evaluated, selected, and distributed to farming operations.
CRISPR-Cas9 gene editing is displacing transgenic insertion for trait development, enabling precise nucleotide changes without foreign DNA sequences. Large-scale row crop developers are adopting edited varieties for disease resistance and herbicide tolerance at accelerating rates. This precision is displacing lengthy regulatory review periods in jurisdictions classifying edited products as conventional breeding outcomes.
The EU's divergent regulatory stance on gene-edited crops—treating them as genetically modified organisms—creates market access barriers distinct from USDA and Argentine frameworks. Seed developers must maintain separate product portfolios and labeling systems for European versus American distribution channels. Vegetable and specialty crop segments bear the highest compliance burden, diverting R&D budgets toward regulatory navigation rather than trait advancement.
Farmer procurement patterns are gravitating toward outcome-based variety selection supported by yield guarantee programs and digital agronomy services. Dealer networks and agricultural cooperatives are ceding influence to integrated seed-chemistry-data platforms that bundle genetics with prescription planting recommendations. This behavioral shift is most pronounced in North American corn and soybean markets, where variable-rate technology adoption correlates directly with branded seed loyalty.
Commercial Seed Market Segmentation
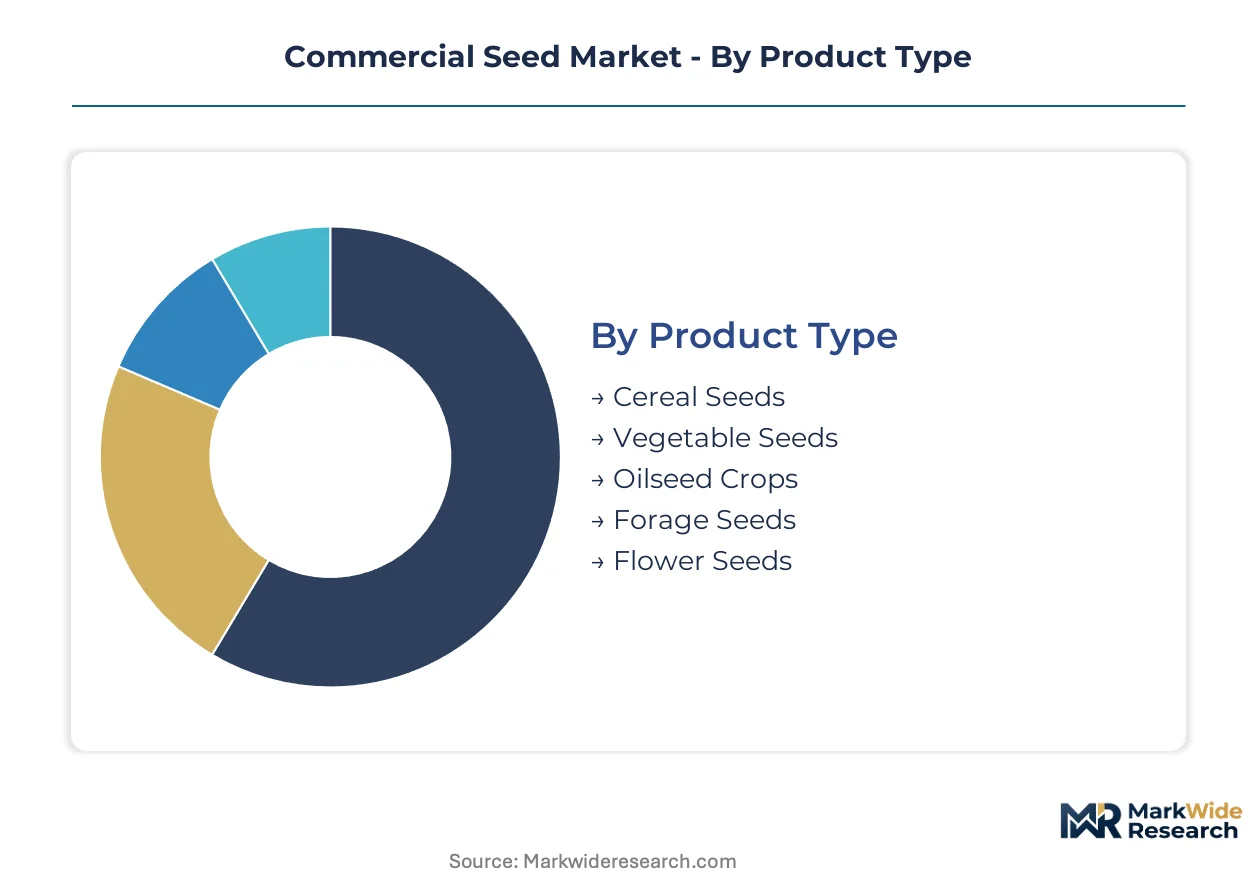
Seed market segmentation reflects divergent regulatory treatment across germplasm categories, with certification requirements and trait approval pathways determining commercial access and pricing power. Understanding these divisions reveals where capital concentrates and which technology platforms face expansion constraints.
Product Type:
Regulatory frameworks distinguish commodity grain seeds from specialty horticultural germplasm through distinct certification protocols and field testing requirements.
- Cereal Seeds:Wheat, corn, rice, and barley germplasm bred for standardized germination rates above 80% under OECD Seed Scheme protocols. Demand concentrates in Brazil's Cerrado frontier where commercial farming operations scale procurement to match crushing capacity expansion.
- Vegetable Seeds:Hybrid tomato, pepper, and cucurbit varieties requiring controlled pollination systems that prevent farmer seed saving. India's BIS certification mandates multi-season field testing extending registration timelines, concentrating supply among established breeding operations with laboratory infrastructure.
- Oilseed Crops:Canola, soybean, and sunflower germplasm serving biofuel and crushing industries.
- Forage Seeds:Alfalfa and pasture grass varieties supporting livestock operations.
- Flower Seeds:Ornamental germplasm for commercial landscaping and greenhouse markets.
Cereal seeds handle the majority of throughput; vegetable seeds are expanding most quickly on margin capture through hybrid technology.
Trait/Treatment:
Technology differentiation creates tiered pricing structures based on regulatory classification and intellectual property protection intensity.
- Hybrid:Controlled pollination systems combining inbred parental lines to produce uniform F1 progeny with heterosis advantages. Vegetable and row crop developers in North American corn markets capture recurring revenue through proprietary inbred lines that prevent seed saving.
- Genetically Modified:Transgenic germplasm with stacked insect resistance and herbicide tolerance traits. EU Plant Reproductive Material Regulation treats these as distinct from conventional varieties, forcing separate product portfolios for European versus American distribution channels.
- Organic:Germplasm bred without synthetic inputs and certified under EU organic regulation restrictions.
- Disease Resistant:Varieties selected for pathogen tolerance through conventional or gene-edited breeding.
- Drought Tolerant:Germplasm with water stress adaptation for arid zone agriculture.
Hybrid traits command the widest adoption base; organic certification is climbing the fastest as premium food channels restrict synthetic input use.
End Use/Application:
Customer procurement patterns vary by operational scale and output destination, from commodity grain handlers to specialized horticulture exporters.
- Commercial Farming:Large-scale grain and oilseed operations purchasing certified germplasm through dealer networks. Brazil's Cerrado agricultural frontier drives concentrated demand as farming operations scale to serve crushing capacity additions.
- Horticulture:Vegetable and fruit producers requiring high-value hybrid varieties with disease resistance packages. EU organic regulation compliance creates dedicated seed lines for contract growers serving premium retail channels.
- Landscaping:Turf and ornamental seed procurement for commercial property maintenance.
- Turf Management:Specialized grass varieties for sports fields and golf courses.
- Greenhouse Cultivation:Climate-controlled production systems demanding uniform germination and predictable maturity windows.
Commercial farming moves the highest volume; horticulture delivers the steepest expansion trajectory through premium pricing.
Packaging Type:
Logistics infrastructure and seed longevity requirements determine format selection across distribution channels.
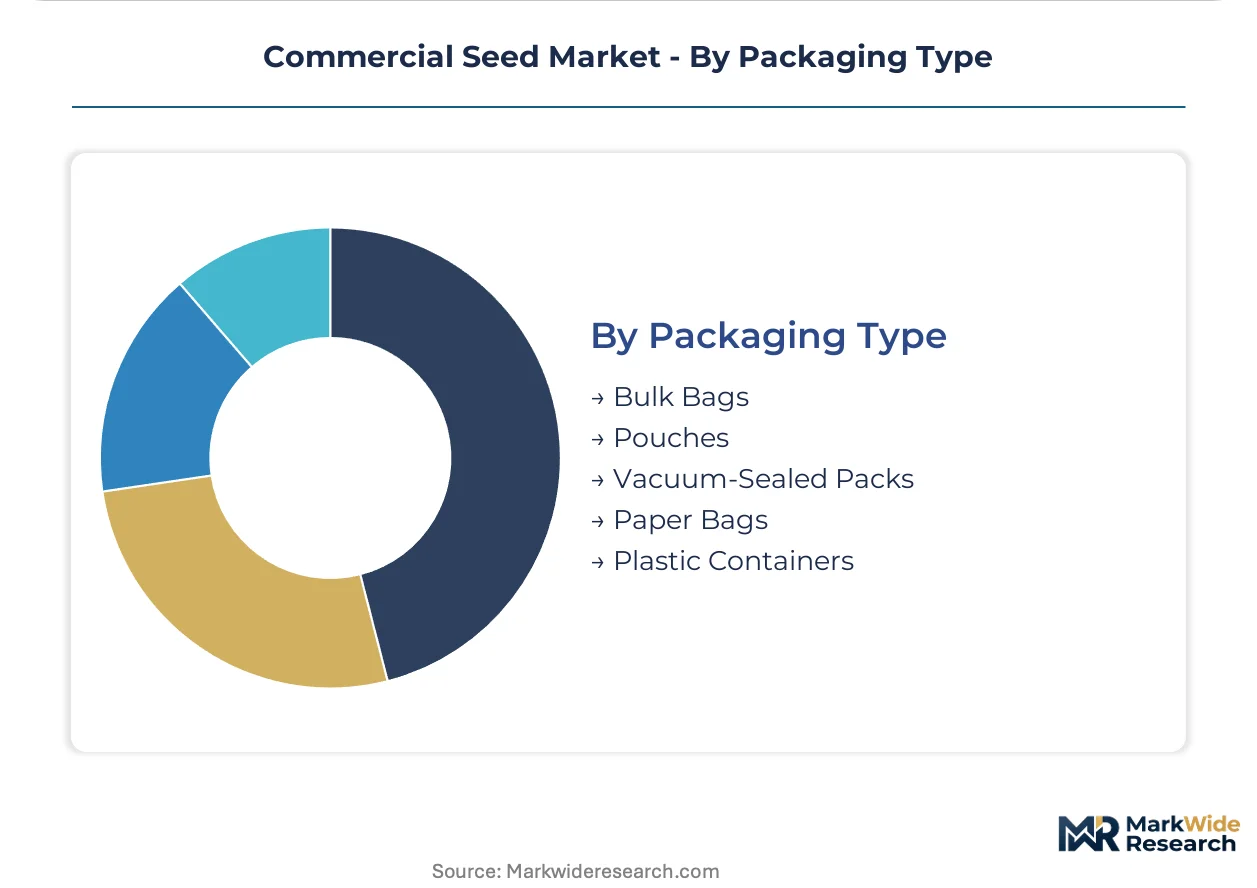
- Bulk Bags:Large-format containers for commodity cereal and oilseed germplasm moving through cooperative procurement systems.
- Pouches:Small-unit retail packaging for vegetable and flower seeds.
- Vacuum-Sealed Packs:Oxygen-barrier formats extending viability for high-value hybrid varieties.
- Paper Bags:Breathable containers for short-lifecycle germplasm in temperate storage.
- Plastic Containers:Reusable formats for pelleted or treated specialty seeds.
Bulk bags handle the majority of tonnage; vacuum-sealed packs are gaining share fastest in high-value hybrid distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River grain corridor underwrites United States seed distribution, moving germplasm from Midwest breeding stations to Gulf export terminals and interior crushing facilities.
United States
Corn and soybean seed procurement concentrates in Iowa and Illinois farming operations scaling to match ethanol and crushing capacity expansions. The USDA Federal Seed Act mandates germination testing and varietal identity verification, consolidating demand toward certified suppliers with established laboratory networks. St. Louis anchors breeding infrastructure where integrated seed-chemistry platforms bundle genetics with prescription planting recommendations.
Brazil
Soybean and canola seed demand accelerates across Mato Grosso and Goiás as commercial farming operations expand into the Cerrado frontier. ANVISA phytosanitary requirements align with OECD Seed Scheme protocols, extending variety registration timelines while rewarding incumbents with field testing infrastructure. Ribeirão Preto clusters breeding stations serving the northern agricultural expansion zones.
India
Cotton and vegetable seed procurement intensifies in Gujarat and Maharashtra as contract growers scale to serve domestic textile and food processing industries. BIS certification mandates multi-season field testing that extends registration timelines to 4-7 years, raising capital barriers for new entrants. Hyderabad concentrates molecular breeding facilities where CRISPR protocol expertise concentrates among narrow specialist pools.
Germany
Sugar beet and cereal germplasm demand stabilizes across Lower Saxony and Bavaria farming cooperatives. EU Plant Reproductive Material Regulation treats gene-edited varieties as genetically modified organisms, forcing separate product portfolios and labeling systems distinct from USDA frameworks. Einbeck anchors KWS SAAT breeding infrastructure serving European and export markets with distinct regulatory dossiers.
China
Rice and hybrid vegetable seed procurement scales across Jiangsu and Shandong provinces as greenhouse cultivation expands. GB standards and MIIT varietal registration protocols mandate germination testing and phytosanitary clearance, shaping market access requirements. Beijing-Tianjin-Hebei clusters state-backed breeding institutes developing climate-adaptive germplasm for domestic food security priorities.
Commercial Seed Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and regulatory navigation capabilities. The vendor base concentrates among integrated breeding platforms with captive laboratory infrastructure and established OECD Seed Scheme relationships. Three archetypes dominate: multinational conglomerates with trait pipelines, regional specialists with varietal portfolios, and cooperative-owned breeders with farmer-captive distribution. Competitive moves center on gene-editing capability acquisition and direct-to-farm distribution network expansion.
Within the multinational tier, Bayer Crop Science AG and Corteva Agriscience exemplify integrated breeding platforms combining germplasm development with regulatory dossier expertise. Limograin occupies a position among European specialists with French-base operations. Sakata Seed Corporation anchors Asian-origin vegetable genetics capabilities. These three represent divergent geographic and crop-specialization strategies without implying specific market share positions.
| Leading Market Players |
|---|
| Limagrain |
| BASF SE |
| Bayer Crop Science AG |
| Land O'Lakes |
| Sakata Seed Corporation |
| Corteva Agriscience |
| KWS SAAT SE & Co. KGaA |
| Vilmorin & Cie |
| Syngenta AG |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Brazilian Cerrado farming cooperatives and multinational breeding platforms lock in both parent line access and multi-season price visibility, insulating procurement budgets from input cost volatility while concentrating supply relationships among OECD-certified suppliers.
Pricing Analysis
Volume-discount tiering structures stratify across certification grade, volume commitment, and trait complexity. Three-tier pricing separates gene-edited premium varieties from standard hybrid germplasm and economy open-pollinated lines. Cost compression in economy cereal seeds is intensifying because royalty stacking from stacked transgenic traits inflates per-unit costs for growers. Smallholder vegetable producers in India exhibit highest price sensitivity, while North American corn operations demonstrate lowest sensitivity due to yield guarantee bundling.
Supply Chain Analysis
Parent line multiplication facilities in the US Corn Belt, French Beauce region, and Brazilian Ribeirão Preto cluster constitute critical chokepoints controlling global hybrid seed output. Germplasm development draws from proprietary inbred repositories, CRISPR protocol expertise, and controlled-environment pollination infrastructure. Single-source vulnerability concentrates in trait licensing pools held by integrated breeding platforms. Distribution runs through agricultural cooperative networks and direct-to-farm e-commerce platforms bypassing traditional dealer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molecular breeding capability and regulatory dossier expertise now constitute scarcer assets than germplasm repositories, with CRISPR protocol specialists commanding premium compensation across Hyderabad, St. Louis, and Beijing-Tianjin-Hebei clusters.
For Market Incumbents: Secure captive CRISPR protocol expertise through targeted hiring in Hyderabad and Beijing-Tianjin-Hebei clusters before talent scarcity intensifies. Expand speed-breeding greenhouse capacity in Brazil's Cerrado frontier to compress variety selection cycles. Defend against gene-editing regulatory divergence by maintaining parallel dossier strategies for EU Plant Reproductive Material Regulation and USDA frameworks. For New Entrants and Emerging Players: Lead with direct-to-farm distribution platforms targeting India's fragmented procurement landscape where BIS certification timelines have excluded agile competitors. White-space opportunity concentrates in organic-certified vegetable germplasm serving EU premium retail channels. Contract growers in Gujarat and Maharashtra represent the most penetrable customer segment for specialty hybrid varieties. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid vegetable specialists with proprietary inbred lines preventing farmer seed saving. Long-term viability over the coming decade rests on gene-editing regulatory clarity and climate-adaptive trait pipelines. Acquisition targets should demonstrate established OECD Seed Scheme relationships and laboratory infrastructure. The signal to watch is EU reclassification of CRISPR-derived varieties away from genetically modified organism treatment.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR Capability Acquisition | Gene-editing expertise concentrates among narrow specialist pools in Hyderabad and Beijing-Tianjin-Hebei. |
| Speed-Breeding Facility Expansion | Accelerated greenhouse cycles compress variety development timelines for Brazil's Cerrado frontier. |
| Direct-to-Farm Platform Launch | E-commerce networks bypass traditional cooperative channels in India's fragmented procurement landscape. |
| OECD Certification Investment | Laboratory infrastructure investments satisfy tightening BIS and EU Plant Reproductive Material requirements. |
| Organic Seed Line Development | EU organic regulation restrictions create dedicated germplasm demand from contract growers. |
Research Approach
Desk research of OECD Seed Scheme certification databases, USDA Federal Seed Act filings, and EU Plant Reproductive Material Regulation precedents preceded structured interviews with molecular breeding directors, regulatory affairs leads at multinational platforms, BIS certification officers, and agricultural cooperative procurement managers. Secondary validation drew from ANVISA phytosanitary records, customs germplasm trade data, and SEC 10-K disclosures from listed breeding platforms. Bottom-up variety registration timelines and top-down market sizing were triangulated across primary and secondary sources.
Variance-decomposition across product type, trait category, end-use application, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro agricultural input demand indicators. Modeled inputs included crushing capacity expansion in Brazil's Cerrado, ethanol facility additions in Iowa and Illinois, and greenhouse cultivation scaling in Jiangsu and Shandong provinces.
Forecasts assume regulatory continuity in EU Plant Reproductive Material Regulation, USDA Federal Seed Act, and India's BIS certification framework; material policy shifts on gene-edited variety classification would require re-modeling. Practitioners should keep alternative scenarios live as OECD Seed Scheme protocol revisions and climate adaptation breeding priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
China Seed Market
Seeds
Global Sports Turf Seed Market
Seeds
Global Alfalfa Seed Market
Seeds
Americas Seeds Market
Seeds
Indonesia Seeds Market
Seeds
Tallow Tree Seed Market
Seeds
Flax Seed Market
Seeds
Wax Gourd Seed Market
Seeds
Flower Seed Market
Seeds
Global Sunflower Seed (Seed for Sowing) Market
Seeds
Ghana Seeds Market
Seeds
Hemp Seed Oil Market
Seeds
Carrot Seed Oil Market
Seeds
Helianthus Annuus (Sunflower) Market
Seeds
Lupin Market
Seeds
Cotton Seed Treatment Market