
 North America Rainscreen Cladding Market | 2026-2036
North America Rainscreen Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rainscreen Cladding Market Intelligence
Project finance tied to green building certification is reshaping competitive access in the North America Rainscreen Cladding Market, enabling mid-tier contractors to bid larger envelope packages without full capital deployment. Kingspan Group leverages its insulated panel integration to anchor specification chains across cold-climate commercial projects. James Hardie Building Products sustains fiber cement dominance through proprietary formulation chemistry and coast-to-coast distribution density. Trespa International B.V. differentiates via high-pressure laminate technology leadership in institutional facades.
Rainscreen cladding comprises a multi-layer exterior wall assembly where an outer skin deflects bulk water while a ventilated cavity and drainage plane manage moisture migration, typically incorporating sub-framing, insulation, and an air barrier to achieve specified U-values and fire resistance ratings. Metal and fiber cement product categories lead current specification volumes, with metal panels capturing premium commercial towers and fiber cement occupying mid-rise residential and mixed-use typologies where cost-performance balance governs selection. Vinyl segments compete on renovation economics, though thickness customization for wind-load zones increasingly determines project-level viability.
ASHRAE 90.1 energy standards, the International Energy Conservation Code, and NFPA 285 fire propagation testing collectively dictate material selection, cavity depth, and insulation R-value minimums across US and Canadian jurisdictions. Canadian provinces enforce National Building Code thermal bridging limits that intensify demand for thermally broken sub-framing systems, while US Department of Energy directives push envelope performance thresholds higher in climate zones 5 through 8. Stakeholders must monitor code harmonization pressures between US and Canadian jurisdictions, as diverging fire-test protocols and carbon-accounting rules for embodied materials threaten to fragment supply chain standardization.
Market Dynamics
ASHRAE 90.1 and IECC code cycles are tightening thermal performance mandates across US and Canadian jurisdictions, forcing envelope specification toward deeper cavity rainscreen assemblies with thermally broken sub-framing and continuous insulation. This regulatory compression is accelerating material substitution and contractor capability consolidation.
Growth Catalysts
- NFPA 285 fire testing mandates:Type I commercial construction across Chicago, Los Angeles, and Seattle now requires compliant assemblies, driving specification of fiber cement and metal panel systems with verified cavity fire blocking.
- Canadian National Building Code thermal bridging limits:Provincial enforcement in British Columbia and Ontario intensifies demand for thermally broken aluminum sub-framing and mineral wool continuous insulation in high-rise envelopes.
- Deep energy retrofit programs:US Department of Weatherization Assistance Program funding and Canadian Greener Homes Initiative are channeling volume toward rainscreen-over-cladding renovation assemblies in climate zones 5 through 8.
Market Restraints
- Aluminum and steel input volatility:Metal panel and sub-framing costs fluctuate with LME pricing and Section 232 tariff exposure, compressing bid accuracy for fixed-price envelope contracts.
- Specialized installer concentration:Certified rainscreen contractors cluster in coastal metropolitan corridors, creating bottleneck risk for interior and secondary market projects in the US Midwest and Canadian Prairies.
- Curtain wall substitution:Unitized glazing systems with integrated rainscreen backup capture premium tower envelopes where speed-to-enclosure outweighs cost differentials.
Strategic Opportunities
- US Sun Belt multifamily acceleration:Phoenix, Austin, and Miami construction pipelines lack mature rainscreen installer networks, creating first-mover advantage for system manufacturers with training infrastructure.
- Mass timber building code expansion:ICC adoption of tall wood construction standards in 2021 and 2024 opens rainscreen specification for Type IV-A, B, and C structures previously dominated by concrete and steel envelopes.
- Utility demand response integration:Smart cladding with embedded phase-change materials and sensor-driven cavity ventilation aligns with FERC Order 2222 aggregation frameworks for grid-interactive efficient buildings.
Industry Challenges
- Building envelope commissioning talent scarcity:Qualified envelope consultants capable of whole-assembly thermal modeling and field verification remain concentrated in fewer than 15 US and Canadian metropolitan areas.
- Multi-jurisdictional code fragmentation:Divergent US state amendments to IECC and Canadian provincial NBC interpretations force manufacturers to maintain parallel testing and documentation for cross-border projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rainscreen Cladding Market |
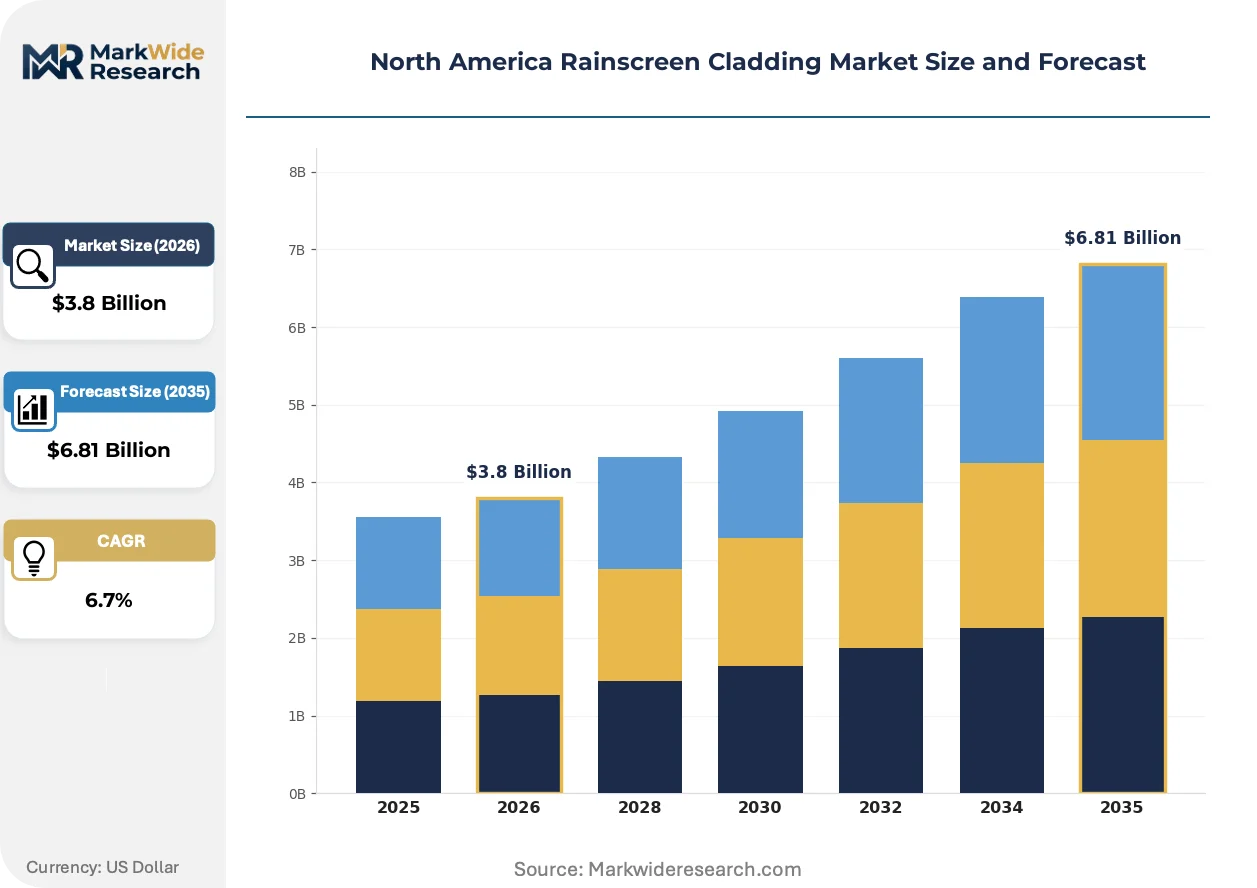
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal, Wood, Fiber Cement, Vinyl Installation Method: Anchored, Freestanding, Support Systems, Direct Aiming End User: Commercial, Residential, Institutional, Industrial Thickness: Standard, Lightweight, Heavy-duty, Custom |
| Companies Covered | James Hardie Building Products, Trespa International B.V., Kingspan Group, OmniMax International, Inc., Cladding Corp, ROCKWOOL International A/S, DuPont de Nemours, Inc., TERREAL Group, SFS Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rainscreen Cladding Market Strategic Shifts & Innovations
Material science advances and digital specification tools are compressing design-to-installation cycles while expanding performance boundaries for rainscreen assemblies. Three developments are restructuring competitive access and buyer expectations.
Photovoltaic-integrated cladding is hybridizing rainscreen function with on-site generation. BIPV laminate manufacturers are partnering with metal panel producers to deliver structurally integrated solar facades. High-rise commercial developers in California and New York are specifying these assemblies to meet Title 24 and Local Law 97 carbon limits while preserving architectural flexibility.
The US Department of Energy's Better Buildings Initiative and equivalent Natural Resources Canada programs are accelerating performance-based procurement for envelope systems. Federal and provincial facility managers now require modeled energy savings guarantees rather than component-level specifications. This shift disadvantages catalog-driven distributors and rewards manufacturers with in-house energy modeling and post-occupancy validation capabilities.
Design-assist contracting is displacing traditional design-bid-build sequences for complex envelope packages. Architects in Vancouver, Toronto, and Boston are engaging rainscreen specialists during schematic design to resolve thermal bridging and fire assembly conflicts before documentation finalization. This early involvement compresses contractor risk premiums and locks specification chains before competitive bidding opens.
North America Rainscreen Cladding Market Segmentation
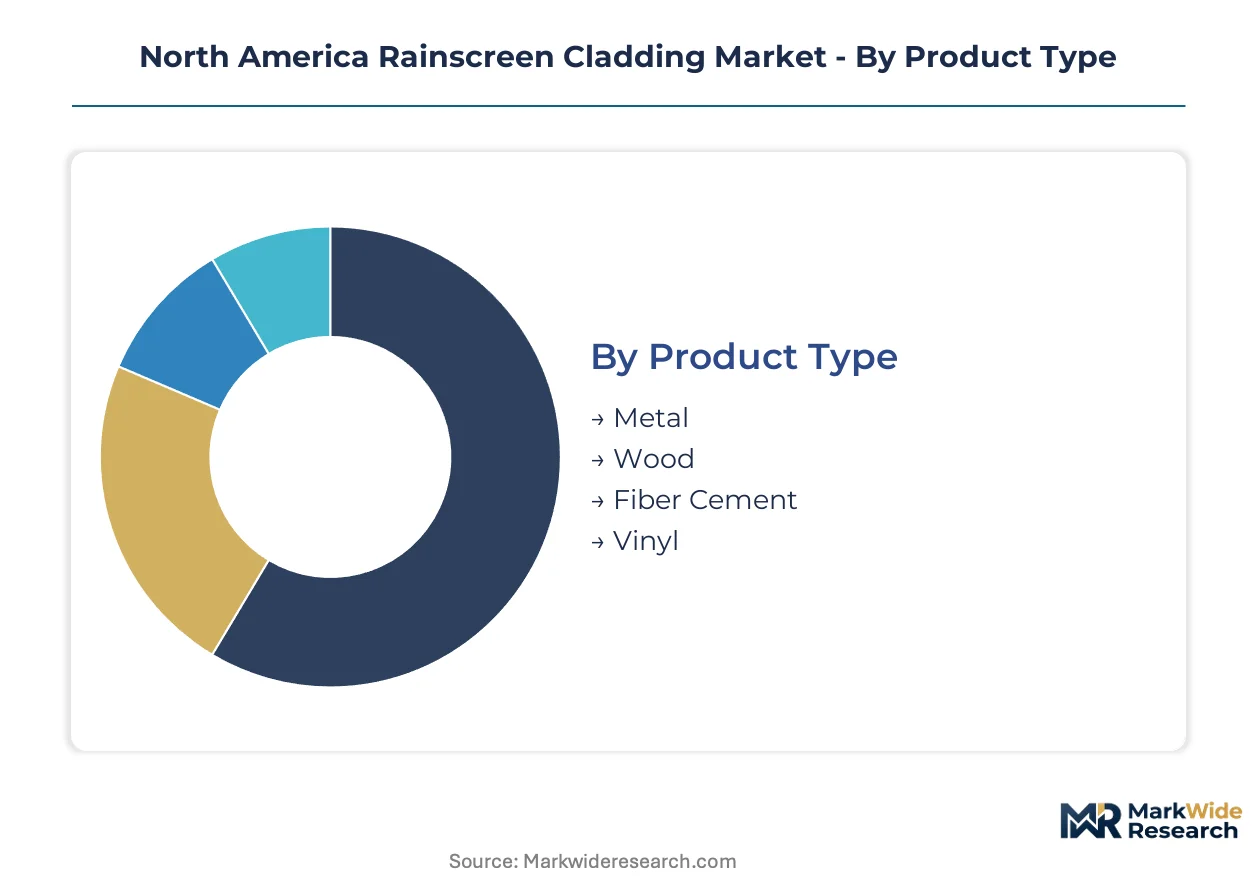
Rainscreen cladding specification diverges sharply across building typologies and performance requirements, forcing manufacturers to maintain parallel product architectures. Segmentation discipline separates volume-driven residential programs from premium commercial towers where code compliance and thermal modeling dominate procurement.
Product Type:
Mature metal and fiber cement systems anchor current specification volumes while wood and vinyl occupy specialized niches with distinct growth profiles.
- Metal:Aluminum and steel composite panels deliver NFPA 285-compliant assemblies with integrated thermal breaks for Type I high-rise construction. Toronto and Vancouver commercial towers specify these systems under Canadian NBC thermal bridging limits, with Chicago and Seattle following under equivalent ASHRAE 90.1 cycles.
- Fiber Cement:Calcium-silicate formulations achieve fire resistance ratings without cavity fire blocking complexity, reducing installed cost for mid-rise residential and mixed-use typologies. James Hardie's proprietary chemistry sustains specification dominance across Phoenix, Austin, and Miami multifamily pipelines.
- Wood:Mass timber building code expansion in ICC 2021 and 2024 editions opens specification for Type IV-A, B, and C structures previously closed to combustible cladding.
- Vinyl:Renovation economics drive selection in climate zones 5 through 8 weatherization programs, though thickness customization for wind-load zones increasingly governs project viability.
Metal handles the majority of throughput; fiber cement is expanding most quickly on share.
Installation Method:
Cost tier stratification separates engineered support systems from field-adaptable anchoring approaches across project scales.
- Anchored:Direct mechanical fastening to structural substrates dominates residential and light commercial renovation where substrate condition variability requires field-adjustable attachment.
- Freestanding:Self-supporting aluminum or steel sub-framing enables deep cavity assemblies with continuous insulation and drainage plane integration, commanding premium specification in Boston and Toronto design-assist contracts.
- Support Systems:Thermally broken aluminum rails and clips manage structural loads while minimizing thermal bridging, mandatory under British Columbia and Ontario provincial enforcement of NBC thermal performance limits.
- Direct Aiming:Simplified bracket systems reduce material cost for standardized panel formats in volume residential production, competing primarily on installer labor efficiency.
Support systems capture the steepest expansion trajectory as code-driven cavity depth requirements intensify.
End User:
Application context dictates fire rating, thermal performance, and aesthetic specification intensity across building ownership models.
- Commercial:High-rise office and retail envelopes face Local Law 97 and Title 24 carbon limits in New York and California, driving BIPV-integrated metal panel specification.
- Residential:Multifamily construction in US Sun Belt markets lacks mature installer networks, creating first-mover infrastructure opportunity for system manufacturers with training programs.
- Institutional:Federal and provincial facility managers under US DOE Better Buildings and Natural Resources Canada programs now require modeled energy savings guarantees rather than component specifications.
- Industrial:Warehouse and logistics envelope projects prioritize speed-to-enclosure, exposing rainscreen systems to curtain wall substitution where unitized glazing offers faster enclosure.
Commercial dominates current value capture; residential multifamily is climbing the fastest on volume.
Thickness:
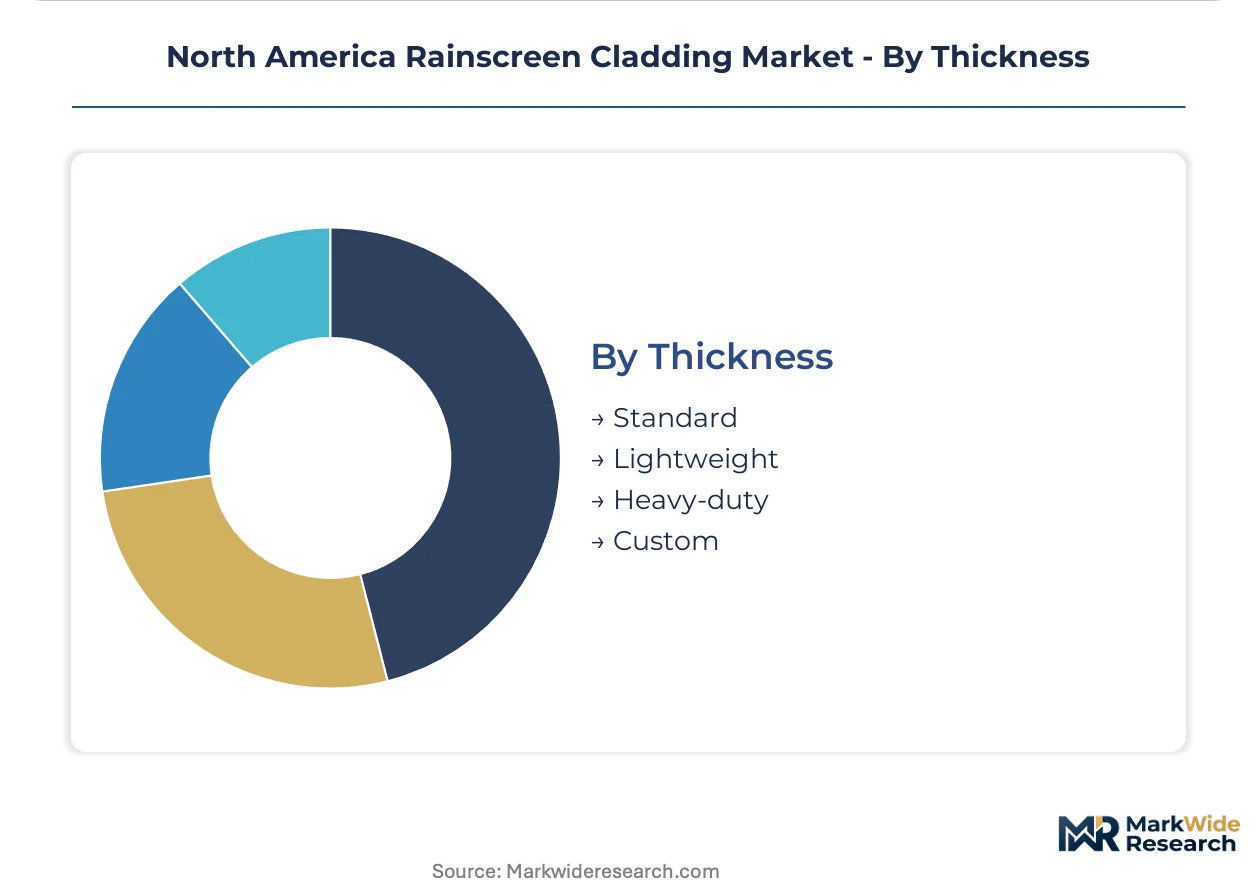
Margin structure separates commodity standard formats from engineered heavy-duty and custom specifications.
- Standard:6-8mm fiber cement and 3-4mm metal gauges serve cost-optimized mid-rise residential where wind-load requirements permit thinner profiles.
- Lightweight:Reduced-mass panels enable faster installation with smaller crane capacity, penetrating renovation markets where structural load limits constrain retrofit options.
- Heavy-duty:Reinforced fiber cement and thicker aluminum extrusions withstand high-velocity hurricane zones and seismic lateral loads, mandatory in Miami-Dade and coastal California jurisdictions.
- Custom:Project-specific thickness engineering resolves unique thermal bridging or acoustic performance requirements, typical in Boston and Vancouver design-assist engagements.
Standard thickness maintains volume leadership; heavy-duty is gaining share fastest as climate zone 4 and above enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States imports specialized rainscreen sub-framing components from Canadian aluminum extruders while exporting fiber cement panel formulations to Mexican construction markets. Cross-border supply chains concentrate fabrication capacity near the Great Lakes and Pacific Coast corridors.
United States
Commercial high-rise construction in New York City and Chicago drives specification of NFPA 285-compliant metal panel assemblies. ASHRAE 90.1 energy standards mandate deeper cavity depths with continuous insulation across climate zones 5 through 8. The Pacific Northwest cluster around Seattle and Portland anchors design-assist contracting for complex envelope packages.
Canada
Toronto and Vancouver commercial towers require thermally broken sub-framing under provincial enforcement of National Building Code thermal bridging limits. British Columbia and Ontario jurisdictions lead North American adoption of mineral wool continuous insulation specifications. Montreal fabricators supply cross-laminated timber-compatible rainscreen systems for emerging mass timber construction.
Mexico
Industrial warehouse construction in Nuevo León and Mexico City generates demand for speed-to-enclosure rainscreen alternatives to curtain wall systems. Mexican building codes adopt ASHRAE-based thermal performance references for border-adjacent commercial projects. Bajío Region automotive manufacturing facilities specify metal panel rainscreens for process-controlled envelope environments.
North America Rainscreen Cladding Market Key Industry Players
On the supply side, the industry is consolidating around integrated building envelope specialists with captive insulation and sub-framing capabilities. Three strategic archetypes dominate: full-system integrators controlling specification chains through energy modeling services, component specialists defending share via proprietary material chemistry, and regional fabricators competing on installation training infrastructure. Competitive moves concentrate on design-assist contracting partnerships with major metropolitan architecture firms and backward integration into thermally broken aluminum extrusion.
Among North American building material conglomerates, Kingspan Group and James Hardie Building Products occupy positions as archetype anchors for integrated system and fiber cement specialization respectively. Trespa International B.V. represents the high-performance laminate tier serving institutional facade specifications. These three companies exemplify the divergence between scale-driven envelope integration and material-specific technology leadership.
| Leading Market Players |
|---|
| James Hardie Building Products |
| Trespa International B.V. |
| Kingspan Group |
| OmniMax International, Inc. |
| Cladding Corp |
| ROCKWOOL International A/S |
| DuPont de Nemours, Inc. |
| TERREAL Group |
| SFS Group |
| Others |
Cost & Logistics Intelligence
Canadian aluminum extruders supplying thermally broken sub-framing components concentrate upstream margin capture, while downstream pricing power pools with design-assist contractors in Toronto, Vancouver, and Boston who control specification chains before competitive bidding opens.
Pricing Analysis
Industrial OEM buyers anchor project-based transactional pricing across envelope packages, with three-tier pricing structure across premium, standard, and economy levels separating NFPA 285-certified metal assemblies from fiber cement mid-rise specifications and vinyl renovation alternatives. Price differentiation centers on thermal performance certification tier and geographic delivery cost to climate zones 5 through 8. Cost compression in standard-grade fiber cement is intensifying because of raw material formulation competition. Multifamily developers in Phoenix, Austin, and Miami exhibit highest price sensitivity, while institutional facility managers under federal performance-based procurement show lowest sensitivity due to modeled energy savings guarantees.
Supply Chain Analysis
Aluminum feedstock draws from Canadian smelters, US Midwest rolling mills, and Mexican extrusion facilities, with calcium-silicate fiber cement formulations resting on US and Canadian gypsum and silica sourcing. Raw material dependencies span LME-traded aluminum, mineral wool insulation, and engineered polymer fasteners. Single-source vulnerability concentrates in thermally broken aluminum rail fabrication for NBC-compliant assemblies. Distribution runs through coast-to-coast building material distributors with regional fabrication partnerships near Great Lakes and Pacific Coast corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward design-assist contractors and institutional facility managers as specification authority concentrates in fewer than 15 metropolitan envelope consulting clusters across the US and Canada.
For Market Incumbents: Entrench specification chain control through captive energy modeling services and post-occupancy validation capabilities that lock procurement before competitive bidding. Backward integration into thermally broken aluminum extrusion defends against Canadian fabricator expansion into US markets. Counter curtain wall substitution threat in premium commercial towers by demonstrating speed-to-enclosure parity through prefabricated rainscreen panelization. For New Entrants and Emerging Players: Pursue installer training infrastructure deployment in Phoenix, Austin, and Miami Sun Belt markets where multifamily construction pipelines outpace certified contractor availability. Target mass timber-compatible rainscreen specification for Type IV-A, B, and C structures under expanded ICC tall wood standards. Lead with BIPV-integrated metal panel offerings to capture California Title 24 and New York Local Law 97 compliance-driven procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional envelope specialists holding design-assist relationships with Boston, Toronto, and Vancouver architecture firms. Long-term viability hinges on regulatory harmonization between US and Canadian jurisdictions over the next decade. Watch for NFPA 285 test protocol divergence or carbon-accounting rule fragmentation as inflection signals for supply chain standardization investments.| Strategic Initiative | Industry Significance |
|---|---|
| Design-Assist Contracting Partnerships | Early architect engagement locks specification chains before competitive bidding opens in complex envelope packages. |
| Thermally Broken Aluminum Extrusion Integration | Captive sub-framing production defends margin against Canadian fabricator expansion under NBC thermal bridging limits. |
| Sun Belt Installer Training Infrastructure | First-mover certification programs capture Phoenix, Austin, and Miami multifamily volume ahead of mature networks. |
| BIPV Metal Panel Development | Title 24 and Local Law 97 carbon limits drive specification of photovoltaic-integrated cladding for high-rise commercial. |
| Mass Timber Rainscreen Specification | ICC 2021 and 2024 tall wood standards open Type IV-A, B, and C construction previously closed to combustible cladding. |
Research Approach
Desk research of ASHRAE 90.1 code cycle documentation, IECC amendment tracking, and NFPA 285 test protocol records preceded structured interviews with envelope consultants, design-assist contractors, facility managers under federal Better Buildings programs, and aluminum extrusion procurement leads. Secondary validation drew from National Building Code provincial interpretation bulletins, US Department of Energy envelope performance directives, and Natural Resources Canada Greener Homes Initiative program data. Bottom-up project pipeline analysis across Toronto, Vancouver, New York, Chicago, and Seattle triangulated against top-down construction spending forecasts.
Assumptions held ASHRAE and IECC code adoption timelines fixed while varying aluminum and steel input cost trajectories, installer certification expansion rates, and mass timber building code adoption speed across the analysis window. Segmentation modeling incorporated product type, installation method, end user, and thickness tier dimensions alongside climate zone regulatory intensity. CAGRs derived from weighted average of historical envelope specification growth and projected commercial high-rise permitting volumes, with mineral wool insulation penetration and thermally broken sub-framing adoption as key industry-specific inputs.
Sensitivities concentrate around LME aluminum price volatility, Section 232 tariff exposure, and divergent US state amendments to IECC that could fragment manufacturer testing requirements. Forecasts reflect documented assumptions on code harmonization pressures and cross-border supply chain continuity. Cross-checking against local construction permitting databases and architecture firm specification tracking services is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Moisture Resistant Gypsum Board Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Residential Energy Efficient Windows Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Cultured Marble Market
Building & Construction Materials
Indonesia Ceramic Tiles Market
Building & Construction Materials
Construction Aggregates Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market