
 Greenhouse Ventilation System Market | 2026-2036
Greenhouse Ventilation System Market Size, Share, and Industry Trends Forecast 2026-2036
Greenhouse Ventilation System Market Insights
Equipment leasing and project finance is fragmenting competitive dynamics in greenhouse ventilation by lowering capital barriers for mid-sized growers. Munters leverages its manufacturing scale to anchor premium mechanical ventilation lines across North American operations. Vostermans competes through specialized fan engineering for high-humidity agricultural environments. Dalsem differentiates with integrated greenhouse project delivery that bundles ventilation with structural and climate systems.
Greenhouse ventilation systems are engineered assemblies of fans, louvers, vents, and automated controllers designed to regulate temperature, humidity, and CO2 concentration within enclosed growing structures, typically achieving air exchange rates of 10-30 volumes per hour depending on crop requirements. Mechanical ventilation commands the largest installed base among product types due to its reliability in extreme climates, while sensor-based systems represent the fastest-expanding technology segment as precision agriculture protocols tighten environmental tolerances for yield optimization.
EPA energy efficiency standards and EU F-Gas Regulation are reshaping equipment specifications by mandating lower-emission refrigerants and higher motor efficiency tiers in climate-controlled agriculture. OSHA ventilation requirements for agricultural worker safety further constrain system design in US commercial operations. Stakeholders must weigh retrofit compatibility against new construction specifications as regulatory thresholds tighten without grandfathering existing installations.
Market Dynamics
Mechanical ventilation systems are displacing passive designs as EU F-Gas Regulation phase-downs force refrigerant-dependent climate systems toward higher-efficiency motor tiers and alternative cooling architectures in controlled-environment agriculture.
Growth Catalysts
- EU F-Gas Regulation phase-down:Mandated refrigerant emission reductions are accelerating mechanical ventilation retrofits across Dutch and Spanish commercial greenhouse clusters.
- Precision agriculture protocols:Tightening environmental tolerances for yield optimization are pulling sensor-based control systems into tomato and pepper production facilities.
- Almería greenhouse cluster expansion:Concentrated vegetable production in Spain's southeast is generating concentrated demand for humidity-optimized ventilation engineering.
Market Restraints
- Copper and rare-earth magnet cost volatility:Input price swings for high-efficiency motor components compress margin structures for equipment manufacturers.
- Technical limitation in extreme cold climates:Mechanical ventilation efficiency degrades below -15°C, restricting addressable geographies for standard product configurations.
- Substitution threat from passive vent designs:Low-cost natural ventilation with automated louvers competes for mid-tier greenhouse operators in moderate climate zones.
Strategic Opportunities
- Underpenetrated controlled-environment cannabis:North American licensed producers are installing specialized odor-containment ventilation with carbon filtration.
- Technology convergence of ventilation and lighting:Integrated climate-lighting control platforms are opening bundled specification opportunities with LED retrofit projects.
- Equipment-as-a-service channels:Leasing models are lowering capital barriers for mid-sized growers in Spain and the Netherlands.
Industry Challenges
- HVAC-agronomy skill gap:Shortage of technicians who understand both mechanical systems and crop-specific climate requirements slows commissioning timelines.
- Integration complexity with legacy polyhouse structures:Retrofitting automated ventilation into aging Dutch Venlo-type greenhouses requires structural reinforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greenhouse Ventilation System Market |
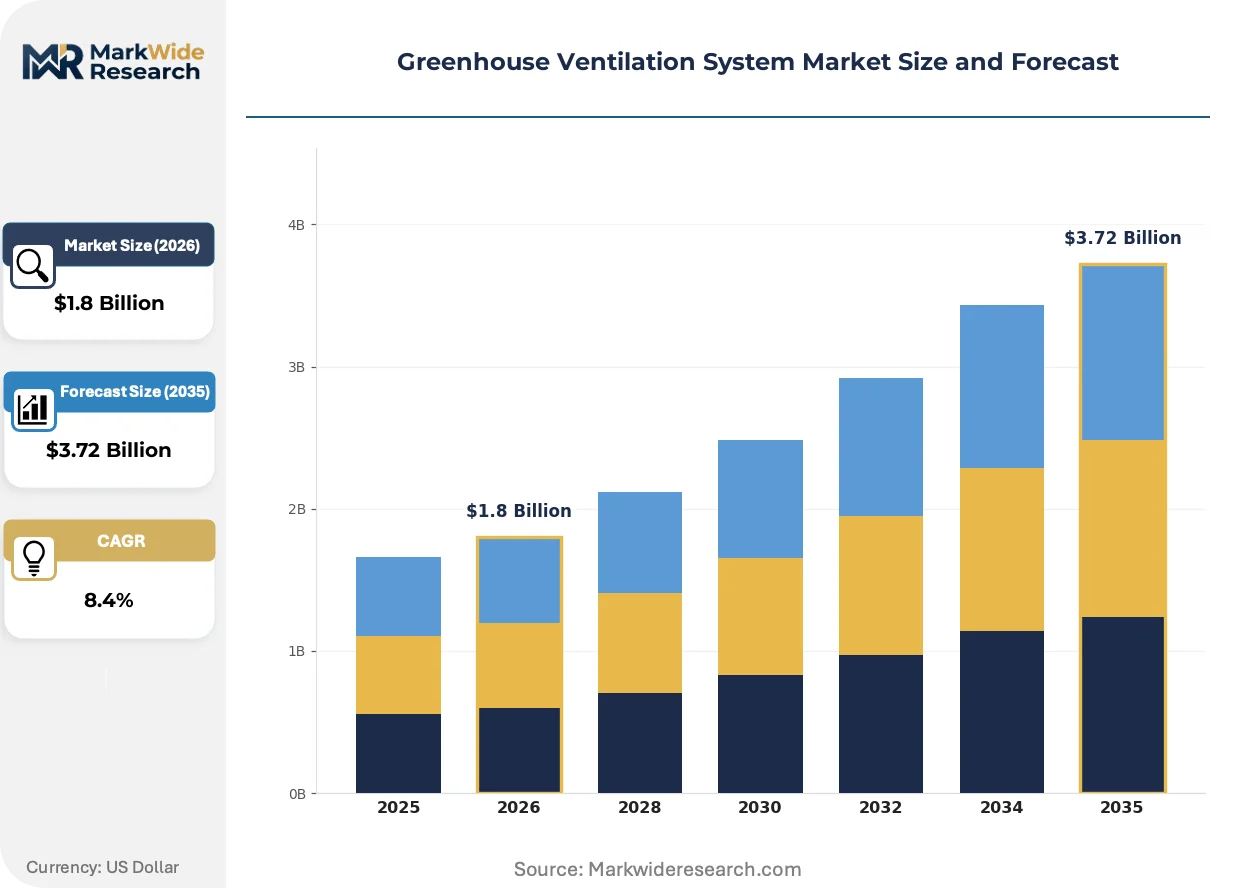
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Ventilation, Mechanical Ventilation, Hybrid Systems, Control Systems End User: Commercial Growers, Research Institutions, Home Gardeners, Agricultural Co-ops Technology: Passive Cooling, Active Cooling, Sensor-based Systems, Automated Controls Installation Type: Retrofit, New Construction, Modular Systems, Custom Solutions |
| Companies Covered | Rough Brothers Inc., Greenhouse Megastore, Richel Group, GGS Structures Inc., Agra Tech, Vostermans, Dalsem, Munters, Harnois, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greenhouse Ventilation System Market Trends and Innovations
Sensor-driven climate control is compressing environmental variance tolerances while regulatory pressure on refrigerants and motor efficiency is forcing equipment architecture redesigns across commercial agriculture.
Variable-speed EC motor technology is hybridizing with traditional AC fan architectures in greenhouse ventilation. Large-scale tomato producers in the Netherlands are specifying these systems for humidity modulation during night cycles. This hybridization is compressing energy consumption benchmarks while extending equipment service intervals in high-moisture environments.
EU F-Gas Regulation refrigerant phase-down mandates are forcing climate system redesigns across Spanish and Dutch greenhouse operations. Equipment manufacturers must certify new ventilation configurations for lower-global-warming-potential refrigerants or eliminate refrigerant dependence entirely. Controlled-environment vegetable producers are responding by accelerating mechanical ventilation specifications that reduce or eliminate compressor-based cooling.
Service unbundling is fragmenting traditional equipment supply relationships in commercial greenhouse operations. Dutch growers are separating ventilation hardware procurement from installation and maintenance contracts, opening specialist service provider channels. This pattern is most visible in Almería's pepper production cluster where mid-sized operators seek operational flexibility through modular service arrangements.
Greenhouse Ventilation System Market Segmentation
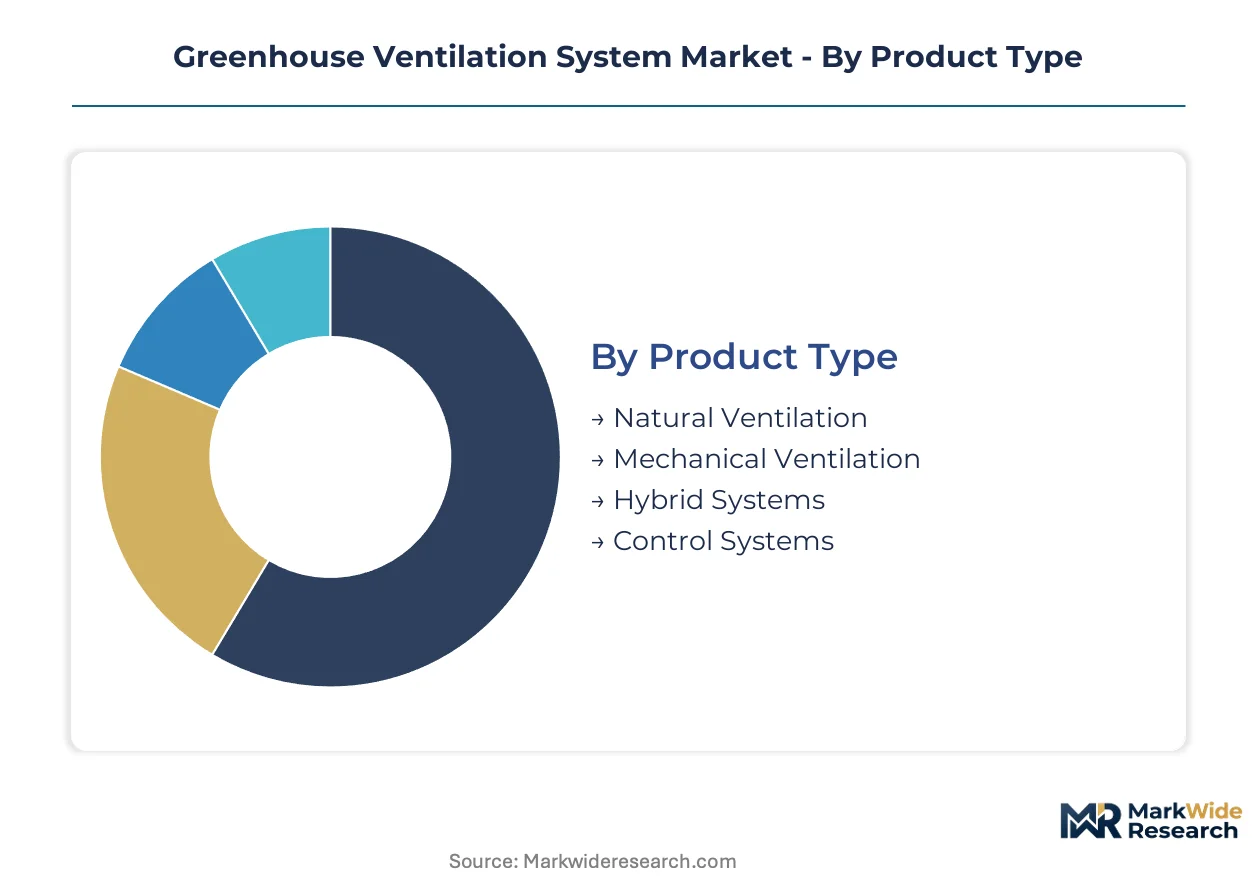
Segmentation in greenhouse ventilation reveals divergent service intensity requirements across product architectures. Mechanical systems demand intensive preventive maintenance programs, while sensor-based controls require software calibration contracts that reshape vendor-customer relationships.
Product Type:
After-sales service intensity varies dramatically across ventilation architectures, with mechanical systems requiring quarterly motor inspections and control systems needing continuous firmware updates.
- Mechanical Ventilation:Engineered assemblies of high-efficiency EC motors, axial fans, and ducting networks achieve air exchange rates of 10-30 volumes per hour. Dutch tomato producers in Westland specify these systems for humidity modulation during night cycles where passive designs fail. Service contracts typically cover motor bearing replacement and blade balancing on 18-month intervals.
- Control Systems:Programmable logic controllers, environmental sensors, and cloud-connected dashboards automate louver positioning and fan speed modulation. Spanish pepper growers in Almería are pulling these into retrofit projects as EU F-Gas Regulation tightens manual climate management tolerances. Vendors generate recurring revenue through sensor recalibration and software licensing.
- Natural Ventilation:Roof vents, side louvers, and wind-driven ridge extractors rely on thermal buoyancy and prevailing winds without motorized components.
- Hybrid Systems:Integrated architectures combine passive daytime cooling with mechanical night-cycle humidity control for Mediterranean climate zones.
By volume, Mechanical Ventilation leads. By growth pace, Control Systems is expanding most quickly.
End User:
Customer scale determines procurement sophistication, with commercial operations separating hardware from service contracts while home gardeners seek bundled turnkey solutions.
- Commercial Growers:Large-scale vegetable producers operating climate-controlled facilities exceeding 10 hectares require engineered ventilation with integrated CO2 dosing and humidity recovery. Netherlands-based greenhouse operators are unbundling equipment procurement from installation contracts to secure operational flexibility.
- Research Institutions:University agricultural departments and crop science facilities specify precision environmental control with data logging for experimental reproducibility.
- Agricultural Co-ops:Member-owned operations aggregate procurement for shared greenhouse facilities in Spain's Murcia region.
- Home Gardeners:Hobby-scale operators in North American suburban markets purchase compact fan-and-louver kits through garden retail channels.
Commercial Growers dominate absolute spend. Research Institutions are climbing the fastest as controlled-environment agriculture funding accelerates.
Technology:
Technology selection tracks climate severity, with extreme heat zones requiring active cooling while temperate regions optimize passive architectures.
- Sensor-based Systems:IoT-enabled temperature, humidity, and CO2 sensors feed predictive algorithms that preemptively adjust ventilation setpoints. These installations are gaining share fastest in Dutch operations where labor costs drive automation.
- Active Cooling:Compressor-based refrigeration and evaporative cooling units supplement fan ventilation in arid high-temperature zones.
- Automated Controls:Motorized louver actuators and variable-frequency drives respond to environmental sensor inputs without human intervention.
- Passive Cooling:Thermal mass, shade screens, and natural airflow patterns reduce mechanical energy consumption in moderate climates.
Sensor-based Systems command premium pricing. Automated Controls show the steepest expansion trajectory as retrofit demand concentrates in aging European greenhouse infrastructure.
Installation Type:
Project delivery mode reflects building vintage, with new construction enabling integrated design while retrofits confront structural constraints.
- Retrofit:Installation of automated ventilation into existing Dutch Venlo-type greenhouses requires structural reinforcement for motor mounting and cable routing. Spanish operators in Almería are accelerating these projects to meet EU F-Gas compliance deadlines.
- New Construction:Integrated ventilation design during greenhouse erection allows optimal ducting placement and sensor network architecture.
- Modular Systems:Pre-engineered ventilation units with standardized mounting interfaces reduce commissioning time for mid-sized growers.
- Custom Solutions:Bespoke engineering addresses non-standard greenhouse geometries or specialized crop requirements like cannabis odor containment.
Retrofit generates the largest project pipeline. Modular Systems are gaining share fastest as equipment-as-a-service channels lower capital barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch growers command premium pricing for precision-engineered systems while Spanish operators optimize for volume throughput in Mediterranean conditions. This asymmetry shapes procurement patterns across European greenhouse clusters and influences equipment specification tiers in export markets.
Netherlands
Westland greenhouse operators are unbundling equipment procurement from installation contracts to secure operational flexibility. EU F-Gas Regulation phase-down mandates are accelerating mechanical ventilation retrofits across Dutch Venlo-type facilities. The Randstad cluster concentrates demand for humidity-optimized EC motor systems serving tomato and pepper production.
Spain
Almería's pepper production cluster is generating concentrated demand for sensor-based climate controls as EU F-Gas compliance deadlines tighten. Spanish growers are separating ventilation hardware procurement from maintenance contracts through modular service arrangements. The southeast Mediterranean belt is retrofitting aging polyhouse structures with automated louver systems.
United States
North American licensed cannabis producers are installing specialized odor-containment ventilation with carbon filtration infrastructure. EPA energy efficiency standards are mandating higher motor efficiency tiers in climate-controlled agriculture. California's Central Valley and Pacific Northwest greenhouse belts are specifying integrated climate-lighting control platforms alongside LED retrofit projects.
Canada
Ontario and British Columbia greenhouse operators are adopting equipment-as-a-service channels to lower capital barriers for mid-sized vegetable producers. Health Canada regulations for controlled-environment agriculture are tightening environmental documentation requirements. The Prairie Provinces are expanding tomato and cucumber production facilities with mechanical ventilation specified for extreme cold climate performance.
China
Shandong Peninsula and Yangtze River Delta greenhouse belts are scaling climate-controlled vegetable production for domestic food security programs. MIIT efficiency standards for agricultural machinery are driving motor technology upgrades in protected cultivation. Shouguang's greenhouse cluster is integrating domestic fan manufacturing with imported sensor-based control systems.
Greenhouse Ventilation System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying motors, sensors, and fan assemblies to multiple downstream assemblers. The vendor base organizes around three archetypes: full-service greenhouse project deliverers, specialized ventilation component manufacturers, and diversified climate equipment conglomerates. Two competitive moves dominate: geographic expansion through distribution partnerships and technology convergence bundling ventilation with lighting and irrigation controls.
Among the named players, Munters exemplifies the scale-driven conglomerate archetype with manufacturing breadth across North American operations. Vostermans and Dalsem occupy differentiated positions—Vostermans represents specialized fan engineering for high-humidity agricultural environments, while Dalsem anchors the integrated project delivery tier that bundles ventilation with structural and climate systems. These three illustrate how competitive positioning fragments across component specialization versus system integration vectors.
| Leading Market Players |
|---|
| Rough Brothers Inc. |
| Greenhouse Megastore |
| Richel Group |
| GGS Structures Inc. |
| Agra Tech |
| Vostermans |
| Dalsem |
| Munters |
| Harnois |
| Others |
Pricing and Supply Chain Analysis
Shouguang's greenhouse manufacturing cluster in Shandong Province anchors global fan motor capacity, with its domestic EC motor production scaling directly influencing pricing power for European and North American system integrators. Dutch equipment buyers face widening spreads between premium sensor-integrated ventilation and standard mechanical configurations as this concentration tightens.
Pricing Analysis
Configured-to-order pricing for integrated climate-lighting platforms commands substantial premiums over standard mechanical ventilation SKUs. Project-based contracting dominates commercial greenhouse procurement, with price differentiation tracking motor efficiency tier and after-sales service bundling intensity. Cost compression in mid-tier equipment is intensifying because Spanish and Dutch growers are unbundling hardware from installation contracts. Agricultural co-ops in Murcia exhibit highest price sensitivity, while Netherlands-based Westland operators prioritize performance specifications over unit economics.
Supply Chain Analysis
Contract manufacturing for EC motor assemblies concentrates in China, Germany, and the Netherlands, with Shouguang-based foundries feeding component supply to European system integrators. Rare-earth magnet sourcing draws from Chinese processing facilities, while copper winding supply rests on Chilean and Peruvian mining output. Single-source vulnerability in rare-earth magnet supply creates structural risk for high-efficiency motor production. Distribution runs through greenhouse project developers and specialized agricultural equipment distributors serving regional production clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward commercial greenhouse operators in the Netherlands and Spain as procurement unbundling fragments traditional vendor relationships. This consolidation of purchasing sophistication among mid-sized growers is forcing equipment suppliers toward flexible service arrangements.
For Market Incumbents: Build switching-cost moats through sensor calibration subscription bundles that lock in Dutch tomato producers beyond hardware replacement cycles. Deepen backward integration into EC motor manufacturing to offset rare-earth magnet cost volatility. Anchor capacity expansion in Almería's pepper production cluster to capture EU F-Gas retrofit demand before compliance deadlines tighten. For New Entrants and Emerging Players: Build out odor-containment ventilation specialization targeting North American licensed cannabis producers where regulatory compliance creates premium pricing tolerance. Canadian equipment-as-a-service channels offer the most penetrable entry path for mid-sized vegetable operators seeking capital flexibility. Lead with modular retrofit kits designed for aging Dutch Venlo-type greenhouse structural constraints. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EU F-Gas phase-down mandates and EPA efficiency standards are structurally expanding addressable market for mechanical ventilation retrofits. Target acquisition candidates with integrated control system software platforms and established service contract revenue streams. Watch Health Canada environmental documentation requirements as the inflection signal for North American controlled-environment agriculture capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EC Motor Manufacturing Scale-Up | Captures efficiency tier premiums as EU F-Gas mandates accelerate motor upgrades across Dutch facilities. |
| Sensor-Platform Integration Partnership | Bundles ventilation controls with LED lighting retrofits in California Central Valley greenhouse operations. |
| Equipment-as-a-Service Channel Launch | Lowers capital barriers for Spanish mid-sized pepper growers through modular lease arrangements. |
| Odor-Containment System Certification | Unlocks North American cannabis producer segment requiring carbon filtration infrastructure compliance. |
| Retrofit-Focused Engineering Development | Addresses structural reinforcement needs in aging Dutch Venlo-type greenhouse ventilation upgrades. |
Research Methodology
A spread of perspectives from greenhouse project engineers, agricultural equipment procurement managers, climate system maintenance directors, and controlled-environment agriculture facility operators converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with Dutch Westland operators and Spanish Almería growers alongside secondary validation through EU F-Gas Regulation implementation reports, EPA energy efficiency standard filings, and agricultural machinery trade data. Bottom-up equipment shipment tracking and top-down greenhouse construction permit analysis provided triangulation across the analysis window.
Demand-supply balance modeling anchored the forecast framework across the projection horizon. Segmentation dimensions included product architecture type, installation mode, technology tier, and regional regulatory cluster intensity. CAGRs were derived from equipment replacement cycle analysis and new greenhouse construction pipeline assessment. Industry-specific inputs incorporated EU F-Gas compliance deadline scheduling and Health Canada controlled-environment agriculture documentation requirement evolution.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified climate equipment conglomerates would shift outcomes beyond modeled ranges. Regulatory acceleration or delay in refrigerant phase-down timelines represents primary revision risk. Cross-checking against national greenhouse construction permit databases and agricultural machinery import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Cooling Tower Fans Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Global Ductless Heating and Cooling Systems Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
Spray Booth Ventilation System Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Industrial Exhaust Fan Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Global Ventilation Grills Market
HVAC Systems
North America Scrubber System Market
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Europe Boiler System Market
HVAC Systems
Water Saving Shower Heads Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
Gas Wall Hung Boilers Market