
 Global PUR and PIR Sandwich Panels Market | 2026-2036
Global PUR and PIR Sandwich Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Global PUR and PIR Sandwich Panels Market Foresight
Modular prefabrication of wall-and-roof assemblies is recalibrating buyer choice toward factory-integrated panel systems that compress on-site labor. Kingspan Group leverages its controlled distribution network across Europe to anchor specification-driven projects. Tata Steel competes through captive steel supply and in-house polyurethane chemistry, while Metecno Group specializes in cold-chain configurations for food processing clients.
PUR and PIR sandwich panels are composite building elements comprising rigid polyurethane or polyisocyanurate foam cores bonded to metal or polymer facings, delivering thermal conductivity values near 0.022 W/m·K for temperature-controlled envelopes. Their primary commercial purpose is to minimize thermal bridging in refrigerated warehouses, clean rooms, and climate-sensitive manufacturing plants. Polyisocyanurate foam panels command margin pools in data center and pharmaceutical applications where fire resistance ratings and dimensional stability under load are non-negotiable. Cold storage facilities represent the most mature application segment, while modular buildings are attracting accelerated specification activity from developers seeking compressed construction schedules.
REACH in Europe restricts isocyanate exposure limits and mandates hazard communication across the supply chain, elevating compliance costs for panel fabricators. The EPA in the United States enforces SNAP program phaseouts of high-GWP hydrofluorocarbon blowing agents, forcing reformulation of core foam chemistry. China's MEE enforces VOC emission standards at manufacturing plants, reshaping production equipment investment patterns. Stakeholders must monitor regulatory divergence on blowing agent chemistry, as compliance with one jurisdiction's low-GWP mandate may not satisfy another's fire-performance or toxicity thresholds.
Market Dynamics
The EU F-Gas Regulation is forcing wholesale reformulation of core foam chemistry across the entire supply base, compressing margins for non-compliant fabricators while rewarding early movers with locked-in specification pipelines.
Growth Catalysts
- EU F-Gas Regulation:Mandates phase-down of high-GWP blowing agents, accelerating R&D investment in hydrofluoroolefin and hydrocarbon alternatives among German and French panel producers.
- Cold storage buildout:Food processing facilities in China and the United States are expanding refrigerated warehouse capacity to serve e-commerce grocery fulfillment networks.
- Polyisocyanurate fire performance:Superior flame resistance ratings are displacing conventional PUR in data center and pharmaceutical clean room specifications where insurance underwriters demand stricter material certification.
Market Restraints
- Steel price volatility:Galvanized coil and aluminum facing costs fluctuate with energy-intensive smelting economics, compressing fabricator margins on fixed-price construction contracts.
- Blowing agent supply concentration:Patent-protected low-GWP formulations from a narrow base of chemical suppliers create input bottlenecks during regulatory transition periods.
- Technical limitation in extreme cold:PIR foam exhibits brittle fracture susceptibility below -40°C, restricting deployment in Arctic LNG terminal applications without costly protective lamination.
Strategic Opportunities
- India cold-chain deficit:Perishable food losses exceeding 30% create urgent demand for refrigerated warehousing as the country's FSSAI tightens food safety infrastructure mandates.
- Modular data center integration:Factory-integrated panel systems converge with precision cooling and power distribution modules, enabling turnkey hyperscale facility deployment.
- US Inflation Reduction Act:Energy efficiency tax credits for commercial building envelopes are redirecting developer specification toward high-R-value insulated panel assemblies.
Industry Challenges
- Polyurethane chemist shortage:Specialized formulation expertise for low-GWP blowing agent integration is concentrated among retiring technical staff at legacy European producers.
- Multi-jurisdiction certification lag:Fire-performance testing to EN 13501-2, FM 4880, and UL 1040 standards creates 18-24 month product launch timelines for global fabricators.
- Legacy ERP integration:Batch manufacturing execution systems at established plants resist real-time connectivity with modular prefabrication scheduling platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PUR and PIR Sandwich Panels Market |
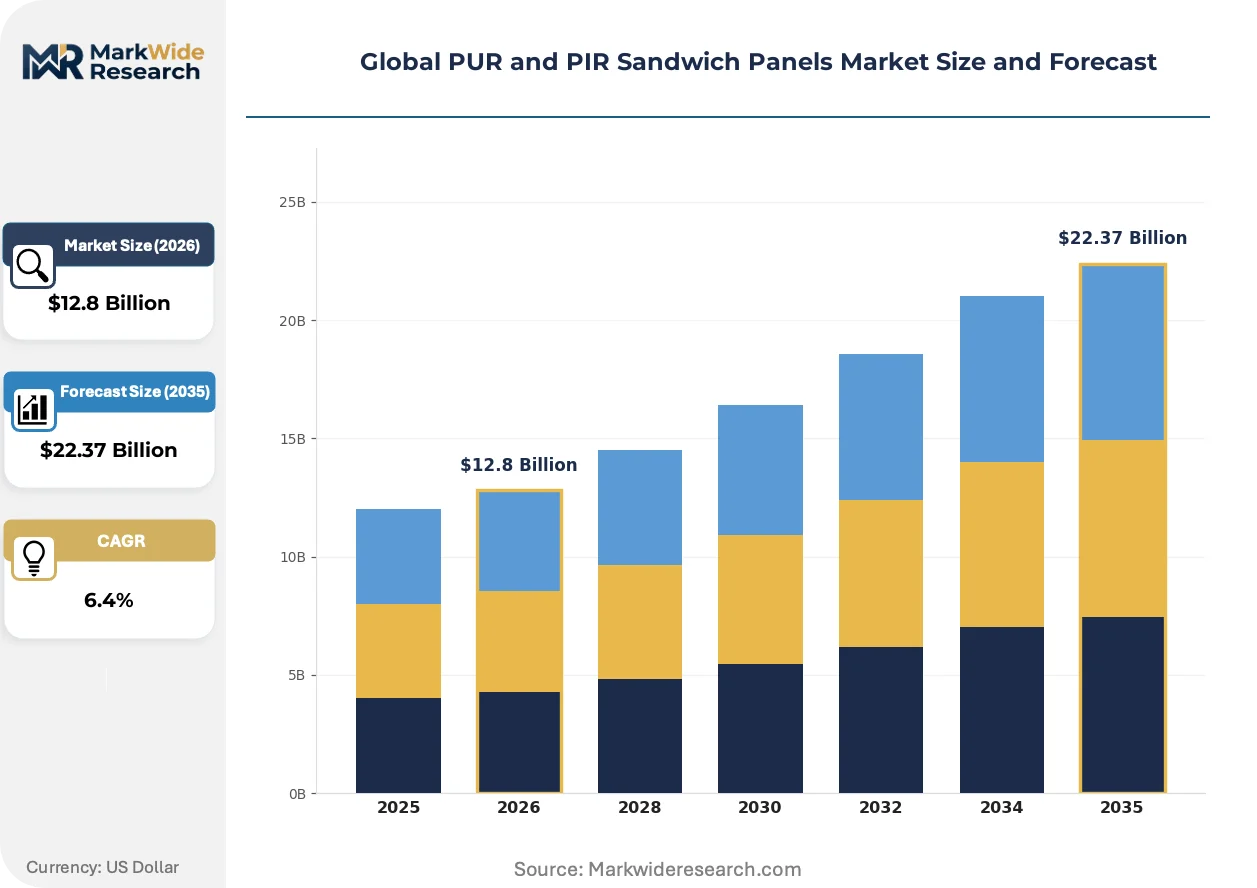
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane Foam Panels, Polyisocyanurate Foam Panels, Composite Sandwich Boards, Insulated Metal Panels Application: Cold Storage Facilities, Commercial Roofing, Wall Cladding, Modular Buildings, Clean Rooms End Use Industry: Food Processing Facilities, Data Centers, Warehousing, Pharmaceutical Units, Educational Institutions Installation Type: New Construction, Retrofit Projects, Prefabricated Systems, Industrial Assemblies |
| Companies Covered | Tata Steel, Isopan S.p.A., Kingspan Group, Dana Group, Ruukki, Metecno Group, Assan Panel, Lattonedil S.p.A., ArcelorMittal Construction, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PUR and PIR Sandwich Panels Market Shifts & Advancements
Factory-integrated envelope systems are compressing construction schedules and recalibrating buyer expectations toward turnkey performance guarantees rather than component-level procurement.
Continuous panel production lines with inline foaming and automated facing lamination are modularizing delivery of complete wall-and-roof assemblies. Data center developers in Germany and the Netherlands are specifying these systems to compress mechanical-electrical-envelope integration timelines from months to weeks. The structural consequence is displacement of stick-built insulation approaches in speed-sensitive verticals.
REACH authorization requirements for aromatic diisocyanates are elevating hazard communication and exposure monitoring obligations across the European supply chain. Panel fabricators must now maintain substance volume tracking from raw material through end-of-life demolition protocols. Food processing and pharmaceutical clean room segments are absorbing compliance costs through longer-term supplier contracts that amortize certification investment.
Developer procurement of envelope systems is consolidating toward design-build contractors with captive panel supply relationships, bypassing traditional distributor channels. Cold storage construction in the United States is concentrating award volume with national refrigeration contractors who self-perform insulated envelope installation. This channel compression is marginalizing independent specification influence among regional architectural practices.
Global PUR and PIR Sandwich Panels Market Segmentation
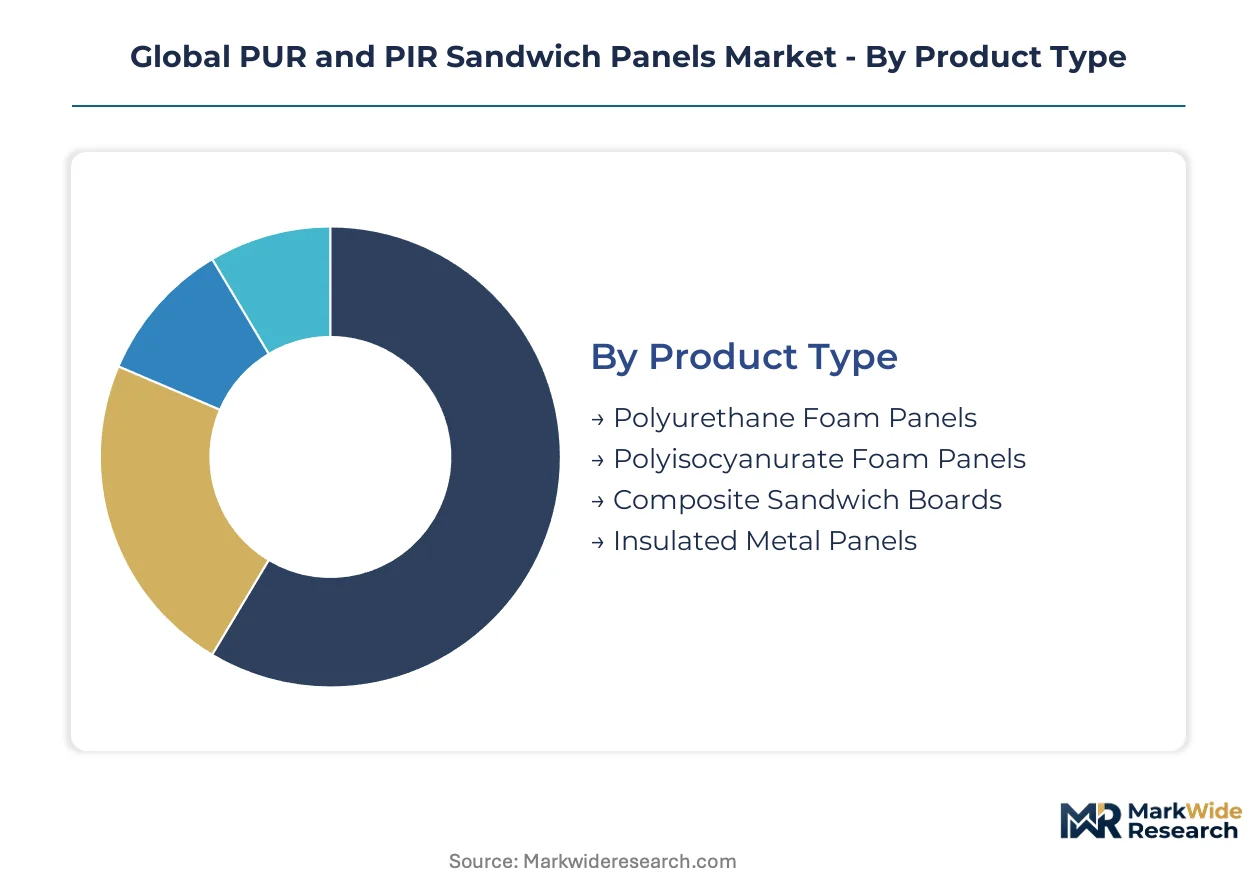
Segmentation in the PUR and PIR sandwich panels market reveals how technical specifications, regulatory compliance, and installation economics fragment procurement decisions across buyer categories. Understanding these divisions exposes where margin pools concentrate and which specifications are displacing legacy alternatives.
Product Type:
Supply concentration in foam chemistry patents and facing metal rolling capacity shapes competitive positioning across product categories.
- Polyisocyanurate Foam Panels:Closed-cell rigid foam cores deliver superior fire resistance ratings and dimensional stability under sustained load. Data center developers in Germany and the Netherlands specify these panels where insurance underwriters mandate FM 4880 certification and thermal conductivity below 0.024 W/m·K.
- Polyurethane Foam Panels:Conventional PUR formulations dominate cold storage construction through lower material cost and established supply chains. Food processing facilities in China absorb the majority of global PUR panel volume for refrigerated warehouse envelopes where fire ratings are less stringent.
- Composite Sandwich Boards:Hybrid core constructions bond mineral wool or EPS with polyurethane layers for mixed-performance applications.
- Insulated Metal Panels:Pre-finished steel or aluminum facings with factory-applied foam cores serve fast-track commercial roofing projects.
Today's leader: Polyurethane Foam Panels. Tomorrow's challenger: Polyisocyanurate Foam Panels.
Application:
Cost tier differentiation separates specification-driven premium envelopes from commodity procurement in standard climate control.
- Cold Storage Facilities:Temperature-controlled warehouses demand continuous insulation envelopes with thermal bridging minimized at panel joints. E-commerce grocery fulfillment networks in the United States and China are expanding refrigerated capacity, driving panel procurement volumes at specifications requiring -25°C operational stability.
- Modular Buildings:Factory-integrated wall-and-roof assemblies compress construction schedules from months to weeks. German developers specify turnkey envelope systems where mechanical-electrical integration occurs off-site.
- Clean Rooms:Pharmaceutical and semiconductor manufacturing requires particle-controlled environments with sealed panel joints and wash-down surfaces.
- Commercial Roofing:Standing-seam and concealed-fastener panel systems replace built-up roofing in industrial facilities seeking faster installation.
- Wall Cladding:Architectural facade panels combine thermal performance with aesthetic finishes for commercial and institutional exteriors.
Volume concentrates in Cold Storage Facilities. Steepest expansion trajectory: Modular Buildings.
End Use Industry:
Customer type fragmentation separates specification influencers from procurement decision-makers across vertical markets.
- Data Centers:Hyperscale facility operators demand fire-resistant envelopes with precise thermal performance guarantees. The EU F-Gas Regulation and EPA SNAP program are accelerating specification shifts toward low-GWP panel cores in German and US deployments.
- Food Processing Facilities:Refrigerated production and storage environments require hygienic panel surfaces resistant to chemical cleaning protocols. India's FSSAI mandates are tightening cold-chain infrastructure requirements, opening new specification opportunities.
- Pharmaceutical Units:Clean room and cold chain applications demand validated panel systems with batch traceability and fire certification to EN 13501-2.
- Warehousing:General logistics facilities prioritize cost-optimized insulation over specialized performance characteristics.
- Educational Institutions:Public sector procurement emphasizes first-cost minimization in climate-controlled building envelopes.
Specification authority sits with Data Centers. Procurement volume flows through Food Processing Facilities.
Installation Type:
Geography of construction labor cost and project urgency determines installation method selection across markets.
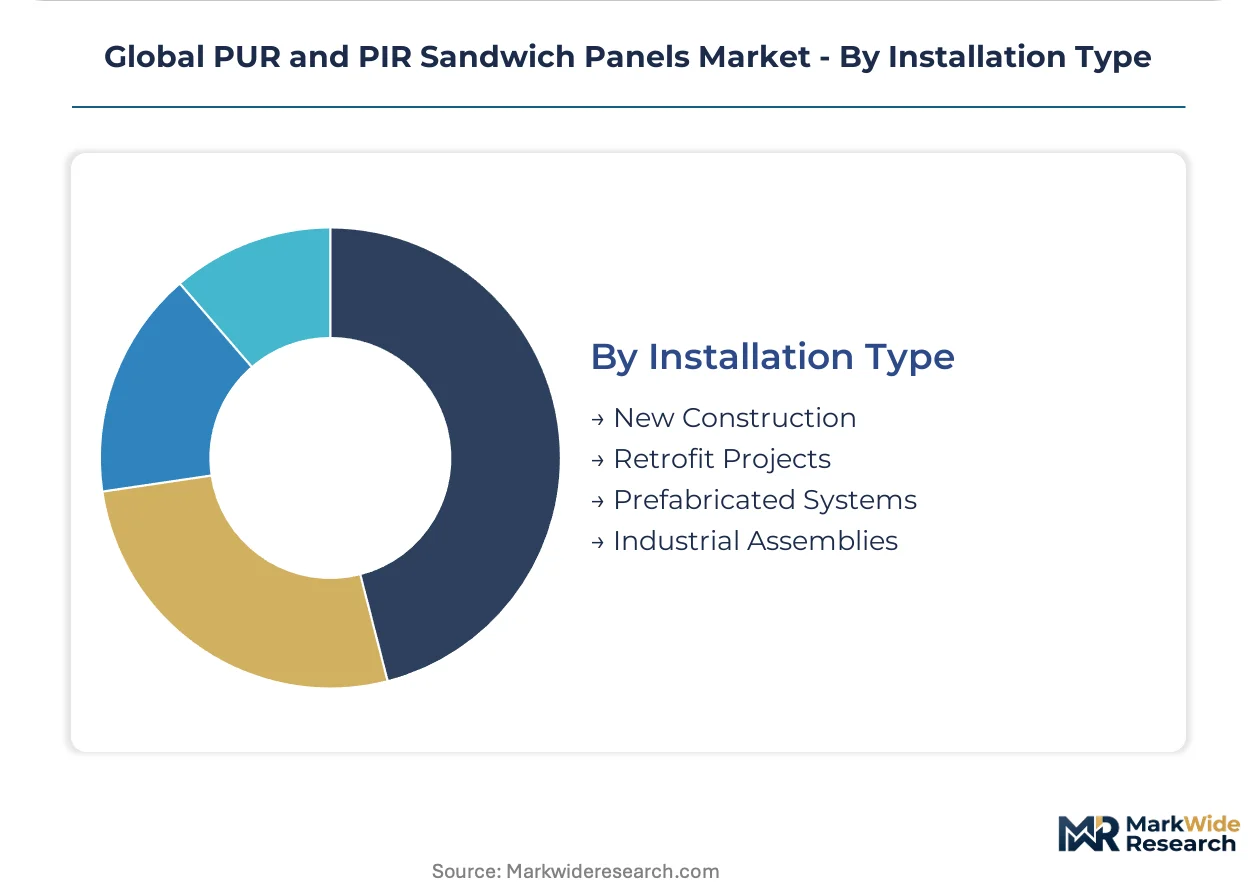
- Prefabricated Systems:Complete wall-and-roof modules arrive site-ready with integrated windows, doors, and MEP rough-ins. Dutch and German data center contractors specify these systems to compress mechanical-electrical-envelope integration timelines.
- New Construction:Ground-up projects allow optimized panel sequencing and joint detailing for maximum thermal performance.
- Retrofit Projects:Existing building envelope upgrades face dimensional constraints and structural loading limitations.
- Industrial Assemblies:Heavy-duty panel systems with enhanced structural cores serve manufacturing facilities with equipment mounting requirements.
Momentum favors Prefabricated Systems. Legacy volume remains in New Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered continuous panel lamination technology in the 1970s, establishing the industrial foundation that now spans factory-integrated envelope systems across multiple continents. Cold storage construction and data center buildout now concentrate procurement volumes in specific national markets with distinct regulatory drivers.
Germany
Hyperscale data center operators in Frankfurt and Berlin demand FM 4880-certified PIR panels with thermal conductivity below 0.024 W/m·K. The EU F-Gas Regulation forces reformulation of core foam chemistry among Bavarian and North Rhine-Westphalian fabricators. Industrial clusters around Düsseldorf and Munich anchor specification-driven procurement for pharmaceutical clean rooms and refrigerated logistics facilities.
China
E-commerce grocery fulfillment networks in Shanghai and Beijing are expanding refrigerated warehouse capacity at unprecedented scale. The MEE enforces VOC emission standards at manufacturing plants, reshaping production equipment investment patterns across Shandong and Jiangsu provinces. Yangtze River Delta panel producers now supply modular cold-chain infrastructure for domestic food processing majors and Southeast Asian export markets.
United States
Refrigerated warehouse construction in Dallas-Fort Worth and Chicago serves Amazon, Walmart, and Kroger distribution networks. The EPA SNAP program phaseouts of high-GWP hydrofluorocarbon blowing agents force reformulation of core foam chemistry among domestic fabricators. Texas and Illinois industrial corridors concentrate national refrigeration contractors who self-perform insulated envelope installation, bypassing traditional distributor channels.
India
Perishable food losses exceeding 30% create urgent demand for refrigerated warehousing as FSSAI tightens food safety infrastructure mandates. Maharashtra and Gujarat cold-chain deficits attract panel procurement from European and East Asian suppliers seeking volume offset. Mumbai-Pune and Ahmedabad-Vadodara industrial belts are emerging as specification battlegrounds for pharmaceutical and dairy processing applications.
Netherlands
Data center developers in Amsterdam and Eindhoven specify factory-integrated envelope systems to compress mechanical-electrical-envelope integration timelines. REACH authorization requirements for aromatic diisocyanates elevate hazard communication obligations across the Dutch supply chain. Randstad logistics hubs are deploying modular panel systems for temperature-controlled pharmaceutical distribution to continental European markets.
Global PUR and PIR Sandwich Panels Market Competitive Landscape
The competitive structure tilts toward integrated building envelope specialists with captive chemistry capabilities and controlled distribution networks. Three to five multinational fabricators anchor specification-driven segments in data centers and pharmaceutical clean rooms, while regional metal processors compete on cost-optimized cold storage procurement. The vendor base stratifies across premium PIR specialists, volume PUR producers, and steel-backed integrated manufacturers. Dominant competitive moves include backward integration into polyurethane chemistry and strategic partnerships with national refrigeration contractors.
Among European-integrated fabricators, Kingspan Group and Metecno Group exemplify the envelope-systems archetype with specification authority in data center and cold-chain verticals. Tata Steel occupies a position representing the steel-backed integrated model, leveraging captive metallurgical supply for facing material cost control. These three anchors illustrate how competitive positioning diverges between chemistry-forward and materials-forward strategic postures.
| Leading Market Players |
|---|
| Tata Steel |
| Isopan S.p.A. |
| Kingspan Group |
| Dana Group |
| Ruukki |
| Metecno Group |
| Assan Panel |
| Lattonedil S.p.A. |
| ArcelorMittal Construction |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators across Northern Italy and the German Mittelstand anchor supply discipline through generational ownership horizons that resist short-term price wars. Their patient capital structures buffer margin compression during raw material spikes while sustaining R&D investment in low-GWP foam chemistry.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FM 4880-certified PIR panels for data centers from commodity PUR grades for cold storage. Price differentiation rests on fire certification tier and volume commitment scale. Cost compression in standard-grade PUR is intensifying because Chinese producers are absorbing steel facing volatility to maintain share. Cold storage developers exhibit highest price sensitivity, while pharmaceutical clean room operators prioritize certified performance over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for cold-chain infrastructure are reshaping sourcing patterns toward Maharashtra-based steel rolling and Gujarat foam production. Supply concentrates in Germany, China, and the United States for continuous lamination equipment and proprietary blowing agent formulations. Raw material dependencies encompass galvanized steel coil, aromatic diisocyanates, and hydrofluoroolefin propellants. Single-source vulnerability in patent-protected low-GWP chemistry creates bottlenecks during regulatory transitions. Distribution runs through national refrigeration contractors who self-perform envelope installation in the United States and design-build specialists in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as data center and pharmaceutical specifications harden around FM 4880 and EN 13501-2 certification tiers, displacing uncertified alternatives.
For Market Incumbents: To counter margin erosion from Chinese commodity imports, lock in specification pipelines through captive blowing agent chemistry partnerships and extend service revenue via predictive maintenance contracts on installed panel envelopes. Prioritize certification investment in India's FSSAI-mandated cold-chain buildout before local competitors achieve scale. For New Entrants and Emerging Players: Enter via modular data center integration partnerships where factory-integrated envelope systems converge with precision cooling modules, bypassing established distributor channels. Target India's Gujarat and Maharashtra cold-chain deficits where European supply relationships command premium positioning. Lead with turnkey performance guarantees rather than component-level pricing. For Investors and Strategic Acquirers: Valuations sit cheapest among regional metal processors lacking captive foam chemistry, presenting consolidation candidates for backward integration plays. Long-term viability hinges on locked-in low-GWP formulation access and specification authority in data center verticals. Watch for EPA SNAP enforcement acceleration as the inflection signal for domestic US reformulation investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Chemistry | Captive isocyanate supply secures margin control during REACH authorization transitions. |
| Factory-Integrated Envelope Systems | German data center developers compress mechanical-electrical integration timelines from months to weeks. |
| Low-GWP Blowing Agent Reformulation | EU F-Gas Regulation compliance locks in specification pipelines for early movers. |
| National Refrigeration Contractor Partnerships | US channel compression bypasses traditional distributors for cold storage procurement volume. |
| India Cold-Chain Infrastructure Certification | FSSAI mandates create urgent demand for refrigerated warehousing in Maharashtra and Gujarat. |
Research Methodology
Multiple input streams — technical discussions with plant managers at European and Chinese panel fabricators, procurement leads at food processing and data center developers, and distribution channel partners — were reconciled against customs filings, ECHA REACH registration databases, and SEC disclosures from building materials specialists. Bottom-up volume estimates from continuous lamination line capacity and top-down demand calibration from construction permit data were cross-validated.
Historical shipment patterns were cross-referenced against panel input from plant-level technical assessments across the projection horizon. Segmentation dimensions modeled encompass product type, application vertical, end-use industry, and installation method. CAGRs were derived from regression analysis of panel procurement against cold storage construction starts and data center capex cycles, with specific inputs from EPA SNAP program phaseout timelines and EU F-Gas Regulation step-down schedules.
Inputs from regulatory filing databases and industry association production surveys were available through the study window; gaps in real-time panel inventory data and proprietary blowing agent formulation costs introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions regarding enforcement consistency of low-GWP mandates and steel price normalization trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Europe Geogrids Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
Cladding Systems Market