
 Elevated Water Storage Tanks Market | 2026-2036
Elevated Water Storage Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Elevated Water Storage Tanks Market Analysis
India is fragmenting its elevated water storage tank supply base as domestic steel fabrication capacity expands and municipal Jal Jeevan Mission contracts multiply. CB&I leverages its legacy in large-diameter welded steel reservoirs to anchor utility-scale projects across the Midwest. McWane Ductile competes through ductile iron expertise and backward integration into foundry operations. Caldwell Tanks specializes in composite elevated tanks with concrete pedestals, differentiating on seismic resilience in earthquake-prone zones.
Elevated water storage tanks are vertical reservoirs mounted on structural supports or pedestals that maintain hydraulic pressure in distribution networks without continuous pumping, typically constructed from welded steel, reinforced concrete, or composite materials with capacities ranging from thousands to millions of gallons. Steel tank types dominate existing installed base due to lower capital cost and AWWA D100 fabrication standards, though concrete variants capture premium margin pools where seismic codes demand mass-damping performance. Municipal end users represent the mature volume anchor, while industrial applications in power generation and data center cooling constitute the fastest-growing demand segment as process water reliability requirements tighten.
AWWA D100 and D110 standards govern welded steel and prestressed concrete tank design in North America, while EPA Safe Drinking Water Act amendments drive lead-free material mandates and inspection frequency. India's BIS certification requirements and Jal Jeevan Mission technical specifications are reshaping procurement criteria for rural elevated storage. Stakeholders must monitor evolving seismic zone reclassifications and corrosion protection mandates that will determine retrofit versus replacement economics across aging tank inventories.
Market Dynamics
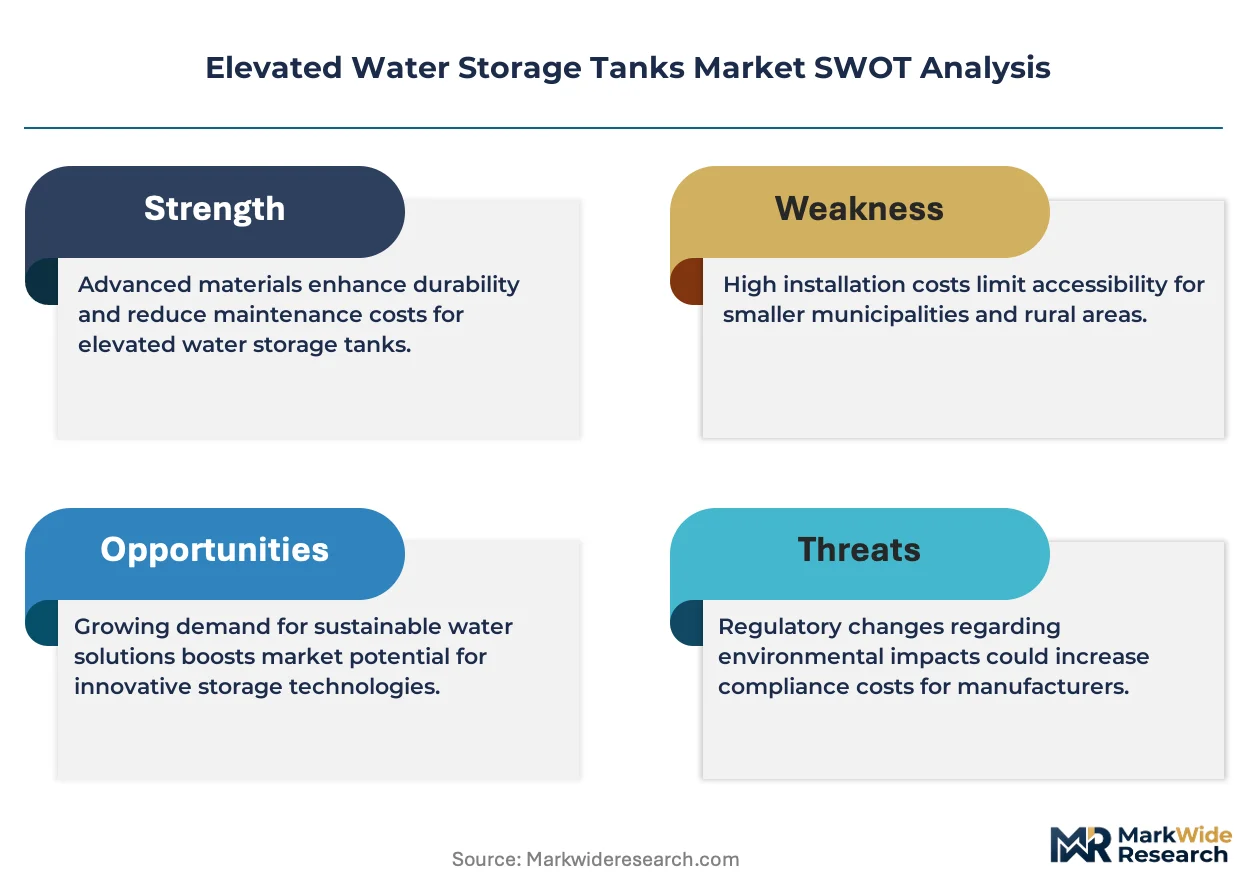
Municipal infrastructure replacement cycles are compressing as corrosion failures in 1960s-era welded steel tanks accelerate, forcing utilities to choose between AWWA D100-compliant rehabilitation and full composite pedestal replacement.
Growth Catalysts
- Jal Jeevan Mission procurement:India's rural water scheme is generating thousands of elevated tank contracts, fragmenting supply toward domestic fabricators with BIS certification.
- Data center cooling reliability:Hyperscale operators are specifying redundant elevated storage for process water backup, creating industrial demand outside traditional municipal anchors.
- Seismic zone reclassifications:Updated USGS hazard maps in the Intermountain West are mandating mass-damped concrete pedestal designs that command premium engineering margins.
Market Restraints
- Steel price volatility:Hot-rolled coil fluctuations disrupt project budgeting for welded steel tank contractors, compressing bid accuracy on fixed-price municipal contracts.
- Fabrication capacity concentration:Large-diameter rolled plate forming is limited to a handful of Gulf Coast and Midwest facilities, creating geographic supply bottlenecks during peak construction seasons.
- Concrete curing timelines:Prestressed tank construction requires 28-day minimum curing periods that conflict with compressed municipal procurement schedules favoring faster steel erection.
Strategic Opportunities
- Smart monitoring integration:IoT corrosion sensors and structural health telemetry are opening recurring revenue streams for tank operators seeking predictive maintenance contracts.
- Industrial microgrids:Power generation facilities are pairing elevated storage with on-site water treatment, creating bundled EPC opportunities beyond standalone tank supply.
- EPA Lead and Copper Rule revisions:Lead-free material mandates are disqualifying legacy coated steel inventories, accelerating replacement demand in older distribution systems.
Industry Challenges
- Welder certification scarcity:AWWA D100-qualified structural welders are retiring faster than apprenticeship programs replenish skilled labor pools, extending project timelines.
- Legacy foundation assessment:Existing concrete pedestals often lack original geotechnical documentation, forcing expensive subsurface investigation before capacity upgrades.
- Multi-agency permitting:Aviation clearance requirements near airports and FAA coordination add procedural layers that municipal utilities underestimate in procurement schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elevated Water Storage Tanks Market |
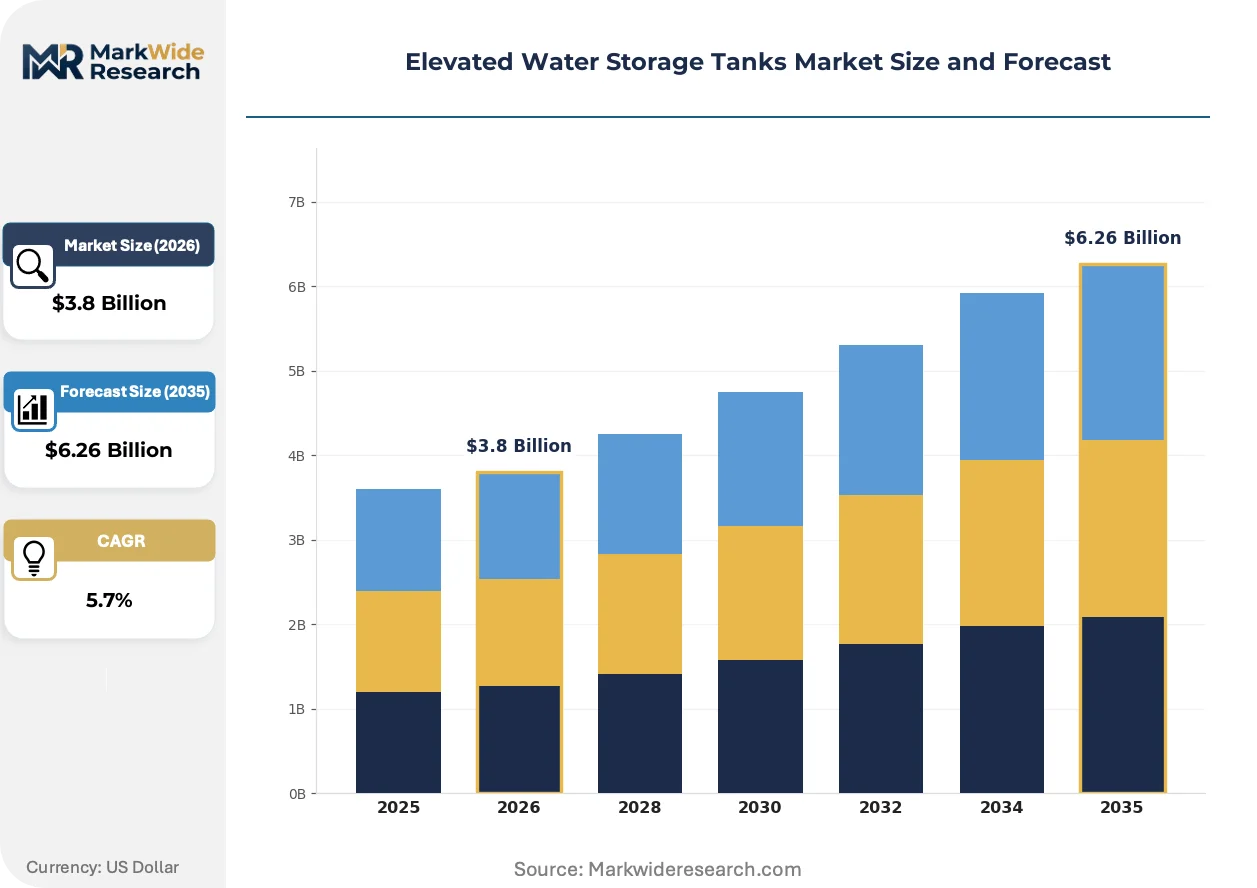
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tank Type: Steel, Concrete, Fiberglass, Plastic Capacity: Less than 1000 Gallons, 1000 to 5000 Gallons, 5000 to 10000 Gallons, More than 10000 Gallons Installation Method: Above Ground, In Ground, Modular, Elevated End User: Agriculture, Residential, Industrial, Municipal |
| Companies Covered | CB&I, McWane Ductile, Pittsburg Tank & Tower Group, DN Tanks, Superior Tank Co., Caldwell Tanks, Phoenix Tank, Containment Solutions, Landmark Structures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elevated Water Storage Tanks Market Emerging Trajectories
Digital design-to-fabrication workflows and advanced composite materials are compressing traditional engineering cycles while expanding performance envelopes beyond conventional steel and concrete specifications.
Glass-reinforced polymer (GRP) linings and thermoset coating systems are extending service intervals for welded steel interiors by eliminating galvanic corrosion at waterlines. Municipal utilities in coastal Florida and Gulf Coast Texas are specifying these systems on replacement contracts. Conventional epoxy coating rehabilitation cycles is rendering obsolete for high-chloride environments.
EPA's Lead and Copper Rule Improvements are tightening material traceability requirements for all wetted surfaces, forcing fabricators to document mill certifications through final coating application. Tank owners in Illinois and Ohio are front-loading inspection budgets to demonstrate compliance ahead of enforcement timelines. Small municipal systems with limited engineering staff face the steepest adaptation curves.
Performance-based specifications are displacing prescriptive design-bid-build contracts as water authorities transfer seismic and corrosion risk to EPC contractors. California's Department of Water Resources and Texas Water Development Board have both adopted outcome-oriented procurement templates. This shift concentrates contract awards toward integrated fabricators with in-house geotechnical and structural engineering capabilities.
Elevated Water Storage Tanks Market Segmentation
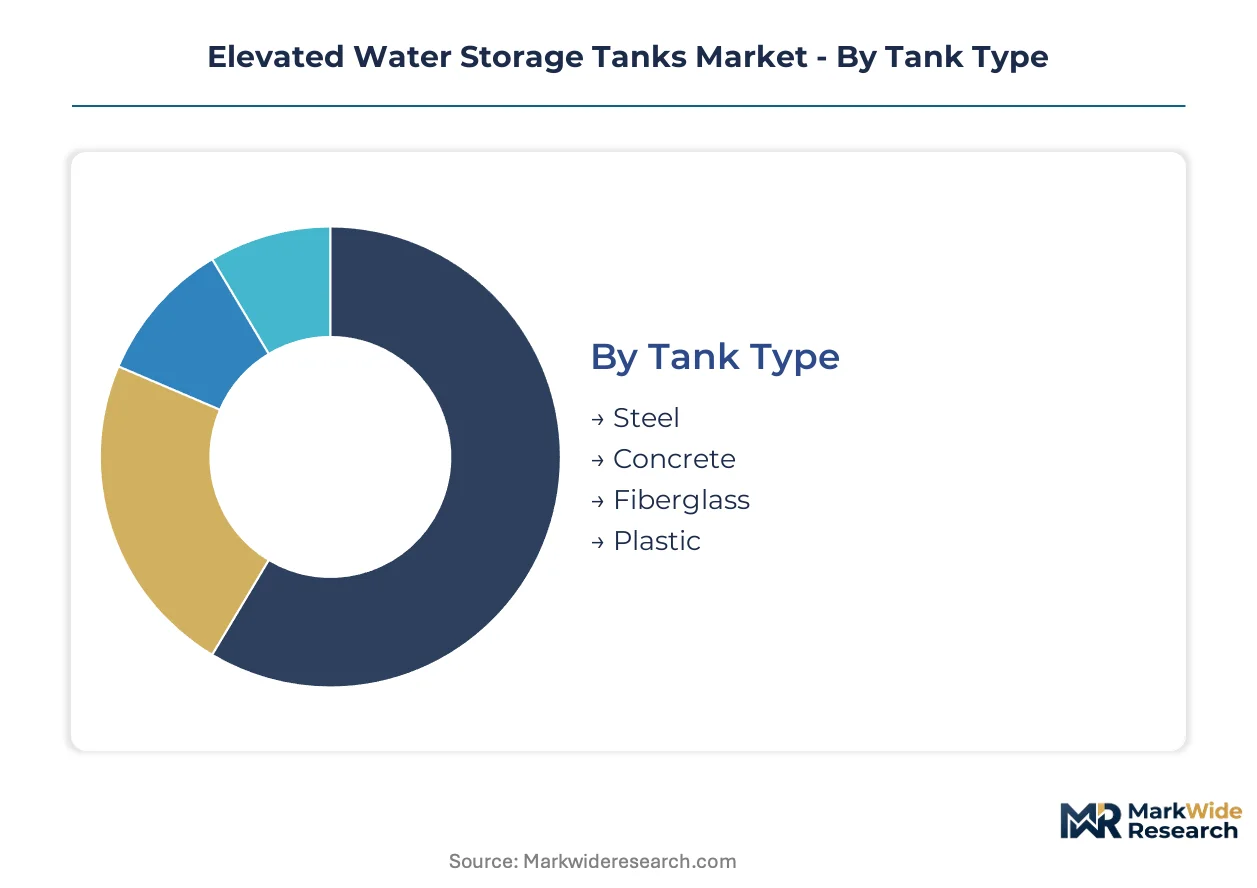
Segmentation in elevated water storage tanks reveals how material science, hydraulic engineering, and procurement economics intersect. Understanding these divisions exposes where capital concentrates and which specifications command premium positioning.
Tank Type:
Mature welded steel dominates existing infrastructure while emerging composites reshape seismic-critical applications.
- Steel:Welded carbon steel fabricated to AWWA D100 standards offers the lowest capital cost per gallon and fastest field erection. Municipal utilities in Texas and Florida specify steel for routine replacement cycles where seismic loads remain moderate.
- Concrete:Prestressed concrete with composite pedestals delivers mass-damping performance for updated USGS seismic zones. California's Department of Water Resources mandates concrete for high-hazard areas, compressing procurement toward engineered-to-order contracts.
- Fiberglass:Corrosion-resistant GRP shells suit coastal desalination plants and chemical process water with minimal maintenance intervals.
- Plastic:Rotationally molded polyethylene serves temporary construction dewatering and remote agricultural applications with limited structural load requirements.
Steel handles the majority of throughput; concrete is the fastest mover on share.
Capacity:
Volume tiers align with hydraulic pressure requirements and foundation economics across distribution network scales.
- Less than 1000 Gallons:Compact elevated tanks serve isolated residential clusters and agricultural irrigation points with minimal pumping infrastructure.
- 1000 to 5000 Gallons:Mid-scale steel tanks anchor small municipal systems and rural water districts where population density supports distributed storage.
- 5000 to 10000 Gallons:Standard municipal workhorse capacity balances pedestal foundation costs against pressure maintenance across neighborhood distribution loops.
- More than 10000 Gallons:Utility-scale concrete or composite structures integrate with regional transmission mains; hyperscale data centers in Virginia and Arizona specify redundant million-gallon pairs for cooling reliability.
1000 to 5000 gallon units move the highest unit volumes; above-10000 gallon contracts capture the steepest expansion trajectory.
Installation Method:
Construction approach determines timeline risk and geotechnical complexity in procurement evaluation.
- Above Ground:Surface-mounted steel tanks on grade beams dominate flat terrain applications with minimal excavation and rapid commissioning.
- In Ground:Buried concrete reservoirs preserve site aesthetics and thermal stability for sensitive industrial processes.
- Modular:Prefabricated panel systems enable rapid deployment in India's Jal Jeevan Mission rural schemes where skilled welder availability constrains field fabrication.
- Elevated:Structural pedestal mounting maintains hydraulic pressure without continuous pumping; this method defines the core market and commands premium engineering margins.
Elevated installation anchors the value pool; modular approaches are expanding most quickly in emerging procurement.
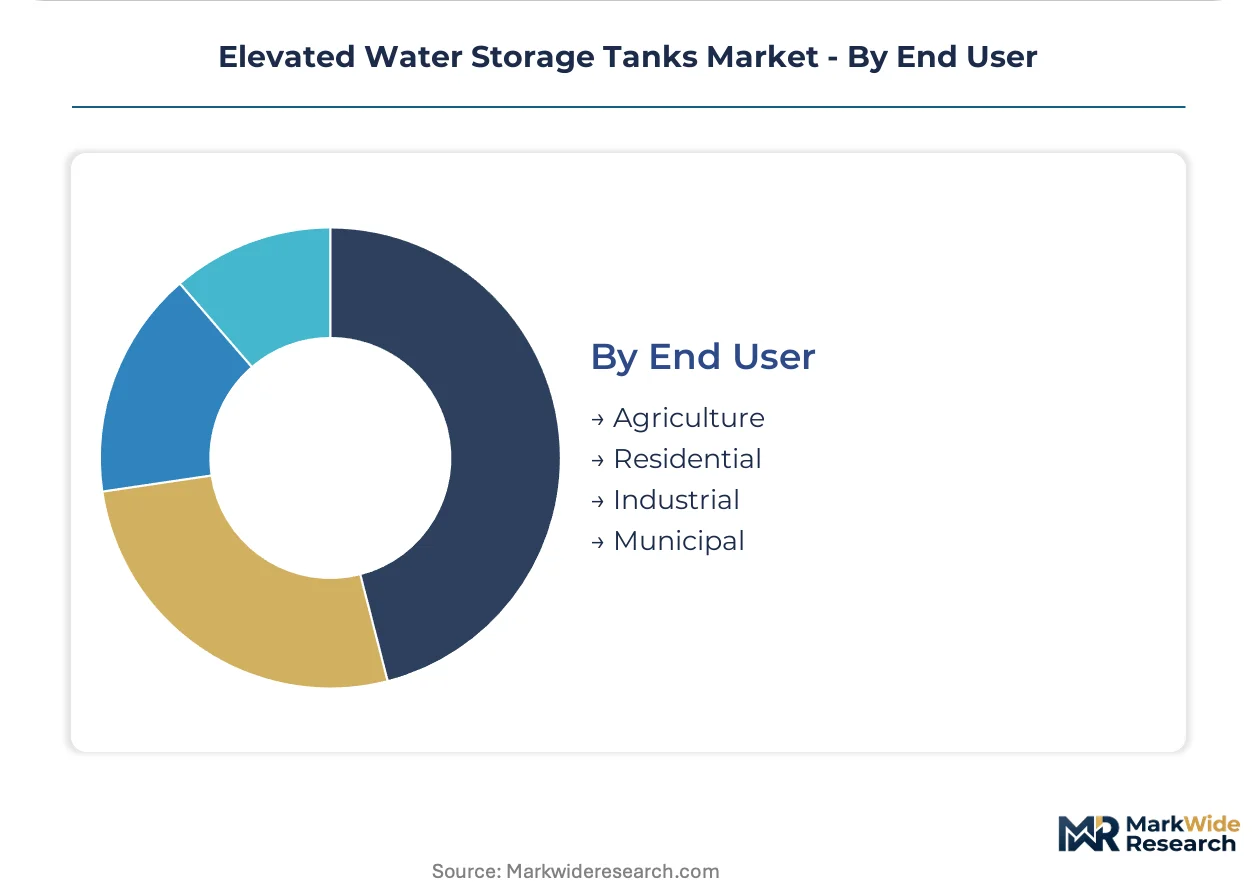
End User:
Customer type segmentation exposes diverging specification priorities between public infrastructure and private industrial reliability.
- Agriculture:Irrigation districts prioritize capital efficiency and seasonal drawdown cycles over seismic performance, favoring welded steel in grain belt states.
- Residential:Subdivision developers specify compact elevated tanks to meet pressure requirements without booster pump stations, particularly in exurban Sun Belt growth corridors.
- Industrial:Power generation and semiconductor fabrication demand redundant storage with zero-failure specifications; EPA cooling water regulations and process uptime requirements drive premium concrete pedestal procurement.
- Municipal:City utilities balance AWWA compliance, corrosion rehabilitation cycles, and ratepayer cost containment across aging distribution system inventories.
Municipal contracts handle the majority of throughput; industrial end users are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-diameter rolled plate forming concentrates among Gulf Coast and Midwest fabrication facilities, creating geographic bottlenecks during peak construction seasons. Municipal procurement patterns diverge sharply between seismic-critical zones and routine replacement markets. Regulatory fragmentation across national standards bodies shapes local specification requirements.
United States
Sun Belt population expansion strains aging distribution systems across Texas, Florida, and Arizona utilities. EPA Lead and Copper Rule revisions and AWWA D100 standards tighten material specifications for welded steel rehabilitation. Dallas-Fort Worth and Houston metropolitan clusters drive elevated tank procurement for suburban pressure maintenance without booster stations.
India
Jal Jeevan Mission rural water schemes generate thousands of elevated tank contracts across underserved districts. BIS certification requirements and domestic steel fabrication expansion fragment supply toward local fabricators. Gujarat and Maharashtra industrial corridors anchor modular prefabricated panel deployment where skilled welder availability constrains field fabrication.
Germany
Industrial process water reliability requirements tighten across power generation and chemical manufacturing sectors. REACH compliance and EU drinking water directives govern material traceability for all wetted surfaces. Rhine-Ruhr and Bavarian manufacturing clusters specify redundant concrete pedestal storage for zero-failure cooling water specifications.
China
Dual carbon goals and GB standards accelerate replacement of legacy coated steel inventories in older distribution systems. MIIT industrial water recycling mandates expand elevated storage procurement for captive treatment facilities. Yangtze River Delta municipalities prioritize seismic-resilient composite designs as urban density increases.
Japan
Updated seismic hazard maps and METI infrastructure resilience programs mandate mass-damped concrete pedestal replacement cycles. JIS standards govern prestressed tank design in high-hazard zones. Kanto and Kansai metropolitan utilities concentrate procurement toward engineered-to-order contracts with integrated geotechnical capabilities.
Elevated Water Storage Tanks Market Vendor Landscape
Integrated fabricators and specialized pedestal engineers split the market along seismic performance and speed-to-commissioning vectors. Tier concentration favors mid-scale regional players with AWWA D100 certification over fragmented local contractors. Two strategic archetypes dominate: legacy welded steel specialists with Gulf Coast plate-forming assets, and composite pedestal integrators capturing premium seismic-margin pools. Competitive moves center on backward integration into foundry operations and smart monitoring telemetry partnerships for predictive maintenance contracts.
Among legacy welded steel fabricators, CB&I and Caldwell Tanks occupy distinct positioning archetypes. CB&I represents the utility-scale reservoir specialist with large-diameter project legacy across Midwest municipal systems. Caldwell Tanks exemplifies the composite pedestal differentiator, anchoring seismic-resilient positioning in earthquake-prone zones. McWane Ductile sits within the backward-integrated foundry tier, competing through captive ductile iron supply chains.
| Leading Market Players |
|---|
| CB&I |
| McWane Ductile |
| Pittsburg Tank & Tower Group |
| DN Tanks |
| Superior Tank Co. |
| Caldwell Tanks |
| Phoenix Tank |
| Containment Solutions |
| Landmark Structures |
| Others |
Supply Flow & Price Mechanics
Hot-rolled coil price volatility determines both the spread between steel and concrete procurement tiers and the geographic clustering of fabrication capacity around Gulf Coast and Midwest plate-forming facilities. Municipal utilities face compressed bid accuracy on fixed-price contracts when coil fluctuations exceed project budgeting cycles, forcing specification shifts toward prestressed concrete where seismic codes permit.
Pricing Analysis
AWWA D100 dictates the pricing tier structure across welded steel fabrication, separating certified structural welder premiums from standard-grade municipal contracts. Three-tier pricing structure across premium seismic-rated, standard AWWA-compliant, and economy rehabilitation levels reflects certification depth and after-sales telemetry bundling. Cost compression in economy-tier steel rehabilitation is intensifying because EPA lead-free material mandates disqualify legacy coated inventories. Small rural water districts exhibit the highest price sensitivity, while hyperscale data center operators prioritize zero-failure specifications over capital cost.
Supply Chain Analysis
Hot-rolled coil feedstock draws from integrated steel mills in the United States, India, and China, with domestic plate forming concentrated in Gulf Coast and Midwest facilities. Rolled carbon steel plate, prestressed concrete strand, and GRP lining systems anchor material inputs. Single-source vulnerability concentrates in large-diameter plate forming capacity, where fewer than ten facilities handle tanks exceeding fifty-foot diameters. Distribution runs through municipal procurement officers and EPC contractors bidding design-build contracts, with industrial buyers increasingly sourcing direct for bundled water treatment integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal buyer consolidation through regional water authority mergers is shifting procurement leverage toward larger contract volumes and outcome-based specifications, fragmenting awards toward integrated fabricators with captive engineering capabilities.
For Market Incumbents: Build engineering-to-order moats around seismic resilience certification and in-house geotechnical capabilities. CB&I and Caldwell Tanks anchor positioning through large-diameter legacy assets and composite pedestal expertise respectively. Threat from modular prefabricated panel entrants in India's Jal Jeevan Mission demands backward integration into foundry operations or smart monitoring telemetry partnerships. Capacity addition in Gujarat and Maharashtra industrial corridors secures BIS-certified supply chain control for rural contract capture. For New Entrants and Emerging Players: Establish a beachhead in India's Jal Jeevan Mission rural schemes where domestic fabrication capacity expansion fragments procurement toward BIS-certified local players. Modular prefabricated panel deployment in water-stressed districts of Gujarat offers the most penetrable white space, with skilled welder scarcity constraining incumbent field fabrication. Partner with state water boards on performance-based specifications to bypass legacy design-bid-build procurement barriers. For Investors and Strategic Acquirers: EPA Lead and Copper Rule revisions reshape the acquisition landscape toward fabricators with mill certification traceability and lead-free coating application capabilities. Long-term viability hinges on exposure to industrial microgrid bundling and predictive maintenance telemetry recurring revenue. Target mid-scale regional players with AWWA D100 certification and underdeveloped smart monitoring portfolios. Monitor USGS seismic zone reclassification announcements as the signal for concrete pedestal demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | McWane Ductile's captive ductile iron supply secures margin control against steel price volatility. |
| Smart Monitoring Telemetry Partnership | IoT corrosion sensor integration opens recurring revenue streams for predictive maintenance contracts. |
| Performance-Based Specification Adoption | California Department of Water Resources templates transfer seismic risk to EPC contractors with engineering depth. |
| Modular Prefabricated Panel Deployment | Jal Jeevan Mission rural schemes in Gujarat bypass skilled welder constraints through factory fabrication. |
| Seismic Resilience Certification Investment | Updated USGS hazard maps in the Intermountain West mandate mass-damped concrete pedestal premiums. |
Methodological Framework
A spread of perspectives from municipal utility procurement officers, AWWA D100-certified structural welders, EPC contract managers, and state water board engineers converged on the working assumptions for demand segmentation and replacement cycle timing. Secondary validation drew from EPA Safe Drinking Water Act amendments, AWWA standards documentation, Jal Jeevan Mission technical specifications, USGS seismic hazard map revisions, and municipal bond issuance disclosures for water infrastructure. Bottom-up tank inventory age analysis triangulated against top-down municipal capital expenditure forecasts.
Demand-supply balance framing anchored the analytical approach across the analysis window, modeling municipal replacement cycles against fabrication capacity constraints and raw material lead times. Segmentation dimensions included tank material type, capacity tier, installation method, and end-user category, with regional regulatory cluster variations for seismic zone reclassifications. CAGRs were derived from replacement pipeline quantification and industrial demand elasticity for process water reliability. Forecast inputs incorporated hot-rolled coil price trajectory assumptions and welder certification pipeline replenishment rates.
Stress conditions across steel price volatility bands, seismic zone reclassification timing, and Jal Jeevan Mission contract award velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding corrosion failure acceleration rates and EPA enforcement timeline interpretation. Cross-checking against municipal bond prospectus infrastructure disclosure and state water development board capital improvement plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Sectional Door Market
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Quarry Tiles Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Glass Tiles Market