

Residential Energy Efficient Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Energy Efficient Windows Market Insights
Modular window-wall systems bundling glazing, framing, and installation services is rebalancing buyer choice toward turnkey solutions rather than component sourcing. Andersen Corporation leverages its captive distribution network to control channel economics across North American retrofit demand. Pella Corporation sustains R&D intensity in smart-window interfaces that integrate with residential automation platforms. Saint-Gobain anchors European supply through backward integration into float glass and specialized coatings production.
Residential energy efficient windows are fenestration assemblies engineered with multiple glazing layers, inert gas fills, and low-emissivity coatings to minimize thermal transmittance, typically achieving U-values below 1.0 W/m²K in triple-glazed configurations. Their primary purpose is reducing HVAC energy consumption in dwellings while maintaining visible light transmission and acoustic comfort. Triple Glazing and Low-E Glass command premium positioning where building codes mandate stringent thermal performance, while Vacuum Insulated Glass represents the fastest-growing technology segment as manufacturers resolve sealing durability at scale. New Construction and Renovation applications split demand unevenly, with renovation pulling ahead in mature housing stocks across Western Europe and the northeastern United States where window replacement cycles compress under efficiency mandates.
EPA ENERGY STAR certification and DOE Zero Energy Ready Home standards shape product eligibility and rebate access in the United States, while the EU Green Deal and national building renovation passports in France and Germany mandate performance thresholds for replacement windows. FERC demand-response programs and state-level utility incentives further condition purchase timing and technology selection for homeowners. Stakeholders must monitor evolving code harmonization between federal efficiency standards and local net-zero ordinances to anticipate where specification requirements will tighten next.
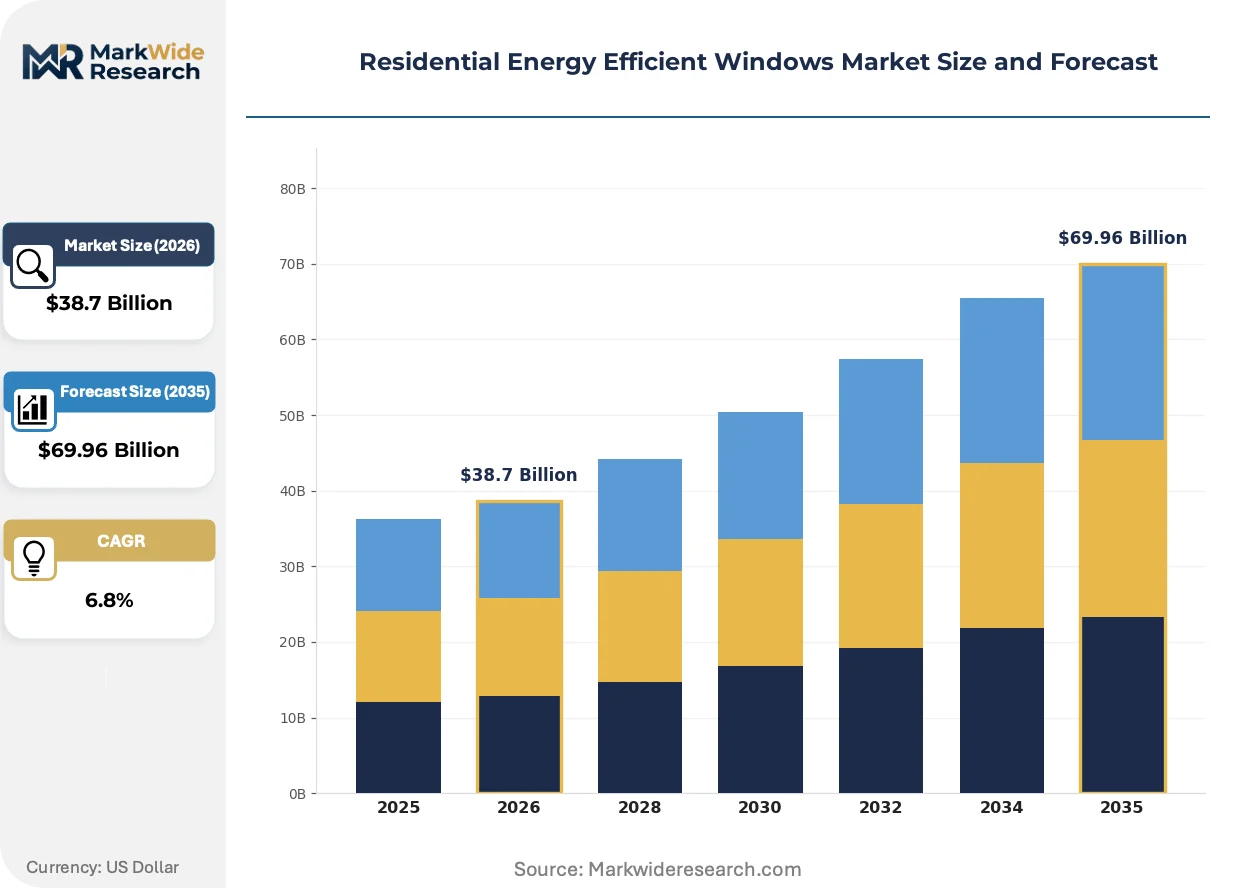
Market Dynamics
Building energy codes in Germany, the United States, and Japan are compressing replacement cycles and forcing specification upgrades across single-family and multi-family housing segments. These regulatory pressures are rebalancing procurement toward turnkey window-wall systems that bundle glazing, framing, and installation services.
Growth Catalysts
- Net-zero building mandates:Germany's building renovation passports and France's RE2020 thermal regulations mandate performance thresholds that accelerate premium window adoption in retrofit applications.
- Utility demand-response programs:FERC-authorized state-level incentives in the northeastern United States condition purchase timing toward high-efficiency glazing that qualifies for peak-load reduction credits.
- Triple-glazing technology maturation:Vacuum Insulated Glass manufacturing scale-up in Japanese industrial clusters is resolving sealing durability constraints and opening residential cost parity with conventional triple-pane units.
Market Restraints
- Float glass supply concentration:European flat glass production clusters in Belgium and northern France create input cost volatility exposure for independent window fabricators lacking captive supply.
- Technical limitation in vacuum sealing:Vacuum Insulated Glass edge-seal longevity under thermal cycling remains unproven beyond 15-year warranties, constraining lender financing for residential installations.
- Regulatory friction from fragmented codes:Non-harmonized municipal net-zero ordinances across California, New York, and Massachusetts multiply SKU complexity for national distributors.
Strategic Opportunities
- Underpenetrated multi-family stock:Post-war rental housing in the Netherlands and Denmark presents concentrated retrofit potential where window replacement rates lag single-family penetration by 40 percentage points.
- Smart-window convergence:Integration of electrochromic glazing with residential automation platforms creates premium positioning for technology-forward installers serving custom home builders.
- IRA residential efficiency credits:The Inflation Reduction Act's 30% tax credit for qualified window replacements is pulling forward demand timing in Midwestern states with aging housing stock.
Industry Challenges
- Installation skill scarcity:Certified window-wall system installers are concentrated in coastal metropolitan markets, creating service gaps in secondary cities where code enforcement is tightening.
- Certification timeline compression:EPA ENERGY STAR Version 7.0 testing protocols require third-party validation cycles that delay product launches by 8-12 months relative to prior standards.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Energy Efficient Windows Market Trends and Innovations
Vacuum Insulated Glass manufacturing is resolving production bottlenecks that previously constrained residential adoption. Three interconnected developments are reshaping how windows are specified, procured, and installed.
Thin-film low-emissivity coatings applied to inner glass surfaces are consolidating thermal performance leadership in cold-climate markets. Custom home builders in Minnesota and Wisconsin specify these coatings to meet Passive House U-value requirements without triple-pane weight penalties. The technology is consolidating specification authority away from framing manufacturers toward coating specialists with proprietary sputtering equipment.
The EU Green Deal's building renovation targets are forcing national regulators to align disparate member-state efficiency standards. France's RE2020 and Germany's GEG 2024 now reference common thermal transmittance calculations, reducing compliance fragmentation for cross-border window suppliers. Nordic markets are responding fastest, with Denmark mandating window replacement at property transfer to meet 2030 stock renovation goals.
Homeowner buying patterns are fragmenting across channel types. Big-box retailers capture volume replacement demand in sunbelt states with mild code enforcement, while certified contractor networks dominate specification-driven markets in the Pacific Northwest. This bifurcation is compressing distributor margins in intermediary geographies where neither channel achieves scale dominance.
Residential Energy Efficient Windows Market Segmentation
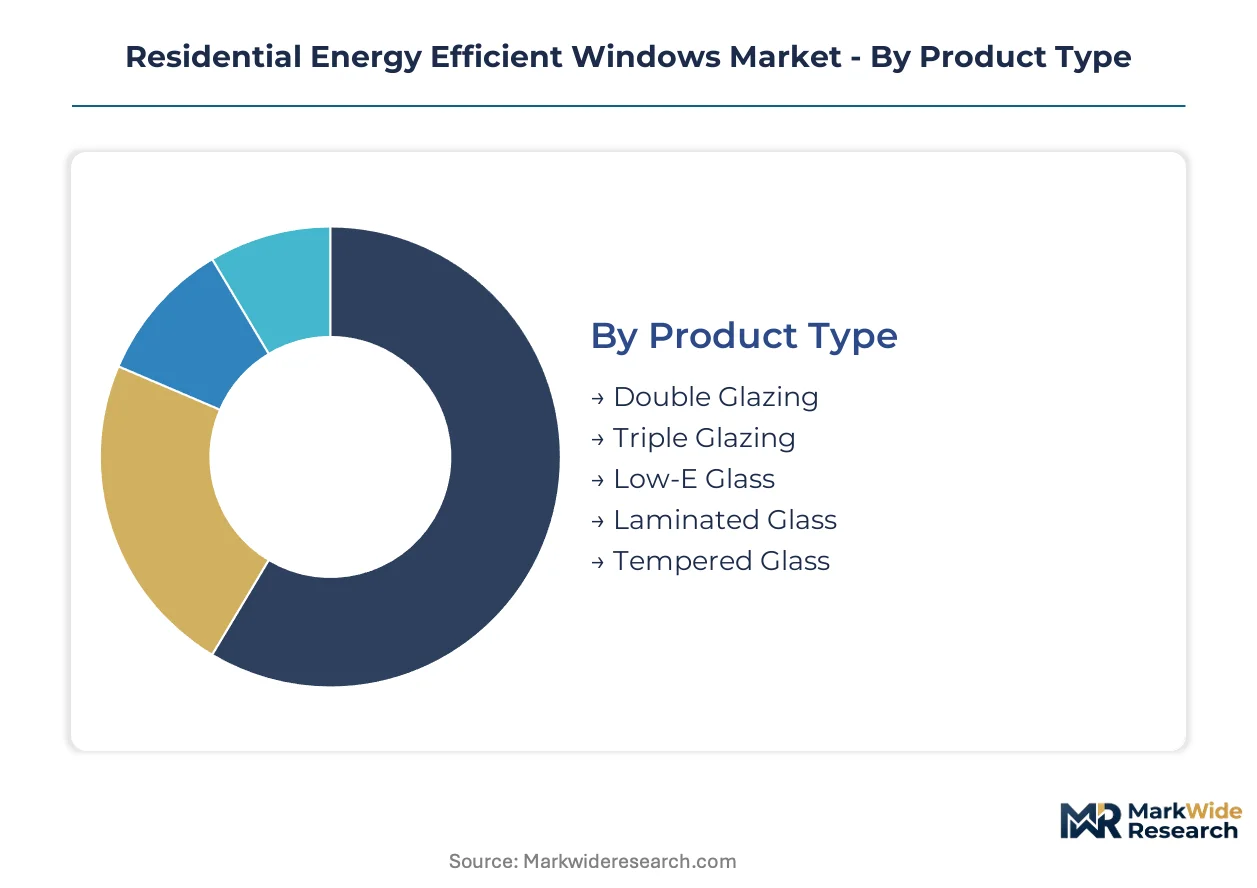
Window specification varies sharply across building types, regulatory climates, and owner priorities. Procurement patterns in this market split along four axes: product configuration, glazing technology, project timing, and buyer economics. Each dimension carries distinct margin profiles and certification requirements that reshape competitive positioning.
Product Type:
Supply of float glass and specialized coatings concentrates among integrated manufacturers with captive melting capacity, tilting procurement power toward backward-integrated fabricators.
- Double Glazing:Two-pane assemblies with air or gas-filled cavities remain the volume baseline in mild-climate markets. Demand concentrates in sunbelt states where code enforcement lags and replacement cycles stretch longest.
- Triple Glazing:Three-pane configurations with dual low-E coatings achieve U-values below 0.8 W/m²K. Scandinavian and German residential construction mandates this specification for Passive House compliance, compressing replacement cycles to 20-year intervals.
- Low-E Glass:Thin-film metallic coatings on inner surfaces reduce radiant heat transfer. Minnesota and Wisconsin custom builders specify these for thermal performance without triple-pane weight penalties.
- Laminated Glass:Polyvinyl butyral interlayers bond glass plies for acoustic dampening and impact resistance. Coastal Florida and Gulf Coast markets prioritize this for hurricane code compliance.
- Tempered Glass:Heat-strengthened safety glazing shatters into granular fragments. California Title 24 mandates this for operable windows above ground level.
Double Glazing commands volume leadership in replacement markets. Triple Glazing gains specification authority fastest where building codes tighten.
Technology:
Cost tiering across technology segments separates premium electrochromic systems from commodity gas-filled units, with vacuum insulation occupying an emerging mid-premium position.
- Vacuum Insulated Glass:Micron-scale evacuated cavities eliminate gas conduction. Japanese industrial clusters are resolving edge-seal durability constraints to unlock residential cost parity with conventional triple-pane units.
- Gas Filled Insulation:Argon or krypton injection between panes suppresses convective heat transfer. This mature technology dominates mid-market replacement volume across the northeastern United States.
- Solar Control Coating:Spectrally selective films block infrared while transmitting visible light. Arizona and Nevada desert markets specify these for peak-load reduction under utility demand-response programs.
- Thermochromic Glass:Temperature-responsive glazing darkens automatically to reduce solar gain. Early adoption concentrates in high-end custom homes where automation integration justifies premium pricing.
- Electrochromic Glass:Voltage-tinted windows integrate with residential control platforms. Pella Corporation and smart-home installers target this segment for technology-forward custom builders.
Gas Filled Insulation anchors current volume. Vacuum Insulated Glass climbs the fastest as manufacturing scale resolves prior bottlenecks.
Application:
Volume distribution across application types reflects housing stock age and code enforcement intensity, with renovation pulling ahead in mature Western European and northeastern US markets.
- New Construction:Window-wall systems specified at design phase achieve tightest thermal bridging control. Germany's GEG 2024 mandates net-ready performance thresholds that compress specification windows.
- Renovation:Replacement cycles in post-war housing stocks accelerate under efficiency mandates. France's building renovation passports trigger window upgrades at property transfer.
- Retrofit:In-situ glazing upgrades without full frame replacement reduce labor costs. Netherlands rental housing cooperatives deploy this for cost-constrained multi-family stock.
- Smart Homes:Electrochromic and connected glazing integrates with automation platforms. Premium positioning targets custom builders in Pacific Northwest tech corridors.
- Passive Houses:Ultra-low U-value specifications below 0.6 W/m²K demand triple-glazing with thermally broken frames. Certification requirements in Germany and Austria concentrate demand among specialized fabricators.
Renovation leads current demand. Smart Homes show steepest expansion trajectory as automation penetration deepens.
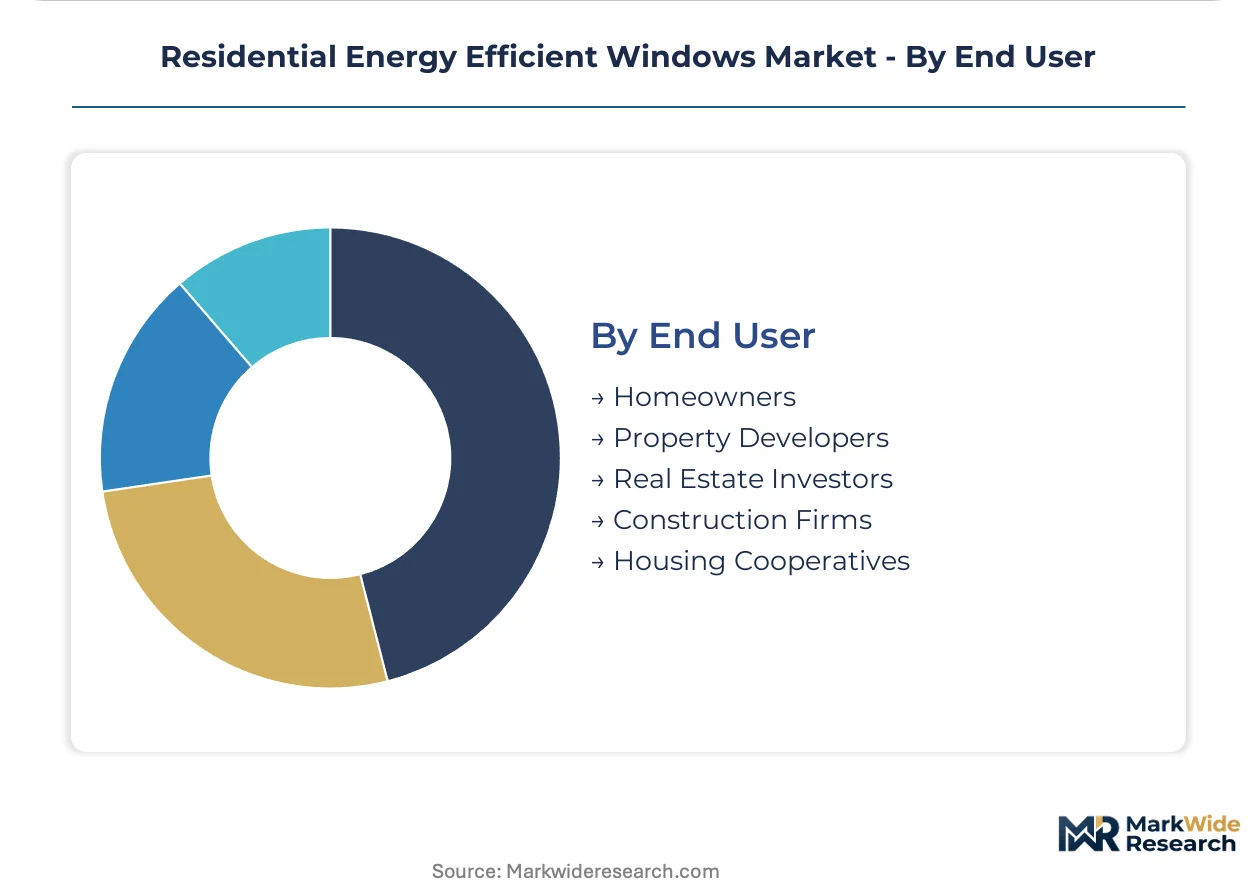
End User:
Customer type determines procurement channel and specification authority, with property developers and housing cooperatives commanding volume discounts unavailable to fragmented homeowners.
- Homeowners:Individual purchasers respond to utility rebates and tax credits. IRA residential efficiency credits pull forward replacement timing in Midwestern states with aging stock.
- Property Developers:Multi-unit builders achieve scale economics through standardized specifications. Denmark mandates window replacement at property transfer, concentrating developer procurement.
- Real Estate Investors:Institutional owners prioritize rapid payback periods for efficiency upgrades. Netherlands post-war rental stock presents concentrated retrofit potential.
- Construction Firms:General contractors source through certified installer networks where code enforcement is strictest. Skill scarcity in secondary cities creates service gaps.
- Housing Cooperatives:Collective decision-making in multi-family structures slows procurement but unlocks volume pricing. Copenhagen and Amsterdam cooperatives lag single-family penetration by substantial margins.
Property Developers dominate volume flows. Housing Cooperatives represent the most underpenetrated structural opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Float glass production scaled first in Belgium and northern France during the 1960s, establishing European supply dominance that persists in today's window fabrication networks. German and Japanese industrial clusters later pioneered low-emissivity coating technologies that now define thermal performance standards across temperate climate zones.
United States
Retrofit demand concentrates in Midwestern states with post-war housing stock aging past 50-year replacement cycles. The Inflation Reduction Act's residential efficiency credits accelerate upgrade timing where FERC-authorized utility programs offer peak-load reduction incentives. Andersen Corporation's captive distribution network controls channel economics across northeastern metropolitan markets.
Germany
Passive House certification mandates compress window replacement intervals to 20-year cycles in single-family construction. The Building Energy Act (GEG 2024) imposes net-ready performance thresholds that eliminate double-glazing from new specifications. Bavarian fabricators specialize in thermally broken frames meeting U-values below 0.6 W/m²K.
Japan
Vacuum Insulated Glass manufacturing clusters in Aichi and Kanagawa prefectures are resolving edge-seal durability constraints for residential cost parity. METI efficiency standards for net-zero buildings drive specification upgrades in Tokyo and Osaka metropolitan housing stocks. YKK AP anchors domestic supply through backward integration into aluminum extrusion and coating production.
France
Building renovation passports trigger mandatory window upgrades at property transfer under RE2020 thermal regulations. Demand concentrates in Île-de-France and Auvergne-Rhône-Alpes where post-war multi-family stock exceeds single-family penetration by substantial margins. Saint-Gobain's float glass and specialized coatings production anchors European supply security.
Netherlands
Rental housing cooperatives in Amsterdam and Rotterdam present underpenetrated retrofit potential where window replacement rates lag single-family markets by 40 percentage points. EU Green Deal renovation targets mandate efficiency improvements at scale for post-war social housing stock. Eindhoven-region fabricators supply cost-constrained in-situ glazing upgrades without full frame replacement.
Residential Energy Efficient Windows Market Competitive Landscape
The competitive structure tilts toward integrated manufacturers with captive float glass supply and captive distribution networks controlling channel economics. Three archetypes dominate: backward-integrated glass producers commanding input cost advantages, specialized fabricators with certified installer networks, and technology-forward developers of smart-window interfaces. Consolidation pressure intensifies as national building codes harmonize and SKU complexity multiplies compliance costs for mid-scale distributors.
Among North American fabricators, Andersen Corporation and Pella Corporation occupy positions at opposite ends of the technology spectrum. Andersen exemplifies the distribution-integrated archetype through its captive installer network controlling retrofit channel economics. Pella represents the innovation-focused tier with sustained positioning in smart-window interfaces. Saint-Gobain anchors European competitive dynamics as a backward-integrated glass producer with captive supply of float glass and specialized coatings.
| Leading Market Players |
|---|
| Andersen Corporation |
| Pella Corporation |
| Marvin Windows and Doors |
| JELD-WEN |
| Saint-Gobain |
| YKK AP |
| Deceuninck |
| Nippon Sheet Glass |
| AGC Inc. |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal building renovation targets gate qualified supply and premium-tier pricing access by mandating certified fabricators for rebate-eligible installations, compressing margin capture toward backward-integrated producers with captive float glass capacity while independent distributors face cost pass-through limitations from Belgian and northern French production clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Passive House-certified triple-glazing from ENERGY STAR baseline units and big-box retail double-pane replacements. Price differentiation rests on thermal performance certification and installation service bundling. Cost compression in the standard tier intensifies because independent fabricators lack captive glass supply. Homeowners in sunbelt states exhibit highest price sensitivity, while German single-family builders show lowest sensitivity due to GEG 2024 compliance mandates.
Supply Chain Analysis
Reverse-logistics flows for vacuum-insulated glass edge-seal refurbishment remain underdeveloped, creating end-of-life liability concentration with original manufacturers. Primary production draws from Belgium, northern France, and Japan for float glass and specialized coatings. Raw material dependencies center on soda ash, low-emissivity sputtering targets, and argon gas supplies. Single-source vulnerability runs through European flat glass production clusters. Distribution runs through captive installer networks in strict-code markets and big-box retail in enforcement-lax regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where German and Japanese regulatory stringency creates 40-point penetration gaps versus Dutch multi-family cooperatives, enabling cost-efficient capacity deployment into underenforced jurisdictions before code harmonization closes the window.
For Market Incumbents: To counter vacuum-insulated glass manufacturing scale-up by Japanese industrial clusters, deepen backward integration into float glass production and secure captive low-emissivity coating capacity. Prioritize certification investment for EPA ENERGY STAR Version 7.0 pre-approval to compress competitor launch timelines by 8-12 months. For New Entrants and Emerging Players: Certified installer networks in secondary US cities present the most penetrable channel gap, where skill scarcity has created service voids under tightening municipal net-zero ordinances. Target Netherlands housing cooperatives with cost-constrained in-situ glazing upgrade solutions that bypass full frame replacement labor costs. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale distributors lacking captive supply or certified installer networks, as SKU complexity from fragmented municipal codes multiplies compliance costs. Acquisition focus should center on fabricators with thermally broken frame specialization for Passive House thresholds. Monitor FERC demand-response program expansion across Midwestern states as inflection signal for retrofit demand timing acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Float Glass | Captive supply from Belgian and northern French production clusters insulates margin compression from input cost volatility. |
| Smart-Window Platform Integration | Electrochromic glazing interfaces with residential automation platforms command premium positioning in Pacific Northwest tech corridors. |
| Certified Installer Network Expansion | Service coverage in secondary cities addresses skill scarcity gaps under tightening municipal net-zero enforcement. |
| Vacuum Insulated Glass Scale-Up | Japanese industrial clusters resolving edge-seal durability constraints unlock residential cost parity with triple-pane units. |
| Building Renovation Passport Alignment | France and Germany regulatory harmonization reduces SKU complexity for cross-border window suppliers. |
Research Methodology
Bottom-up housing stock modeling reconciled against top-down float glass production tracking forms the analytical core. Primary interviews with window fabricator procurement directors, certified installer network managers, housing cooperative decision-makers, and municipal code enforcement officers combined with secondary validation from EPA ENERGY STAR certification databases, EU Green Deal implementation reports, FERC demand-response program filings, and national building energy code repositories. Triangulation between end-use demand signals and supply-side capacity announcements anchors volume estimates.
Historical trendline analysis of replacement cycle compression under efficiency mandates informs the projection framework. Segmentation dimensions span glazing technology tier, application timing, end-user archetype, and regional regulatory enforcement intensity. CAGRs derive from fitted growth curves calibrated to documented code adoption trajectories and utility incentive program budgets. Forecast inputs incorporate housing stock age demographics and net-zero building mandate implementation schedules without year-specific anchoring.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to vacuum-insulated glass edge-seal warranty extension beyond 15 years and harmonization progress between federal efficiency standards and local net-zero ordinances. Practitioners should monitor EPA ENERGY STAR Version 7.0 testing protocol adoption rates and IRA residential efficiency credit utilization thresholds for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.