
 Cultured Marble Market | 2026-2036
Cultured Marble Market Size, Share, and Industry Trends Forecast 2026-2036
Cultured Marble Market Outlook
The capital-intensity gap between large-format slab producers and small-batch vanity fabricators is collapsing as automated casting systems reduce minimum efficient scale. DuPont leverages its resin chemistry expertise to sustain premium positioning in solid surface adjacent categories. Rynone Manufacturing anchors its competitiveness through dedicated vanity production lines serving mid-Atlantic residential contractors. International Marble LLC differentiates via specialized shower wall systems for hospitality retrofit channels.
Cultured marble denotes a cast polymer composite comprising crushed natural marble filler suspended in unsaturated polyester resin, thermoset into molds under controlled temperature and pressure to yield non-porous, seam-integrated surfaces. The material serves primarily as a cost-efficient alternative to quarried stone in wet-environment applications where moisture resistance and uniform appearance outweigh premium aesthetics. Vanities dominate current volume through standardized sizing that minimizes fabrication waste, while shower walls represent the fastest-expanding product category as unitized panel systems reduce on-site labor. The residential end-user segment commands the largest revenue pool, though hospitality applications yield superior per-project margins due to bulk procurement and brand-specified finish requirements.
EPA regulations on styrene emissions from polyester resin curing operations constrain facility siting and capital allocation for domestic manufacturers. OSHA silica standards affect raw material handling protocols throughout the supply chain, elevating compliance costs for smaller fabricators lacking enclosed material processing systems. California Air Resources Board protocols on volatile organic compound content in composite materials create additional formulation constraints for products distributed in that state. Stakeholders must monitor evolving state-level chemical disclosure mandates and assess whether reformulation investments or geographic market prioritization delivers superior risk-adjusted returns.
Market Dynamics
Automated casting systems are collapsing the minimum efficient scale threshold, eroding the historical capital barrier that protected large-format slab producers from vanity-focused fabricators and redistributing competitive advantage toward operational flexibility.
Growth Catalysts
- Residential bathroom renovation cycles:Housing stock turnover in Florida and California sustains replacement demand for wet-environment surfaces. Contractors favor standardized vanity dimensions that reduce on-site cutting and installation labor.
- EPA styrene emission protocols:Compliance investments by incumbent manufacturers create capacity constraints that favor well-capitalized producers able to fund enclosed curing systems and air filtration infrastructure.
- Unitized shower panel systems:Prefabricated wall assemblies cut installation time by half versus tile-and-grout methods, accelerating adoption among hospitality retrofit contractors facing compressed project timelines.
Market Restraints
- Unsaturated polyester resin price volatility:Petrochemical feedstock fluctuations compress margins for producers lacking long-term supply contracts or backward integration into resin chemistry.
- Quarried stone substitution threat:Engineered quartz and sintered stone surfaces capture premium residential segments with superior hardness and thermal resistance, limiting cultured marble's price ceiling.
- OSHA silica handling mandates:Raw material processing requirements elevate compliance costs for small-batch fabricators without enclosed crushing and mixing systems, accelerating consolidation.
Strategic Opportunities
- Aging-in-place bathroom modifications:Medicare-adjacent renovation programs and ADA-compliant grab-bar integration create specification pull for seamless, non-porous shower surrounds in residential retrofit.
- California Air Resources Board VOC protocols:Low-emission formulation mandates favor domestic producers with reformulation capabilities over imports lacking compliant resin systems, creating geographic shelter.
- Direct-to-contractor digital platforms:Configurator tools enabling real-time vanity dimension customization bypass traditional distributor markups and compress order-to-delivery cycles for mid-Atlantic residential builders.
Industry Challenges
- Casting technician skill scarcity:Thermoset mold operation and gel-coat finishing expertise concentrates among aging workforces in legacy manufacturing regions, constraining capacity expansion.
- Multi-jurisdiction chemical disclosure alignment:Divergent state-level ingredient reporting requirements force redundant testing and labeling investments for products distributed across Florida, California, and mid-Atlantic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cultured Marble Market |
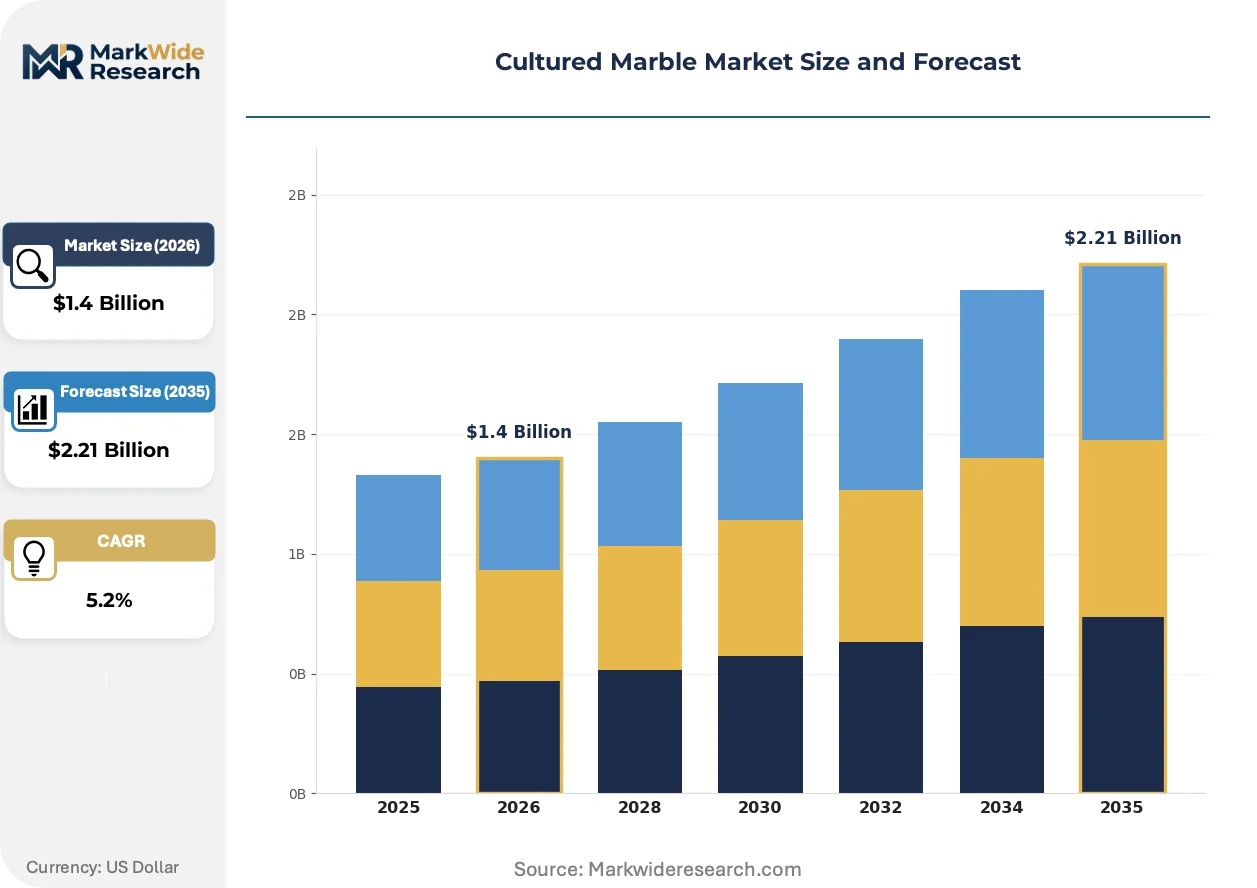
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vanities, Sinks, Shower Walls, Countertops End User: Residential, Commercial, Hospitality, Healthcare Distribution Channel: Online, Retail, Wholesale, Direct Sales Application: Bathroom, Kitchen, Flooring, Walls |
| Companies Covered | Caesarstone, Silestone, DuPont, International Marble LLC, Kuraray, LX Hausys, Cambria, Rynone Manufacturing, Lotte Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cultured Marble Market Strategic Shifts
Digital fabrication workflows and resin chemistry advances are compressing product development cycles while regulatory fragmentation across state environmental agencies forces geographic specialization in formulation strategies.
Closed-mold injection systems are fragmenting the traditional open-casting production model. Hospitality contractors in Florida now specify unitized shower surrounds fabricated through pressure-assisted casting, which yields denser, more uniform surfaces than atmospheric curing. The technology is fragmenting regional supply bases by enabling smaller fabricators to match large producers' surface quality without comparable capital investment.
California Air Resources Board VOC content rules are forcing reformulation of unsaturated polyester resin systems for products entering that state. Manufacturers must either maintain dual inventory streams or absorb higher raw material costs for low-styrene alternatives. Shower wall panels face the tightest compliance burden due to their larger surface area-to-weight ratio and corresponding emission calculations.
Contractor procurement through integrated design-build firms is compressing traditional distributor channels. Mid-Atlantic residential developers now source vanities directly from fabricators offering BIM-compatible specification libraries, bypassing wholesale intermediaries. Florida's hospitality refurbishment sector exhibits the most advanced disintermediation, with major hotel chains maintaining approved manufacturer lists and negotiating master service agreements that lock in volume pricing across multi-property rollouts.
Cultured Marble Market Segmentation
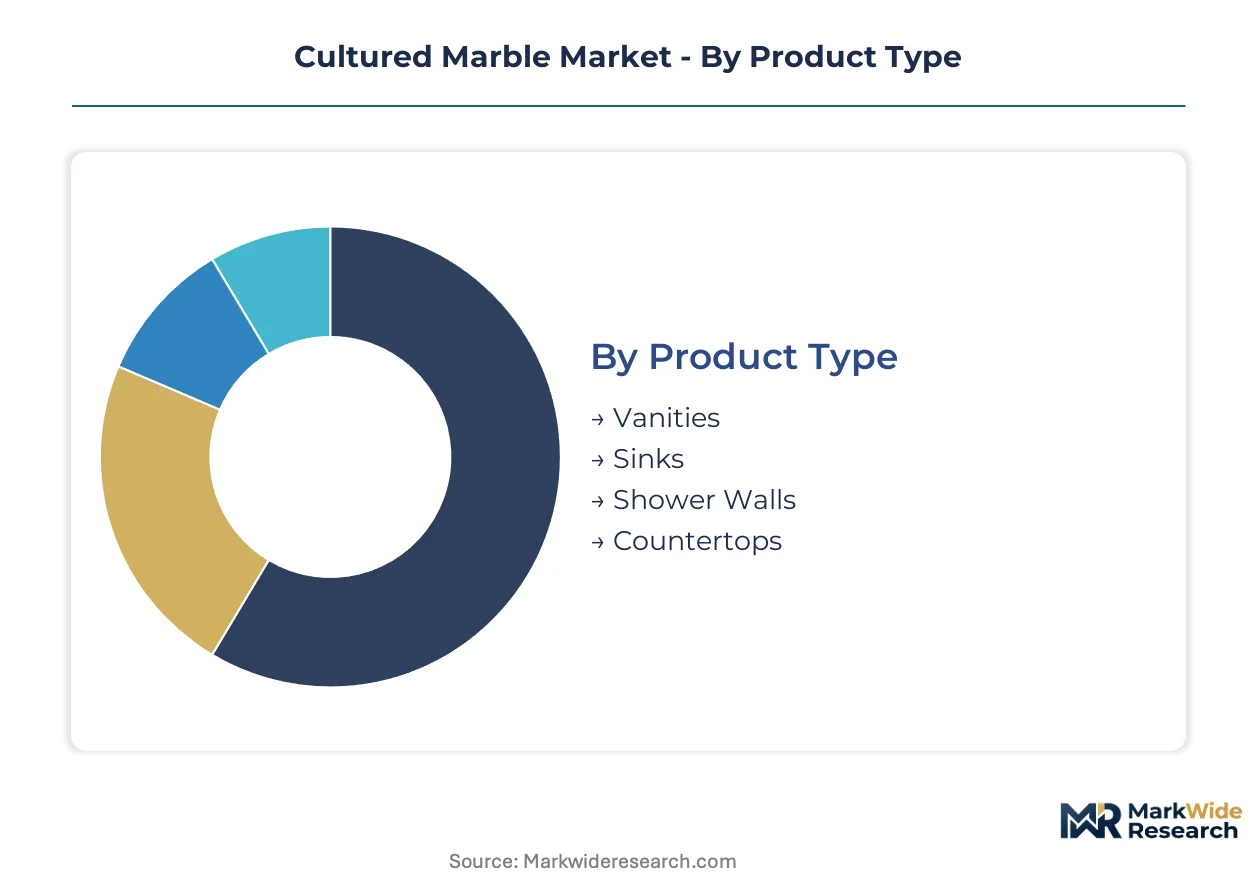
Cultured marble's cast polymer chemistry enables specification across multiple surface categories, but channel economics and installation labor requirements fragment demand patterns. Understanding which segments flow through contractor-direct versus retail pathways determines margin capture and inventory positioning for manufacturers.
Product Type:
Channel mix varies sharply by product complexity, with standardized dimensions favoring wholesale distribution and custom sizing requiring direct contractor relationships.
- Vanities:Pre-cast basin and countertop assemblies in standardized widths dominate volume through distributor relationships with residential contractors. Florida and California housing turnover sustains replacement demand for 31-inch and 43-inch nominal widths that minimize on-site cutting.
- Shower Walls:Unitized panel systems fabricated through pressure-assisted casting yield denser surfaces than atmospheric curing. Hospitality retrofit contractors in Florida specify these for compressed project timelines, with CARB-compliant formulations required for California distribution.
- Sinks:Integrated bowl-and-deck configurations serve mid-market residential bathrooms through retail home improvement channels.
- Countertops:Larger surface areas face substitution pressure from engineered quartz in premium residential segments, limiting cultured marble to cost-sensitive renovations.
Vanities dominate installed base. Shower walls are where expansion concentrates.
End User:
Margin structure inverts across customer types, with bulk procurement compressing per-unit returns while fragmented residential demand sustains pricing power.
- Residential:Individual homeowners and small-scale contractors drive volume through replacement cycles in aging housing stock, particularly in Florida's coastal markets where moisture resistance outweighs premium aesthetics.
- Hospitality:Hotel chains negotiate master service agreements locking in volume pricing across multi-property rollouts, yielding superior per-project margins through brand-specified finish requirements and bulk procurement.
- Commercial:Office and institutional specifications favor durability certifications that cultured marble struggles to match against sintered stone alternatives.
- Healthcare:ADA-compliant grab-bar integration and seamless, non-porous surfaces create specification pull for Medicare-adjacent bathroom modifications in residential retrofit applications.
Residential commands volume share. Hospitality delivers margin concentration.
Distribution Channel:
Digital procurement tools are compressing traditional markups, with configurators enabling real-time dimension customization that bypasses wholesale intermediaries.
- Wholesale:Distributor networks serving mid-Atlantic residential contractors remain the primary path for standardized vanity dimensions that reduce on-site labor.
- Direct Sales:Fabricators with BIM-compatible specification libraries capture mid-Atlantic residential developers, disintermediating traditional channels through integrated design-build firm relationships.
- Retail:Home improvement centers serve DIY renovation segments with limited customization and higher per-unit margins for manufacturers.
- Online:Configurator platforms compress order-to-delivery cycles, though dimensional accuracy requirements limit adoption to simpler product configurations.
Wholesale retains volume dominance. Direct sales channels are climbing the fastest.
Application:
Wet-environment performance characteristics concentrate demand in moisture-exposed locations where uniform appearance and non-porous surfaces justify material selection.
- Bathroom:Vanities and shower surrounds constitute the core specification, with EPA styrene emission protocols favoring well-capitalized producers able to fund enclosed curing systems for compliant resin operations.
- Walls:Vertical installations in hospitality settings leverage unitized panel systems that cut installation time versus tile-and-grout methods, particularly in Florida refurbishment cycles.
- Kitchen:Thermal resistance limitations and hardness deficiencies relative to engineered quartz restrict adoption to budget-sensitive renovation segments.
- Flooring:Load-bearing requirements and abrasion resistance standards largely exclude cultured marble from this category.
Bathroom anchors specification share. Wall applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Florida and California where housing turnover accelerates replacement cycles, while mid-Atlantic contractors absorb margin compression through distributor-dependent procurement channels. This geographic asymmetry shapes manufacturer capacity allocation and regulatory compliance investment priorities.
United States
Florida's coastal housing stock sustains vanity replacement demand through moisture-driven renovation cycles, while California's hospitality refurbishment sector drives shower wall panel specifications. EPA styrene emission protocols constrain facility siting in both states, elevating capital requirements for enclosed curing systems. Tampa and Orlando manufacturing clusters concentrate production capacity serving southeastern residential contractors.
Canada
Ontario's residential construction sector generates steady demand for standardized vanity dimensions through distributor relationships with Toronto-area builders. Health Canada chemical exposure guidelines align with OSHA silica handling standards, streamlining compliance for cross-border manufacturers. The Greater Toronto Area hosts fabrication capacity serving both domestic renovation and export markets.
Germany
Baden-Württemberg's precision manufacturing tradition supports specialized casting equipment production for export to North American fabricators. REACH chemical registration requirements impose formulation documentation burdens on resin system suppliers. Stuttgart-area industrial clusters develop pressure-assisted casting technologies adopted by hospitality-focused producers.
China
Guangdong Province's resin chemistry base supplies unsaturated polyester feedstock to global cultured marble manufacturers, though domestic demand remains limited by preference for sintered stone alternatives. MEE environmental enforcement tightens emissions controls on petrochemical derivatives. The Pearl River Delta concentrates raw material production rather than finished surface fabrication.
India
Maharashtra's construction boom generates emerging specification pull for cost-efficient wet-environment surfaces in mid-market residential developments. BIS quality certification requirements create entry barriers for unstandardized imports. Mumbai-Pune industrial corridors develop fabrication capacity targeting domestic renovation and Middle East export channels.
Cultured Marble Market Competitive Environment
Concentration sits with mid-scale regional fabricators serving contractor-direct channels rather than consolidated multinational surface producers. The vendor base fragments across vanity-specialized manufacturers, hospitality-focused shower system suppliers, and resin-integrated chemistry houses. Three archetypes dominate: automated casting technology adopters, distributor-captive regional producers, and formulation-integrated material science divisions. Competitive moves center on enclosed curing system investments for EPA compliance and direct-to-contractor digital platform deployment.
Among resin-chemistry-integrated manufacturers, DuPont exemplifies formulation-driven positioning through materials science heritage. Rynone Manufacturing anchors the mid-Atlantic regional fabricator tier with contractor-direct relationships. International Marble LLC occupies the hospitality-specialist position through shower wall system focus. These three represent distinct strategic vectors rather than direct peer competition.
| Leading Market Players |
|---|
| Caesarstone |
| Silestone |
| DuPont |
| International Marble LLC |
| Kuraray |
| LX Hausys |
| Cambria |
| Rynone Manufacturing |
| Lotte Chemical Corporation |
| Others |
Value Chain & Pricing Dynamics
EPA styrene emission protocols gate both supply qualification and price differentiation simultaneously, as enclosed curing systems required for compliance create capital barriers that separate premium-tier producers from commodity fabricators while compressing margins for non-compliant entrants.
Pricing Analysis
The customization-premium spread separates configured-to-order shower wall systems from standardized vanity dimensions. Project-based pricing dominates hospitality retrofits where brand-specified finishes command premium positioning, while per-unit transactional pricing prevails in residential replacement cycles. Cost compression in standard vanities intensifies as automated casting systems erode scale advantages. Residential contractors exhibit highest price sensitivity, whereas hospitality procurement teams prioritize installation speed over unit cost.
Supply Chain Analysis
Guangdong Province resin chemistry concentration creates a chokepoint for unsaturated polyester feedstock flowing to North American fabricators. Raw material dependencies center on petrochemical derivatives, crushed marble filler, and gel-coat formulations. Single-source vulnerability runs through Pearl River Delta resin production exposed to MEE environmental enforcement actions. Distribution runs through wholesale distributor networks serving regional contractor bases, with direct-to-fabricator procurement climbing fastest in hospitality channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cultured marble functions as a service-attach opportunity where installation labor coordination and BIM-compatible specification libraries expand faster than material hardware margins.
For Market Incumbents: Secure enclosed curing system investments ahead of EPA enforcement waves to defend capacity positioning against commodity entrants lacking compliant infrastructure. Backward integration into resin chemistry or captive supply agreements with Guangdong feedstock producers anchors margin stability against petrochemical volatility. For New Entrants and Emerging Players: Lead with aging-in-place bathroom modification segments where Medicare-adjacent renovation programs and ADA-compliant grab-bar integration create specification pull underserved by legacy hospitality-focused producers. Direct-to-contractor digital configurators bypass entrenched wholesale markups in mid-Atlantic residential markets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated casting system adopters, compressing minimum efficient scale thresholds and enabling smaller fabricators to match large-producer surface quality. Acquisition targets should display hospitality shower system specialization or CARB-compliant formulation capabilities. The signal to watch is EPA enforcement intensity in Florida and California manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Enclosed Curing System Deployment | EPA styrene emission compliance separates viable producers from capacity-constrained competitors in Florida and California. |
| Backward Integration into Resin Chemistry | Captive supply of unsaturated polyester feedstock insulates margins from Guangdong petrochemical volatility. |
| Direct-to-Contractor Digital Platform Launch | BIM-compatible specification libraries disintermediate wholesale channels serving mid-Atlantic residential builders. |
| CARB-Compliant Formulation Investment | Low-styrene resin systems create geographic shelter against California VOC restrictions on shower wall panels. |
| Unitized Shower Panel System Expansion | Pressure-assisted casting technology captures hospitality retrofit demand with compressed installation timelines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with residential contractors, hospitality procurement managers, casting technicians, and distributor principals, cross-referenced against EPA enforcement records, OSHA silica exposure guidelines, customs trade data on resin feedstock imports, and SEC filings from integrated materials science divisions. Bottom-up fabrication capacity counts triangulated with top-down construction spending allocations across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, end-user category, distribution channel, and application with regional regulatory cluster overlays. CAGRs derived from installed base replacement cycles, housing stock turnover rates, and hospitality refurbishment pipeline data. Forecast inputs incorporated Florida and California housing permit trends alongside EPA styrene emission protocol implementation timelines.
Forecasts assume regulatory continuity in EPA and OSHA regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as CARB VOC content rules and MEE environmental enforcement actions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Asia-Pacific Ready-Mix Concrete Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
China Concrete Superplasticizer Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
Thinset Mortar Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Global Door Market