
 Global Mechanical Seals Market | 2026-2036
Global Mechanical Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mechanical Seals Market Foresight
Seal-as-a-service maintenance contracts is shifting how mechanical seals are procured, bundling predictive monitoring with replacement cycles rather than discrete hardware sales. John Crane leverages its global service network to anchor long-term agreements with downstream operators. EagleBurgmann sustains technology leadership through advanced metal bellows engineering for high-temperature reactor applications. AESSEAL competes on rapid custom fabrication, positioning its distributed manufacturing footprint to reduce lead times for critical spare parts.
Mechanical seals are precision-engineered devices that create a pressure-tight interface between rotating shafts and stationary pump or compressor housings, typically incorporating face materials such as silicon carbide or tungsten carbide lapped to flatness tolerances below one light band to prevent process fluid leakage. Their primary purpose is to contain hazardous, corrosive, or high-value fluids across continuous-duty industrial equipment. Cartridge seal assemblies command premium positioning due to pre-assembled alignment features that slash field installation errors and commissioning time. Metal bellows configurations represent the fastest-growing product category, displacing elastomer-dependent designs in aromatic hydrocarbon service above 200°C where PTFE and fluoroelastomer compounds degrade. Tungsten carbide face pairs dominate severe abrasion duty in pulp mill stock pumps, though silicon carbide pairs are displacing them in newer water treatment installations where corrosion resistance outweighs wear rate.
EPA leak detection and repair mandates under the Clean Air Act shape seal selection criteria for US refineries, while REACH substance restrictions in Europe constrain binder chemistries used in carbon-graphite seal face manufacturing. China's GB standards for hazardous chemical containment, enforced by SAMR and MEE provincial branches, require dual mechanical seals with barrier fluid systems for toxic or flammable media. ISO 21049 and API 682 specifications continue to tighten as baseline procurement references across international project engineering. Stakeholders must monitor how evolving PFAS restrictions under ECHA and state-level US policies reshape elastomer and seal face coating availability before committing to multi-year supply agreements.
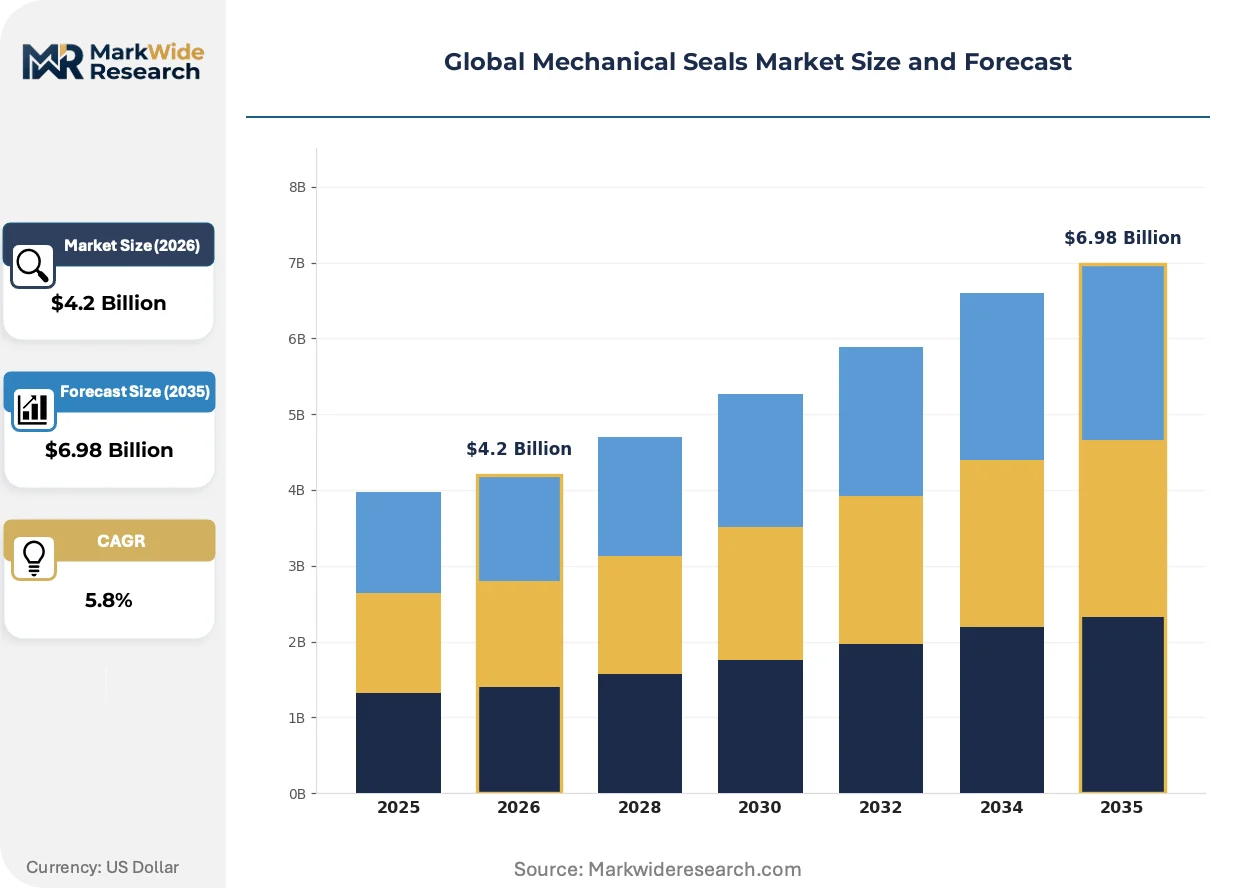
Market Dynamics
Seal-as-a-service contracts are restructuring procurement economics across downstream process industries, collapsing the traditional hardware-plus-maintenance split into unified lifecycle agreements that transfer operational risk from plant operators to seal manufacturers.
Growth Catalysts
- EPA LDAR mandates:Refinery operators face escalating penalty exposure under Clean Air Act enforcement, forcing wholesale seal upgrades to dual-cartridge barrier fluid systems that eliminate fugitive emissions at pump and compressor shafts.
- Metal bellows engineering:High-temperature aromatic hydrocarbon service above 200°C demands elastomer-free designs, with tungsten carbide and silicon carbide face pairs displacing PTFE-dependent configurations in reactor feed pumps.
- Shanghai-Ningbo industrial corridor:Petrochemical capacity expansion along China's eastern seaboard concentrates demand for API 682-compliant cartridge assemblies, with provincial MEE branches enforcing GB hazardous chemical containment standards.
Market Restraints
- Specialized tungsten carbide supply:Sintered seal face manufacturing depends on cobalt binder chemistries now restricted under REACH substance evaluations, compressing qualified European supplier pools and extending lead times.
- Precision lapping equipment concentration:Sub-one-light-band flatness tolerance achievement requires specialized grinding infrastructure concentrated in Germany, Japan, and select US Midwest machining clusters.
- Carbon-graphite face substitution ceiling:Dry-running compressor seals face fundamental temperature-velocity limits that prevent displacement of liquid-lubricated designs in high-speed turboexpander service.
Strategic Opportunities
- Saudi Aramco downstream expansion:Jafurah gas development and Red Sea coastal refinery builds create demand for sour gas service seals handling hydrogen sulfide concentrations above 10 mole percent.
- Digital twin convergence:Vibration and acoustic emission sensors embedded in cartridge seal assemblies enable predictive replacement scheduling, merging hardware supply with condition monitoring software subscriptions.
- India PLI scheme for pumps:Production-linked incentives for domestic pump manufacturing create captive seal demand as OEMs localize supply chains away from European import dependency.
Industry Challenges
- Precision metrology talent scarcity:Seal face lapping to optical flatness tolerances requires specialized technicians with multi-year apprenticeships, with demographic retirement waves thinning the qualified workforce in Midwest US and Ruhr Valley manufacturing hubs.
- ISO 21049 revision compliance:Updated seal testing protocols demand extended validation cycles that compress product development timelines and delay commercialization of next-generation metal bellows geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mechanical Seals Market |
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.98 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Spring, Balanced, Double Acting, Cartridge, Metal Bellows Material: Carbon, Silicon Carbide, Tungsten Carbide, Ceramic, PTFE Application: Pumps, Compressors, Mixers, Agitators, Reactors End User Industry: Petrochemicals, Pulp & Paper, Power Generation, Water Treatment |
| Companies Covered | A.W. Chesterton Company, Flexaseal Engineered Seals and Systems, John Crane, SEPCO, Garlock, EagleBurgmann, AESSEAL, CoorsTek, Flowserve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mechanical Seals Market Shifts & Advancements
Active sensor integration and materials science advances are compressing maintenance intervals while expanding the operational envelope of mechanical seals into previously unserviceable process conditions.
Wireless condition monitoring is decentralizing predictive maintenance responsibility from centralized plant reliability teams to seal OEM service networks. Downstream operators in US Gulf Coast refineries now transmit vibration and temperature data directly to manufacturer analytics platforms. This architecture enables just-in-time seal replacement before leakage occurs, collapsing traditional preventive maintenance calendars.
ECHA PFAS restriction proposals under REACH are forcing reformulation of fluoropolymer secondary seals and PTFE-based face coatings used in chemical service. European carbon-graphite manufacturers are accelerating binder system transitions to phenolic and resin-impregnated alternatives. API 682 fourth edition procurement specifications are already excluding non-compliant elastomer compounds from new project engineering.
Plant operators are consolidating seal specifications across multi-site footprints to compress spare parts inventory carrying costs. Integrated petrochemical complexes in China's Zhejiang province now mandate single-cartridge platform standardization across all centrifugal pump classes. This behavior concentrates procurement volume with manufacturers offering broad material compatibility and rapid custom fabrication capabilities.
Global Mechanical Seals Market Segmentation
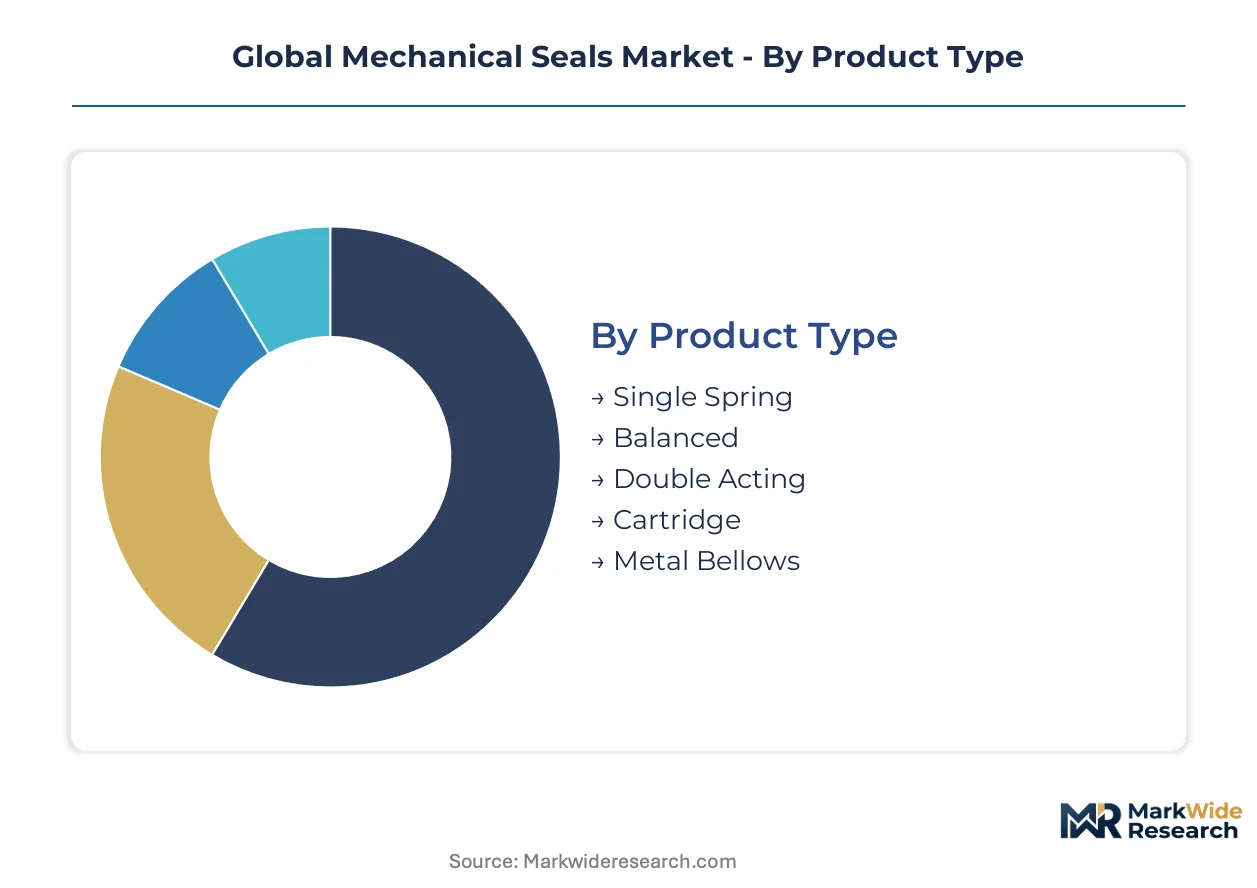
Mechanical seal procurement splits across multiple technical dimensions that dictate performance limits, maintenance economics, and regulatory compliance. Specification choices cascade through seal face material selection, cartridge configuration, and end-use duty severity.
Product Type:
Supply concentration in precision lapping infrastructure tilts manufacturing capability toward pre-assembled cartridge formats that reduce field installation variance.
- Cartridge:Factory-assembled units with pre-set face alignment and barrier fluid ports eliminate field measurement errors during pump commissioning. Demand concentrates in US Gulf Coast refineries where EPA LDAR mandates require dual-seal barrier systems for fugitive emissions control.
- Metal Bellows:Elastomer-free designs with welded stainless steel or Hastelloy bellows sustain seal face loading across thermal cycles above 200°C. Aromatic hydrocarbon service in China's Zhejiang province petrochemical corridor is displacing PTFE-dependent configurations.
- Balanced:Hydraulically balanced face loading reduces seal face wear in high-pressure applications.
- Double Acting:Dual seal faces with intermediate barrier fluid suit toxic or flammable media containment.
- Single Spring:Economical elastomer-bellows designs dominate low-temperature water and light hydrocarbon service.
Cartridge seals absorb the bulk of installed capacity in new refinery and petrochemical builds; metal bellows configurations are expanding most quickly as high-temperature process intensification accelerates.
Material:
Cost tier differentiation separates commodity carbon grades from premium ceramic composites in face pair specifications.
- Tungsten Carbide:Cobalt-bonded sintered carbides deliver extreme abrasion resistance in pulp mill stock pumps handling wood fiber slurries. REACH substance restrictions on cobalt binders compress qualified European supplier pools.
- Silicon Carbide:Reaction-bonded and sintered grades offer superior corrosion resistance in acidic water treatment environments. Newer municipal desalination installations in Saudi Arabia's Red Sea coastal zones specify silicon carbide face pairs over tungsten carbide alternatives.
- Carbon:Resin-impregnated grades provide self-lubricating dry-running capability in compressor seals.
- Ceramic:Aluminum oxide formulations serve moderate-duty chemical pump applications.
- PTFE:Fluoropolymer composites handle aggressive chemical media below thermal degradation thresholds.
Tungsten carbide retains the largest installed base in abrasive duty; silicon carbide is gaining share fastest as corrosion resistance priorities displace wear rate considerations in specification criteria.
Application:
Volume concentration in rotating equipment classes determines aftermarket spare parts demand patterns.
- Pumps:Centrifugal and positive displacement pumps represent the dominant seal installation base across process industries. API 682-compliant cartridge assemblies in China's Shanghai-Ningbo industrial corridor command specification standardization.
- Compressors:Dry gas seals and liquid-lubricated designs handle hydrocarbon gas compression in pipeline and processing service. Jafurah gas development in Saudi Arabia drives sour gas seal demand for hydrogen sulfide concentrations above 10 mole percent.
- Mixers:Top-entry and side-entry agitator seals handle viscous process fluids in batch chemical production.
- Agitators:Reactor vessel seals manage solids suspension and heat transfer in polymerization service.
- Reactors:High-pressure autoclave seals contain catalytic reaction environments.
Pumps absorb the bulk of installed capacity; compressor seals are expanding most quickly as natural gas processing capacity builds accelerate.
End User Industry:
Customer type segmentation separates capital-intensive process industries with in-house reliability teams from utility operators with outsourced maintenance.
- Petrochemicals:Integrated refineries and ethylene crackers operate the most severe seal duty cycles with continuous-run reliability requirements. US Gulf Coast operators are consolidating procurement under seal-as-a-service contracts that bundle predictive monitoring with replacement cycles.
- Water Treatment:Municipal and industrial water facilities prioritize corrosion-resistant materials in lower-pressure service. India's production-linked incentive scheme for domestic pump manufacturing is localizing seal supply chains away from European import dependency.
- Pulp & Paper:Stock pump seals face abrasive fiber slurry duty with high face wear rates.
- Power Generation:Boiler feed pump seals handle high-temperature, high-pressure water in thermal and nuclear plants.
Petrochemicals absorb the bulk of installed capacity; water treatment is expanding most quickly as desalination and wastewater reuse infrastructure multiplies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo industrial corridor concentrates China's petrochemical seal demand, with provincial MEE branches enforcing GB hazardous chemical containment standards across new ethylene cracker installations.
United States
US Gulf Coast refineries drive dual-cartridge barrier seal upgrades under EPA LDAR mandates. The Clean Air Act enforcement escalates penalty exposure for fugitive emissions at pump and compressor shafts. Houston-Texas City-Baytown petrochemical complexes consolidate procurement under seal-as-a-service contracts bundling predictive monitoring with replacement cycles.
Germany
German precision lapping infrastructure supplies sub-one-light-band flatness tolerance seal faces to European process industries. REACH substance evaluations restrict cobalt binder chemistries in tungsten carbide sintering, compressing qualified supplier pools. Ruhr Valley manufacturing hubs face demographic retirement waves thinning specialized technician workforces.
Saudi Arabia
Jafurah gas development and Red Sea coastal refinery builds create demand for sour gas service seals handling hydrogen sulfide concentrations above 10 mole percent. The national oil company downstream expansion prioritizes API 682-compliant cartridge assemblies. Eastern Province industrial cities anchor natural gas processing capacity buildouts.
India
India's production-linked incentive scheme for domestic pump manufacturing localizes seal supply chains away from European import dependency. BIS standards adoption accelerates specification alignment with ISO 21049 protocols. Gujarat and Maharashtra industrial corridors concentrate captive seal demand as OEMs expand machining capacity.
Global Mechanical Seals Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the mechanical seals landscape. Integrated manufacturers maintaining captive precision lapping infrastructure and global service networks face competition from regional fabricators outsourcing critical grinding operations. The market structures around three archetypes: full-service OEMs bundling hardware with predictive maintenance subscriptions, specialized metal bellows engineers serving high-temperature reactor applications, and rapid-customization shops leveraging distributed manufacturing footprints. Dominant competitive moves include seal-as-a-service contract expansion transferring operational risk to manufacturers, and strategic partnerships embedding wireless condition monitoring sensors within cartridge assemblies.
Within the full-service tier, John Crane leverages its global service network to anchor long-term agreements, while EagleBurgmann occupies a position exemplifying advanced metal bellows engineering specialization. AESSEAL represents the rapid-customization archetype, with its distributed manufacturing footprint reducing lead times for critical spare parts. These three companies illustrate how competitive positioning separates around service integration depth, materials science capability, and supply chain responsiveness rather than hardware pricing alone.
| Leading Market Players |
|---|
| A.W. Chesterton Company |
| Flexaseal Engineered Seals and Systems |
| John Crane |
| SEPCO |
| Garlock |
| EagleBurgmann |
| AESSEAL |
| CoorsTek |
| Flowserve Corporation |
| Others |
Supply & Pricing Matrix
US Gulf Coast petrochemical operators consolidating procurement under seal-as-a-service contracts are compressing hardware margins while elevating predictive monitoring premiums. This buyer concentration tilts pricing power toward manufacturers bundling condition-based replacement cycles with cartridge seal supply.
Pricing Analysis
Outcome-based pricing tied to mean-time-between-failure performance anchors premium cartridge seal contracts in refinery service. Three-tier pricing structure across API 682-compliant premium, ISO 21049-standard, and economy single-spring levels differentiates by certification grade and barrier fluid system complexity. Cost compression in cobalt-bonded tungsten carbide face manufacturing is intensifying because REACH substance restrictions compress qualified European supplier pools. Water treatment operators exhibit highest price sensitivity due to municipal budget constraints, while petrochemical reliability teams prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing qualification requirements for critical pump seals in Saudi Aramco downstream projects mandate parallel supplier validation across Germany, Japan, and US Midwest machining clusters. Precision lapping infrastructure for sub-one-light-band flatness tolerance rests on specialized grinding equipment concentrated in Ruhr Valley, Nagoya industrial corridor, and Cleveland-Akron manufacturing belt. Single-source vulnerability in cobalt binder chemistries for sintered seal faces exposes supply chains to ECHA restriction enforcement. Distribution runs through OEM-direct channels for new project engineering and authorized service networks for aftermarket spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mechanical seals market functions as a cost-of-compliance arena where EPA LDAR mandates and REACH substance evaluations erect regulatory moats favoring incumbent manufacturers with validated barrier fluid system portfolios.
For Market Incumbents: Deploy seal-as-a-service contract expansion to transfer operational risk from plant operators and capture recurring revenue streams. Deepen captive precision lapping capacity in Ruhr Valley and Nagoya industrial corridor to defend against lead time compression from emerging Asian fabricators. Metal bellows engineering specialization represents the priority defensive lever against elastomer-free design substitution in high-temperature aromatic hydrocarbon service.
For New Entrants and Emerging Players: Launch via rapid-customization fabrication targeting India's production-linked incentive scheme for domestic pump manufacturing. White-space concentration in Gujarat and Maharashtra industrial corridors offers lowest competitive density against established European import suppliers. Municipal water treatment desalination projects in Saudi Arabia's Red Sea coastal zones present the most penetrable specification entry point.
For Investors and Strategic Acquirers: The window for entry favors precision metrology specialists with multi-year technician apprenticeship pipelines. Long-term viability hinges on consolidation plays capturing lapping infrastructure scarcity as demographic retirement waves thin qualified workforces in Midwest US and German manufacturing hubs. Watch ECHA PFAS restriction finalization as the signal for elastomer reformulation cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Seal-as-a-Service Contract Expansion | John Crane leverages global service networks to anchor predictive monitoring subscriptions with US Gulf Coast refineries. |
| Metal Bellows Capacity Addition | EagleBurgmann sustains technology leadership through Hastelloy bellows welding for reactor applications above 200°C. |
| Distributed Manufacturing Localization | AESSEAL positions rapid custom fabrication footprint to compress lead times for critical spare parts in Zhejiang province. |
| Barrier Fluid System Certification Investment | API 682 fourth edition compliance separates qualified dual-cartridge suppliers from commodity single-spring competitors. |
| Wireless Condition Monitoring Integration | Embedded vibration sensors enable predictive replacement scheduling before fugitive emissions trigger EPA enforcement. |
Research Methodology
SEC 10-K filings, customs trade databases, and API equipment certification registries formed the secondary backbone for market sizing validation. Primary interviews with plant reliability directors, OEM procurement teams, aftermarket service heads, and precision lapping technicians combined with secondary source triangulation. Bottom-up segmentation across cartridge configuration, face material grade, and end-use severity was cross-checked against top-down industry association data from American Chemistry Council and European Sealing Association.
Historical trendline analysis of installed base replacement cycles and new project engineering awards informed the projection framework. Segmentation dimensions modeled include product type, material specification, rotating equipment class, and end-user industry vertical across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating petrochemical capacity buildout timelines and regulatory compliance upgrade cycles. Metal bellows displacement rates and digital twin sensor penetration served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for wireless condition monitoring integration; alternative pathways for predictive maintenance software architecture would alter the outlook. Forecasts reflect assumptions regarding EPA enforcement consistency and REACH substance evaluation timelines. Deviation in cobalt binder chemistry restriction scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Scraper Conveyor Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Industrial Fasteners Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Global Large Conveyor Chain Market
Material Handling Equipment
Mobile Conveyor Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Asia Pacific Automated Material Handling and Storage Systems Market
Material Handling Equipment
United States Conveyor Belt Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Hose Pump Market