
 Laser Cladding Market | 2026-2036
Laser Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Cladding Market Outlook
ISO 9001 and AS9100 certification cycles is bifurcating the competitive landscape into qualified aerospace suppliers and general industrial service providers. TRUMPF leverages its integrated laser source and optics platform to dominate high-precision cladding cells for tool and die restoration. TWI Ltd sustains technology leadership through its proprietary wire-laser cladding processes developed for nuclear pressure vessel repair. Wuhan Hans Goldensky Laser System anchors cost-competitive diode laser systems serving China's domestic energy sector tooling refurbishment.
Laser cladding deposits metallic coating layers onto substrates using focused laser energy to melt feedstock powder or wire, typically achieving bond strengths exceeding those of thermal spray methods. The process serves primarily to restore dimensional tolerance and surface hardness to worn industrial components such as turbine blades, extrusion screws, and forging dies. Fiber laser technology leads installed capacity due to superior wall-plug efficiency and beam quality at kilowatt power levels. Aerospace application commands premium pricing for flight-critical component repair, while automotive repair segments compete on throughput and per-part economics. Nickel alloy material types concentrate in oil and gas valve refurbishment where corrosion resistance requirements gate supplier qualification.
FAA airworthiness directives and EASA Part 145 repair station regulations govern who may perform flight-critical component restoration, creating structural barriers to market entry for uncertified operators. EPA emissions standards and REACH chemical restrictions shape powder alloy formulation choices and captive recycling requirements in US and European facilities. Stakeholders must monitor evolving defense procurement specifications for additive repair as military sustainment budgets shift toward component life extension rather than replacement.
Market Dynamics
The EU F-Gas Regulation is compressing demand for CO₂ laser systems and redirecting capital toward fiber laser platforms with superior wall-plug efficiency and reduced fluorinated gas emissions.
Growth Catalysts
- F-Gas Regulation compliance deadlines:European manufacturers face mandated phase-out of high-global-warming-potential laser gases, forcing fleet replacement with solid-state alternatives.
- Aerospace engine restoration:Turbine blade repair contracts from MRO providers are expanding qualified supplier rosters under FAA and EASA airworthiness frameworks.
- Germany's tooling density:The country's concentration of automotive stamping and extrusion die operations sustains continuous demand for precision cladding cells.
Market Restraints
- Powder alloy cost volatility:Nickel superalloy feedstock prices fluctuate with mining output from Russian and Canadian sources, compressing job shop margins.
- Optics supplier concentration:German and Japanese specialty lens manufacturers control high-power beam delivery components, creating single-source vulnerability.
- Substitution by thermal spray:HVOF and plasma spray systems retain cost advantage for non-flight-critical wear applications in general industry.
Strategic Opportunities
- India's defense MRO expansion:Indigenous fighter jet and helicopter programs are qualifying local laser cladding suppliers under DGFT import substitution mandates.
- Wire-laser hybrid processes:Convergence of arc welding deposition rates with laser precision is opening thick-section repair applications in nuclear pressure vessels.
- CSRD disclosure requirements:European corporate sustainability reporting is creating preference for repair-over-replace service models with documented carbon footprint reduction.
Industry Challenges
- AS9100 certification timelines:Aerospace supplier qualification cycles extend 18-24 months, freezing out capital-constrained entrants from flight-critical segments.
- Multi-axis programming expertise:Shortage of CAM specialists capable of complex toolpath generation for freeform cladding surfaces limits cell utilization rates.
- Legacy ERP integration:Job shops struggle to connect real-time process monitoring data with existing MRP systems for traceability compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Cladding Market |
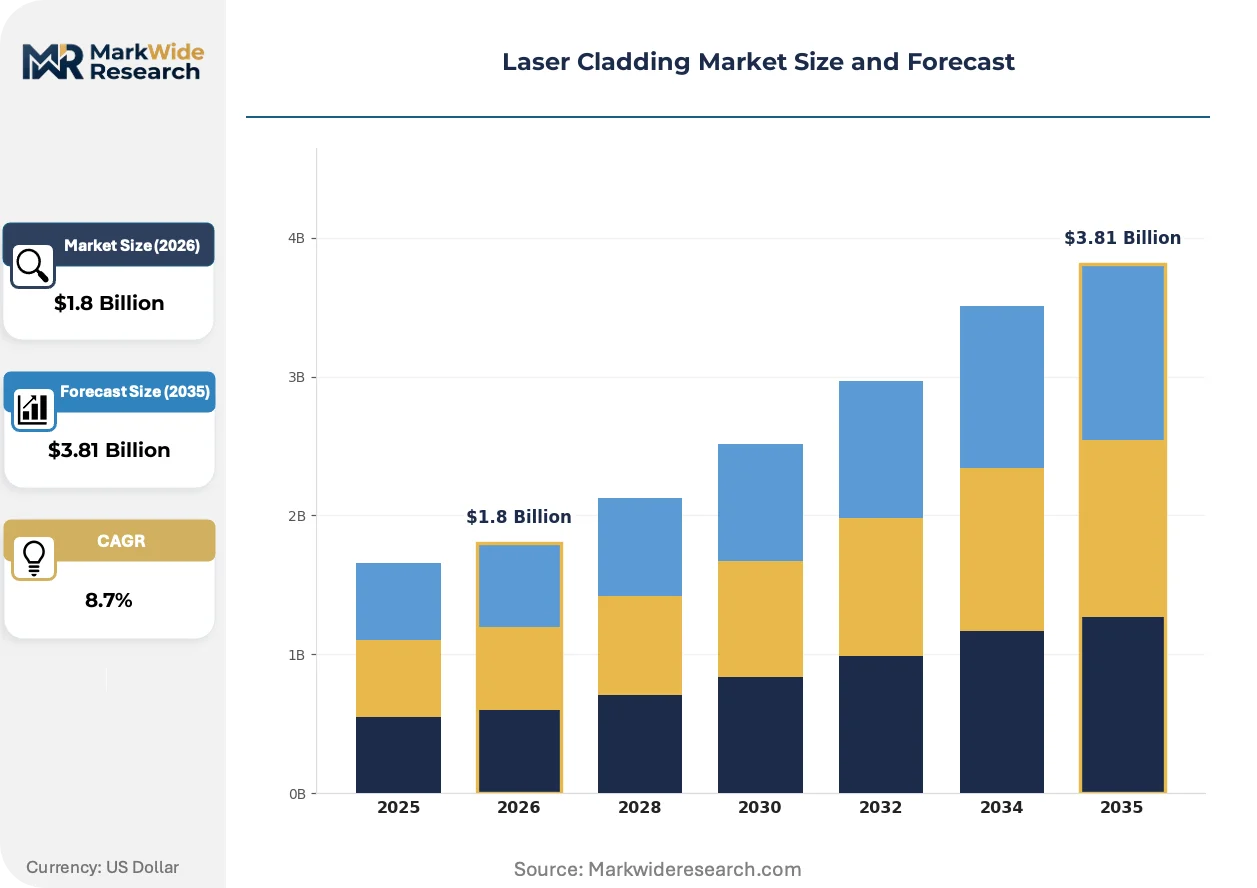
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fiber Laser, CO2 Laser, Diode Laser, Nd:YAG Laser Application: Aerospace, Oil & Gas, Automotive Repair, Tooling Material Type: Stainless Steel, Aluminum, Copper, Nickel Alloy End User: Manufacturers, Energy Sector, Defense, Medical Equipment |
| Companies Covered | Spraywerx, TWI Ltd, TRUMPF, GTV GmbH, Laser Cladding Technology Ltd., OC Oerlikon Management AG, TLM Laser Ltd, Wuhan Hans Goldensky Laser System, Coherent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Cladding Market Strategic Shifts
Process control architectures and feedstock delivery mechanisms are converging to enable autonomous cladding operations with minimal operator intervention.
Closed-loop melt pool monitoring using coaxial pyrometry and machine vision is miniaturizing quality assurance hardware into compact sensor heads that mount directly on cladding nozzles. Aerospace MRO stations in France and the United States are piloting these systems for 24-hour unmanned turbine blade restoration. The technology is compressing post-process inspection cycles and reducing scrap rates in flight-critical applications.
REACH chemical restrictions are forcing reformulation of cobalt-chrome and nickel-based powder alloys to eliminate hexavalent chromium and specific respirable particulates. Powder producers in Germany and Sweden are certifying modified chemistries that maintain hardness and corrosion resistance while satisfying ECHA substance authorization requirements. Oil and gas valve refurbishment segments are absorbing premium pricing for compliant feedstock to maintain EU market access.
After-sales service unbundling is fragmenting traditional equipment supply contracts into separate hardware, software, and consumables purchasing decisions. German automotive tool and die shops are procuring laser cladding cells without mandatory service agreements, instead sourcing maintenance from third-party specialists. This pattern is most pronounced in Bavaria and Baden-Württemberg, where dense supplier networks support competitive service pricing.
Laser Cladding Market Segmentation
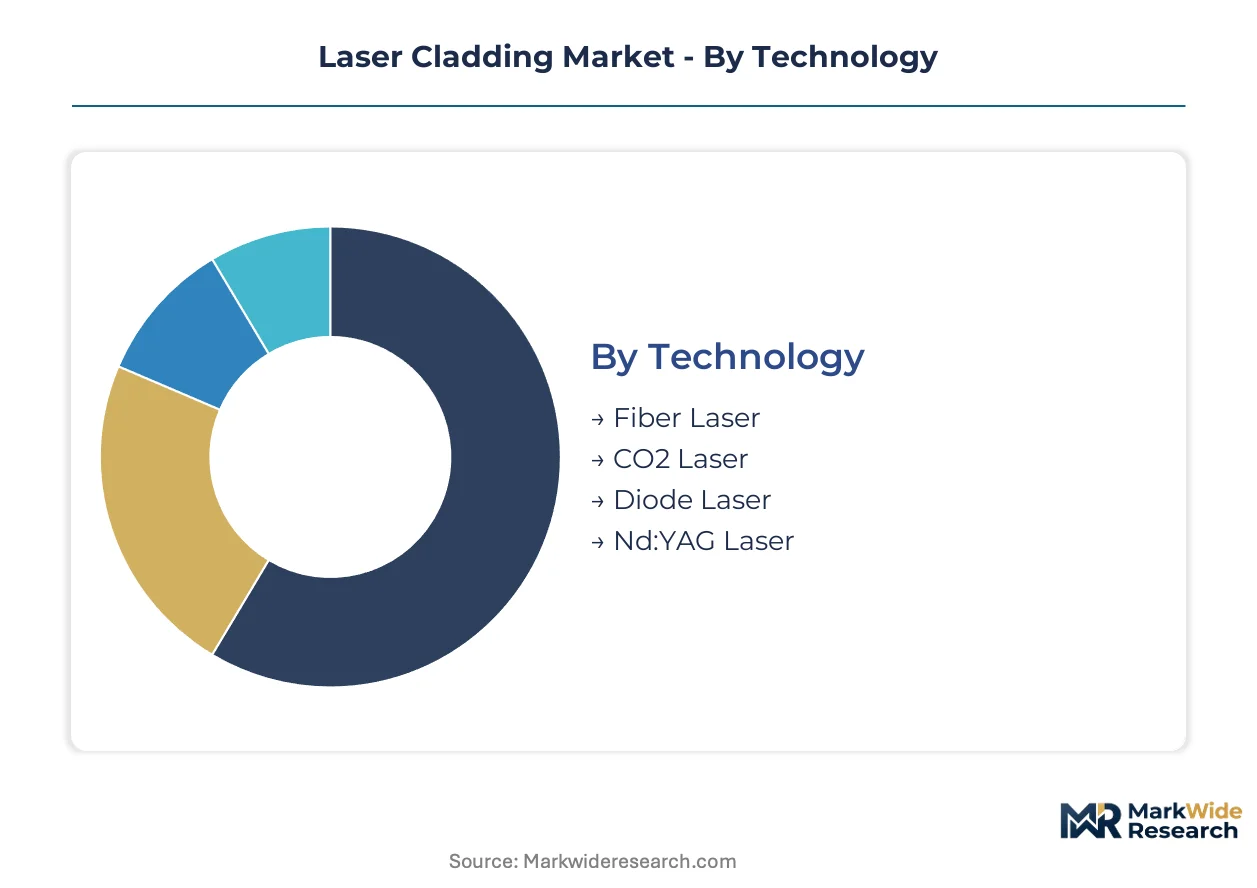
Laser cladding segmentation reveals distinct technology and material clusters that command divergent pricing power based on certification requirements and energy efficiency mandates. Understanding these divides exposes where capital deployment concentrates and where margin compression threatens.
Technology:
Domestic demand in Germany and Japan favors fiber and diode platforms with localized supply chains, while CO₂ laser refurbishment exports concentrate from legacy US and Italian installed bases.
- Fiber Laser:Solid-state architecture delivers wall-plug efficiency exceeding 30% with near-diffraction-limited beam quality. European automotive toolrooms in Stuttgart and Wolfsburg dominate procurement as F-Gas Regulation deadlines force fleet replacement. Momentum accelerates in aerospace MRO stations seeking reduced thermal distortion in thin-section blade restoration.
- CO2 Laser:Gas-discharge systems using fluorinated gain media face accelerated obsolescence under EU environmental mandates. Remaining demand concentrates in North American job shops with amortized capital and established process libraries for thick-section die repair.
- Diode Laser:Direct-emitting bars offer cost-competitive entry points for energy sector tooling refurbishment. Chinese domestic suppliers anchor volume production for pipeline valve restoration.
- Nd:YAG Laser:Lamp-pumped legacy systems persist in defense maintenance depots with frozen specifications and long qualification cycles.
Fiber laser holds the largest share; momentum sits with diode laser as cost-sensitive segments expand.
Application:
Margin structures bifurcate sharply between flight-critical aerospace work with 18-month qualification barriers and throughput-driven automotive repair competing on per-part economics.
- Aerospace:Turbine blade and combustor liner restoration commands premium pricing under FAA and EASA airworthiness frameworks. French and US MRO providers dominate qualified supplier rosters with proprietary process controls.
- Oil & Gas:Downhole tool and valve refurbishment in corrosion-resistant nickel alloys concentrates in Houston and Aberdeen. REACH-compliant powder feedstock absorbs 15-20% cost premiums to maintain EU market access.
- Automotive Repair:Stamping die and extrusion screw restoration in Germany's automotive belt competes on cell utilization and automation density.
- Tooling:General industrial mold and die repair spans fragmented job shop networks with limited certification requirements and price-transparent procurement.
Aerospace captures peak margin; automotive repair expands most quickly as electrification reshapes component wear patterns.
Material Type:
Alloy selection tracks end-use corrosion and temperature requirements, with nickel superalloy supply chains exposed to mining concentration in Russian and Canadian sources.
- Nickel Alloy:Inconel and Hastelloy formulations dominate oil and gas valve cladding where sulfide stress cracking resistance gates supplier qualification. ECHA substance authorization pressures cobalt-bearing variants.
- Stainless Steel:316L and 17-4 PH grades anchor general tooling restoration with standardized procurement and commodity pricing dynamics.
- Aluminum:Lightweight alloy cladding for aerospace structural repair faces challenges with oxide formation and crack sensitivity, limiting qualified process windows.
- Copper:High thermal conductivity substrates require specialized parameter development for mold cooling channel restoration in injection molding applications.
Nickel alloy holds the largest share; aluminum gains share fastest as airframe manufacturers qualify repair processes for weight-critical components.
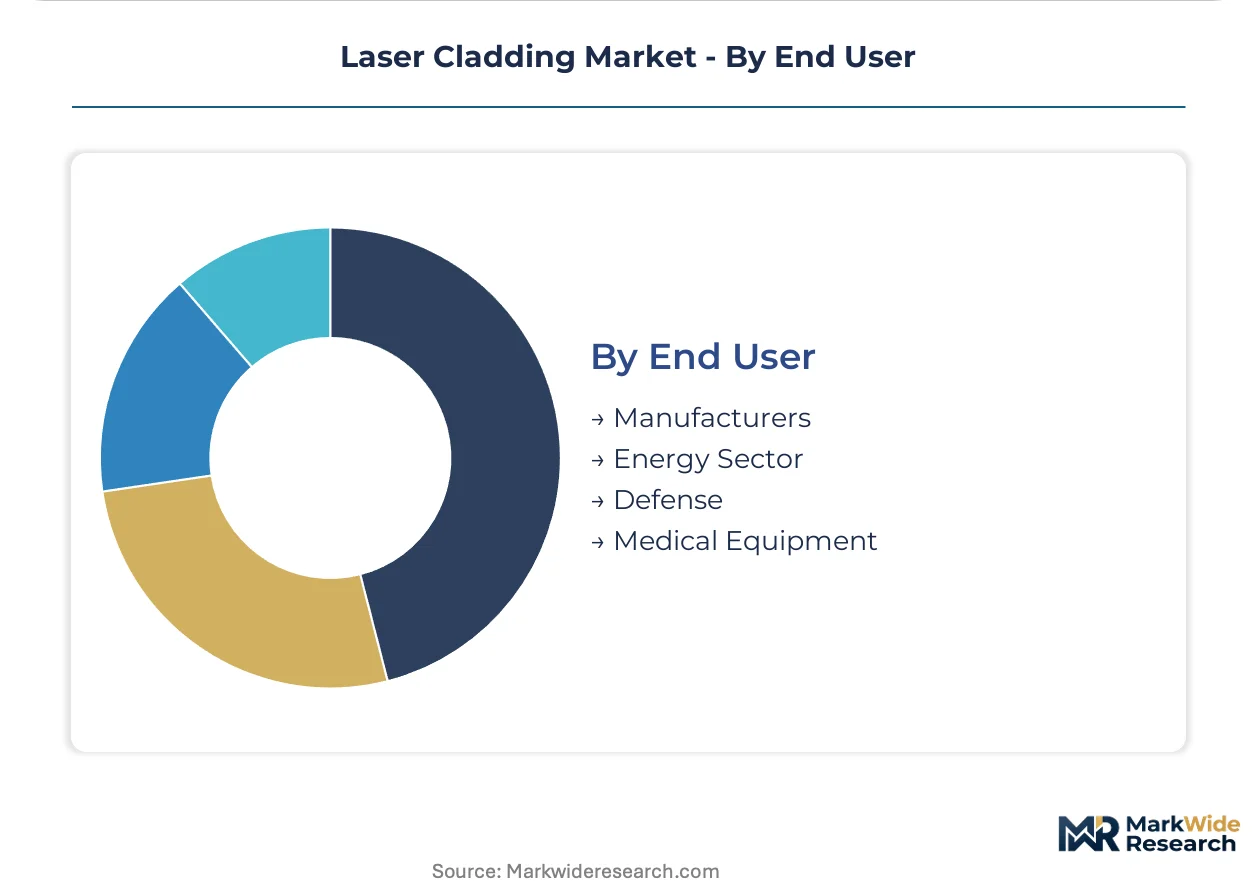
End User:
Procurement authority concentrates differently across segments, with defense and medical equipment imposing captive qualification requirements that fragment supplier access.
- Energy Sector:Oil majors and utilities operate centralized cladding facilities for rotating equipment and pipeline component restoration. Saudi Aramco and Equinor maintain approved vendor lists with stringent metallurgical testing protocols.
- Manufacturers:Automotive OEMs and tier suppliers deploy in-house cells for die maintenance, balancing utilization against third-party job shop economics.
- Defense:Military sustainment depots in the US, UK, and India specify additive repair under component life extension programs with security-cleared supplier requirements.
- Medical Equipment:Orthopedic implant refurbishment demands ISO 13485 alignment with biocompatibility testing that excludes general industrial service providers.
Energy sector holds the largest share; defense climbs the fastest as procurement shifts from replacement toward repair under budget constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive toolrooms and aerospace MRO stations in France and the United States are driving capital deployment toward fiber laser platforms as environmental mandates compress CO₂ laser viability. Procurement patterns concentrate in industrial clusters with dense die-casting, forging, and turbine blade restoration infrastructure.
United States
Aerospace MRO providers in Connecticut and Georgia are expanding qualified supplier rosters for turbine blade restoration under FAA airworthiness frameworks. EPA emissions standards shape powder alloy formulation choices and captive recycling requirements in domestic facilities. Houston anchors oil and gas valve refurbishment demand where nickel superalloy corrosion resistance gates supplier access.
Germany
Automotive stamping and extrusion die operations in Stuttgart and Wolfsburg sustain continuous demand for precision cladding cells with high automation density. The EU F-Gas Regulation is forcing fleet replacement with solid-state fiber laser alternatives ahead of mandated phase-out deadlines. Bavaria and Baden-Württemberg host dense supplier networks that support competitive third-party maintenance pricing.
China
Domestic energy sector tooling refurbishment is absorbing cost-competitive diode laser systems for pipeline valve restoration. The country's dual carbon goals are redirecting industrial laser procurement toward higher wall-plug efficiency platforms. Wuhan anchors volume production clusters serving state-owned oil majors with centralized cladding facilities.
France
Aerospace MRO stations are piloting closed-loop melt pool monitoring systems for 24-hour unmanned turbine blade restoration under EASA Part 145 repair station regulations. REACH chemical restrictions are forcing reformulation of cobalt-chrome powder alloys to eliminate hexavalent chromium. The Toulouse and Paris aerospace clusters concentrate flight-critical component repair expertise.
India
Indigenous fighter jet and helicopter programs are qualifying local laser cladding suppliers under DGFT import substitution mandates. Defense MRO expansion is creating structural demand for component life extension rather than replacement procurement. Bangalore and Hyderabad host emerging supplier development programs aligned with military sustainment budget shifts.
Laser Cladding Market Competitive Environment
Player mix skews toward integrated laser source manufacturers and specialized cladding service providers with captive process libraries. Market structure concentrates around three strategic archetypes: full-stack platform vendors controlling source and optics integration, pure-play service specialists with aerospace certification moats, and regional cost-optimized equipment suppliers. Dominant competitive moves include technology licensing partnerships for wire-laser hybrid processes and geographic expansion into defense MRO markets with security-cleared supplier requirements.
Within the full-stack platform tier, TRUMPF and Coherent occupy positions defined by integrated laser source and beam delivery control. TWI Ltd exemplifies the certified service specialist archetype through its proprietary process development for nuclear pressure vessel repair. Wuhan Hans Goldensky Laser System anchors the cost-optimized regional equipment segment serving energy sector tooling refurbishment with diode laser platforms.
| Leading Market Players |
|---|
| Spraywerx |
| TWI Ltd |
| TRUMPF |
| GTV GmbH |
| Laser Cladding Technology Ltd. |
| OC Oerlikon Management AG |
| TLM Laser Ltd |
| Wuhan Hans Goldensky Laser System |
| Coherent |
| Others |
Value Chain & Pricing Dynamics
FAA airworthiness directives and EASA Part 145 frameworks gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified operators while allowing aerospace-certified providers to command substantial premiums for flight-critical turbine blade restoration.
Pricing Analysis
Certification level (ISO 9001/AS9100-grade) creates the primary spread between aerospace MRO stations and general industrial job shops. Three-tier pricing structure across premium flight-critical, qualified industrial, and uncertified economy levels tracks qualification investment and traceability burden. Cost compression in automotive die repair segments is intensifying because German toolrooms are unbundling after-sales service from equipment procurement. Energy sector valve refurbishment buyers exhibit highest price sensitivity, while French aerospace MRO providers remain least sensitive due to captive airworthiness requirements.
Supply Chain Analysis
High-power beam delivery optics from German and Japanese specialty lens manufacturers underwrites single-source vulnerability across fiber laser cladding cell deployments. Feedstock powder production draws from Russian and Canadian mining concentration for nickel superalloys, with German and Swedish producers reformulating cobalt-chrome chemistries under REACH restrictions. Tariff exposure runs through EU-China laser diode component trade corridors. Distribution feeds from integrated platform vendors through third-party service specialists to captive end-user facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser cladding sits in early-cycle expansion as fiber laser displacement of CO₂ platforms accelerates under EU F-Gas Regulation deadlines, with repair-over-replace service models gaining procurement preference under CSRD disclosure requirements.
For Market Incumbents: Compound aerospace certification moats by accelerating AS9100 qualification timelines for emerging MRO stations in India and France before capital-constrained entrants freeze out. Deepen backward integration into high-power optics supply through captive lens manufacturing partnerships, mitigating single-source vulnerability from German and Japanese suppliers. Thermal spray substitution in non-flight-critical applications poses persistent margin pressure requiring automation density investments in automotive toolroom segments. For New Entrants and Emerging Players: Lead with wire-laser hybrid process development for nuclear pressure vessel thick-section repair, where TWI Ltd's proprietary methods have not yet saturated qualified supplier rosters. India's defense MRO expansion under DGFT import substitution mandates represents the most penetrable geography, with Bangalore and Hyderabad supplier development programs actively seeking local cladding capabilities. Target energy sector tooling refurbishment with cost-optimized diode laser platforms, mirroring Wuhan Hans Goldensky's established penetration model. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fiber laser platform manufacturing as European environmental mandates force fleet replacement cycles. Long-term viability over the coming decade favors full-stack platform vendors with integrated source and optics control, or certified service specialists with captive aerospace process libraries. Acquisition targets should display AS9100 qualification completion or security-cleared defense supplier status. The signal to watch is EASA Part 145 repair station expansion rates in Toulouse and Paris aerospace clusters as unmanned cladding pilot programs scale.| Strategic Initiative | Industry Significance |
|---|---|
| Wire-Laser Hybrid Process Development | Converges arc welding deposition rates with laser precision for nuclear pressure vessel applications. |
| AS9100 Certification Acceleration | Compresses 18-24 month qualification timelines to capture flight-critical turbine blade restoration contracts. |
| Backward Integration into Optics | Captures high-power beam delivery components currently concentrated in German and Japanese suppliers. |
| CSRD-Aligned Service Unbundling | Fragments equipment contracts into separate hardware, software, and consumables purchasing decisions. |
| Defense MRO Geographic Expansion | Establishes security-cleared supplier presence under India's DGFT import substitution mandates. |
Study Parameters
The analysis maps fiber laser platform displacement, CO₂ laser obsolescence trajectories, and wire-laser hybrid adoption curves, each validated through maintenance directors at automotive toolrooms, aerospace MRO procurement leads, and powder alloy technical directors. Primary interviews with plant engineers at German stamping die operations and nuclear pressure vessel specialists at TWI Ltd combined with secondary validation through EASA Part 145 repair station filings, EPA emissions compliance databases, and REACH substance authorization records. Bottom-up equipment shipment tracking and top-down MRO contract value triangulation anchored market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include laser technology architecture, application criticality tier, feedstock alloy family, and end-user procurement authority structure. CAGRs derived from equipment replacement cycle analysis, MRO contract growth patterns, and environmental mandate compliance timelines. Industry-specific forecast inputs incorporated F-Gas Regulation phase-out schedules and defense budget shifts toward component life extension.
Forecasts assume regulatory continuity in EU F-Gas Regulation, FAA airworthiness frameworks, and REACH chemical restrictions; material policy shifts would require re-modeling. Specific risk factors include nickel superalloy supply disruption from mining concentration, optics supplier consolidation, and thermal spray technology advancement. Practitioners should keep alternative scenarios live as unmanned cladding adoption rates and CSRD disclosure stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
Industrial Spindles Market
Precision Mechanics and Electrics
High Precision Worm Shaft Market
Precision Mechanics and Electrics
Precision Engineering Machines Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Right Angle Fastener Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market
Precision Mechanics and Electrics
Global Ball Screw Market