
 Storage Water Heater Market | 2026-2036
Storage Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Storage Water Heater Market Analysis
ENERGY STAR certification is collapsing as a gating mechanism for market access in North American distribution channels. A.O. Smith leverages its captive water heater foundry network to sustain cost positions against import competition. Rheem Manufacturing Company anchors its portfolio with gas-fired tank lines that dominate contractor-specified residential projects. Bradford White Corporation specializes in commercial-grade high-recovery units that occupy the premium specification tier.
A storage water heater is a thermally insulated vessel engineered to heat and store potable water at predetermined temperatures, typically employing glass-lined carbon steel tanks with magnesium anode rods for corrosion protection and pressure-rated relief valves for safety. Electric units draw resistance heating elements rated between 3 and 5.5 kilowatts, while gas variants utilize atmospheric or power-vented burners with flue baffles to maximize heat transfer efficiency. The product type dimension shows heat pump variants capturing disproportionate margin pools as efficiency standards tighten, while the installation type dimension reveals commercial applications generating higher per-unit value despite longer replacement cycles than residential segments.
The US Department of Energy appliance efficiency standards and the European Union Ecodesign Directive are forcing manufacturers to redesign insulation packages and burner architectures to meet escalating minimum performance thresholds. India's Bureau of Energy Efficiency star labeling program shapes consumer purchasing patterns by mandating visible efficiency disclosures at point of sale. Stakeholders must monitor how regulatory divergence between efficiency testing protocols affects cross-border product platform economics.
Market Dynamics
Heat pump water heater technology is bifurcating the competitive landscape as efficiency mandates compress margins on conventional tank-based systems. Regulatory divergence between testing protocols is forcing manufacturers to maintain parallel product platforms.
Growth Catalysts
- India's Bureau of Energy Efficiency star labeling program:Mandated efficiency disclosures at point of sale accelerate replacement cycles in urban housing markets.
- Residential construction across Southeast Asia:Expanding installations of tank-based systems in Vietnam, Indonesia, and Thailand drive volume demand.
- European Union Ecodesign Directive:Redefines efficiency benchmarks and creates technology upgrade imperatives across member states.
Market Restraints
- Steel and copper input volatility:Glass-lined carbon steel tanks and resistance heating elements face raw material cost pressures.
- Supply concentration in foundry capacity:Captive foundry networks in China and India create asymmetric cost positions for integrated versus non-integrated manufacturers.
- Heat pump refrigerant complexity:F-Gas Regulation compliance adds engineering overhead and limits cross-border platform standardization.
Strategic Opportunities
- Commercial-grade high-recovery units:Premium specification tier in hospitality and healthcare verticals generates higher per-unit value despite longer replacement cycles.
- India's urban housing deficit:Government electrification programs create underpenetrated demand pools in tier-2 and tier-3 cities.
- Power-vented burner architectures:Convergence with smart home energy management systems opens retrofit and new construction channels.
Industry Challenges
- Heat pump system integration:Installation complexity with legacy electrical infrastructure requires specialized contractor training and extends sales cycles.
- Cross-border certification timelines:Divergent efficiency testing protocols between US Department of Energy and European Union Ecodesign create product launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storage Water Heater Market |
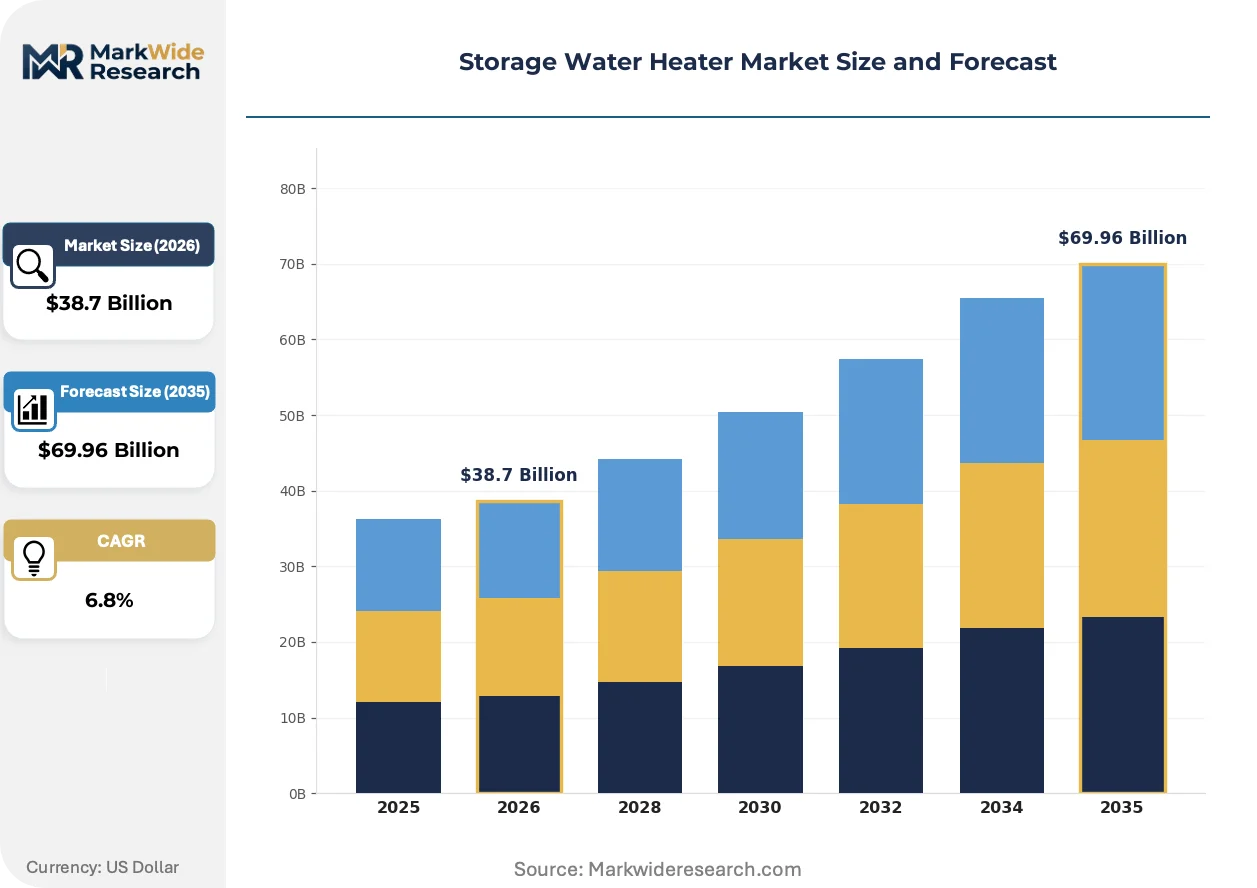
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Solar, Heat Pump Installation Type: Residential, Commercial, Industrial, Portable Energy Source: Natural Gas, Propane, Electricity, Biomass Capacity: 30 Gallons, 50 Gallons, 80 Gallons, 100 Gallons |
| Companies Covered | A.O. Smith, Rheem Manufacturing Company, Ariston Holding N.V., Bosch Thermotechnology, Rinnai Corporation, Whirlpool Corporation, Havells India Limited, Bradford White Corporation, Viessmann Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storage Water Heater Market Emerging Trajectories
Technology trajectories in storage water heating are compressing traditional equipment categories while opening adjacent service revenue streams. Efficiency mandates and digital integration are the dominant reshaping forces.
Heat pump water heater technology is bifurcating the product architecture landscape. These systems extract ambient thermal energy to heat water at three to four times the efficiency of resistance elements. Residential contractors in Germany and France are specifying them for new multi-family construction at accelerating rates. The technology is bifurcating margin pools away from conventional electric and gas tank units toward integrated heat pump systems with higher upfront costs but lower lifecycle operating expenses.
European Union F-Gas Regulation is tightening refrigerant phase-down schedules for heat pump water heaters. Manufacturers must redesign compressor packages and heat exchanger circuits to accommodate lower-global-warming-potential alternatives. Commercial building operators in the Netherlands and Belgium face accelerated replacement deadlines, driving specification shifts toward compliant systems before mandated dates.
After-sales service unbundling is disrupting traditional distribution economics. Equipment-only procurement through digital marketplaces is displacing bundled install-and-maintain contracts in the North American residential segment. Plumbing contractors in Texas and Florida are responding by developing proprietary maintenance subscription models to recover recurring revenue streams.
Storage Water Heater Market Segmentation
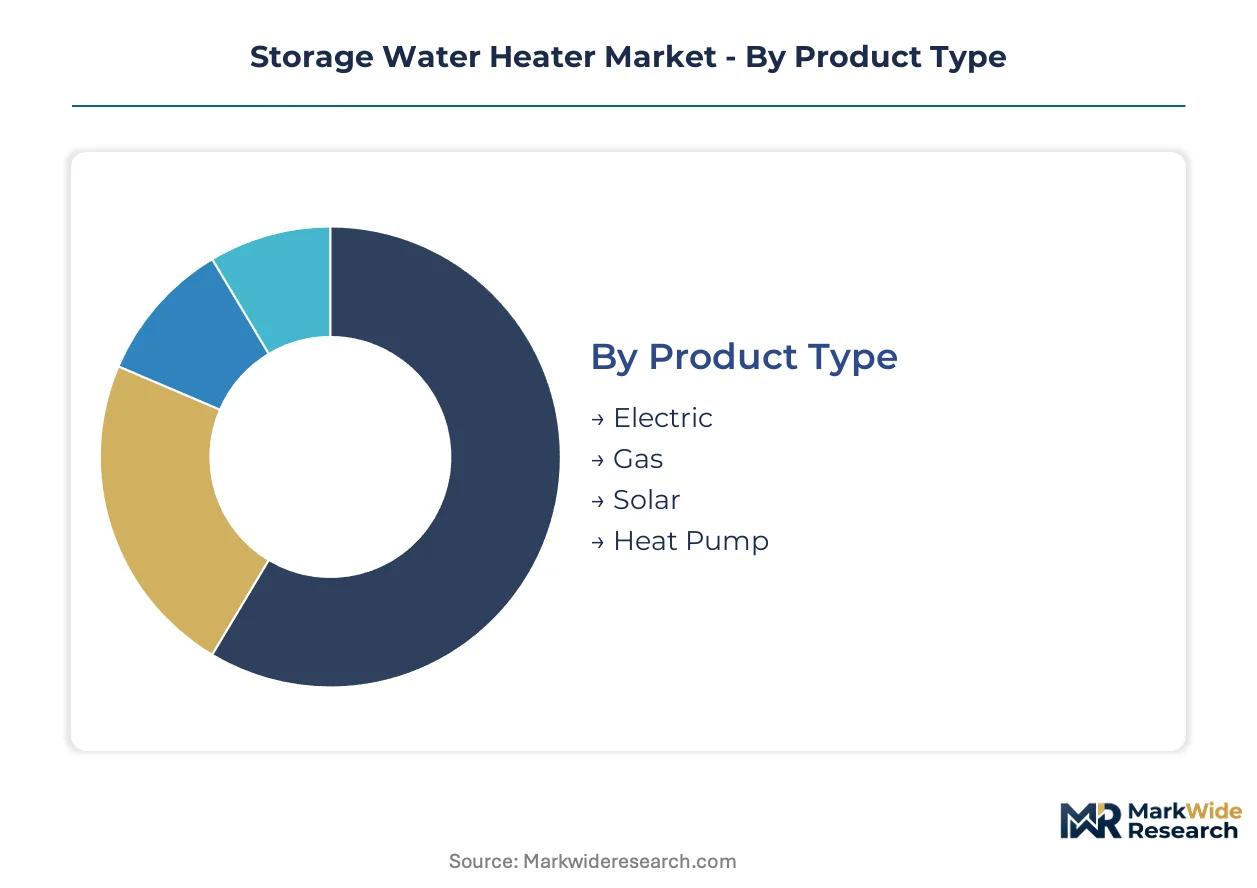
Storage water heater segmentation reveals divergent margin structures across technology platforms and installation contexts. Product type and capacity dimensions determine manufacturing footprint and distribution channel requirements. Installation type shapes service revenue potential and replacement cycle predictability.
Product Type:
Electric and gas variants dominate domestic replacement demand across North American and European residential channels. Heat pump and solar technologies concentrate in export-led premium specification markets driven by efficiency mandates.
- Electric:Resistance heating elements rated 3-5.5 kilowatts power glass-lined carbon steel tanks with magnesium anode corrosion protection. Demand concentrates in Indian urban housing markets where Bureau of Energy Efficiency star labeling accelerates replacement cycles in tier-2 and tier-3 cities.
- Gas:Atmospheric or power-vented burners with flue baffles maximize heat transfer efficiency in tank-based architectures. Residential contractors in Germany and France specify these for new multi-family construction at sustaining rates despite heat pump displacement pressure.
- Solar:Evacuated tube or flat-plate collector systems with integrated storage tanks serve off-grid and grid-tied installations. Southeast Asian residential construction in Vietnam and Thailand drives volume demand for thermosiphon configurations.
- Heat Pump:Compressor-driven systems extract ambient thermal energy at three to four times resistance element efficiency. European Union Ecodesign mandates and F-Gas Regulation compliance requirements create technology upgrade imperatives across member states.
Gas commands the established base. The steepest expansion runs through Heat Pump.
Installation Type:
Cost tier stratification separates high-recovery commercial units from standardized residential volumes. Industrial and portable segments occupy specialized procurement channels with distinct margin profiles.
- Residential:Standardized tank capacities serve single-family and multi-family dwellings through contractor and retail channels. Plumbing contractors in Texas and Florida are developing proprietary maintenance subscription models to recover recurring revenue streams displaced by digital marketplace equipment-only procurement.
- Commercial:High-recovery units with enhanced burner or element density serve hospitality and healthcare verticals. Premium specification tier generates higher per-unit value despite longer replacement cycles than residential segments.
- Industrial:Custom-engineered systems with ASME-rated pressure vessels serve process heating and washdown applications. Procurement concentrates through specified mechanical contractors with extended service agreements.
- Portable:Compact electric units with integrated heating elements serve construction sites, recreational vehicles, and temporary facilities. Distribution runs through equipment rental channels and direct consumer e-commerce.
Residential captures volume concentration. Commercial delivers margin expansion.
Energy Source:
Application context determines fuel selection with infrastructure availability as the binding constraint. Biomass and propane serve niche markets with limited grid connectivity or carbon reduction targets.
- Natural Gas:Pipeline-delivered fuel powers atmospheric and power-vented burner architectures. US Department of Energy appliance efficiency standards force insulation package and burner redesigns to meet escalating minimum performance thresholds.
- Propane:Stored fuel systems serve rural and off-grid installations without natural gas infrastructure. Demand clusters in North American exurban construction and European remote hospitality applications.
- Electricity:Grid-delivered power enables resistance element and heat pump configurations. India's government electrification programs create underpenetrated demand pools where star labeling mandates shape point-of-sale purchasing patterns.
- Biomass:Wood pellet or chip combustion systems serve carbon-neutral heating objectives in Central European residential markets. Regulatory support through national renewable heat incentives determines commercial viability.
Electricity anchors technology transition pathways. Natural gas retains installed base inertia.
Capacity:
Volume distribution correlates with dwelling unit size and peak demand profiles. Larger capacities concentrate in commercial and multi-family applications with recovery rate specifications.
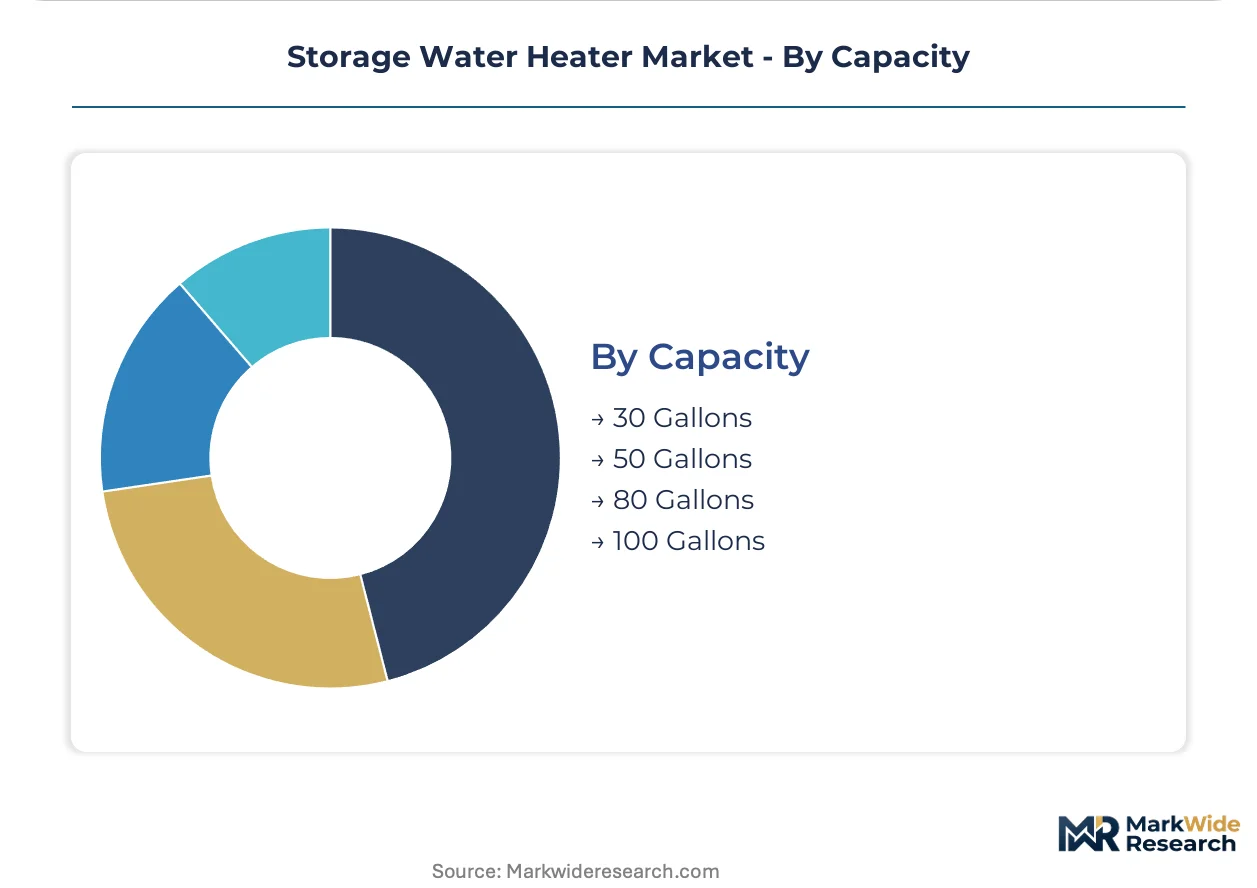
- 30 Gallons:Compact tanks serve single-occupancy dwellings and point-of-use installations. Urban housing deficits in Indian tier-2 cities drive specification for space-constrained apartments.
- 50 Gallons:Standard residential capacity balances first-hour rating against footprint constraints. Replacement cycles in North American single-family homes sustain manufacturing volumes for this specification.
- 80 Gallons:Enhanced storage serves large-family residences and light commercial applications. Higher thermal mass extends standby performance in high-use scenarios.
- 100 Gallons:Maximum residential and entry commercial capacity supports simultaneous fixture demand. Bradford White Corporation specializes in commercial-grade high-recovery variants occupying premium specification tier.
50 Gallons maintains volume leadership. 80 Gallons gains specification share in multi-family construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Bureau of Energy Efficiency star labeling program and the European Union Ecodesign Directive are reshaping procurement patterns across major demand centers. Government electrification programs and efficiency mandates are accelerating replacement cycles in urban housing markets.
United States
Residential contractors in Texas and Florida are developing proprietary maintenance subscription models to offset digital marketplace displacement. The US Department of Energy appliance efficiency standards force insulation package and burner redesigns to meet escalating minimum performance thresholds. Manufacturing clusters in the Midwest sustain captive foundry networks that anchor cost positions against import competition.
Germany
Residential contractors specify heat pump water heaters for new multi-family construction at accelerating rates despite higher upfront costs. The F-Gas Regulation tightens refrigerant phase-down schedules, forcing compressor package redesigns for lower-global-warming-potential alternatives. Industrial concentration in Bavaria and Baden-Württemberg supports integrated heat pump system assembly for export markets.
India
Urban housing deficits in tier-2 and tier-3 cities drive specification for compact 30-gallon tanks in space-constrained apartments. Government electrification programs create underpenetrated demand pools where Bureau of Energy Efficiency star labeling mandates shape point-of-sale purchasing patterns. Manufacturing clusters in Maharashtra and Gujarat concentrate glass-lined tank production for domestic replacement cycles.
Vietnam
Expanding residential construction across Ho Chi Minh City and Hanoi drives volume demand for thermosiphon solar configurations. National building efficiency codes incentivize solar-thermal integration in new multi-family developments. Provincial industrial zones near Da Nang are attracting component assembly operations for Southeast Asian export markets.
Netherlands
Commercial building operators face accelerated replacement deadlines under F-Gas Regulation compliance timelines. The Ecodesign Directive creates technology upgrade imperatives driving specification shifts toward compliant heat pump systems. The Randstad metropolitan corridor concentrates distribution infrastructure for Benelux retrofit channels.
Storage Water Heater Market Vendor Landscape
Player mix skews toward integrated manufacturers with captive foundry networks and regional specialists with distribution depth. Market structure consolidates around three strategic archetypes: vertically integrated tank fabricators, heat pump technology licensors, and commercial-grade specification specialists. Competitive moves concentrate on backward integration into steel forming capacity and strategic partnerships for refrigerant-compliant compressor sourcing.
Within the integrated-manufacturer tier, A.O. Smith and Rheem Manufacturing Company exemplify archetypes that anchor cost positions through in-house production of glass-lined vessels. Bradford White Corporation occupies a position among commercial-grade specification specialists serving hospitality and healthcare verticals. Ariston Holding N.V. and Bosch Thermotechnology sit within the European technology-licensor cluster, representing platforms that bridge efficiency-mandate compliance with modular system architectures.
| Leading Market Players |
|---|
| A.O. Smith |
| Rheem Manufacturing Company |
| Ariston Holding N.V. |
| Bosch Thermotechnology |
| Rinnai Corporation |
| Whirlpool Corporation |
| Havells India Limited |
| Bradford White Corporation |
| Viessmann Group |
| Others |
Supply Flow & Price Mechanics
Foundry utilization rates above 85 percent in Chinese and Indian captive steel-forming facilities create asymmetric cost positions that compress price floors for non-integrated manufacturers. Scale concentration in glass-lined tank production anchors supply-side pricing power while raw material volatility in steel and copper inputs forces margin management through specification tiering rather than uniform price increases.
Pricing Analysis
Certification level creates the primary spread between premium specification tiers and economy-grade residential volumes. The market operates on a three-tier pricing structure across ENERGY STAR-qualified, BEE star-labeled, and uncertified economy levels, with efficiency-grade differentiation widening as Ecodesign mandates tighten in the European Union. Pricing pressure stems from heat pump technology displacement of conventional tank margins, with residential contractors in price-sensitive Indian tier-2 and tier-3 cities driving volume toward lowest-first-cost options while commercial hospitality and healthcare buyers absorb premium positioning for high-recovery units.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for compressor and heat exchanger components sourced from East Asian manufacturing clusters. Supply concentrates in China for glass-lined carbon steel tank fabrication, India for resistance element assembly, and Germany for heat pump system integration, with raw material dependencies on copper wiring, magnesium anode rods, and refrigerant-grade aluminum. Single-source vulnerability in F-Gas-compliant compressor sourcing creates supply chain risk as regulatory phase-down deadlines accelerate. Distribution runs through contractor-specified channels in North America, retail point-of-sale in India, and specified mechanical procurement in European commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The storage water heater market tracks a cyclical recovery anchored to residential construction permit velocity and government electrification program funding cycles. Replacement demand in aging installed bases across North America and Europe provides countercyclical ballast against new construction volatility.
For Market Incumbents: Fortify captive foundry positions through in-house production expansion in Maharashtra and Gujarat to offset steel input volatility. Defend against heat pump technology displacement by accelerating BEE star-label certification investments for conventional electric portfolios. Channel control through proprietary maintenance subscription models recovers recurring revenue streams threatened by digital marketplace equipment-only procurement.
For New Entrants and Emerging Players: Lead with heat pump system architectures targeting F-Gas Regulation compliance deadlines in the Netherlands and Belgium where accelerated replacement timelines compress sales cycles. White-space concentration in Indian tier-2 urban housing deficits offers penetrable demand pools underserved by established distribution networks. Go-to-market execution through direct contractor training programs addresses installation complexity barriers that extend legacy player sales cycles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among commercial-grade specification specialists with extended service agreements in hospitality and healthcare verticals. Long-term viability across the analysis window favors acquisition targets with backward integration into steel forming capacity and refrigerant-compliant compressor sourcing partnerships. The signal to watch is Bureau of Energy Efficiency mandate expansion into rural electrification zones as an inflection indicator for volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Forming | Captive glass-lined tank production insulates margin positions against raw material volatility in Chinese import markets. |
| Heat Pump Technology Licensing | Modular compressor architectures from Bosch Thermotechnology accelerate Ecodesign compliance across European member states. |
| Maintenance Subscription Development | Texas and Florida plumbing contractors recover recurring revenue displaced by digital marketplace equipment-only procurement. |
| Refrigerant-Compliant Sourcing Partnerships | F-Gas Regulation phase-down schedules force redesign alliances for lower-global-warming-potential compressor alternatives. |
| Commercial High-Recovery Capacity Expansion | Bradford White Corporation's premium specification tier demonstrates higher per-unit value capture in hospitality verticals. |
Methodological Framework
Initial hypotheses were tested against primary input from residential contractor specification managers, commercial building operators, plumbing aftermarket service heads, and Bureau of Energy Efficiency compliance officers, and refined through secondary validation against customs trade data, BEE star-labeling registration databases, US Department of Energy appliance efficiency filings, and European Commission Ecodesign implementing measure texts. Bottom-up and top-down triangulation reconciled channel shipment volumes with regulatory mandate implementation timelines.
Variance decomposition across the projection horizon isolates technology substitution effects, regulatory mandate acceleration, and raw material cost pass-through as distinct forecast drivers. Segmentation dimensions modeled include product type, installation context, capacity tier, energy source, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis, new construction permit trajectories, and efficiency mandate compliance deadlines. Industry-specific inputs incorporated F-Gas Regulation phase-down schedules and BEE star-labeling penetration rates.
Forecasts assume regulatory continuity in US Department of Energy efficiency standards, European Union Ecodesign and F-Gas Regulation frameworks, and India's Bureau of Energy Efficiency labeling mandates; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Canada Electric Space Heater Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
Power Over Ethernet Lighting Market
Electrical Power Equipment
Electric Vehicle Charging Cables Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
Busway-Bus Duct Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Alternator Regulator Market