
 North America Protective Relays Market | 2026-2036
North America Protective Relays Market Size, Share, and Industry Trends Forecast 2026-2036
North America Protective Relays Market Analytics
Market Context
Modular relay platforms with integrated communications and condition monitoring is recalibrating how utilities evaluate total cost of ownership. Schweitzer Engineering Laboratories dominates North American digital relay supply through deep specialization in transmission-class protection. ABB Ltd leverages its installed base of electromechanical units to convert customers toward microprocessor-based replacements. Eaton Corporation anchors the industrial automation segment with panel-mounted configurations for heavy manufacturing.
Technical Definition and Segment Structure
Protective relays are electromechanical or solid-state devices that detect abnormal electrical conditions and initiate circuit isolation through breaker tripping, typically responding to overcurrent, differential, distance, or frequency disturbances within cycles. Digital and microprocessor-based relays now embed IEC 61850 communications protocols, enabling centralized substation automation and event logging. The product type mix shows electromechanical relays retaining share in legacy utility installations while microprocessor-based units capture all incremental growth from smart grid investments. Application demand skews toward transmission and distribution protection, where NERC reliability mandates drive replacement cycles, while industrial automation applications favor compact solid-state relays for motor protection and process continuity.
Regulatory Environment and Outlook
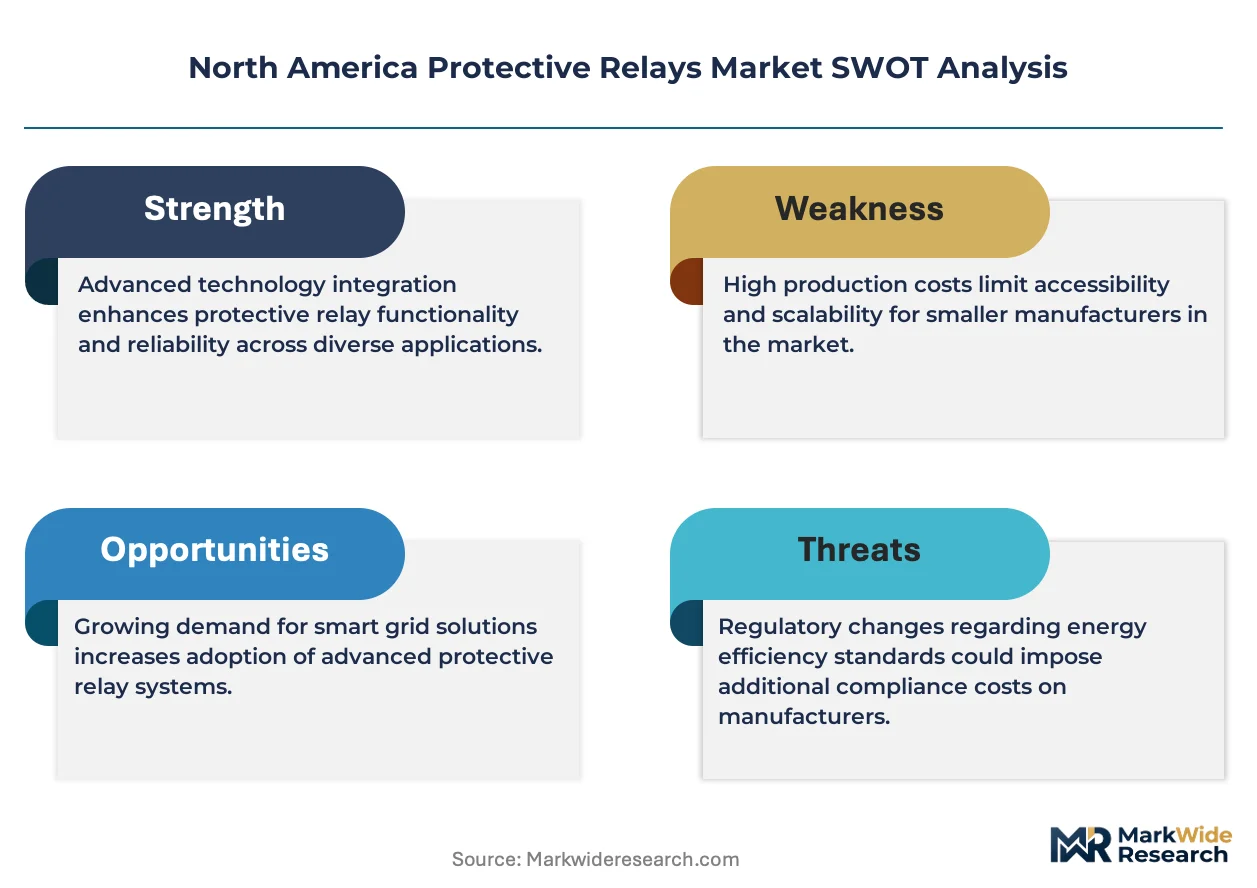
NERC CIP reliability standards and IEEE 1547 interconnection requirements shape product certification pathways and procurement specifications for North American utilities. FERC Order 2222 and state-level renewable portfolio standards in California, Texas, and New York are accelerating inverter-based resource interconnection, requiring advanced relay coordination against fault-induced inverter ride-through complexity. Stakeholders must monitor how distributed energy resource proliferation reshapes protection coordination studies and relay setting methodologies.
Market Dynamics
NERC reliability mandates and IEEE 1547 interconnection standards are forcing synchronous replacement of electromechanical protection schemes across United States and Canadian transmission networks. Utilities must modernize substation infrastructure to accommodate inverter-based renewable resources while maintaining grid stability.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation rules in the United States are mandating advanced relay coordination for inverter-dominated grids, expanding addressable demand for microprocessor-based protection platforms.
- Utility-scale solar clusters:Texas and California interconnection queues are driving procurement of transmission-class relays capable of managing fault-induced ride-through complexity from photovoltaic inverters.
- IEC 61850 protocol adoption:Ethernet-based substation automation architectures are enabling centralized event logging and remote setting management, reducing operational expenditure for North American grid operators.
Market Restraints
- Copper and semiconductor input volatility:Relay manufacturing depends on stable pricing for copper windings and silicon components, with supply concentration in East Asian foundries creating margin pressure.
- Legacy electromechanical installed base:Decades-old mechanical relays in rural cooperatives and municipal utilities resist replacement due to sunk capital and limited technical staffing for digital migration.
- NERC CIP cybersecurity compliance:Microprocessor-based relays require continuous firmware patching and network segmentation, adding operational burden that slows procurement cycles for smaller utilities.
Strategic Opportunities
- Canadian provincial grids:Ontario and Alberta transmission operators lag U.S. counterparts in digital relay penetration, presenting conversion opportunities as provincial regulators tighten renewable interconnection standards.
- Industrial microgrid protection:Manufacturing campuses and data centers are deploying island-capable relay schemes to ensure process continuity during utility disturbances, creating demand for compact panel-mounted configurations.
- Condition-based maintenance integration:Convergence of protective relaying with dissolved gas analysis and thermal monitoring is enabling predictive asset management contracts for transmission operators.
Industry Challenges
- Protection engineering talent scarcity:North American utilities face acute shortages of engineers capable of performing complex coordination studies for inverter-based resource interconnection.
- Legacy protocol interoperability:Migrating from electromechanical to digital architectures requires bridging DNP3 and Modbus installations with modern IEC 61850 networks, extending project timelines.
- Certification timeline compression:NERC and IEEE testing requirements for new relay firmware versions are lengthening product release cycles, constraining vendor responsiveness to emerging grid conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Protective Relays Market |
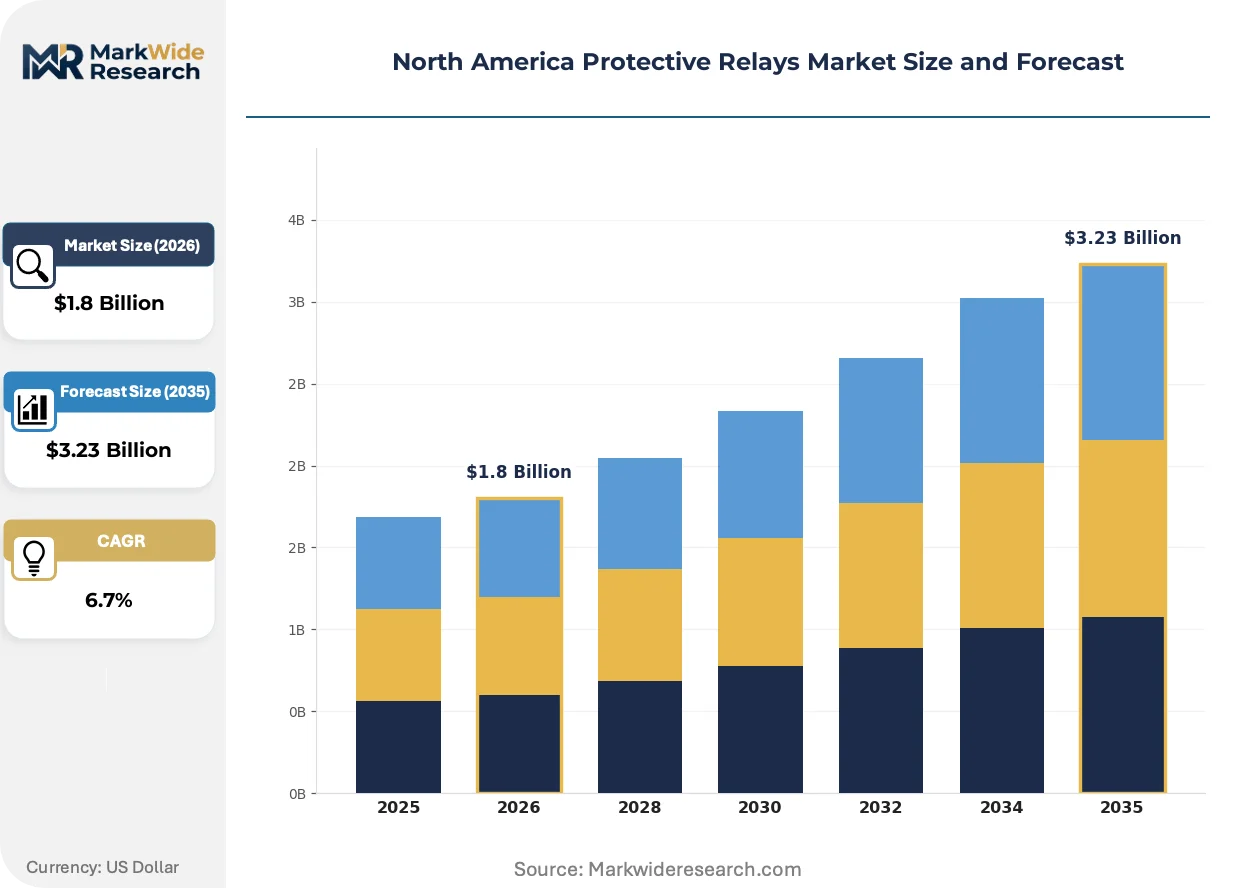
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical Relays, Solid State Relays, Digital Relays, Microprocessor-Based Relays Application: Power Generation, Transmission, Distribution, Industrial Automation End User: Utilities, Heavy Industries, OEMs, Commercial Buildings Installation Type: Indoor, Outdoor, Panel Mounted, Standalone |
| Companies Covered | Woodward Inc., Siemens AG, ABB Ltd, Littelfuse, Inc, General Electric, Schneider Electric SE, Eaton Corporation, Basler Electric, Schweitzer Engineering Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Protective Relays Market Evolving Landscape
Edge computing architectures and software-defined protection logic are restructuring how North American utilities deploy and manage substation automation. These shifts are compressing hardware replacement cycles while expanding service revenue opportunities for relay manufacturers.
Adaptive protection algorithms with machine learning-based fault classification are decentralizing decision-making authority from centralized control centers to substation edge devices. Transmission operators in Texas and California are piloting these systems to manage bi-directional power flows from distributed solar. The technology is decentralizing traditional protection coordination hierarchies, enabling faster fault isolation without upstream communication latency.
NERC CIP-013 supply chain risk management standards are mandating vendor security practices for critical cyber assets, including firmware provenance documentation and secure development lifecycle certification. Relay manufacturers must now embed hardware security modules and encrypted firmware update mechanisms. The regulation is most affecting smaller municipal utilities with limited cybersecurity staffing, forcing them toward bundled managed security services.
Performance-based procurement contracts are displacing traditional capital equipment purchases for transmission protection systems. Grid operators in the U.S. Southeast are contracting relay functionality as subscription services covering hardware, software, and engineering support. This shift is most visible among cooperative utilities seeking to convert fixed capital outlays into operational expenditures aligned with rate-case timelines.
North America Protective Relays Market Segmentation
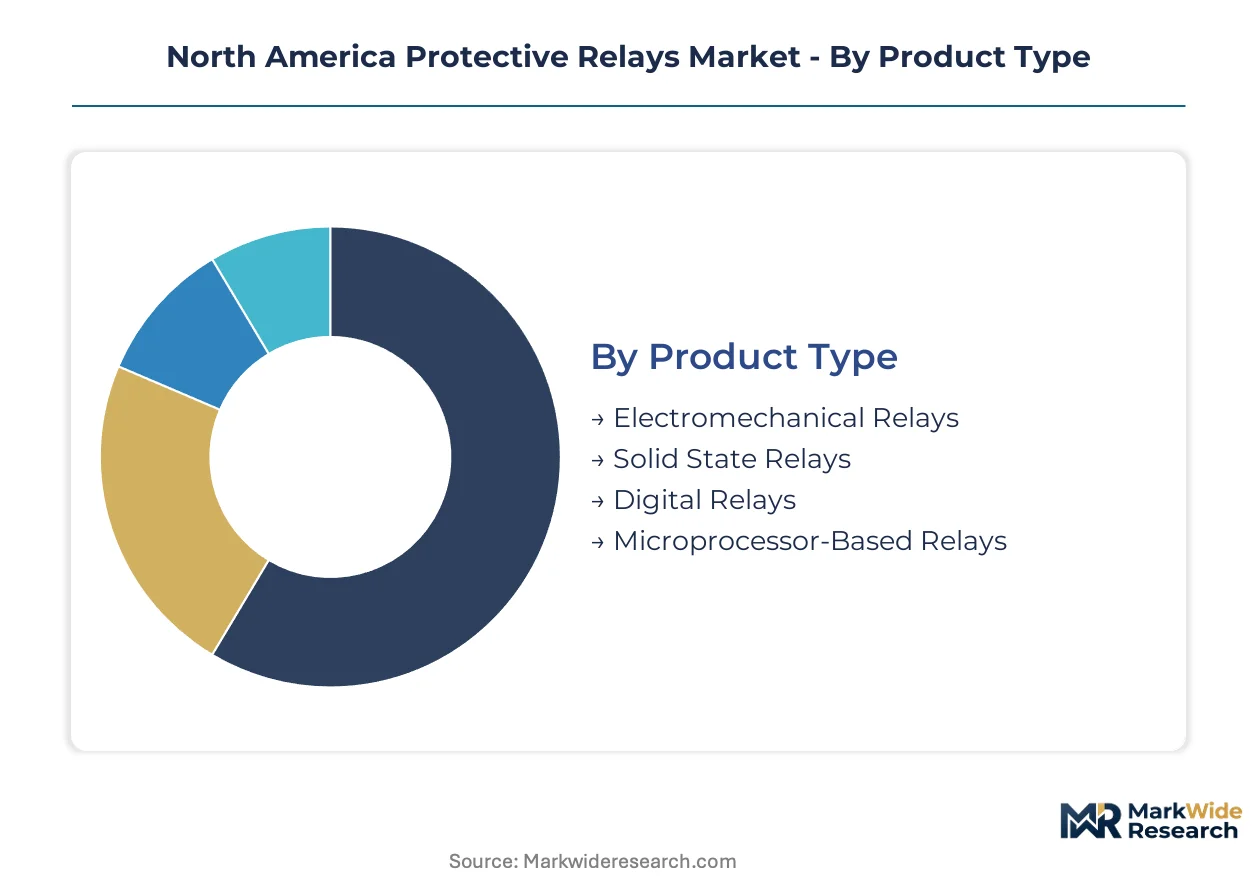
Segmentation in protective relays reveals how technology migration, regulatory pressure, and end-use economics fragment procurement patterns. Understanding these divisions clarifies why microprocessor-based units command premium positioning while electromechanical variants persist in cost-constrained installations.
Product Type:
Customization intensity spans from fully configurable microprocessor platforms to standardized electromechanical designs with fixed characteristic curves.
- Electromechanical Relays:Mechanical induction-disk or plunger mechanisms with discrete component timing. Demand concentrates in rural cooperatives across the U.S. Great Plains and Canadian Prairie provinces, where capital constraints and limited technical staffing slow digital migration despite NERC pressure.
- Microprocessor-Based Relays:Software-configurable protection logic with IEC 61850 communications and adaptive setting capabilities. Procurement concentrates in Texas ERCOT interconnection zones and California ISO territories, where utility-scale solar clusters require sophisticated fault ride-through coordination against inverter-induced disturbances.
- Solid State Relays:Thyristor-based switching without moving parts, suited for high-cycle industrial applications.
- Digital Relays:Early-generation microprocessor units with fixed firmware, bridging legacy and modern architectures in municipal utility fleets.
Most installed capacity flows through Electromechanical Relays. Expansion is steepest in Microprocessor-Based Relays.
Application:
Volume distribution tracks directly to regulatory exposure, with NERC-mandated transmission protection commanding the highest per-unit values.
- Transmission:Distance and differential protection for high-voltage lines above 69kV. Procurement clusters in the U.S. Southeast and Texas, where regional transmission organizations enforce strict fault-clearing timelines under NERC TPL and PRC standards.
- Industrial Automation:Motor protection and process continuity schemes for heavy manufacturing. Demand localizes in Ohio, Michigan, and Ontario automotive corridors, where Eaton and Rockwell Automation specify panel-mounted configurations for plant-floor integration.
- Power Generation:Generator protection and intertie schemes for central station and distributed resources.
- Distribution:Feeder and recloser control for medium-voltage networks, spanning investor-owned utilities and municipal operators.
Transmission captures the highest unit margins. Industrial Automation shows the fastest volume expansion trajectory among application categories.
End User:
Customer sophistication determines specification complexity, with investor-owned utilities demanding full IEC 61850 integration while commercial buyers prioritize cost and footprint.
- Utilities:Investor-owned, municipal, and cooperative grid operators subject to NERC reliability mandates. Procurement concentrates in FERC-jurisdictional territories, where CIP-013 supply chain security requirements now shape vendor qualification.
- Heavy Industries:Petrochemical, mining, and pulp-and-paper operations with captive generation and islanding requirements. Demand localizes in Alberta oil sands and Louisiana Gulf Coast refining complexes.
- OEMs:Switchgear and transformer manufacturers integrating protection into factory-built assemblies.
- Commercial Buildings:Data centers and healthcare facilities requiring selective coordination for critical power.
Utilities account for the dominant installed base. Heavy Industries are gaining share fastest as process continuity economics justify premium protection investments.
Installation Type:
Physical deployment constraints vary sharply between greenfield substations with climate-controlled enclosures and retrofit projects demanding minimal footprint disruption.
- Panel Mounted:DIN-rail or chassis-integrated configurations for industrial control centers and distribution switchgear. Demand concentrates in Great Lakes manufacturing belts and Mexican maquiladora corridors, where space constraints and vibration resistance specifications favor compact solid-state designs.
- Outdoor:NEMA-rated enclosures for transmission substations and distribution reclosers exposed to environmental extremes. Procurement clusters in Gulf Coast and Desert Southwest utilities, where temperature cycling and humidity drive specification toward conformal-coated electronics.
- Indoor:Climate-controlled substation house installations with conventional relay racks.
- Standalone:Self-enclosed units for temporary protection or mobile substation applications.
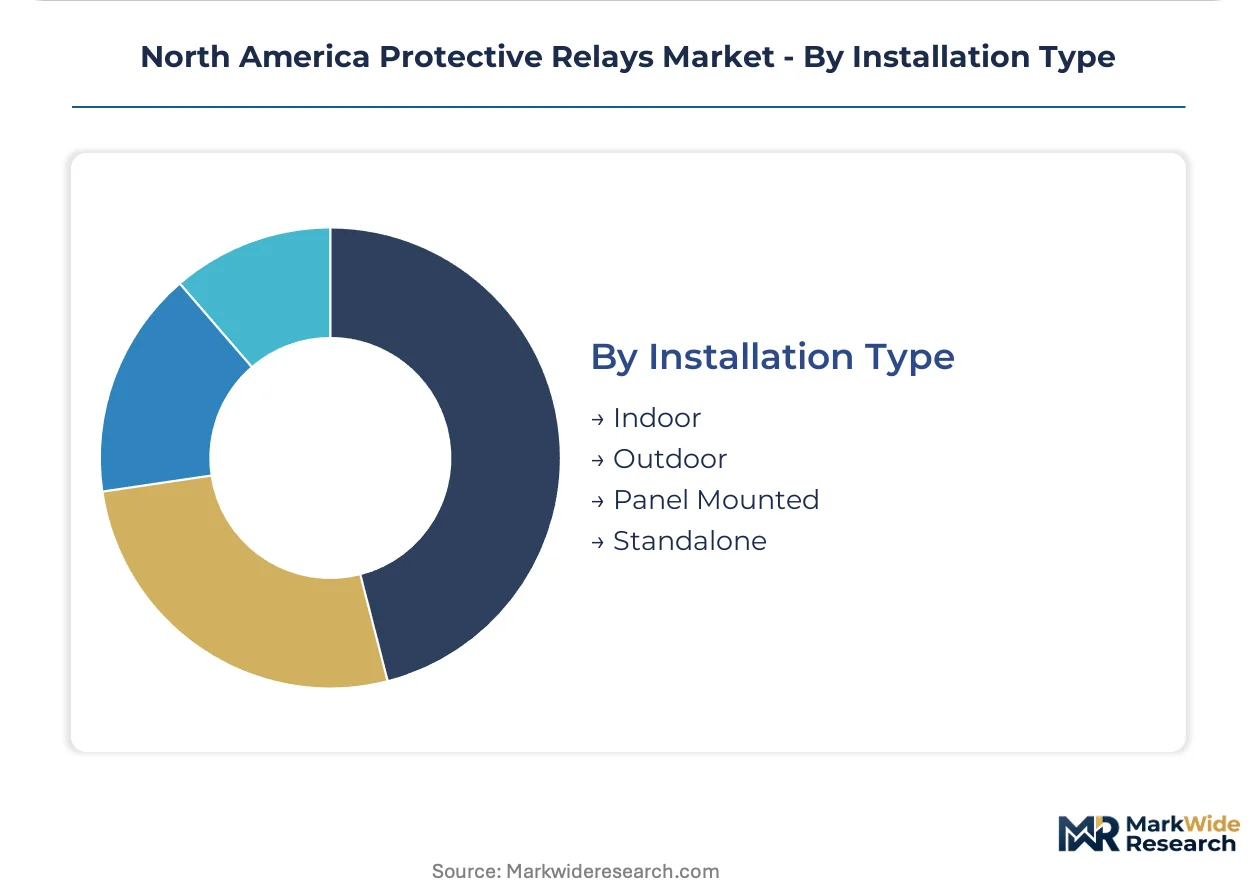
Panel Mounted configurations dominate industrial segments. Outdoor installations are climbing the fastest among installation categories as transmission utilities accelerate rural substation hardening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American protective relays industry traces its commercial roots to early 20th-century electromechanical manufacturing clusters in the U.S. Midwest, where industrial electrification first demanded standardized fault protection equipment.
United States
Texas ERCOT interconnection zones and California ISO territories drive procurement of transmission-class microprocessor relays for utility-scale solar clusters. FERC Order 2222 mandates advanced relay coordination for distributed energy resource aggregation. Houston and Los Angeles metropolitan areas concentrate engineering talent for inverter-dominated grid protection studies.
Canada
Ontario and Alberta transmission operators lag U.S. counterparts in digital relay penetration, creating conversion opportunities as provincial regulators tighten renewable interconnection standards. The Canadian Energy Association coordinates reliability requirements across provincial grids. Calgary and Toronto engineering centers specialize in cold-climate outdoor relay specifications for Arctic substation deployments.
Mexico
CFE transmission modernization programs accelerate electromechanical replacement in the Bajío industrial corridor and northern border states. Mexico's Energy Regulatory Commission implements IEEE-based interconnection standards for private renewable projects. Monterrey and Querétaro manufacturing clusters demand compact panel-mounted relays for automotive supplier microgrids.
North America Protective Relays Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical specialization depth and NERC certification complexity. The vendor base stratifies between transmission-class specialists with deep utility relationships and industrial automation generalists serving manufacturing segments. Three archetypes dominate: vertically integrated electrical conglomerates with broad power portfolio coverage, focused relay specialists with concentrated protection engineering expertise, and industrial automation suppliers leveraging cross-selling into plant-floor protection. Capacity expansion and strategic technology licensing represent the dominant competitive moves as vendors position for IEC 61850 protocol standardization.
Within the specialist tier, Schweitzer Engineering Laboratories and Basler Electric exemplify concentrated protection engineering focus, while Siemens AG and ABB Ltd occupy positions as diversified electrical equipment conglomerates with relay divisions embedded within broader power automation portfolios. Eaton Corporation anchors the industrial automation vector with manufacturing-centric protection configurations.
| Leading Market Players |
|---|
| Woodward Inc. |
| Siemens AG |
| ABB Ltd |
| Littelfuse, Inc |
| General Electric |
| Schneider Electric SE |
| Eaton Corporation |
| Basler Electric |
| Schweitzer Engineering Laboratories |
| Others |
Value Network & Pricing Analysis
Copper winding costs cascade from Chilean and Peruvian mining operations through East Asian semiconductor foundries into three-tier pricing stratification across transmission-class, distribution-grade, and industrial panel-mounted relay configurations. NERC CIP-013 cybersecurity certification requirements now separate premium microprocessor platforms from standard digital units and economy electromechanical replacements.
Pricing Analysis
Subscription-based performance contracts for transmission protection systems are displacing capital equipment purchases across cooperative utilities seeking operational expenditure alignment. Price differentiation hinges on IEC 61850 protocol integration depth and NERC certification tier, with Texas ERCOT interconnection projects commanding premium positioning over rural municipal deployments. Cost compression in standard-tier digital relays stems from Taiwanese foundry capacity expansion and semiconductor input softening. Rural cooperatives exhibit highest price sensitivity due to rate-case constraints, while investor-owned utilities prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific semiconductor hubs to North American assembly plants is amplifying margin pressure on relay manufacturers dependent on just-in-time component flows. Silicon components and copper windings draw from concentrated East Asian foundry and South American mining networks, creating single-source vulnerability for critical microprocessor and analog front-end supplies. Distribution runs through authorized electrical distributor networks serving utility procurement departments, with direct OEM relationships dominating industrial automation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NERC PRC-026 relay coordination mandates create synchronous replacement demand across electromechanical installed bases.
For Market Incumbents: Hedge firmware vulnerability exposure through captive semiconductor sourcing partnerships with Taiwanese foundries qualified under CIP-013 supply chain risk standards. Deepen backward integration into copper winding manufacturing to buffer commodity volatility threatening standard-tier margins. Reinforce utility relationships via managed security service bundles addressing smaller municipal cybersecurity staffing gaps. For New Entrants and Emerging Players: Direct-to-utility digital sales channels bypassing incumbent distributor networks offer white-space access in Canadian provincial markets lagging U.S. digital penetration. Target Alberta and Ontario transmission operators facing renewable interconnection standard tightening with IEC 61850-native platforms priced below Schweitzer and ABB incumbent offerings. Lead with condition-based maintenance integration as differentiated value proposition against capital-equipment-focused legacy vendors. For Investors and Strategic Acquirers: Consolidation pressure builds where NERC certification complexity creates capability moats around transmission-class specialists with deep utility relationships. Five-to-ten year viability favors vendors with software-defined protection architectures capable of absorbing machine learning-based fault classification shifts. Monitor FERC Order 2222 implementation velocity across state regulatory commissions as demand inflection signal for distributed energy resource protection coordination tools.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61850 Protocol Certification | Enables Ethernet-based substation automation architectures reducing operational expenditure for ERCOT and CAISO grid operators. |
| Managed Security Service Bundling | Addresses NERC CIP-013 compliance burden for municipal utilities with limited cybersecurity staffing resources. |
| Condition-Based Maintenance Integration | Converges protective relaying with dissolved gas analysis enabling predictive asset contracts for transmission operators. |
| Canadian Provincial Market Entry | Captures conversion opportunity as Ontario and Alberta regulators tighten renewable interconnection standards. |
| Industrial Microgrid Protection Development | Serves manufacturing campuses and data centers deploying island-capable relay schemes for process continuity. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with transmission planning engineers, substation protection specialists, utility procurement managers, and relay manufacturer product directors combined with secondary validation from FERC interconnection queue databases, NERC reliability standards filings, IEEE working group documentation, and utility rate-case filings. Triangulation across these sources yields volume estimates segmented by product type, application, end user, and installation configuration.
Historical trendline analysis of electromechanical-to-digital replacement cycles informs the projection framework across the analysis window. Segmentation dimensions include relay technology tier, voltage class application, utility ownership structure, and regional regulatory framework. CAGRs derive from regression analysis of utility capital expenditure patterns and renewable interconnection queue growth. Forecast inputs incorporate NERC reliability mandate implementation schedules and provincial renewable portfolio standard adoption trajectories.
The model assumes a particular technology adoption path; alternative pathways for adaptive protection algorithms with machine learning-based fault classification would alter the outlook. Forecasts reflect assumptions regarding FERC Order 2222 implementation velocity and copper-semiconductor input price stability. A model refresh is warranted upon material change in NERC reliability standard enforcement intensity or distributed energy resource interconnection volume thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
Europe Alternating Current (AC) Drive Market
Electrical Power Equipment
Storage Water Heater Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
US Air Filter Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
Electric Insulator Market
Electrical Power Equipment
AC Drives Market