
 Digital Fault Recorder (DFR) Market | 2026-2036
Digital Fault Recorder (DFR) Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Fault Recorder (DFR) Market Outlook
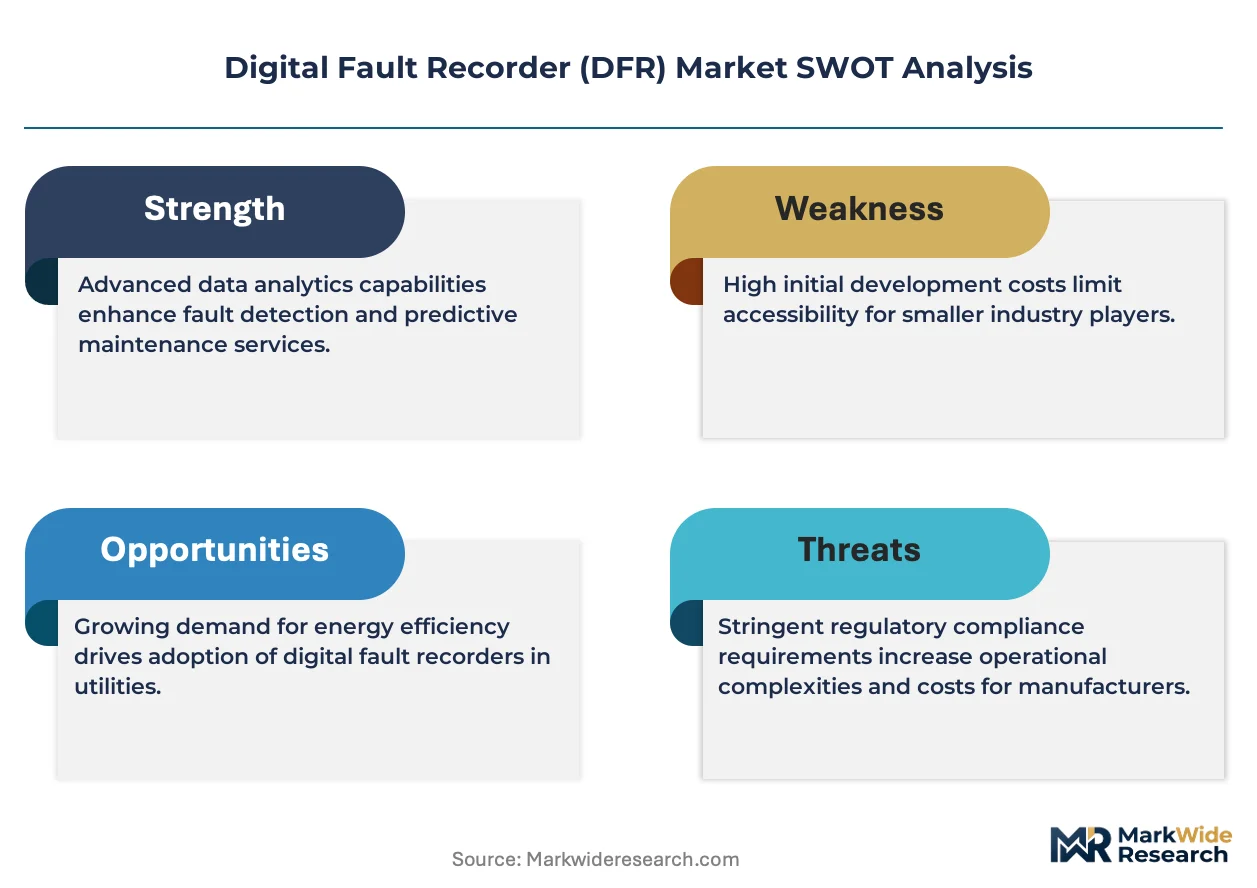
The gap between legacy analog architectures and digital substation standards is narrowing as utilities retrofit protection systems. Schweitzer Engineering Laboratories leads substation automation integration through its relay-to-recorder platforms. ABB Ltd. leverages its installed base of protection equipment to cross-sell modular DFR upgrades. Siemens AG sustains competitive positioning with IEC 61850-certified product lines across European transmission operators.
A Digital Fault Recorder captures high-resolution voltage and current waveforms during power system disturbances at sampling rates exceeding 256 samples per cycle, enabling post-event analysis for protection coordination and equipment diagnostics. Stationary DFR units dominate utility substation deployments due to permanent installation requirements and hardened environmental specifications. Cloud-Based Technology represents the fastest-expanding segment as operators seek centralized fleet analytics and remote waveform access without on-premise storage infrastructure.
North American utilities navigate NERC PRC-002-2 disturbance monitoring requirements that mandate sustained fault recording capabilities across bulk power system nodes. European grid operators face EU Green Deal-aligned network codes requiring enhanced observability for renewable integration zones. Stakeholders must weigh capital expenditure cycles against accelerating software-defined recorder architectures that promise faster deployment but demand cybersecurity compliance with evolving IEC 62351 standards.
Market Dynamics
The Digital Fault Recorder market pivots on the collision between legacy substation hardening requirements and software-defined architectures that promise faster deployment cycles. Utilities must reconcile decades-old protection coordination protocols with IEC 61850 digital substation mandates that demand waveform analytics integration.
Growth Catalysts
- NERC PRC-002-2 mandates:Bulk power system operators across the United States face compulsory disturbance monitoring upgrades, forcing sustained capital deployment into stationary recording infrastructure.
- EU Green Deal network codes:European transmission operators must enhance observability in renewable integration zones, creating regulatory pull for high-resolution waveform capture systems.
- Cloud-Based Technology adoption:Centralized fleet analytics platforms enable remote waveform access without on-premise storage, accelerating replacement of localized analog recorder banks.
Market Restraints
- Copper and rare earth input volatility:Hardened DFR enclosures and magnetic components face raw material cost swings that compress hardware margins.
- Supply concentration in semiconductor foundries:High-speed analog-to-digital converters and FPGA chips concentrate in East Asian fabrication facilities, exposing procurement to geopolitical friction.
- IEC 62351 cybersecurity compliance:Evolving encryption and access control standards extend certification timelines and inflate engineering overhead for new product introductions.
Strategic Opportunities
- India transmission modernization:Central Electricity Authority mandates for grid stability monitoring create underpenetrated demand for IEC 61850-compliant DFR deployments in substation retrofits.
- Edge-to-cloud convergence:Integration of time-synchronized edge recording with centralized AI analytics platforms opens subscription revenue models beyond hardware sales.
- Distribution network extension:Medium-voltage grid operators in Germany and California seek portable DFR units for distributed energy resource interconnection testing.
Industry Challenges
- Substation automation engineering scarcity:Utilities and vendors compete for limited talent pools capable of configuring IEC 61850 GOOSE messaging and sampled value streams.
- Legacy protection system interoperability:Retrofit projects require complex protocol translation between modern DFR units and decades-old relay communication schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Fault Recorder (DFR) Market |
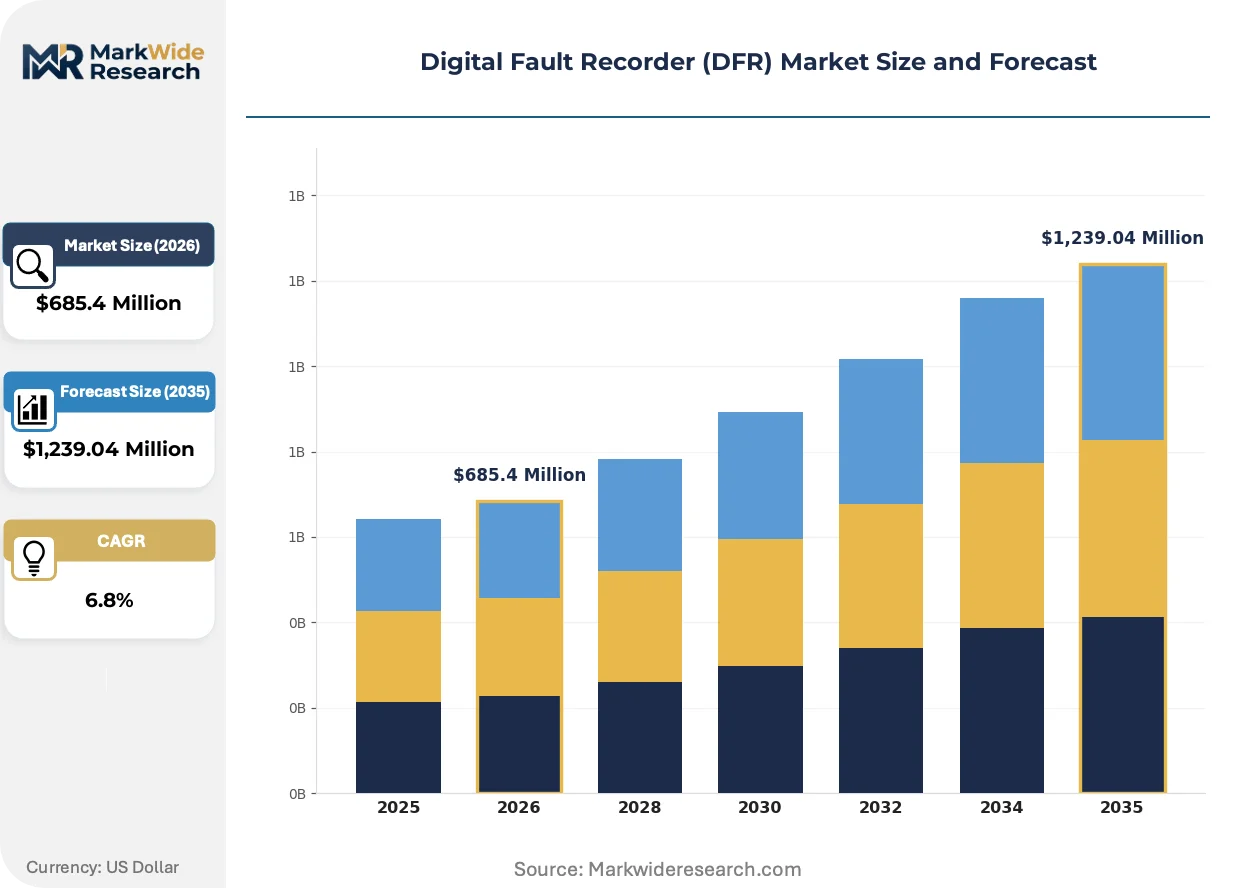
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary DFR, Portable DFR, Wireless DFR, Modular DFR Technology: Analog Technology, Digital Technology, Hybrid Technology, Cloud-Based Technology End User: Utilities, Oil & Gas, Manufacturing, Transportation Application: Power Quality Monitoring, Fault Detection, Performance Analysis, Data Analysis |
| Companies Covered | AMETEK, Schweitzer Engineering Laboratories, Qualitrol Company LLC, ERLPhase Power Technologies, Hitachi Energy Ltd., GE Vernova, ABB Ltd., KoCoS Messtechnik AG, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Fault Recorder (DFR) Market Strategic Shifts
Waveform analytics capabilities are migrating from post-event forensic tools to real-time grid intelligence platforms. Three developments are compressing product lifecycles and reshaping competitive positioning.
Time-synchronized phasor measurement integration is migrating from standalone PMU networks to consolidated DFR-PMU hybrid platforms. Transmission operators in Texas and Scandinavia now demand unified disturbance recording and wide-area situational awareness from single hardware deployments. This convergence is compressing the addressable market for dedicated phasor measurement units while elevating software complexity requirements for recorder vendors.
The EU Cybersecurity Act and accompanying IEC 62443-3-3 zone model are mandating encrypted firmware and secure boot capabilities for critical infrastructure components. European transmission operators now exclude uncertified recorders from tender processes. Vendors are responding by hardening Linux-based recorder operating systems and establishing dedicated EU cybersecurity certification tracks.
Subscription-based waveform analytics services are displacing perpetual license models for enterprise fleet management. North American municipal utilities and generation operators now favor operational expenditure structures that bundle hardware, cloud storage, and AI-assisted disturbance classification. This shift pressures traditional equipment vendors to build software service organizations or partner with specialized analytics platforms.
Digital Fault Recorder (DFR) Market Segmentation
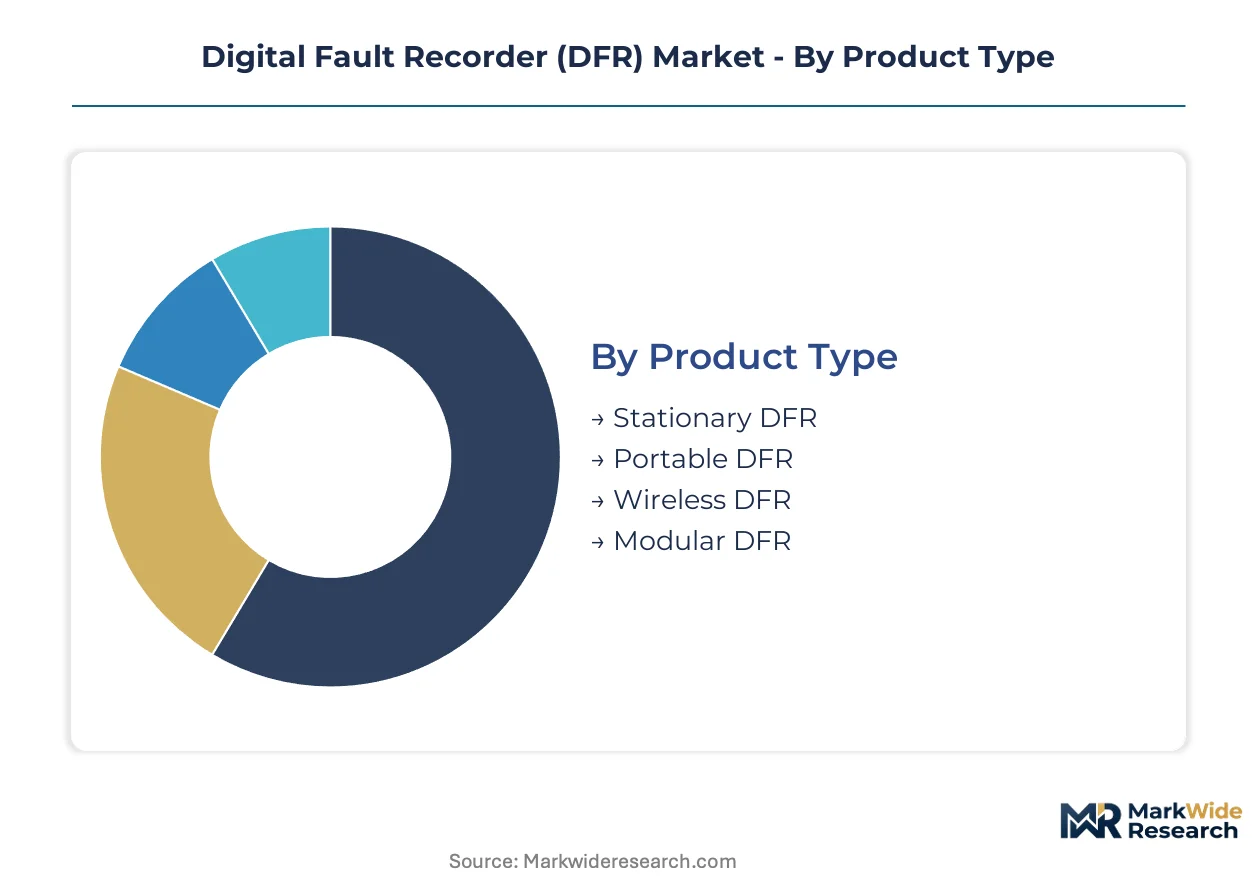
DFR procurement patterns diverge sharply across deployment contexts. Stationary installations face decade-long replacement cycles tied to substation capital planning, while portable and wireless units turn over faster as field testing protocols evolve.
Product Type:
Replacement velocity separates permanent infrastructure from mobile diagnostic equipment. Stationary units anchor utility balance sheets through depreciation schedules spanning fifteen years or more. Portable and wireless alternatives refresh every three to five years as semiconductor and battery improvements compound.
- Stationary DFR:Hardened enclosures withstand temperature extremes, vibration, and electromagnetic interference across utility substations. United States transmission operators deploy these for NERC PRC-002-2 compliance, with procurement locked to five-year capital planning horizons.
- Portable DFR:Battery-powered units enable temporary deployment for commissioning tests and disturbance investigations. German distribution network operators favor these for distributed energy resource interconnection validation, where mobility outweighs sampling precision.
- Wireless DFR:Cellular or mesh-networked recorders eliminate copper cabling in retrofit installations. These units gain traction where trenching costs dominate project economics.
- Modular DFR:Rack-mounted chassis accept hot-swappable input cards for channel expansion. These configurations suit industrial facilities with evolving protection zone requirements.
Stationary DFR dominates installed base. Portable DFR is where expansion concentrates.
Technology:
Cost tier stratification separates legacy analog maintenance from digital upgrade investments. Analog systems burden operators with calibration labor and tape-based storage. Digital and cloud architectures command premium upfront expenditure but compress total cost of ownership through automated analysis and remote accessibility.
- Analog Technology:Tape-based waveform capture and electromechanical triggering persist in aging infrastructure. These systems concentrate in developing economy utilities with constrained capital budgets and minimal cybersecurity exposure.
- Digital Technology:Microprocessor-based sampling with solid-state storage enables IEC 61850 protocol integration. Chinese grid operators mandate these for new substation construction under dual carbon grid modernization directives.
- Hybrid Technology:Combines analog front-end conditioning with digital back-end processing for transitional deployments. These units bridge legacy relay communication schemes and modern substation automation architectures.
- Cloud-Based Technology:Edge recording with centralized fleet analytics eliminates on-premise storage infrastructure. This segment is climbing the fastest as municipal utilities in California and Texas adopt subscription operational expenditure models.
Digital Technology anchors current procurement. Cloud-Based Technology is where vendor R&D concentrates.
End User:
Application maturity varies across sector risk tolerance and regulatory exposure. Utilities face mandatory disturbance monitoring standards. Industrial users prioritize equipment protection over grid-wide observability.
- Utilities:Transmission and distribution operators deploy DFRs for protection coordination studies and regulatory compliance. FERC-jurisdictioned entities in the United States sustain the largest addressable demand through NERC enforcement.
- Oil & Gas:Pipeline compressor stations and offshore platforms require fault recording for motor protection and power quality verification. These installations favor explosion-proof stationary units with extended temperature ratings.
- Manufacturing:Semiconductor fabs and automotive plants use DFRs to isolate voltage sag sources that disrupt sensitive process equipment. These users prioritize high sampling rates over long-term waveform retention.
- Transportation:Electrified rail networks and EV charging infrastructure operators deploy portable units for commissioning and troubleshooting. Traction power system harmonics drive specialized filtering requirements.
Utilities dominate installed base. Manufacturing is where pricing premiums concentrate.
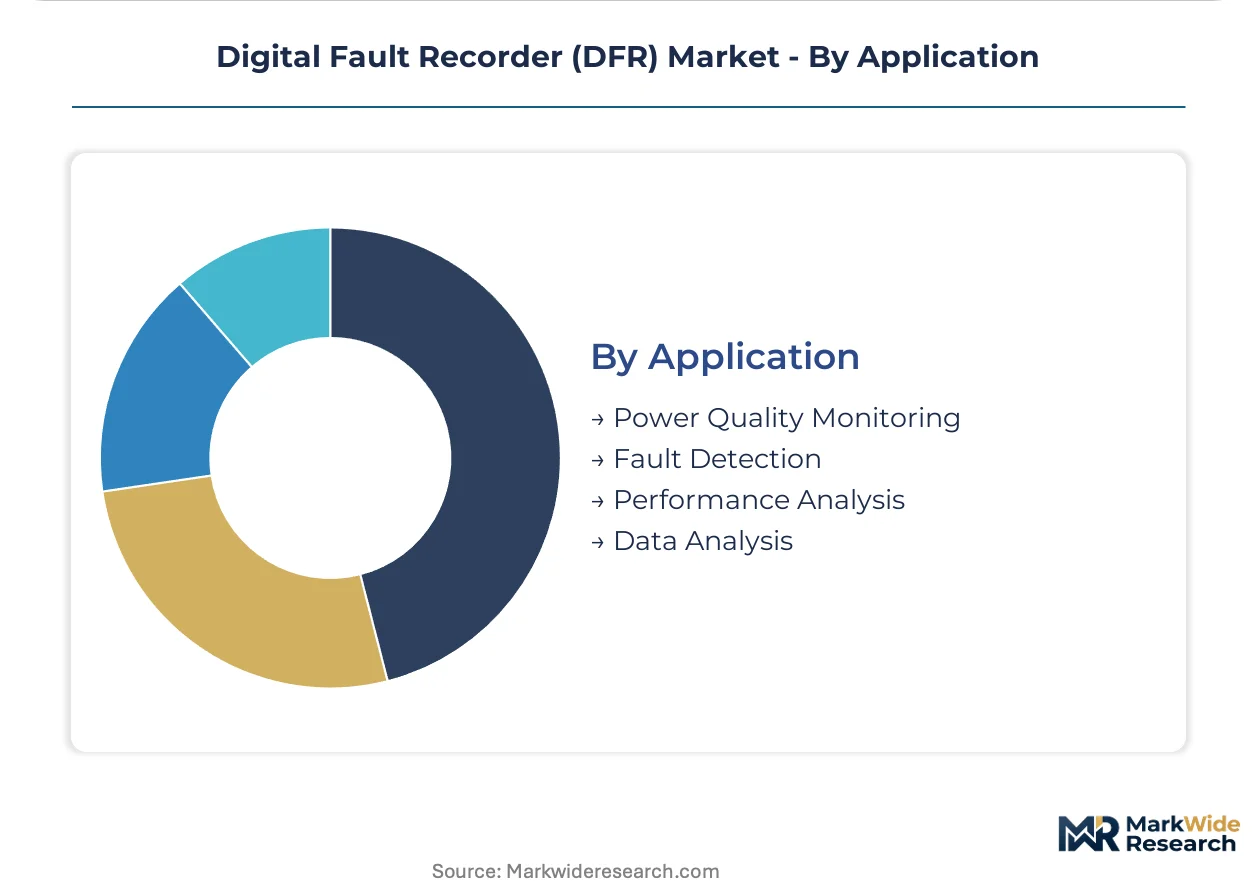
Application:
Volume distribution skews toward reactive fault investigation over proactive power quality management. Post-event analysis remains the default procurement justification. Real-time monitoring applications require higher channel counts and faster networking infrastructure.
- Power Quality Monitoring:Continuous sag, swell, and harmonic tracking for industrial and commercial facilities. These deployments integrate with building management systems and energy management platforms.
- Fault Detection:High-speed triggering on overcurrent, undervoltage, and frequency deviation events. This application anchors utility procurement specifications and defines baseline channel count requirements.
- Performance Analysis:Protection relay coordination verification and breaker operation timing studies. These applications demand time-synchronized multi-channel recording across geographically separated substations.
- Data Analysis:AI-assisted disturbance classification and predictive maintenance algorithms. This segment is gaining share fastest as cloud analytics platforms mature.
Fault Detection dominates installed base. Data Analysis is where software differentiation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing of high-speed analog-to-digital converters and FPGA components concentrates in East Asian fabrication facilities, while DFR system integration and deployment revenues flow toward transmission operators in North America and Europe. Import dependency for semiconductor inputs shapes procurement timelines across utility sectors.
United States
FERC-jurisdictioned entities sustain the largest addressable demand through NERC PRC-002-2 enforcement, which mandates sustained fault recording capabilities across bulk power system nodes. Texas transmission operators now demand unified disturbance recording and wide-area situational awareness from consolidated DFR-PMU hybrid platforms. California municipal utilities favor subscription operational expenditure models that bundle hardware, cloud storage, and AI-assisted disturbance classification.
Germany
Distribution network operators seek portable DFR units for distributed energy resource interconnection testing, where mobility outweighs sampling precision. The EU Cybersecurity Act and accompanying IEC 62443-3-3 zone model mandate encrypted firmware and secure boot capabilities, excluding uncertified recorders from tender processes. Industrial facilities in Baden-Württemberg deploy rack-mounted modular configurations with hot-swappable input cards for evolving protection zone requirements.
China
Grid operators mandate digital DFR architectures for new substation construction under dual carbon grid modernization directives. The Central Electricity Authority framework drives demand for IEC 61850-compliant deployments in substation retrofits across provincial transmission networks. Manufacturing clusters in the Yangtze River Delta supply hardened enclosures and magnetic components facing raw material cost volatility.
India
Central Electricity Authority mandates for grid stability monitoring create underpenetrated demand for IEC 61850-compliant DFR deployments in substation retrofits. State transmission utilities in Maharashtra and Gujarat prioritize transmission network reliability through protection coordination studies. Renewable integration zones in Rajasthan and Tamil Nadu require enhanced observability for variable generation forecasting.
Digital Fault Recorder (DFR) Market Competitive Environment
On the supply side, the industry is moderately consolidated around integrated electrical equipment conglomerates with legacy protection equipment installed bases and specialized substation automation firms with relay-to-recorder platform expertise. Strategic archetypes include full-spectrum automation integrators leveraging cross-sell opportunities, modular hardware specialists targeting retrofit flexibility, and cloud-native analytics platforms pursuing subscription revenue conversion. Dominant competitive moves encompass IEC 61850 certification racing across European transmission operator tender processes and cybersecurity hardening investments to meet evolving IEC 62351 and IEC 62443-3-3 standards.
Within the integrated automation tier, ABB Ltd. and Siemens AG occupy positions anchored by protection equipment installed bases that facilitate modular DFR upgrade pathways. Schweitzer Engineering Laboratories exemplifies the relay-to-recorder platform specialist archetype through substation automation integration capabilities. These three entities represent distinct strategic vectors: cross-selling from legacy protection footprints, certified product line breadth across European operators, and unified hardware-software platform convergence.
| Leading Market Players |
|---|
| AMETEK |
| Schweitzer Engineering Laboratories |
| Qualitrol Company LLC |
| ERLPhase Power Technologies |
| Hitachi Energy Ltd. |
| GE Vernova |
| ABB Ltd. |
| KoCoS Messtechnik AG |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta manufacturing cluster anchors global supply of hardened DFR enclosures and magnetic components, with capacity utilization swings in this region translating directly into downstream pricing leverage for system integrators. Semiconductor foundry constraints in East Asia compound input cost volatility, forcing DFR vendors to absorb margin compression or pass through component premiums to transmission operators locked in multi-year capital planning cycles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by IEC 61850 certification grade and after-sales service bundling. Cloud-based subscription models are displacing perpetual licenses in North American municipal utilities, compressing upfront hardware margins while extending customer lifetime value. Pricing pressure stems from raw material volatility in copper and rare earth inputs, with developing economy utilities exhibiting highest price sensitivity due to capital budget constraints.
Supply Chain Analysis
Export controls on high-speed analog-to-digital converters and FPGA technologies limit procurement flexibility for DFR manufacturers sourcing from Taiwanese and South Korean fabrication facilities. Supply chains draw from China for magnetic components, Germany for precision enclosures, and Japan for specialized capacitors, creating tariff exposure at multiple nodes. Distribution runs through authorized electrical equipment distributors with substation automation engineering support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Fault Recorder market sits in early-cycle expansion as cloud-based fleet analytics penetration remains below twenty percent among North American municipal utilities. IEC 61850 digital substation mandates across FERC-jurisdictioned entities and EU transmission operators sustain replacement tailwinds independent of cyclical capital expenditure fluctuations.
For Market Incumbents: Entrench competitive position through backward integration into FPGA programming capabilities and cybersecurity certification tracks aligned with IEC 62443-3-3 zone models. Cloud-native analytics platforms threaten hardware-centric revenue streams; incumbents must build software service organizations or acquire specialized disturbance classification platforms to defend subscription revenue conversion. For New Entrants and Emerging Players: Mid-market commercial and industrial facilities in India and Southeast Asia represent the most penetrable entry point, as grid stability monitoring mandates from Central Electricity Authority create underpenetrated demand for IEC 61850-compliant portable units. Target distribution network operators in Germany and California seeking mobile DFR solutions for distributed energy resource interconnection testing, leveraging direct sales partnerships with substation automation engineering consultancies. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure software convergence play because waveform analytics capabilities are migrating from forensic tools to real-time grid intelligence platforms. Acquisition targets should display relay-to-recorder platform integration expertise or AI-assisted disturbance classification IP. The signal to watch is FERC enforcement intensity around NERC PRC-002-2 compliance deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Integration | Subscription revenue models displace perpetual licenses among California municipal utilities. |
| IEC 62443-3-3 Certification | Encrypted firmware capabilities exclude uncertified vendors from EU transmission tenders. |
| Backward Integration into Semiconductors | In-house FPGA programming reduces exposure to East Asian foundry concentration. |
| Strategic Partnership with Analytics Platforms | AI-assisted disturbance classification accelerates software service revenue conversion. |
| Geographic Expansion into India | Central Electricity Authority mandates create underpenetrated demand for substation retrofits. |
Study Parameters
A spread of perspectives from utility planning officers, substation automation engineers, protection equipment procurement managers, and cybersecurity compliance leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FERC filings, NERC reliability standards documentation, IEC technical committee publications, and customs trade data on high-speed ADC imports. Bottom-up channel checks across authorized distributors triangulated against top-down transmission operator capital expenditure disclosures.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling across product type, technology architecture, end-user sector, and application use case. CAGRs derived from replacement cycle analysis of legacy analog installations and greenfield digital substation deployment pipelines. Forecast inputs incorporated NERC enforcement timelines, EU Green Deal network code implementation schedules, and provincial grid modernization directives from China's dual carbon policy framework.
Macroeconomic conditions sit as an overlay; deviation in copper and rare earth commodity prices, semiconductor foundry utilization rates, or utility capital expenditure prioritization would shift the trajectory. Forecasts reflect documented assumptions on regulatory compliance deadlines and technology substitution curves. Material shifts in IEC 62351 cybersecurity standard finalization or FERC jurisdiction expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
India Gas Insulated Switchgear Market
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Busbar Protection Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Electric Submersible Pump Cable Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
Portable Space Heater Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
Optical Current Transformer Market