
 Bucket Water Heater Market | 2026-2036
Bucket Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Bucket Water Heater Market Outlook
Modular bundling of immersion rods with insulated buckets is expanding buyer choice across portable heating segments. Gesail leverages its specialization in submersible heating elements to anchor the North American outdoor recreation channel. KD Heater sustains manufacturing scale through captive production of resistance coils, while Bajaj dominates India's electrical goods retail network with extensive distributor control.
A bucket water heater is an immersion-type electric or fuel-fired device designed to heat water in open or semi-enclosed containers, typically operating at 120-240V with wattage ratings from 1000W to 3000W and incorporating thermostatic cutoff mechanisms for scald prevention. Its primary commercial purpose is to deliver on-demand hot water in locations lacking plumbed infrastructure, including construction sites, military encampments, and rural hospitality settings. Electric bucket configurations lead the product type landscape due to lower upfront cost and minimal installation, while portable installation types capture the fastest growth as mobile workforces and disaster relief operations prioritize transportability over fixed mounting. The 10-liter capacity band occupies the central margin pool, balancing heating speed against energy efficiency for small-batch commercial users.
The US Consumer Product Safety Commission and India's BIS mandate grounding-fault protection and immersion-depth markings, pushing manufacturers toward double-insulated designs and tethered float switches. China's GB standards for household electrical appliances further constrain export-oriented producers who supply cross-border e-commerce channels. Stakeholders must monitor evolving efficiency labeling regimes and decide whether to absorb compliance costs or retreat from markets with divergent certification requirements.
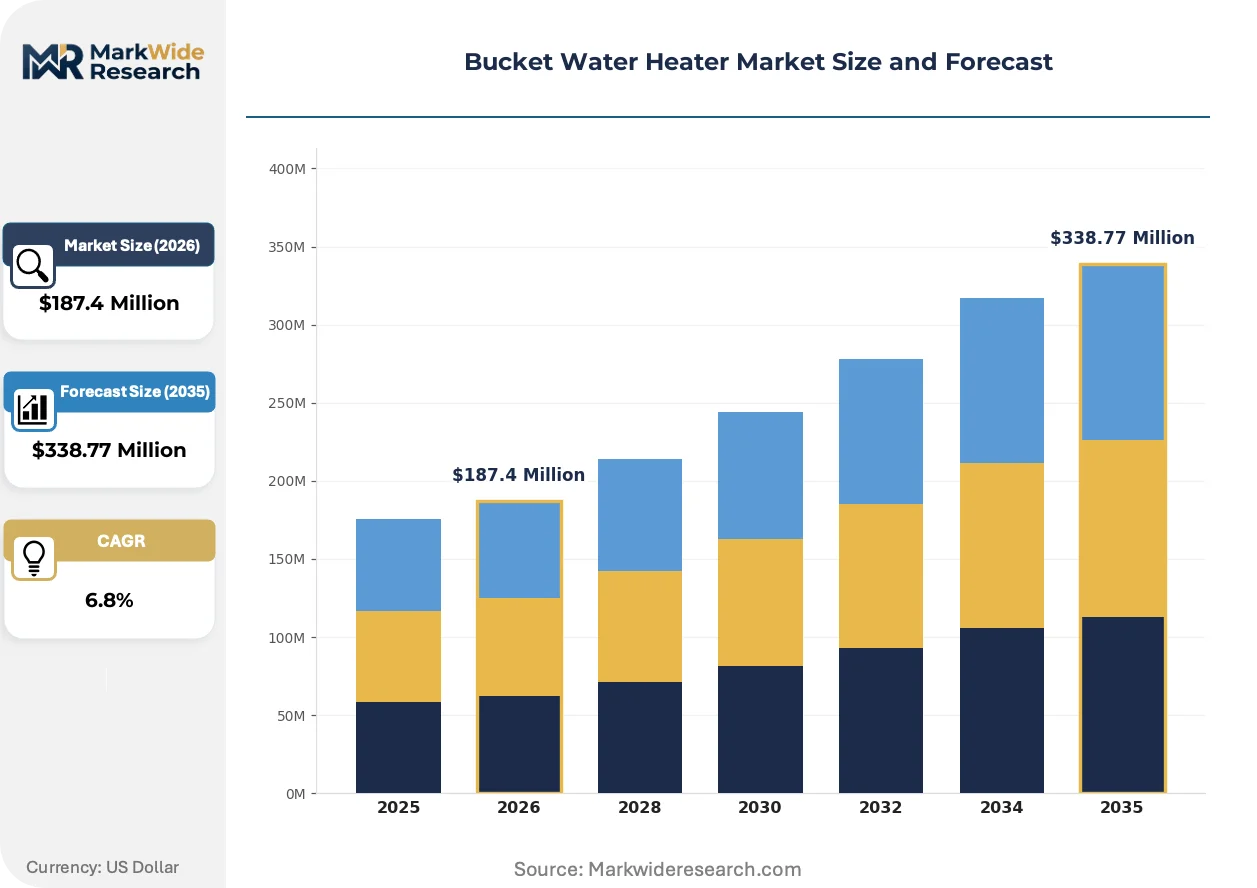
Market Dynamics
Portable immersion heating is displacing fixed infrastructure across construction and outdoor hospitality verticals as grid reliability gaps and mobile workforce requirements reshape procurement priorities. India's BIS certification mandates and China's GB standards are fragmenting compliance requirements, forcing manufacturers into dual-design strategies.
Growth Catalysts
- Construction site electrification:Infrastructure buildouts in South Asian urban clusters are creating demand for point-of-use heating where plumbed hot water remains unavailable. Contractors specify portable units to bypass fixed installation timelines.
- BIS certification expansion:India's mandatory grounding-fault protection and immersion-depth markings are standardizing safety benchmarks across import channels, elevating product quality floors for all market entrants.
- Resistance coil manufacturing scale:Captive production of heating elements in key supply geographies is compressing component lead times and enabling faster OEM turnaround for seasonal demand spikes.
Market Restraints
- Copper and nickel price volatility:Resistance coil manufacturing depends on these base metals, exposing margin structures to commodity swings that producers cannot fully pass through in price-sensitive segments.
- Supply concentration in East Asian coil production:A narrow supplier base for precision-wound heating elements creates single-source vulnerability for mid-tier assemblers lacking backward integration.
- Electric grid capacity constraints:Rural hospitality operators in load-shedding zones face operational uncertainty that caps deployment density regardless of unit portability.
Strategic Opportunities
- Disaster relief procurement channels:Emergency response agencies are building portable water heating into mobile shelter specifications, creating institutional demand with longer contract cycles than consumer markets.
- Solar-battery hybrid integration:Coupling immersion rods with DC microgrids and lithium storage is opening off-grid applications beyond generator-dependent sites.
- Cross-border e-commerce standardization:Platform sellers who pre-certify against multiple national electrical codes can capture arbitrage opportunities in markets with underdeveloped retail networks.
Industry Challenges
- Electrical safety engineering talent scarcity:Designers fluent in both thermostatic control systems and emerging market voltage irregularities command premium compensation that strains R&D budgets.
- Multi-jurisdiction certification timelines:Parallel testing against BIS, GB, and UL standards extends product launch windows by 8-14 months, freezing capital in pre-revenue inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bucket Water Heater Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Bucket, Gas Bucket, Solar Bucket, Instant Heating Bucket End User: Residential, Commercial, Industrial, Hospitality Installation Type: Wall-mounted, Portable, Under-sink, Floor-standing Capacity: 5 Liters, 10 Liters, 15 Liters, 20 Liters |
| Companies Covered | Gesail, KD Heater, Diximus, Lewis N. Clark, Bajaj, Crompton, Havells, Midea, Haier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bucket Water Heater Market Strategic Shifts
Heating element architecture is fragmenting into swappable, wattage-specific modules that let buyers configure systems for container size and ambient temperature rather than accepting fixed-output units. This shift is compressing SKU proliferation while expanding addressable use cases.
Silicone-carbide coated immersion rods are modularizing across outdoor recreation and military supply chains. Campsite operators and expedition outfitters are specifying these units for rapid deployment in variable voltage environments. The technology is modularizing procurement decisions by separating heating element replacement from full unit replacement, extending asset life cycles.
REACH substance restrictions and EU F-Gas Regulation are pressuring manufacturers to eliminate PFAS-containing coatings and legacy refrigerant-based alternatives in adjacent heating product lines. Industrial consequences include accelerated R&D spending on ceramic-based insulation and dry-film lubricants. Portable electric configurations are capturing preference share in European commercial channels as fuel-fired alternatives face compliance headwinds.
Rental and lease-to-own arrangements are displacing outright purchase in construction equipment channels. Equipment lessors are bundling portable water heaters with site power distribution units, unbundling after-sales service from hardware margins. This pattern is most visible in US and Australian mining and infrastructure camps where capital deployment flexibility outweighs long-term ownership economics.
Bucket Water Heater Market Segmentation
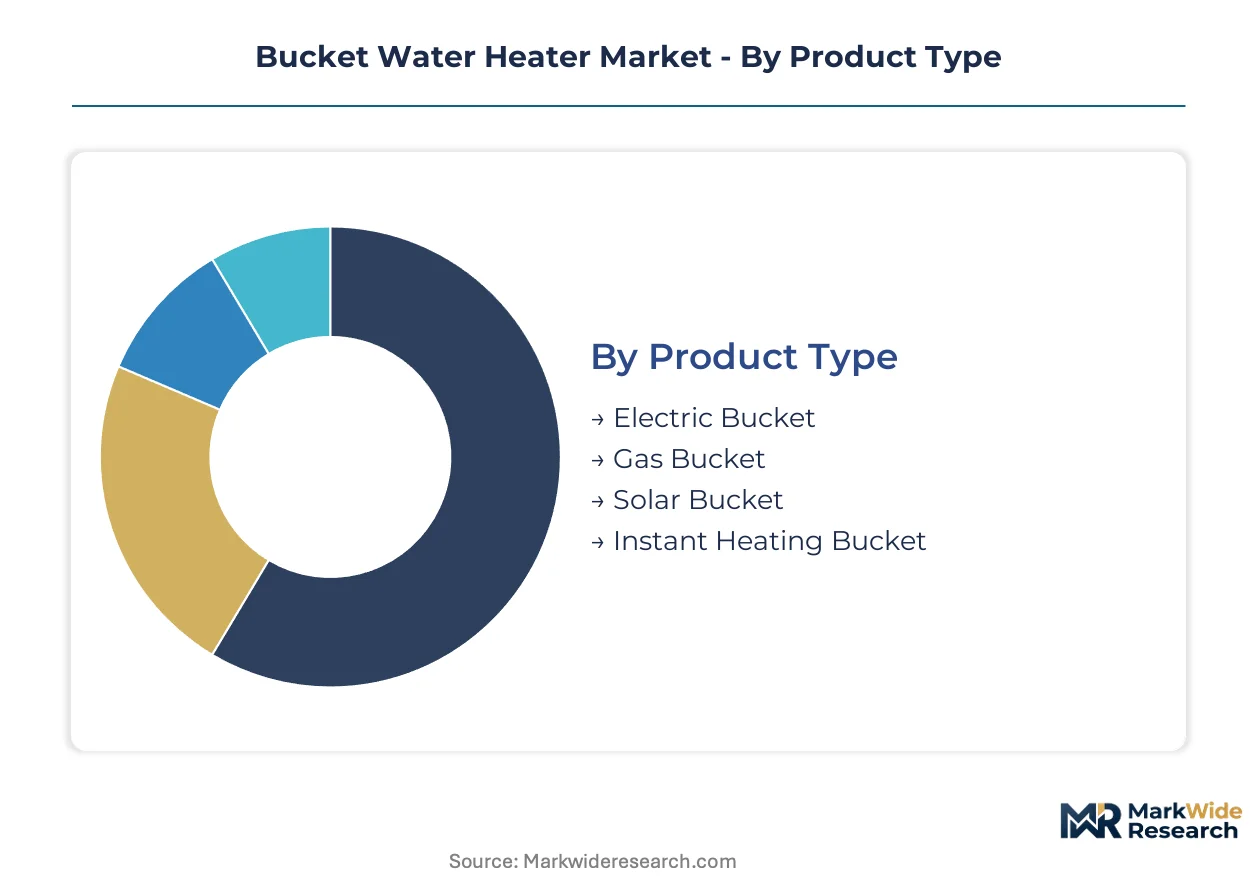
Bucket water heater procurement splits sharply between cost-driven bulk buyers and specification-focused niche operators. Understanding where volume concentrates versus where margins thicken guides portfolio allocation across component suppliers and finished goods distributors.
Product Type:
Volume leadership sits with mature electric configurations, while premium pricing accrues to emerging hybrid and instant-response technologies.
- Electric Bucket:Submersible resistance coils operating at 1000-3000W dominate construction site and rural hospitality deployment due to minimal upfront cost and zero fuel logistics. India's BIS grounding-fault mandates are compressing supplier margins while elevating safety floors for import channels.
- Gas Bucket:LPG-fired units with piezoelectric ignition serve off-grid mining camps and disaster relief operations where generator fuel chains prove unreliable. Demand clusters in South Asian load-shedding zones and remote Australian infrastructure corridors.
- Solar Bucket:DC-coupled immersion elements paired with photovoltaic arrays target eco-lodges and military forward operating bases seeking fossil fuel independence.
- Instant Heating Bucket:Flow-through heating chambers with sub-30-second response times command specification in premium outdoor hospitality and medical field stations requiring on-demand temperature precision.
Today's leader: Electric Bucket. Tomorrow's challenger: Instant Heating Bucket.
End User:
Application maturity runs from saturated residential replacement cycles to nascent industrial rental channels.
- Residential:Point-of-use heating in informal urban settlements and peri-urban clusters substitutes for centralized hot water infrastructure. India's grid reliability gaps sustain demand for portable units over plumbed alternatives.
- Commercial:Construction contractors and equipment lessors specify portable electric configurations to bypass fixed installation timelines and capital deployment constraints.
- Industrial:Mining camps and shipyard maintenance crews rent immersion heating systems bundled with power distribution units, unbundling ownership from operational access.
- Hospitality:Glamping operators and expedition outfitters specify silicone-carbide coated rods for rapid deployment across variable voltage environments.
Commercial procurement is climbing the fastest as mobile workforce requirements reshape equipment rental economics.
Installation Type:
Transportability premiums widen where site tenure measures weeks rather than years.
- Wall-mounted:Fixed bracket systems with hardwired electrical connections serve semi-permanent worker dormitories and institutional kitchens with predictable hot water demand profiles.
- Portable:Corded immersion rods with carrying cases capture specification from disaster relief agencies and infrastructure contractors prioritizing redeployment speed over installation permanence.
- Under-sink:Compact tank-in-tank configurations fit space-constrained food service operations and mobile medical clinics requiring concealed placement.
- Floor-standing:Elevated reservoir designs with integrated heating elements target agricultural processing and commercial laundry batches exceeding 20-liter volumes.
Portable units are gaining share fastest as procurement shifts from ownership to operational leasing.
Capacity:
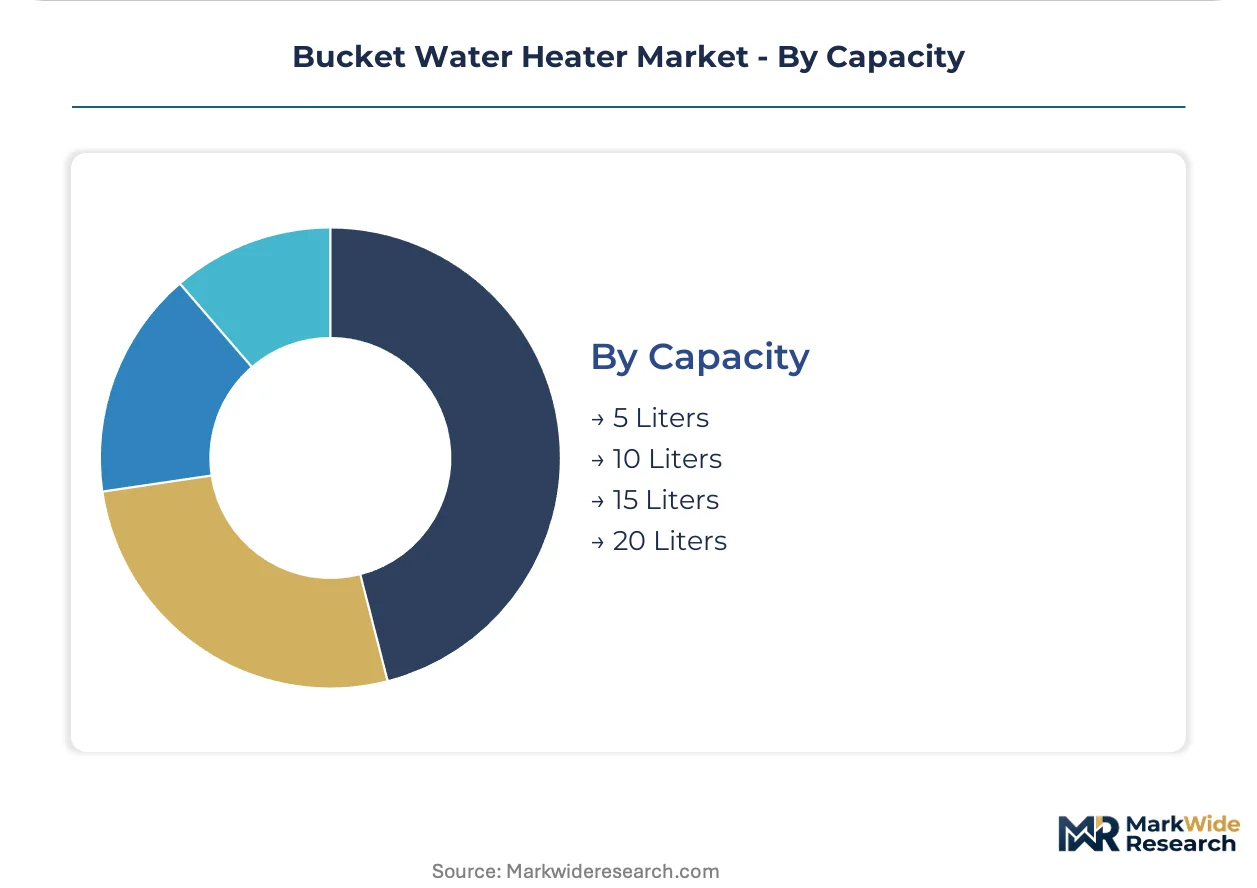
Heating speed trades against energy efficiency across batch size requirements.
- 5 Liters:Personal-scale immersion rods heat individual washing basins and food preparation vessels in remote field stations.
- 10 Liters:Mid-range vessels balance thermal recovery time against power draw for small construction crews and campsite hygiene stations.
- 15 Liters:Extended-duty coils serve commercial kitchen pre-rinse operations and medical instrument sterilization workflows.
- 20 Liters:Maximum batch configurations target laundry operations and livestock processing facilities with concentrated hot water demand spikes.
Ten-liter specifications anchor current procurement volumes. Fifteen-liter configurations are expanding most quickly as commercial operators standardize around unified crew-size batches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bucket water heater manufacturing traces its commercial roots to post-war Japan's electrification drive, where immersion heating technology first scaled for industrial applications before diffusing to portable consumer formats across Asia-Pacific and North American construction corridors.
United States
Construction contractors and disaster relief agencies drive portable unit procurement through equipment rental channels. The US Consumer Product Safety Commission mandates grounding-fault protection and immersion-depth markings, elevating safety engineering requirements for import brands. Dallas-Fort Worth and Houston anchor distribution networks serving Permian Basin oilfield camps and Gulf Coast infrastructure projects.
India
Informal urban settlements and peri-urban construction clusters sustain point-of-use heating demand where centralized hot water infrastructure remains absent. The Bureau of Indian Standards enforces mandatory grounding-fault protection and depth markings, reshaping import compliance and elevating domestic manufacturer quality floors. Maharashtra's Mumbai-Pune industrial corridor concentrates electrical goods manufacturing and distributor networks.
China
Resistance coil production clusters in Guangdong and Zhejiang provinces supply global OEM assembly lines with precision-wound heating elements. GB standards for household electrical appliances constrain export-oriented producers supplying cross-border e-commerce channels. The Pearl River Delta maintains captive manufacturing scale for thermostatic control components and double-insulated housing assemblies.
Germany
REACH substance restrictions and EU F-Gas Regulation pressure manufacturers to eliminate PFAS-containing coatings from heating element insulation. ECHA compliance timelines extend product certification cycles for brands accessing European commercial channels. Bavaria's industrial equipment distributors bundle portable water heaters with site power distribution systems for construction lessors.
Australia
Mining camps and remote infrastructure projects specify portable electric configurations to bypass fixed installation timelines in transient work sites. The country's national electrical safety regulator mandates alignment with IEC standards for immersion appliance grounding. Western Australia's Pilbara region drives seasonal demand spikes through fly-in-fly-out workforce accommodation contracts.
Bucket Water Heater Market Competitive Environment
The competitive structure tilts toward scale-driven electrical goods conglomerates with captive distribution networks. Tiering separates premium safety-engineered brands from price-optimized commodity assemblers. Three archetypes dominate: submersible heating element specialists, diversified appliance manufacturers with backward-integrated coil production, and platform-native brands optimized for cross-border e-commerce fulfillment. Competitive moves concentrate on multi-jurisdiction certification pre-qualification and seasonal inventory pre-positioning ahead of construction cycle peaks.
Among North American outdoor recreation specialists, Gesail anchors the premium portable segment through heating element engineering depth. KD Heater occupies the manufacturing-scale tier with captive resistance coil production compressing component lead times. Bajaj exemplifies distributor-network dominance, leveraging extensive electrical goods retail penetration across South Asian urban clusters. These three represent distinct competitive vectors: engineering specialization, upstream manufacturing control, and channel density.
| Leading Market Players |
|---|
| Gesail |
| KD Heater |
| Diximus |
| Lewis N. Clark |
| Bajaj |
| Crompton |
| Havells |
| Midea |
| Haier |
| Others |
Value Chain & Pricing Dynamics
Construction contractors and disaster relief procurement programs anchor demand for portable bucket water heaters, locking pricing into a three-tier structure across premium, standard, and economy levels where safety certification grade and volume scale separate tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with UL and BIS certification tiers creating price differentiation alongside brand premium and after-sales service bundling. Cost compression in economy segments is intensifying because copper and nickel price volatility erodes assembler margins. Commercial rental channels exhibit lowest price sensitivity due to operational leasing economics, while informal residential buyers in South Asian urban clusters drive maximum price elasticity.
Supply Chain Analysis
India's BIS domestic-content mandates and China's GB standards are reshaping sourcing patterns for resistance coil assemblies. Supply concentrates in China's Guangdong and Zhejiang provinces for precision-wound heating elements, with India's Maharashtra corridor expanding captive coil production. Raw material dependencies draw from copper cathode, nickel-chromium alloy wire, and ceramic insulation substrates. Single-source vulnerability persists for thermostatic control modules. Distribution runs through electrical goods wholesalers in South Asian urban clusters and equipment rental channels in North American construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bucket water heater market represents a late-cycle quality story as procurement shifts toward BIS-certified, double-insulated configurations that command specification premiums over commodity immersion rods.
For Market Incumbents: Anchor market position through backward integration into resistance coil manufacturing and preemptive multi-jurisdiction certification against BIS, GB, and UL standards. Gesail's heating element engineering depth and KD Heater's captive production demonstrate defensible moats against emerging platform-native brands. Certification investment serves as the critical lever to absorb compliance cost compression while elevating quality floors for import competitors. For New Entrants and Emerging Players: Launch via cross-border e-commerce pre-certification against divergent electrical codes to capture arbitrage in underdeveloped retail networks. Disaster relief procurement channels present the most penetrable white-space, with longer contract cycles and institutional specification requirements that favor new entrants with safety-engineered credentials. Solar-battery hybrid integration offers a second entry vector for off-grid applications beyond generator-dependent sites. For Investors and Strategic Acquirers: Electrical goods conglomerates with captive distribution networks are the most active acquirer in this space, seeking heating element specialists to complement appliance portfolios. The market exhibits durable 5-10 year viability anchored by construction electrification and mobile workforce expansion. Acquisition target archetypes include submersible heating element engineers with BIS pre-qualification and platform-native brands with cross-border fulfillment infrastructure. Monitor copper-nickel price spreads as the signal for margin compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Pre-Qualification | BIS, GB, and UL alignment compresses launch windows for cross-border e-commerce channels. |
| Backward Integration into Resistance Coil Production | Captive manufacturing in Guangdong or Maharashtra insulates margin structures from commodity volatility. |
| Solar-Battery Hybrid Product Development | DC-coupled immersion elements paired with lithium storage open military and eco-lodge specifications. |
| Equipment Rental Channel Partnership | Bundling with site power distribution units captures procurement shifts from ownership to operational leasing. |
| Silicone-Carbide Coating Technology Licensing | Modular heating element replacement extends asset life cycles for expedition outfitters and campsite operators. |
Study Parameters
Coverage spans North America, South Asia, East Asia, and Europe, with primary inputs from each region combining interviews with electrical goods distributors, construction equipment lessors, thermostatic control engineers, and BIS certification consultants alongside secondary validation. Trade data from India's DGFT, China's customs records, and US CPSC safety filings anchor supply-side analysis. SEC 10-K disclosures from listed appliance manufacturers and cross-border e-commerce platform transaction data complete the demand picture. Bottom-up unit economics triangulate against top-down construction spending and electrification indices.
Granularity extends to product type, installation configuration, capacity band, and end-use vertical across the analysis window. Electric, gas, solar, and instant heating architectures were modeled separately with installation mobility and grid coupling status as cross-cutting dimensions. CAGRs derive from regression against construction cycle indicators, rural electrification rates, and disaster relief budget allocations. Copper price futures and nickel spot market volatility feed into margin sensitivity scenarios.
Forecast precision tightens around the base case; tail outcomes carry wider variance under BIS enforcement acceleration or prolonged load-shedding in South Asian urban clusters. Assumptions reflect documented regulatory timelines and commodity price bands. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Busbar Protection Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
Gas Circuit Breaker Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
GCC Induction Motor Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
3rd Rail Current Collector Market
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
India Gas Insulated Switchgear Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Middle East and Africa Hazardous Location Motor Starters Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
Smart Electric Heater Market