

Switching Residential Voltage Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
Switching Residential Voltage Regulator Market Insights
Project finance and leasing arrangements for distributed energy assets is tilting competitive dynamics toward capital-light entrants in residential power conditioning. Schneider Electric leverages its integrated energy management portfolio to dominate turnkey installations across European markets. Siemens anchors its position through deep R&D intensity in digital control architectures. Eaton competes by specializing in surge-resistant designs for multi-unit housing applications.
A switching residential voltage regulator employs semiconductor-based power electronics—typically insulated-gate bipolar transistors or MOSFETs operating at 10–50 kHz—to maintain output voltage within ±1% of nominal 120V or 230V despite input fluctuations. The device converts AC to DC and back through high-frequency switching, eliminating mechanical wear while enabling millisecond response times critical for sensitive residential electronics. Automatic voltage regulators command the largest installed base but face margin compression from commoditization, whereas DSP control technology captures premium pricing through adaptive load algorithms. Pulse width modulation leads unit shipments due to cost efficiency, though microcontroller-based platforms represent the fastest-growing category as firmware updates enable remote diagnostics.
EPA Energy Star specifications and DOE appliance efficiency standards shape minimum performance thresholds for units sold in the United States, while CE marking and EU F-Gas Regulation govern refrigerant-cooled variants in European markets. India's BIS certification mandates tropical climate derating factors that exclude many import designs. Stakeholders must monitor how evolving grid-interconnection codes in Germany, India, and the United States redefine permissible harmonic distortion limits for residential-connected power electronics.
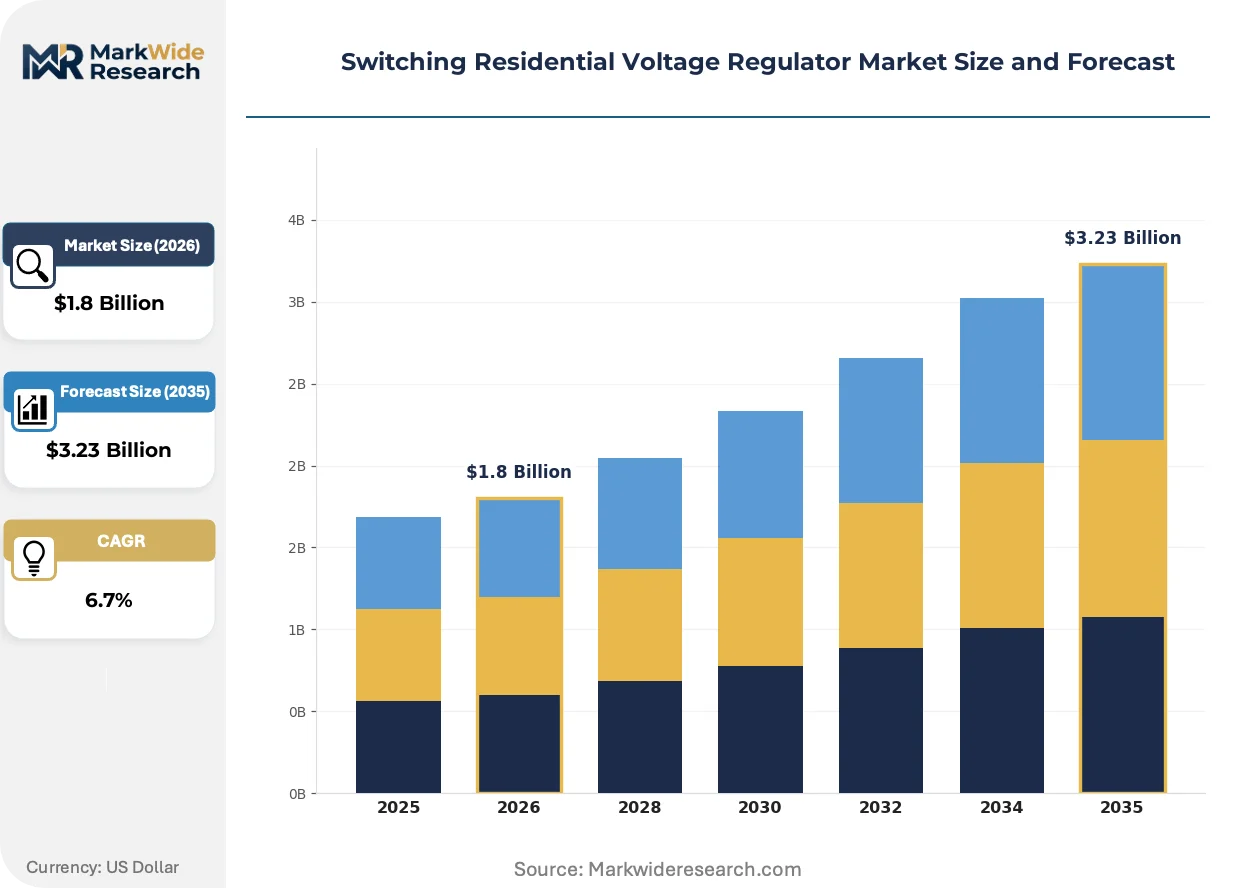
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant-cooled variant margins while accelerating solid-state switching architectures across European residential installations. Semiconductor-based power electronics are displacing electromechanical tap-changers as grid modernization mandates tighten harmonic distortion requirements in Germany, India, and the United States.
Growth Catalysts
- Grid-interconnection codes:Germany's VDE-AR-N 4105 and India's CEA technical standards are mandating millisecond-response voltage regulation for residential solar inverters, forcing upgrades to switching regulator architectures.
- Smart home penetration:DSP-controlled platforms with adaptive load algorithms are capturing premium positioning as home automation systems require ±1% voltage stability for sensitive electronics.
- Climate adaptation:India's BIS tropical derating certification is excluding import designs and creating protected demand for locally engineered heat-resistant semiconductor packages.
Market Restraints
- IGBT supply concentration:Japanese and German semiconductor foundries control high-voltage insulated-gate bipolar transistor output, exposing residential regulator manufacturers to 26-week lead time volatility.
- Copper winding costs:Toroidal transformer cores in hybrid designs face input cost pressure from Chilean and Peruvian concentrate supply disruptions.
- Electromechanical substitution:Automatic voltage regulators maintain installed base inertia in price-sensitive Indian and Southeast Asian housing markets despite inferior response times.
Strategic Opportunities
- Remote firmware architectures:Microcontroller-based platforms with over-the-air diagnostic updates are opening recurring revenue streams in European and North American premium residential segments.
- Multi-unit housing surge protection:Eaton's specialized designs for apartment complexes reveal unmet demand for centralized power conditioning in dense German and Indian urban developments.
- EU Green Deal retrofit mandates:Building renovation wave targets are creating replacement cycles for inefficient electromechanical regulators in 195 million European residential units.
Industry Challenges
- Power electronics talent scarcity:Germany and India face acute shortages of engineers proficient in 10–50 kHz switching topology design and thermal management simulation.
- Harmonic compliance testing:Evolving IEC 61000-3-2 and IEEE 519 residential limits require expensive third-party certification cycles that delay product launches by 8–14 months.
- Legacy system integration:Electromechanical regulator replacement in 1970s–1990s housing stock demands custom form-factor engineering that fragments production runs.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switching Residential Voltage Regulator Market Trends and Innovations
Distributed energy resource penetration is forcing residential voltage regulation toward bidirectional power flow architectures. Semiconductor switching frequencies are climbing while thermal management constraints drive material substitution in high-density packages.
Silicon carbide MOSFETs are replacing silicon IGBTs in premium residential units, enabling 50 kHz switching frequencies that shrink magnetic component volume by 40 percent. German and Japanese inverter manufacturers are accelerating qualification timelines for SiC-based residential regulators. This transition is digitizing control architectures by embedding real-time adaptive algorithms that legacy analog loops cannot execute.
The EU F-Gas Regulation is banning refrigerant-cooled designs for units below 5 kVA rating, forcing air-cooled and liquid-cooled thermal management innovation. European manufacturers are redesigning heat sink geometries and fan curves to maintain semiconductor junction temperatures under tropical derating conditions. Residential regulator portfolios in Germany, France, and Italy are consolidating around solid-state platforms that eliminate compressor-based cooling entirely.
Leasing and power-purchase agreements for rooftop solar are bundling voltage regulation into integrated home energy service contracts. German and California installers are displacing standalone regulator sales with subscription-based power quality guarantees. This model concentrates procurement authority with EPC firms and financing platforms rather than individual homeowners, compressing brand loyalty and elevating total-cost-of-ownership analytics in vendor selection.
Switching Residential Voltage Regulator Market Segmentation
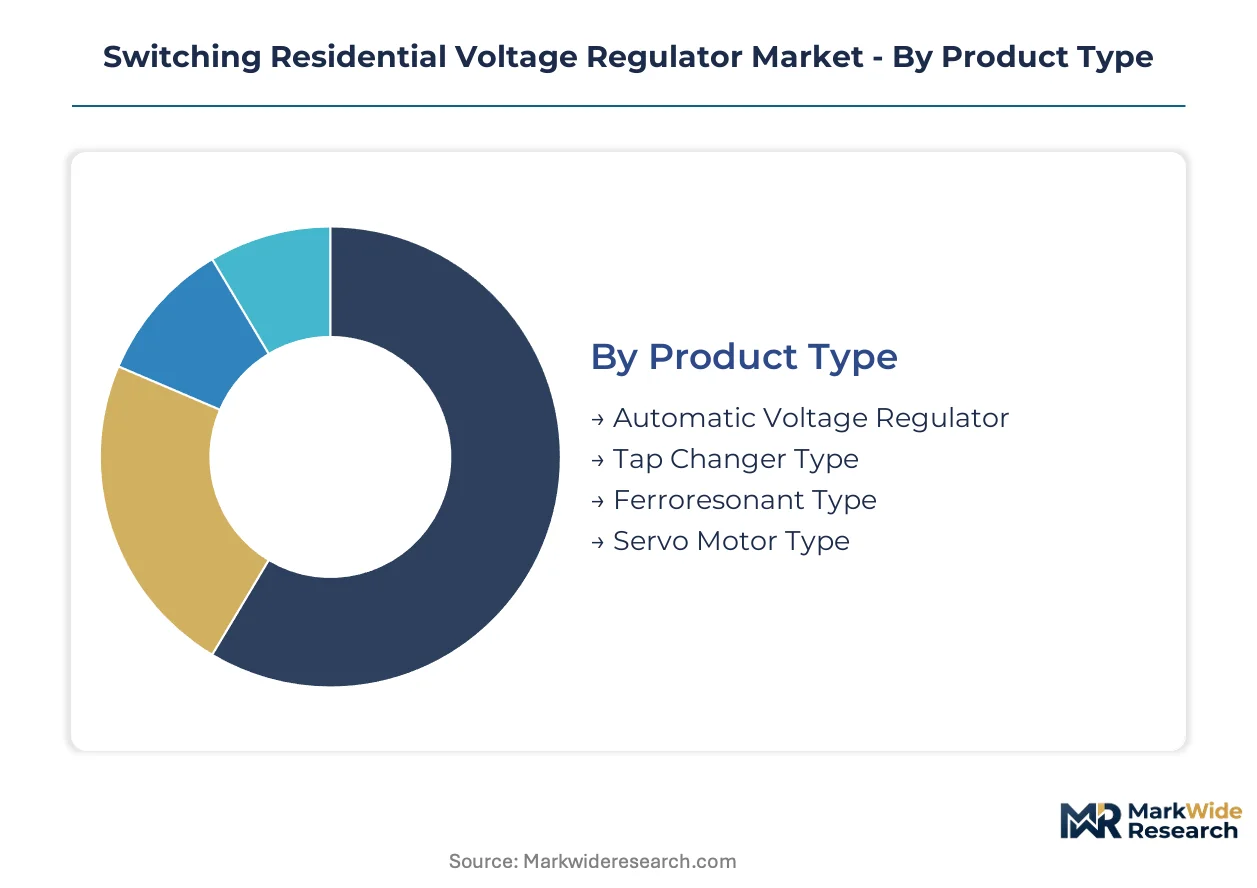
Segmentation in switching residential voltage regulators reveals how semiconductor switching frequencies, thermal management architectures, and control firmware complexity map to distinct service intensity profiles across installation types. Each segment carries differentiated warranty exposure, remote diagnostic capability, and replacement cycle economics that shape vendor profitability.
Product Type:
After-sales-service intensity varies sharply across electromechanical versus solid-state architectures, with semiconductor-based designs demanding firmware update subscriptions while tap-changer variants require mechanical maintenance contracts.
- Automatic Voltage Regulator:Electromechanical servo systems with carbon brush contactors and toroidal autotransformers dominate legacy installed bases across Indian and Southeast Asian housing markets. Margin compression from commoditized manufacturing in Chinese and Taiwanese facilities limits service revenue attachment rates for distributors.
- Tap Changer Type:Silicon-controlled rectifier modules enable step-voltage correction without mechanical wear, attracting premium positioning in German and California residential solar installations where millisecond response codes apply. Localized winding repair networks in Bavaria and Baden-Württemberg sustain higher service contract penetration than import-dependent markets.
- Ferroresonant Type:Saturable transformer cores with resonant tank circuits deliver inherent surge protection for rural American installations with frequent lightning exposure.
- Servo Motor Type:Brushless DC motor drives with optical position feedback maintain ±2% regulation in price-sensitive Indian apartment complexes where electromechanical inertia persists.
By volume, Automatic Voltage Regulator leads. By growth pace, Tap Changer Type is ahead.
Technology:
Cost tier stratification separates commodity PWM platforms from premium DSP architectures, with microcontroller-based systems capturing mid-market positioning through over-the-air diagnostic enablement.
- Pulse Width Modulation:Fixed-frequency IGBT switching at 10–20 kHz dominates unit shipments across mass-market Indian and Chinese manufacturing, with minimal firmware differentiation compressing gross margins toward 15–20%.
- DSP Control:Adaptive load algorithms with real-time harmonic compensation command premium positioning in German smart home installations integrated with Schneider Electric and Siemens energy management ecosystems. Service contracts for algorithm updates extend customer lifetime value beyond hardware margins.
- Digital Signal Processor:Dedicated floating-point architectures enable predictive thermal modeling for California Title 24 compliance in high-efficiency residential construction.
- Microcontroller Based:ARM Cortex-M4 platforms with Wi-Fi diagnostic stacks are expanding most quickly in North American premium segments as remote firmware updates reduce truck-roll service costs.
- Analog Control:Op-amp comparator networks with discrete component tuning persist in legacy American housing stock replacement markets.
By volume, Pulse Width Modulation leads. By growth pace, Microcontroller Based is climbing the fastest.
Application:
Customer type concentration shapes procurement authority, with property developers driving standardized specifications for multi-unit housing while individual homeowners prioritize smart home integration.
- Multi-Unit Housing:Centralized three-phase installations with surge-resistant bus architectures concentrate demand in dense German urban developments and Indian metropolitan construction. Eaton's specialized designs for apartment complexes reveal unmet demand for consolidated power conditioning with single-point service accountability.
- Smart Home Systems:±1% voltage stability requirements for sensitive electronics integration with voice assistants, EV chargers, and battery storage create premium positioning in California and German retrofit markets. Firmware interoperability with Home Energy Management Systems extends replacement cycles through remote optimization.
- Single-Family Dwelling:Standalone 120V/230V units with plug-and-install simplicity dominate American suburban replacement demand.
- Energy Efficient Buildings:EU Green Deal renovation wave targets in France, Italy, and Spain are forcing electromechanical regulator replacement in 195 million European residential units with solid-state platforms.
By volume, Single-Family Dwelling leads. By growth pace, Smart Home Systems is gaining share fastest.
End User:
Supply concentration among Japanese and German IGBT foundries differentially impacts procurement leverage, with utility service providers capturing volume discounts unavailable to fragmented residential consumer channels.
- Utility Service Providers:Grid-interconnection mandates in Germany's VDE-AR-N 4105 and India's CEA technical standards concentrate procurement authority with EPC firms bundling voltage regulation into rooftop solar leasing contracts. Power-purchase agreement structures displace standalone regulator sales with subscription-based power quality guarantees.
- Property Developers:Pre-installation specifications for new German and Indian urban housing stock enable vendor lock-in through integrated energy service contracts with 10-year maintenance riders.
- Residential Consumers:Price-sensitive Indian and Southeast Asian homeowners maintain electromechanical regulator preference despite inferior response times.
- Electrical Contractors:Installation margin dependence on markup flexibility drives brand-agnostic specification in American residential retrofit markets.
By volume, Residential Consumers leads. By growth pace, Utility Service Providers shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in switching residential voltage regulators tilt toward import-dependent markets in India and Southeast Asia, while Germany and the United States maintain balanced equipment exchange through integrated manufacturing and R&D bases.
Germany
VDE-AR-N 4105 grid-interconnection codes mandate millisecond-response voltage regulation for residential solar installations, accelerating solid-state platform adoption across Bavarian and Baden-Württemberg industrial clusters. The EU F-Gas Regulation eliminates refrigerant-cooled designs below 5 kVA, forcing air-cooled thermal innovation in Stuttgart-area engineering centers.
India
CEA technical standards and BIS tropical derating certification exclude heat-sensitive import designs, creating protected demand for locally engineered semiconductor packages in Maharashtra and Gujarat manufacturing corridors. Grid modernization concentrates procurement authority with utility-scale EPC firms bundling voltage regulation into rooftop solar leasing.
United States
EPA Energy Star specifications and DOE appliance efficiency standards shape minimum performance thresholds, while California Title 24 compliance drives predictive thermal modeling adoption in Pacific Coast residential construction. Texas and Florida housing markets sustain demand for surge-resistant architectures in lightning-exposed regions.
Japan
METI efficiency directives and JIS standards govern high-voltage IGBT qualification timelines, concentrating semiconductor foundry output in Kyushu and Nagoya industrial zones. Domestic manufacturers supply precision switching components to German and American residential regulator assemblers.
China
MIIT power electronics standards and GB certification frameworks commoditize PWM platform manufacturing in Pearl River Delta facilities, exporting cost-optimized units to price-sensitive Indian and Southeast Asian housing markets while importing premium DSP control architectures from German and Japanese specialists.
Switching Residential Voltage Regulator Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying power semiconductors and control firmware. The vendor base stratifies across three tiers: diversified electrical conglomerates with energy management portfolios, pure-play voltage conditioning specialists, and semiconductor foundries providing IGBT and SiC devices. Consolidation pressure intensifies as leasing and power-purchase agreement structures concentrate procurement authority with EPC firms and financing platforms. Competitive moves center on firmware subscription architectures and thermal management material substitution rather than capacity expansion.
Among diversified electrical conglomerates, Schneider Electric and Siemens exemplify platform integrators leveraging energy management ecosystems to anchor turnkey installation contracts. Eaton occupies a position within the surge protection specialization tier, representing demand concentration in multi-unit housing applications. These three entities sit within distinct competitive archetypes while collectively shaping procurement standards across German, Indian, and North American residential markets.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton |
| General Electric |
| Siemens |
| Emerson Electric |
| ABB |
| Mitsubishi Electric |
| Texas Instruments |
| Infineon Technologies |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese PWM manufacturing facilities is compressing gross margins toward 15-20% for commodity-grade units while simultaneously forcing German and Japanese semiconductor foundries to defend premium positioning through SiC qualification timelines. This utilization asymmetry between mass-market assembly and precision component fabrication shapes divergent pricing postures across the switching residential voltage regulator value chain.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with DSP-controlled platforms commanding premiums through adaptive algorithm subscriptions while PWM units trade on volume scale. Price differentiation rests on certification grade—CE marking for EU F-Gas compliance and BIS tropical derating for Indian eligibility—plus after-sales firmware update bundling. Cost compression in the PWM tier is intensifying because Pearl River Delta exporters are absorbing copper winding volatility to maintain market share. Residential consumers in Southeast Asia exhibit highest price sensitivity, whereas German utility service providers demonstrate lowest sensitivity due to power-purchase agreement structures that internalize hardware costs.
Supply Chain Analysis
High-voltage IGBT wafer fabrication concentrates in Japan and Germany, with silicon carbide substrate growth accelerating in Kyushu and Nagoya industrial zones. Raw material dependencies include Chilean copper concentrate for toroidal transformer cores, rare earth elements for high-frequency magnetic components, and epoxy molding compounds for semiconductor packaging. Single-source vulnerability in Japanese foundry output exposes 26-week lead time volatility for residential regulator assemblers. Distribution runs through EPC firms and financing platforms in German and Indian rooftop solar markets, displacing traditional electrical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering proficiency in 10-50 kHz switching topology design and thermal management simulation is concentrated among a shrinking cohort of German and Indian specialists, creating asymmetric capability access that will determine competitive survival as grid-interconnection codes tighten harmonic distortion requirements.
For Market Incumbents: Pre-empt SiC MOSFET supply lock-in through captive qualification partnerships with Kyushu foundries before Japanese inverter manufacturers exhaust available capacity. Defend against capital-light EPC entrants by embedding remote diagnostic firmware as mandatory subscription riders in turnkey installation contracts, leveraging existing Schneider Electric and Siemens energy management ecosystem relationships to elevate switching costs. For New Entrants and Emerging Players: Maharashtra and Gujarat manufacturing corridors offer underpenetrated white-space for locally engineered heat-resistant semiconductor packages that satisfy BIS tropical derating certification. Target multi-unit housing surge protection specifications in dense German urban developments where Eaton's specialized designs reveal unmet demand for consolidated power conditioning. Pursue power-purchase agreement bundling models that concentrate procurement authority with financing platforms rather than competing for fragmented homeowner sales. For Investors and Strategic Acquirers: Long-term, this sits as a grid-interdependence play because distributed energy resource penetration is forcing bidirectional power flow architectures that obsolete legacy electromechanical inventories. Acquisition candidates should display embedded firmware subscription revenue streams and demonstrated thermal management innovation under air-cooled constraints. Monitor EU Green Deal building renovation wave execution velocity as the signal for replacement cycle acceleration across 195 million European residential units.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Captive access to Kyushu foundry output secures switching frequency leadership against IGBT-dependent competitors. |
| Firmware Subscription Architecture Deployment | Remote diagnostic stacks reduce truck-roll service costs while extending customer lifetime value in North American premium segments. |
| BIS Certification Investment for Tropical Derating | Indian regulatory compliance creates protected demand exclusion for heat-sensitive import designs in Maharashtra corridors. |
| Multi-Unit Housing Surge Protection Specialization | Centralized bus architectures address unmet demand in dense German urban developments with single-point service accountability. |
| Power-Purchase Agreement Bundling | Subscription-based power quality guarantees displace standalone regulator sales through EPC procurement concentration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and semiconductor foundry capacity disclosures. Primary interviews engaged power electronics design engineers, EPC project developers, utility interconnection officers, and residential electrical contractors across German, Indian, and North American markets. Secondary validation drew from EPA Energy Star specifications, EU F-Gas Regulation documentation, CEA technical standards, and SEC filings from diversified electrical conglomerates. Bottom-up unit shipment estimates triangulate against top-down grid modernization investment flows.
Forecast inputs span product type segmentation across electromechanical and solid-state architectures, technology tiers from PWM through microcontroller-based platforms, application concentration in multi-unit housing versus smart home systems, and end-user procurement authority distribution across utility service providers and residential consumers. CAGRs derive from regression analysis against grid-interconnection code implementation timelines and building renovation wave targets. Industry-specific inputs include IGBT and SiC device qualification timelines, copper concentrate price volatility indices, and firmware update attach rate trajectories.
Practitioners should monitor Japanese foundry capacity utilization, EU F-Gas Regulation enforcement consistency, and Indian rooftop solar leasing penetration for early signals requiring forecast revision. Semiconductor supply disruptions, harmonic compliance testing backlog duration, and electromechanical substitution persistence in Southeast Asian markets constitute material uncertainty factors. Cross-checking against IEA distributed energy resource deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.