
 Train Contactor Market | 2026-2036
Train Contactor Market Size, Share, and Industry Trends Forecast 2026-2036
Train Contactor Market Analytics
EN 50155-compliant contactor specifications is reorganizing procurement criteria across European and Asian rail fleets. Siemens Mobility leverages captive semiconductor fabrication to secure solid-state contactor supply chains. ABB sustains electromagnetic contactor dominance through scale manufacturing in Germany and Switzerland. Schneider Electric differentiates via integrated power distribution architectures that bundle contactors with protection relays.
A train contactor is an electromechanical or solid-state switching device engineered to interrupt or establish high-current circuits, typically rated between 1,000 V and 3,000 V DC or 15 kV to 25 kV AC, within rolling stock electrical systems. Its primary function is to manage power flow between traction converters, auxiliary inverters, and catenary pickup assemblies while withstanding vibration, temperature cycling, and electromagnetic interference endemic to rail environments. Electromagnetic contactors retain the largest installed base due to proven reliability in legacy propulsion systems, though solid-state variants are capturing fastest growth in signaling applications where arc-free operation reduces maintenance intervals. Vacuum contactors command premium positioning in high-voltage power distribution segments where dielectric recovery speed determines system availability. Trackside installations represent a concentrated margin pool as infrastructure renewal programs outpace new rolling stock procurement cycles.
The European Union's F-Gas Regulation and CE marking directives under the MDR framework mandate reduced fluorinated gas content and enhanced fire-resistance documentation for onboard electrical components, effectively filtering non-compliant suppliers from tender participation. The EPA's locomotive emissions standards in the United States indirectly tighten electrical system reliability requirements as diesel-electric hybrids demand more frequent power switching cycles. China's GB standards and NMPA-equivalent rail certification protocols enforce localized testing regimens that extend market access timelines for foreign contactor manufacturers. Stakeholders must weigh regional certification burden against volume concentration when allocating R&D and qualification budgets across geographic footprints.
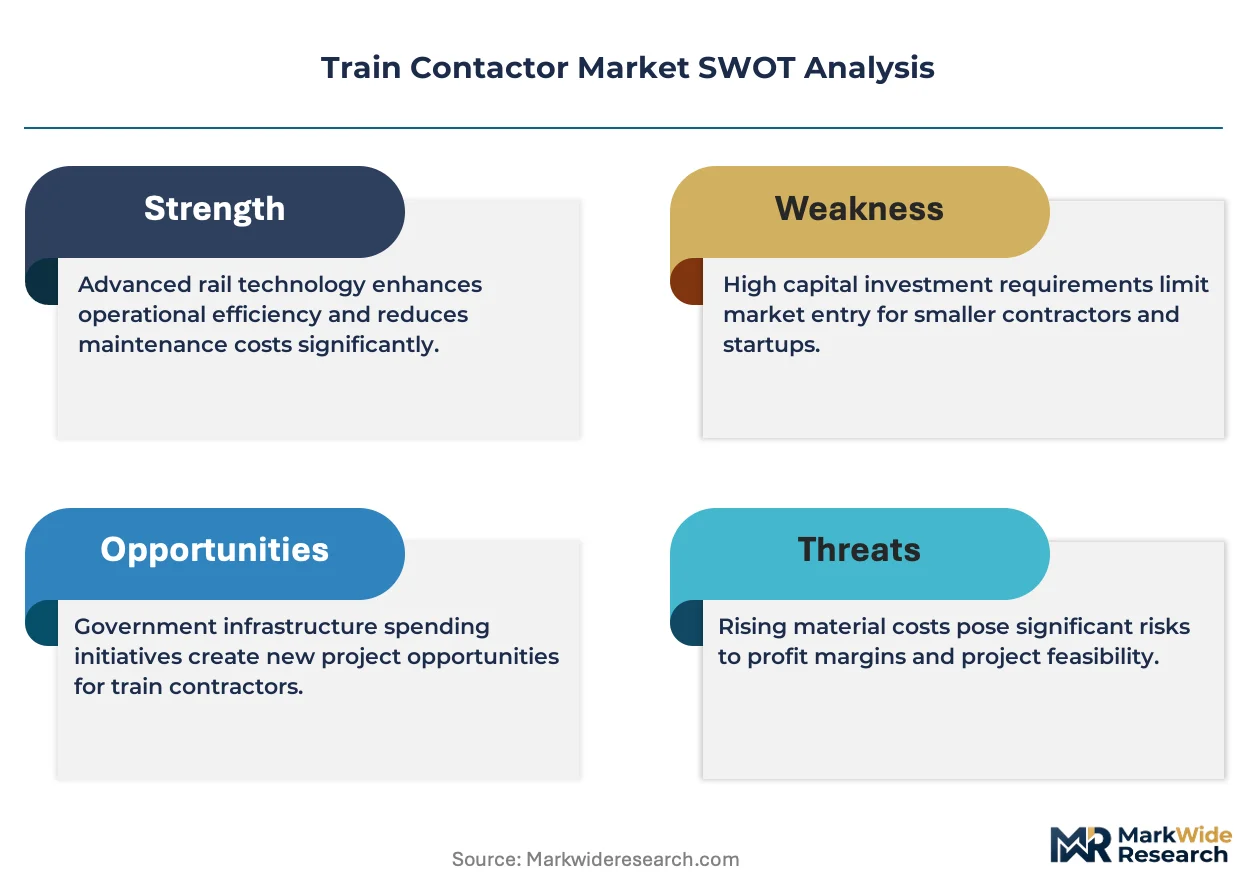
Market Dynamics
Electrification mandates across passenger and freight corridors are forcing rolling stock operators to replace mechanical switching with solid-state architectures, compressing replacement cycles and rewiring supplier qualification protocols.
Growth Catalysts
- EU F-Gas Regulation:Fire-safety mandates for fluorinated gas reduction are accelerating vacuum contactor deployment in European high-speed and commuter fleets.
- China's 25 kV AC expansion:Electromagnetic contactor procurement is intensifying along Beijing-Shanghai and Chengdu-Chongqing corridors as high-speed network density increases.
- Solid-state switching:Silicon carbide power modules are enabling arc-free operation in signaling circuits, reducing maintenance intervals and downtime costs.
Market Restraints
- Copper and silver price volatility:Contact material costs swing with commodity markets, squeezing margin structures for electromagnetic contactor producers.
- German-Swiss supply concentration:Electromagnetic contactor fabrication clusters heavily in Central Europe, creating geographic vulnerability to energy cost shocks.
- EN 50155 certification timelines:Extended qualification periods for onboard electronics filter smaller suppliers from European tender participation.
Strategic Opportunities
- India's suburban electrification:The Railway Board's 25 kV AC traction rollout across Mumbai, Chennai, and Kolkata corridors opens volume procurement for domestic and foreign contactor vendors.
- Digital twin integration:Predictive maintenance platforms are converging with contactor health monitoring, creating bundled service revenue streams.
- US IRA clean rail incentives:Tax credits for zero-emission locomotive retrofits are expanding addressable demand for solid-state power distribution systems.
Industry Challenges
- Power electronics engineering scarcity:Solid-state contactor design requires semiconductor packaging expertise that rail electrical teams rarely possess in-house.
- Legacy system interoperability:Electromagnetic contactor replacement in 30-year-old rolling stock demands custom interface engineering that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Contactor Market |
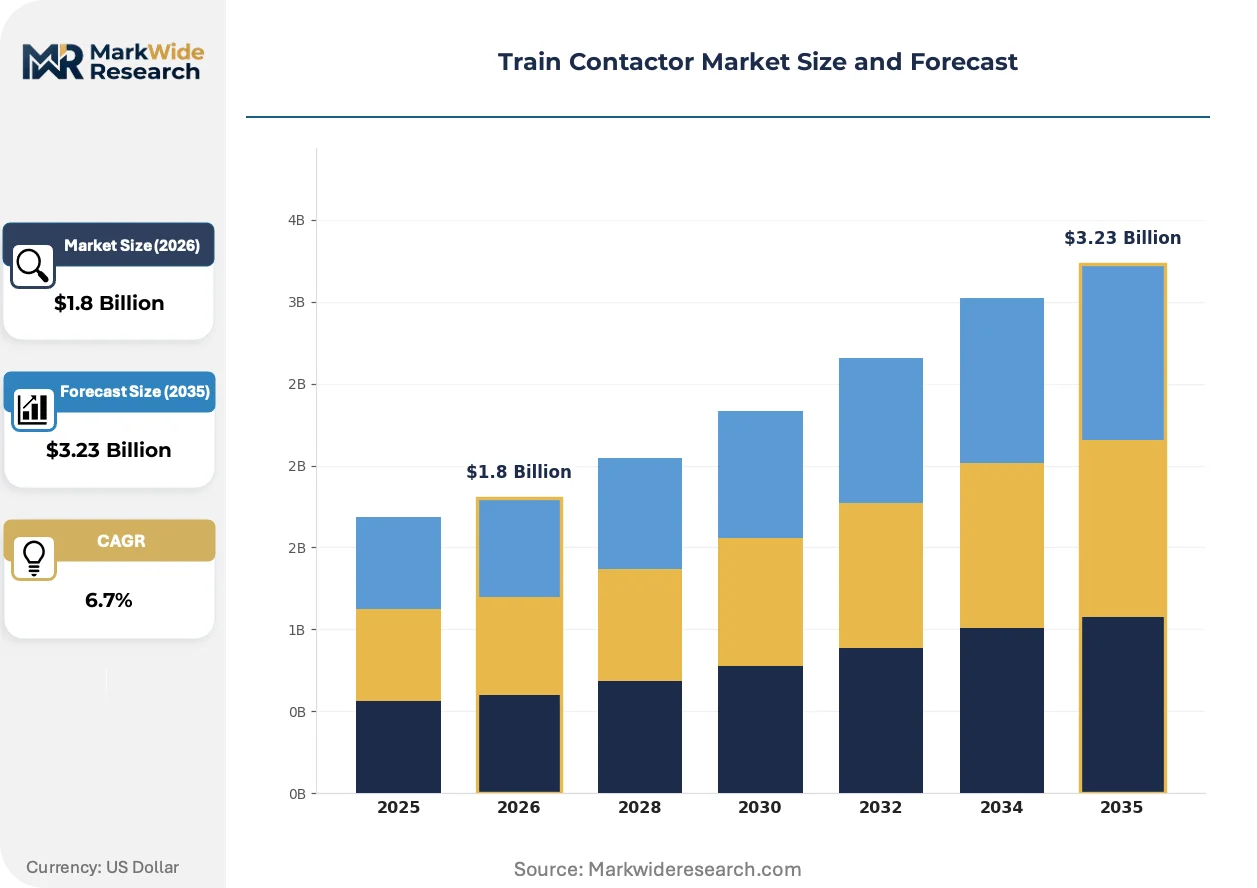
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Solid State, Air, Vacuum End User: Rail Operators, Transit Authorities, Contractors, OEMs Application: Signaling Systems, Power Distribution, Propulsion Systems, Safety Equipment Installation Type: Onboard Systems, Trackside Installations, Control Rooms, Maintenance Facilities |
| Companies Covered | Siemens Mobility, ABB, Schaltbau, Sécheron Hasler Group, Schneider Electric, Alstom, Telema spa, LEGRAND, Sensata Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Contactor Market Evolving Landscape
Power semiconductor packaging and predictive analytics are converging to redefine how rolling stock operators manage electrical switching assets, shifting value capture from hardware sales toward lifecycle performance guarantees.
Solid-state contactors based on silicon carbide MOSFETs are decomposing the traditional electromagnetic contactor value chain by eliminating mechanical wear components. Traction converter manufacturers in Japan and South Korea are adopting these devices fastest for auxiliary inverter circuits. The technology is decomposing maintenance cost structures and compressing supplier margins on replacement parts.
The EU F-Gas Regulation and associated CE marking directives under the MDR framework are mandating reduced fluorinated gas content and enhanced fire-resistance documentation for onboard electrical components. This regulatory pressure is filtering non-compliant Asian suppliers from European tender participation. Vacuum contactor manufacturers with pre-certified EN 50155 portfolios are capturing disproportionate share in French and German fleet renewal programs.
Rail operators are unbundling contactor procurement from rolling stock OEM contracts and establishing direct supplier relationships for aftermarket replacement. Infrastructure managers in Spain and Italy are consolidating purchasing through framework agreements that span trackside and onboard applications. This behavioral shift is compressing distributor margins and forcing component manufacturers to build direct service networks.
Train Contactor Market Segmentation
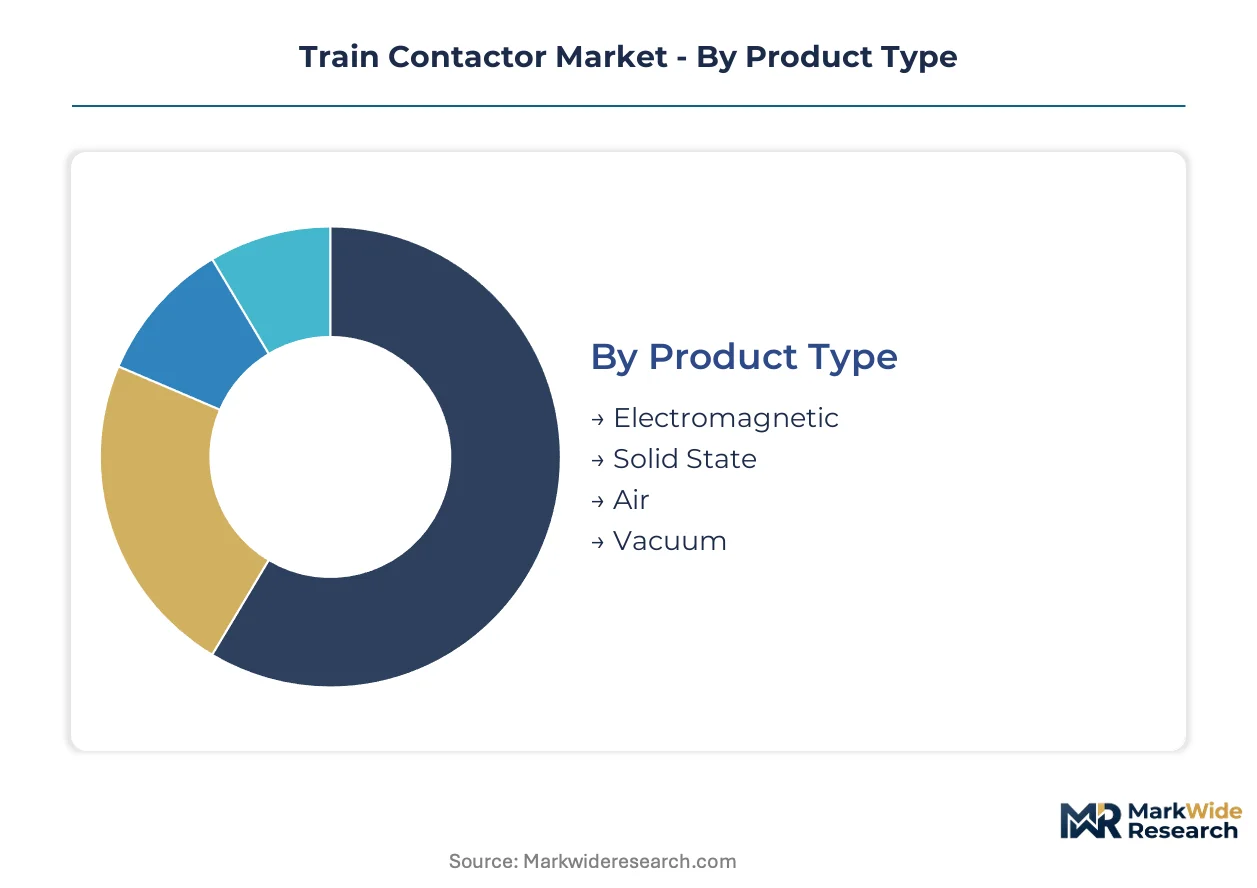
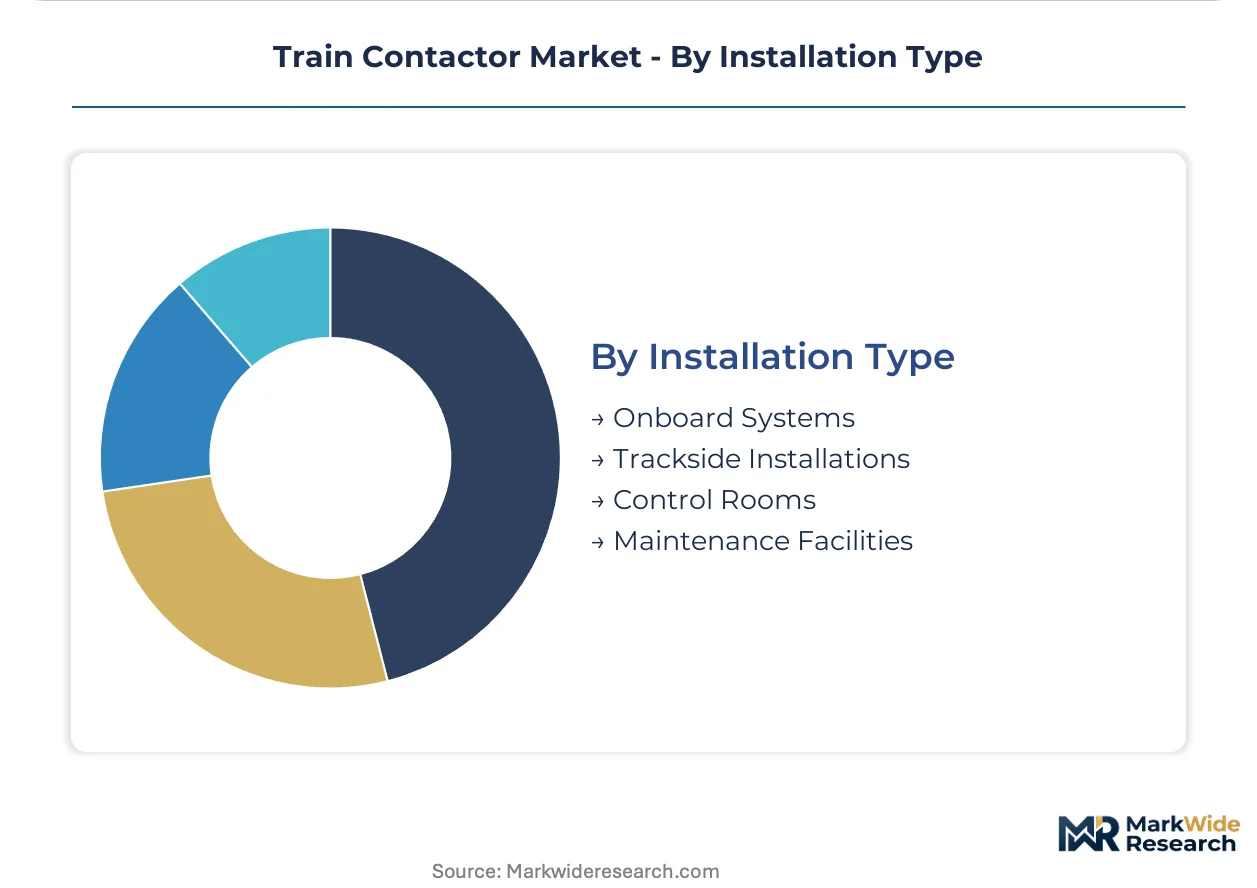
Train contactor procurement patterns diverge sharply across product architectures, end-user procurement models, and installation environments. Each segmentation axis reveals distinct margin structures and qualification barriers that reshape supplier positioning.
Product Type:
Margin pools concentrate in vacuum and solid-state architectures where dielectric performance and semiconductor packaging command technical premiums.
- Electromagnetic:Relies on copper coils and silver-alloy contacts to switch high-current circuits through mechanical actuation. Demand clusters in China's 25 kV AC high-speed corridors where proven reliability outweighs switching speed requirements.
- Solid State:Silicon carbide MOSFETs eliminate arcing and mechanical wear, enabling arc-free operation in auxiliary inverter circuits. Japanese and South Korean traction converter manufacturers are adopting these fastest for signaling applications where maintenance intervals determine lifecycle costs.
- Air:Compressed air drives contact closure in legacy DC traction systems still operational across older European commuter fleets.
- Vacuum:Hermetically sealed contacts with rapid dielectric recovery serve high-voltage power distribution segments where system availability dictates procurement decisions.
The dominant share belongs to Electromagnetic contactors, while Solid State is closing the gap fastest.
End User:
Procurement authority is fragmenting as rail operators bypass rolling stock OEMs to source replacement contactors directly.
- Rail Operators:National railways and private freight carriers with captive maintenance workshops. These buyers prioritize EN 50155-certified inventory pools and framework pricing agreements that span multiple fleet generations.
- Transit Authorities:Municipal and regional bodies managing urban metro and light rail networks. Procurement concentrates in electrified suburban corridors across India where the Railway Board's 25 kV AC expansion is rewiring vendor qualification protocols.
- Contractors:Third-party maintenance providers serving fragmented regional fleets with spot-buy replacement patterns.
- OEMs:Rolling stock manufacturers integrating contactors into original propulsion and auxiliary systems during new-build programs.
Rail Operators capture the largest procurement volume, though Transit Authorities are expanding their share fastest through direct supplier relationships.
Application:
Functional requirements determine contactor specification tiers, with propulsion systems demanding the highest current interruption ratings.
- Propulsion Systems:Manages power flow between traction converters and catenary pickup assemblies. Specifications center on 1,000 V to 3,000 V DC or 15 kV to 25 kV AC ratings with vibration resistance for underframe mounting.
- Signaling Systems:Controls track circuit and interlocking logic where arc-free solid-state switching reduces electromagnetic interference and extends maintenance cycles.
- Power Distribution:Routes auxiliary power to HVAC, lighting, and battery charging subsystems across multiple voltage buses.
- Safety Equipment:Emergency braking and fire suppression circuits requiring failsafe contactor logic with redundant coil configurations.
Propulsion Systems retain the dominant specification share, while Signaling Systems are climbing the fastest as silicon carbide modules penetrate auxiliary circuits.
Installation Type:
Trackside infrastructure renewal is outpacing new rolling stock procurement, concentrating margin capture in ground-based electrical assets.
- Trackside Installations:Substation contactors managing section isolation and feeder switching for 25 kV AC electrification. Infrastructure managers in Spain and Italy are consolidating procurement through multi-year framework agreements.
- Onboard Systems:Underframe and roof-mounted contactors within rolling stock electrical enclosures, subject to EN 50155 shock, vibration, and temperature cycling standards.
- Control Rooms:Centralized SCADA-controlled switching for yard and depot power management.
- Maintenance Facilities:Portable and fixed test rigs for contactor inspection and refurbishment.
Trackside Installations command the steepest margin expansion trajectory, while Onboard Systems retain volume concentration through fleet replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement contexts. India's suburban electrification programs prioritize volume procurement at compressed margins, while European high-speed fleet renewals absorb premium vacuum contactor pricing under stringent fire-safety mandates.
China
Beijing-Shanghai and Chengdu-Chongqing high-speed corridors are driving electromagnetic contactor procurement at scale. GB standards and NMPA-equivalent rail certification protocols enforce localized testing regimens that extend market access timelines for foreign manufacturers. CRRC's supply chain concentration in Changzhou and Zhuzhou anchors domestic fabrication capacity.
Germany
Siemens Mobility and ABB maintain electromagnetic contactor dominance through scale manufacturing in Bavaria and Baden-Württemberg. The EU F-Gas Regulation and CE marking directives under the MDR framework mandate reduced fluorinated gas content for onboard electrical components. Stuttgart's industrial cluster concentrates semiconductor packaging expertise for solid-state traction applications.
India
The Railway Board's 25 kV AC traction rollout across Mumbai, Chennai, and Kolkata corridors is rewiring vendor qualification protocols. CEA electrification mandates and PLI scheme incentives for domestic manufacturing are reshaping procurement criteria. Bhel and Titagarh Wagons anchor fabrication clusters in Jhansi and West Bengal.
United States
EPA locomotive emissions standards are tightening electrical system reliability requirements as diesel-electric hybrids demand more frequent power switching cycles. IRA clean rail tax credits are expanding addressable demand for solid-state power distribution systems. Wabtec's Pittsburgh operations and Siemens Mobility's Sacramento facility concentrate rolling stock electrical integration.
Japan
Hitachi and Toshiba are adopting silicon carbide solid-state contactors fastest for auxiliary inverter circuits in Shinkansen fleet renewals. METI decarbonization roadmaps are accelerating electrification procurement specifications. Nagoya's Chubu industrial corridor concentrates traction converter manufacturing for export markets.
Train Contactor Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes. Electromagnetic contactor fabrication clusters heavily in Central Europe, creating geographic concentration around German-Swiss engineering centers. Solid-state specialists compete on semiconductor packaging expertise rather than scale manufacturing. Two strategic archetypes dominate: diversified industrial conglomerates with captive rail divisions, and specialized electrical component manufacturers with EN 50155 certification depth. Competitive moves center on backward integration into semiconductor supply chains and direct service network construction to bypass distributor margins.
Among European industrial conglomerates, Siemens Mobility and ABB exemplify scale-driven archetypes with integrated manufacturing footprints. Schneider Electric occupies a position bundling contactors with protection relays and power distribution architectures. Sensata Technologies represents the specialized component tier with sensor-to-switch integration capabilities. These three anchors illustrate how supplier positioning fragments across bundled system sales versus discrete component procurement.
| Leading Market Players |
|---|
| Siemens Mobility |
| ABB |
| Schaltbau |
| Sécheron Hasler Group |
| Schneider Electric |
| Alstom |
| Telema spa |
| LEGRAND |
| Sensata Technologies |
| Others |
Value Network & Pricing Analysis
EN 50155 certification timelines simultaneously gate supplier qualification and stratify price tiers, compressing margins for uncertified vendors while allowing compliant manufacturers to capture service-contract premiums across European and Asian rail fleets.
Pricing Analysis
Aftermarket parts and service contracts generate lifetime value that exceeds original equipment sales by substantial multiples. Three-tier pricing structure across EN 50155-certified premium, standard commercial-grade, and economy non-certified tiers reflects certification burden and geographic delivery cost. Cost compression in economy electromagnetic contactor tiers intensifies because copper and silver commodity volatility squeezes margin structures. Transit authorities in India's electrified corridors exhibit highest price sensitivity, while European high-speed operators absorb premium vacuum contactor pricing under F-Gas Regulation mandates.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for semiconductor packaging materials and silver-alloy contact components. Electromagnetic contactor fabrication concentrates in Germany, Switzerland, and China, drawing from copper coil suppliers in Chile and silver contact material processors in South Korea. Single-source vulnerability runs through silicon carbide wafer supply anchored in Taiwan and Japan. Distribution runs through rolling stock OEM integrated procurement channels and direct rail operator framework agreements, with distributor margins compressing as operators unbundle component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The train contactor market operates as a regulatory-moat business where EN 50155 certification depth creates switching costs that entrench qualified suppliers across multi-decade fleet replacement cycles.
For Market Incumbents: Compound certification advantage by deepening semiconductor packaging expertise in Stuttgart and Nagoya clusters to capture solid-state transition premiums. Extend direct service networks into India's suburban electrification corridors before domestic fabrication scales. Defend against silicon carbide module suppliers by bundling predictive maintenance platforms with contactor hardware. For New Entrants and Emerging Players: Fast-track EN 50155 certification through partnership with established European testing laboratories to penetrate French and German fleet renewal programs. Target trackside infrastructure procurement in Spain and Italy where framework agreements favor new qualified entrants over incumbent OEM channels. Lead with digital twin integration as differentiated service bundling to bypass hardware margin compression. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down deadlines reshape the acquisition landscape toward vacuum contactor specialists with pre-certified portfolios. Long-term viability centers on suppliers with captive semiconductor packaging capability or deep rail operator service relationships. Monitor silicon carbide MOSFET cost curves as inflection signal for solid-state displacement velocity in auxiliary inverter segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Packaging | Siemens Mobility's captive fabrication in Stuttgart secures solid-state contactor supply chains against wafer shortage volatility. |
| Direct Service Network Construction | Schneider Electric's bypass of distributor channels captures aftermarket margins in India's 25 kV AC corridor expansion. |
| Digital Twin Platform Integration | Sensata Technologies' predictive maintenance bundling shifts revenue from hardware sales to lifecycle performance guarantees. |
| EN 50155 Certification Fast-Track Partnership | Specialist component manufacturers filter into European tenders through laboratory collaboration accelerating qualification timelines. |
| Trackside Infrastructure Framework Bidding | Consolidated procurement by Spanish and Italian infrastructure managers concentrates margin capture in ground-based electrical assets. |
Research Methodology
Desk research of customs trade databases, rolling stock production registries, and railway electrification procurement disclosures preceded structured interviews with traction converter engineering directors, rail operator procurement managers, infrastructure maintenance heads, and semiconductor packaging specialists. Primary fieldwork across German, Swiss, Chinese, and Indian manufacturing clusters combined with secondary validation against EN 50155 certification registries and EU F-Gas Regulation compliance filings. Bottom-up contactor shipment analysis triangulated against top-down rail electrification capital expenditure tracking.
Variance decomposition across product architecture, installation environment, and end-user procurement model shaped analytical framework construction over the projection horizon. Segmentation dimensions modeled encompass electromagnetic, solid-state, vacuum, and air contactor types; propulsion, signaling, power distribution, and safety equipment applications; onboard, trackside, control room, and maintenance facility installations; plus rail operator, transit authority, contractor, and OEM buyer categories. CAGRs derived from fitted growth curves incorporating electrification mandate intensity, fleet replacement cycle timing, and semiconductor cost trajectory assumptions.
Decision-makers should treat outputs as directional under sustained electrification policy commitment and stable copper-silver commodity regimes; material deviation would warrant model refresh. Specific risks include abrupt F-Gas Regulation enforcement changes, silicon carbide supply disruptions, or Indian domestic content requirement shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
HVDC Converter Station Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Motor Generator Set Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
North America Protective Relays Market
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
North America Surge Arresters Market