
 United States Electric Space Heaters Market | 2026-2036
United States Electric Space Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Space Heaters Market Insights
Modular heating configurations that pair portable units with smart thermostats and air-quality sensors is pivoting buyer choice toward bundled home-climate solutions. Honeywell International Inc. leverages its building-controls heritage to integrate heater hardware with connected-home platforms. Lasko Products LLC anchors the mid-market through broad retail distribution and seasonal merchandising scale. Vornado Air LLC differentiates on vortex airflow engineering that commands premium positioning in specialty channels.
United States electric space heaters are self-contained electromechanical devices that convert electrical energy into thermal output through resistive, radiant, or forced-air elements, typically rated between 750 and 1,500 watts for residential circuits and designed to raise localized air temperature without ducted distribution. Their primary purpose is zone-level thermal comfort in residential, commercial, and temporary settings where central heating is insufficient, unavailable, or economically impractical. Fan-forced and convection units dominate unit volume in residential applications, while radiant formats capture higher margin pools in commercial spot-heating and outdoor installations. Portable design types sustain the largest addressable base through seasonal retail turnover, though wall-mounted and built-in configurations are gaining specification in multi-family construction and hospitality renovation.
DOE appliance efficiency standards, EPA emissions guidelines for power generation that affect operating-cost comparisons, and state-level building electrification mandates in California, New York, and Washington shape product development priorities and market access conditions for electric heater manufacturers. NRTL safety certifications including UL 1278 govern retail distribution eligibility and liability exposure. Stakeholders must monitor evolving state electrification roadmaps and efficiency tier thresholds to align R&D pipelines with compliance windows and utility rebate qualification criteria.
Market Dynamics
State electrification mandates in California, New York, and Washington are compressing product development cycles while DOE efficiency standards force ceramic and infrared technology upgrades across manufacturer portfolios. Cold-climate residential retrofit activity in the Northeast and Midwest sustains replacement demand against this regulatory backdrop.
Growth Catalysts
- DOE Appliance Efficiency Standards:Federal mandates accelerate adoption of higher-efficiency ceramic heating elements and smart thermostat integration, pushing manufacturers toward premium product tiers that qualify for utility rebate programs.
- Cold-Climate Retrofit Demand:Homeowners in Minnesota, Wisconsin, and Michigan supplement aging central HVAC systems with portable units during seasonal heating peaks, sustaining steady replacement cycles.
- Smart Home Convergence:Integration of electric space heaters with connected-home platforms and air-quality sensors is creating bundled climate-control solutions that command higher average selling prices.
Market Restraints
- Electricity Cost Volatility:Regional utility rate spikes in the Northeast compress operating-cost advantages against natural gas alternatives, dampening incremental purchase decisions during high-price periods.
- Residential Circuit Limitations:Standard 15-amp household wiring constrains unit output to 1,500 watts, capping thermal performance and limiting commercial applications without electrical upgrades.
- Seasonal Demand Concentration:Fourth-quarter retail turnover generates 60-70% of annual volume, forcing manufacturers to absorb inventory carrying costs and markdown risk during off-peak months.
Strategic Opportunities
- Multi-Family Built-In Specifications:Wall-mounted and hardwired configurations are gaining traction in hospitality renovation and apartment construction, escaping portable-unit commoditization.
- Commercial Outdoor Spot Heating:Infrared radiant formats capture margin pools in restaurant patios, warehouse loading docks, and construction sites where forced-air solutions prove impractical.
- State Rebate Program Alignment:Utility-sponsored electrification incentives in Washington and New York reward ENERGY STAR-certified units, creating preferential channel access for qualifying manufacturers.
Industry Challenges
- UL 1278 Certification Timelines:NRTL safety testing for new product variants extends 12-16 weeks, delaying seasonal launches and compressing revenue windows for winter-selling products.
- Electronics Supply Fragmentation:Microcontroller and sensor sourcing from Asian contract manufacturers introduces lead-time volatility that disrupts smart-feature rollout schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Space Heaters Market |
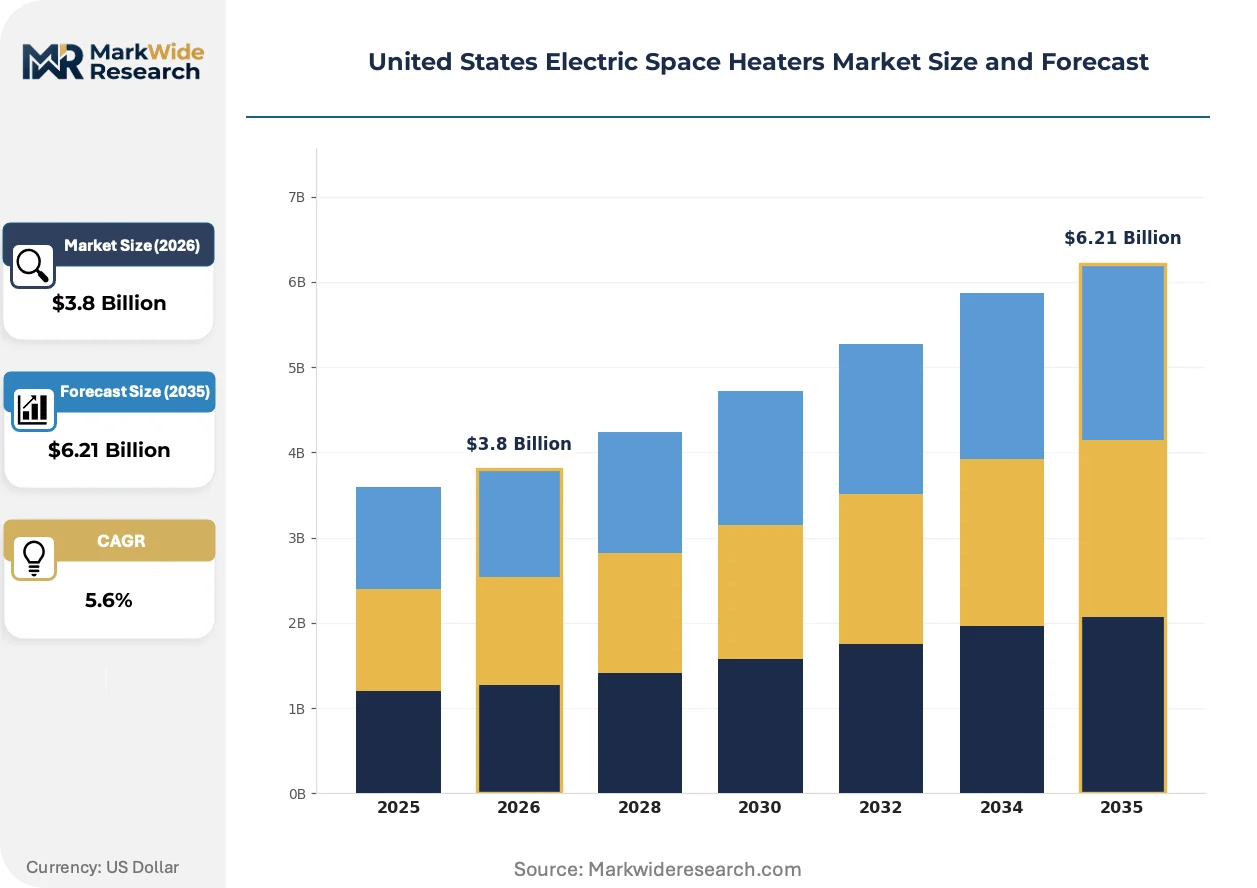
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiant, Convection, Fan-forced, Baseboard Application: Residential, Commercial, Industrial, Temporary Heating Energy Source: Electricity, Solar Power, Battery-operated, Hybrid Design Type: Portable, Wall-mounted, Ceiling-mounted, Built-in |
| Companies Covered | Honeywell International Inc., Dyson Ltd., Lasko Products LLC, De'Longhi Appliances S.r.l., Crane, Daikin Industries Ltd., Newell Brands Inc., Vornado Air LLC, Dr. Infrared Heater, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Space Heaters Market Trends and Innovations
Product engineering is pivoting toward modularity and connectivity as manufacturers seek differentiation beyond wattage ratings. Ceramic and infrared technologies are displacing legacy wire-element designs across price tiers.
Ceramic positive temperature coefficient heating elements are rewriting thermal efficiency benchmarks in residential applications. Homeowners in the Northeast and Midwest specify these units for supplemental zone heating. The technology is compressing market share for conventional wire-coil designs that lack tip-over safety integration.
EPA emissions guidelines affecting power-generation cost comparisons are reshaping consumer operating-cost calculations nationwide. Industrial and commercial buyers now factor carbon-intensity metrics into equipment selection alongside thermal output ratings. Facilities in states with aggressive renewable portfolio standards show strongest preference for electric over fossil-fuel alternatives.
Retail channel consolidation is concentrating buyer power among big-box and e-commerce platforms that demand exclusive SKUs and promotional funding. Independent hardware stores and HVAC distributors lose assortment authority to seasonal merchandising programs. This shift is most visible in the Midwest, where Menards and Fleet Farm dominate winter heating displays with private-label and exclusive-brand allocations.
United States Electric Space Heaters Market Segmentation
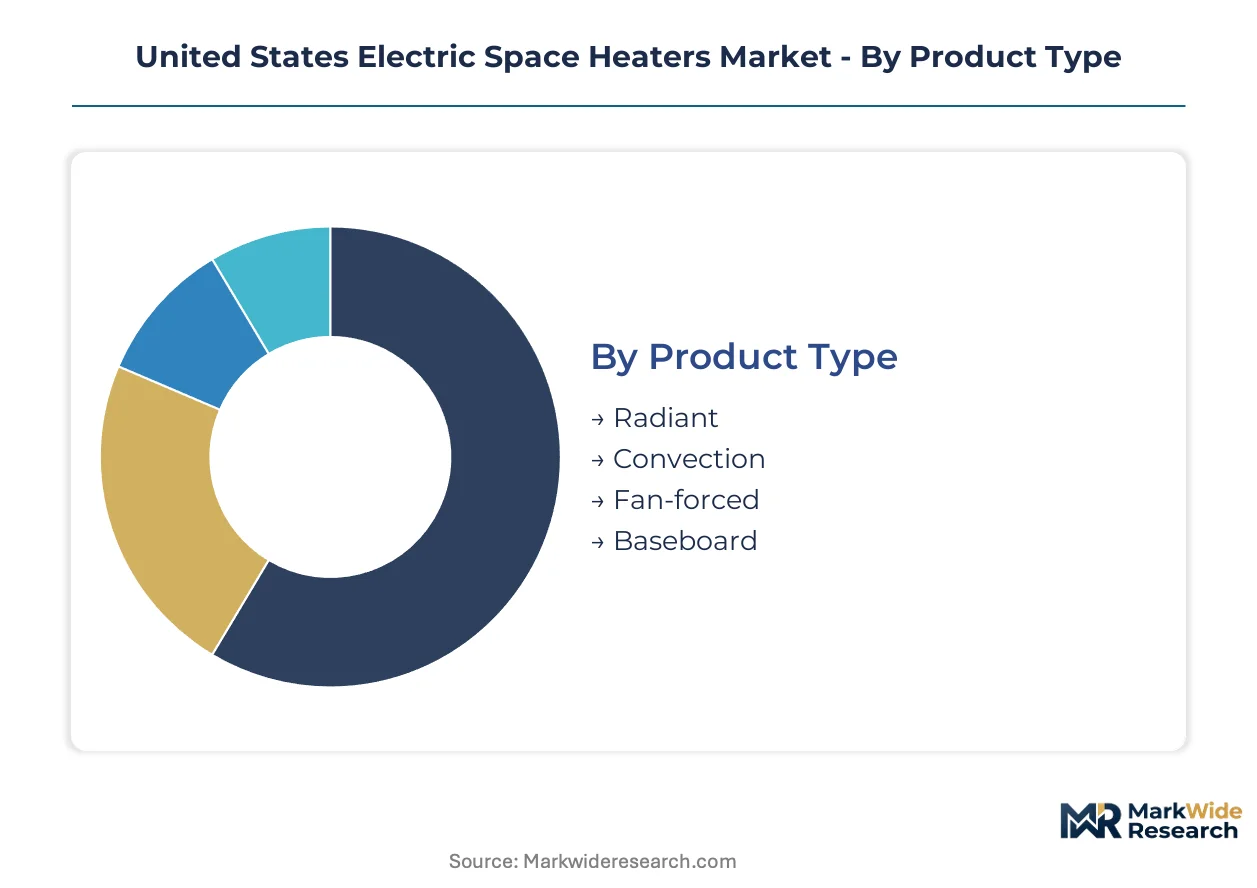
Electric space heater segmentation reveals how UL 1278 certification requirements, installation complexity, and end-use thermal loads fragment demand across distinct product configurations. Each category carries unique compliance burdens and channel economics that shape manufacturer portfolio priorities.
Product Type:
UL 1278 governs all residential formats, while commercial radiant installations trigger additional OSHA workplace heating guidelines. Certification depth varies by thermal element technology and tip-over safety integration.
- Radiant:Infrared quartz or carbon fiber elements deliver directional heat without air circulation, making them suitable for allergy-sensitive environments. Restaurant patios in Minnesota and Wisconsin specify these units for outdoor dining extensions, though bulb replacement costs temper residential adoption.
- Fan-forced:Ceramic PTC elements with integrated blowers dominate unit volume through rapid heat distribution and compact footprints. Michigan homeowners deploy these as primary supplemental heat in home offices and bedrooms during shoulder seasons, driving consistent replacement cycles.
- Convection:Oil-filled or mica-panel designs circulate heat through natural airflow without moving parts, appealing to noise-sensitive users. These units carry lower fire-risk profiles that simplify insurance compliance in multi-family housing.
- Baseboard:Hardwired convection strips require dedicated 240V circuits and professional installation, limiting them to new construction and major renovation projects. Washington state electrification mandates are accelerating specification in apartment developments seeking fossil-fuel elimination.
Leading the category by volume: Fan-forced. Growing fastest: Radiant.
Application:
End-use thermal load profiles and duty-cycle intensity determine whether portable residential units or fixed commercial installations command procurement budgets.
- Residential:Seasonal supplemental heating in single-family homes drives 60-70% of annual retail turnover through big-box and e-commerce channels. Cold-climate states concentrate demand where aging furnaces create zone-heating needs.
- Commercial:Retail storefronts, offices, and hospitality venues require continuous-duty units with enhanced safety interlocks and longer warranty terms. ENERGY STAR certification increasingly gates utility rebate eligibility in New York and California.
- Industrial:Warehouse loading docks and manufacturing floor stations demand high-output radiant or fan-forced units with ruggedized housings. OSHA compliance for worker comfort standards shapes specification in northern-tier facilities.
- Temporary Heating:Construction sites and event venues deploy rental fleets of portable units during cold-weather operations. Short-term deployment cycles prioritize durability and rapid deployment over efficiency ratings.
Residential claims the largest revenue pool. Commercial applications are expanding most quickly as electrification mandates penetrate building codes.
Energy Source:
Grid dependency dominates, though distributed generation and storage integration are emerging in off-grid and resilience-oriented installations.
- Electricity:Standard 120V residential circuits power the vast majority of units, with 240V configurations for baseboard and high-output commercial models. Regional utility rate structures in the Northeast directly influence operating-cost competitiveness against gas alternatives.
- Solar Power:Off-grid cabins and net-zero residential projects pair DC-rated units with rooftop generation and battery storage. California's Title 24 building standards accelerate specification in new construction.
- Battery-operated:Rechargeable lithium-ion units serve camping, emergency preparedness, and construction site mobility needs. Limited runtime and thermal output constrain addressable market penetration.
- Hybrid:Dual-source units combining grid power with battery backup address resilience demand in storm-prone regions. Premium pricing limits adoption to high-income preparedness segments.
Grid-tied electricity dominates unit economics. Solar-integrated configurations are climbing the fastest as distributed generation costs decline.
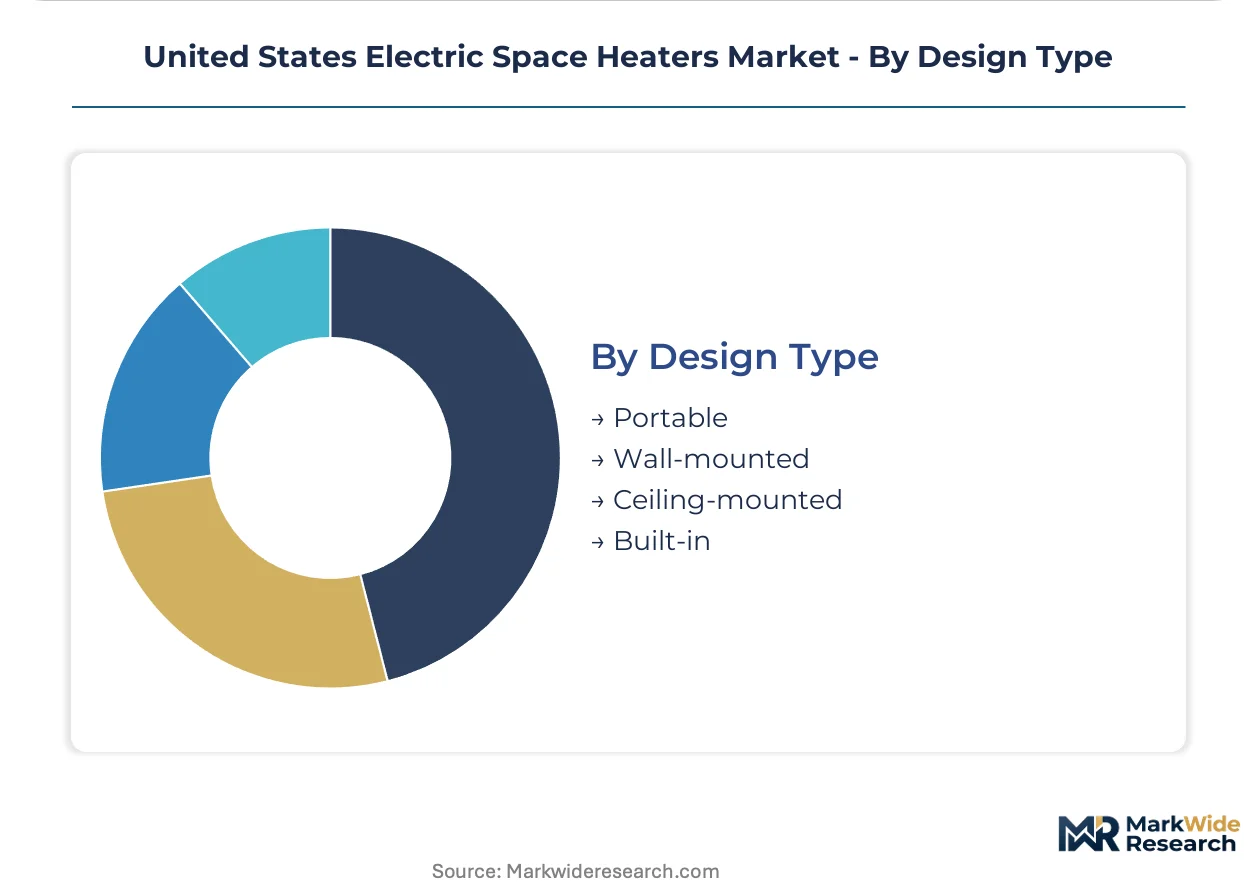
Design Type:
Installation permanence and mobility requirements split demand between seasonal retail turnover and specification-driven built-in projects.
- Portable:Freestanding units with caster bases or carry handles sustain the largest addressable market through seasonal retail replenishment. Tip-over switches and cool-touch housings are mandatory for UL 1278 compliance in residential channels.
- Wall-mounted:Hardwired or plug-in brackets free floor space and reduce tip-over risk in high-traffic commercial environments. Hospitality renovation projects in the Northeast are specifying these for guest room retrofits.
- Ceiling-mounted:Infrared radiant panels target warehouse and manufacturing applications where floor space is constrained and directed heat zones are required. Installation requires structural assessment and electrical contractor involvement.
- Built-in:Fully integrated wall cavities or toe-kick plinths in kitchen and bath cabinetry deliver invisible climate control. Multi-family developers in Washington and New York specify these to meet electrification mandates without sacrificing aesthetic standards.
Portable designs command unit volume leadership. Built-in configurations are gaining share fastest as new construction electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed census tracts across cold-climate states concentrate electric space heater demand through tax-advantaged residential rehabilitation projects. State electrification mandates and utility rebate programs reshape procurement patterns in targeted sub-regional markets.
Northeast Corridor
Massachusetts and New York homeowners drive replacement cycles for aging central HVAC systems through supplemental zone heating. New York's Clean Heat program rewards ENERGY STAR-certified units with utility rebates that compress payback periods. Boston's dense multi-family housing stock accelerates wall-mounted and built-in specifications in renovation projects.
Upper Midwest
Minnesota, Wisconsin, and Michigan sustain the highest per-capita unit demand through extreme seasonal heating loads and prolonged shoulder seasons. Wisconsin Focus on Energy rebates incentivize ceramic PTC technology upgrades over legacy wire-element designs. Minneapolis-St. Paul retail channels generate concentrated fourth-quarter turnover through big-box seasonal merchandising programs.
Pacific Northwest
Washington state's building electrification mandates accelerate specification in new multi-family construction and hospitality renovation. Seattle's Title 24-aligned building codes drive built-in and hardwired configurations over portable alternatives. Oregon's renewable portfolio standards reshape operating-cost comparisons against fossil-fuel alternatives in commercial applications.
Southwest
California's Title 24 building standards and SB 100 electrification roadmap accelerate solar-integrated and battery-backup heater specifications in net-zero residential projects. Los Angeles basin multi-family developers specify invisible climate-control solutions to meet aesthetic and efficiency mandates simultaneously. Arizona's utility rate structures create intermittent operating-cost disadvantages during peak demand periods.
United States Electric Space Heaters Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price and technology segments. The vendor base splits between building-controls heritage players, seasonal appliance specialists, and airflow engineering boutiques. Three archetypes dominate: integrated smart-home platforms, retail-scale seasonal merchandisers, and premium vortex-technology engineers. Competitive moves concentrate on strategic partnerships with connected-home ecosystems and geographic expansion through exclusive retail allocations.
Among diversified conglomerates, Honeywell International Inc. and Daikin Industries Ltd. occupy positions leveraging building-automation heritage toward climate-control integration. Lasko Products LLC exemplifies the mid-market retail-scale archetype through broad distribution reach. Vornado Air LLC anchors the premium engineering tier with vortex airflow specialization. Dr. Infrared Heater represents focused radiant-technology positioning in commercial spot-heating applications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Dyson Ltd. |
| Lasko Products LLC |
| De'Longhi Appliances S.r.l. |
| Crane |
| Daikin Industries Ltd. |
| Newell Brands Inc. |
| Vornado Air LLC |
| Dr. Infrared Heater |
| Others |
Pricing and Supply Chain Analysis
State-level electrification mandates in Washington and New York are forcing manufacturers to source UL 1278-certified ceramic PTC elements and smart-control microcontrollers from qualified suppliers, compressing procurement timelines and elevating input costs for compliant product tiers. This specification-driven demand is concentrating purchasing power among vendors with pre-certified component libraries, widening cost spreads between premium connected units and legacy wire-element designs.
Pricing Analysis
Short lead-time premiums for UL 1278-certified ceramic heating elements and integrated smart sensors command pricing advantages over spot-market wire-coil inventory with longer certification cycles. Three-tier pricing structure across premium smart-home-integrated, standard ENERGY STAR-certified, and economy wire-element tiers separates buyers by connectivity requirements and rebate eligibility. Cost compression in the economy tier is intensifying because raw aluminum and copper volatility squeezes margin on legacy designs. Residential retrofit buyers in Minnesota and Michigan show highest price sensitivity, while hospitality developers in the Northeast prioritize specification compliance over unit cost.
Supply Chain Analysis
UL 1278 certification gating restricts component sourcing to NRTL-qualified suppliers in China, Mexico, and domestic US contract manufacturers with established safety testing relationships. Ceramic PTC elements, microcontroller boards, and tip-over safety switches draw from concentrated Asian electronics manufacturing clusters with secondary metal fabrication in Mexico. Single-source vulnerability for specialized heating element substrates creates exposure to regional logistics disruptions. Distribution runs through big-box retail seasonal programs and HVAC wholesale channels with divergent inventory carrying requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where DOE appliance efficiency standards and UL 1278 certification timelines create a barrier-to-entry moat favoring incumbents with pre-qualified supply relationships and established NRTL testing partnerships.
For Market Incumbents: Extend certification-advantaged positioning by accelerating ceramic PTC capacity commitments ahead of efficiency tier escalations, while consolidating smart-home platform partnerships to lock in connected-product specifications before rebate program windows narrow. Threat from Asian contract manufacturers with direct retail channel access demands defensive moves in exclusive retail allocations. Vertical integration into heating element substrate sourcing anchors margin control against commodity volatility. For New Entrants and Emerging Players: Battery-backup hybrid configurations targeting California net-zero residential projects offer a technology-first wedge with premium positioning outside commoditized portable segments. Solar-integrated DC-rated units for off-grid construction represent the most penetrable white-space application. Go-to-market through specialty HVAC distributors serving Title 24-compliant multi-family developers bypasses big-box promotional funding requirements. For Investors and Strategic Acquirers: The window for entry favors building-controls heritage players with smart-home ecosystem integration capabilities and established utility rebate program relationships. Long-term viability centers on manufacturers with certified component libraries and regional logistics footprints resilient to tariff exposure. Watch ENERGY STAR tier threshold escalations as the signal for consolidation pressure on economy-tier specialists lacking R&D scale.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Home Platform Integration | Honeywell's connected-home heritage enables bundled climate-control solutions commanding premium positioning. |
| Ceramic PTC Technology Licensing | Proprietary heating element designs differentiate against wire-coil commoditization in efficiency-tier transitions. |
| Utility Rebate Program Alignment | ENERGY STAR certification gates preferential channel access in Washington and New York electrification markets. |
| Multi-Family Built-In Specification | Hardwired configurations escape portable-unit seasonality through hospitality renovation and apartment construction pipelines. |
| NRTL Certification Pre-Qualification | Established UL 1278 testing relationships compress seasonal launch timelines and reduce new product introduction risk. |
Research Methodology
Trade association filings, DOE appliance efficiency rulemakings, and utility rebate program databases formed the secondary backbone, supplemented by customs records tracking heating element and electronics imports. Primary interviews with product development directors at major manufacturers, retail category buyers at big-box chains, and HVAC distribution procurement managers validated specification trends and channel economics. Bottom-up unit shipment modeling triangulated against top-down retail audit data from seasonal merchandising programs.
Historical trendline analysis of replacement cycles, electrification mandate adoption curves, and efficiency standard phase-in timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application end-use, installation design, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating retrofit activity intensity, rebate program expansion, and smart-home penetration rates. Industry-specific inputs included NRTL certification pipeline data and regional utility rate structure forecasts.
Several conditions sit outside the modeled scope, including unanticipated EPA power-generation rule shifts, extreme weather event frequency affecting seasonal demand patterns, and semiconductor supply disruptions beyond current lead-time volatility. Forecasts reflect assumptions about regulatory implementation schedules and rebate program continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
3rd Rail Current Collector Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Busway-Bus Duct Market
Electrical Power Equipment
GCC Induction Motor Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
AV Power Conditioners Market