
 Europe Solar Microinverter Market | 2026-2036
Europe Solar Microinverter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Solar Microinverter Market Intelligence
Remote monitoring and predictive maintenance software is decoupling hardware sales from long-term revenue streams in the Europe solar microinverter landscape. Enphase Energy leverages its subscription-based monitoring platform to sustain recurring revenue beyond initial equipment deployment. SMA Solar Technology anchors its competitive stance through deep R&D intensity in grid-forming inverter capabilities. Delta Electronics differentiates via manufacturing scale across its European production footprint.
A solar microinverter is a compact DC-to-AC power conversion device installed at individual photovoltaic module level, typically rated between 250W and 2,000W with peak efficiency exceeding 96% and integrated maximum power point tracking. Its primary commercial purpose is to optimize energy harvest per panel while eliminating single-point failure risks inherent to string inverter architectures. Single-phase units dominate residential deployments across European markets where rooftop constraints favor granular power electronics. Three-phase configurations occupy the fastest-expanding margin pool as commercial and small utility projects scale beyond kilowatt thresholds. Hybrid microinverters incorporating battery-ready DC coupling are capturing premium positioning as storage attachment rates climb.
The EU Green Deal's REPowerEU solar targets, CE marking requirements under the Low Voltage Directive, and Germany's Bundesnetzagentur grid codes collectively shape product certification pathways and interconnection standards for microinverter suppliers. REACH compliance on electronic component substances further constrains material sourcing decisions across the European value chain. Stakeholders must monitor evolving network code harmonization between national regulators and the accelerating integration of cybersecurity mandates into inverter firmware requirements.
Market Dynamics
Module-level power electronics are compressing string inverter margins across European residential rooftops as installers prioritize granular monitoring and fault isolation over centralized conversion architectures.
Growth Catalysts
- REPowerEU solar deployment mandates:The EU Green Deal's binding national targets for distributed generation capacity are accelerating procurement timelines for rooftop installations in Germany, Spain, and Italy.
- F-Gas Regulation phase-down:Fluorinated gas restrictions are forcing cooling system redesigns toward air-cooled and dielectric-fluid architectures that favor compact microinverter form factors.
- Southern European irradiance economics:High solar resource concentration across Iberian and Italian markets improves payback periods for premium module-level electronics relative to northern European deployments.
Market Restraints
- Silicon carbide substrate costs:Wide-bandgap semiconductor feedstock volatility constrains margin expansion for high-efficiency microinverter designs targeting the 96%-plus efficiency threshold.
- East Asian power electronics concentration:Magnetic component and capacitor supply chains cluster in Taiwan and mainland China, exposing European assemblers to trans-shipment risk and tariff exposure.
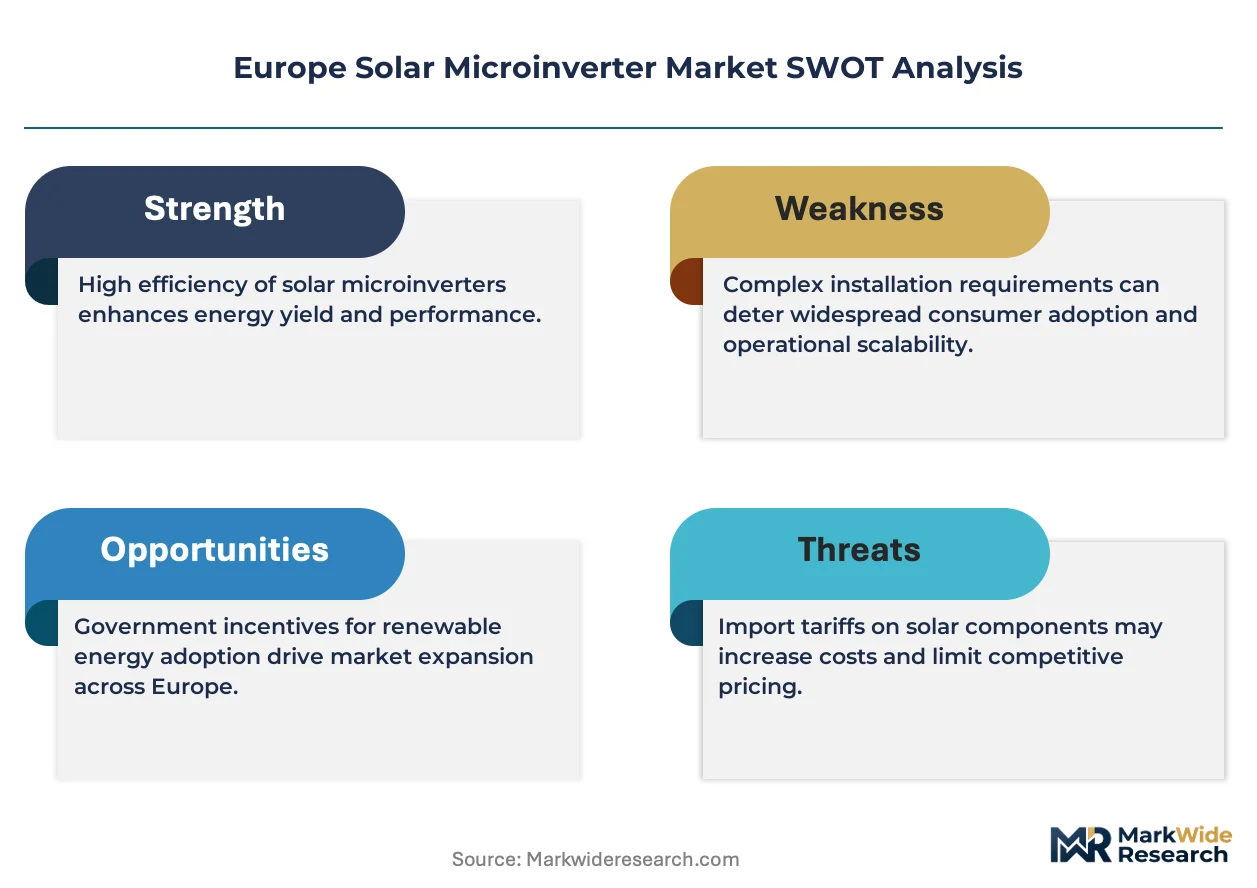
- String inverter substitution in utility-scale:Centralized and string architectures retain cost advantages above 50kW thresholds, capping microinverter addressable market in commercial ground-mount segments.
Strategic Opportunities
- Eastern European rooftop underpenetration:Poland, Romania, and Bulgaria exhibit sub-5% residential solar attachment rates with improving grid-parity economics and nascent subsidy frameworks.
- Hybrid battery-ready microinverters:DC-coupled storage integration enables single-installer deployment models that capture storage attachment revenue streams alongside generation hardware.
- CE marking cybersecurity mandates:Incoming EU network code requirements for inverter firmware authentication create compliance moats for pre-certified suppliers against uncertified import competition.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent in magnetics design and thermal management for high-density conversion remains concentrated in German and Swiss industrial clusters, constraining R&D scaling.
- Multi-jurisdictional certification timelines:Harmonization gaps between Germany's Bundesnetzagentur grid codes, Spain's RD 244, and Italy's CEI 0-21 standards extend product launch cycles by 8-14 months.
- Legacy string inverter installed base:Retrofit compatibility limitations and sunk-cost psychology among existing residential owners slow replacement demand for module-level upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Solar Microinverter Market |
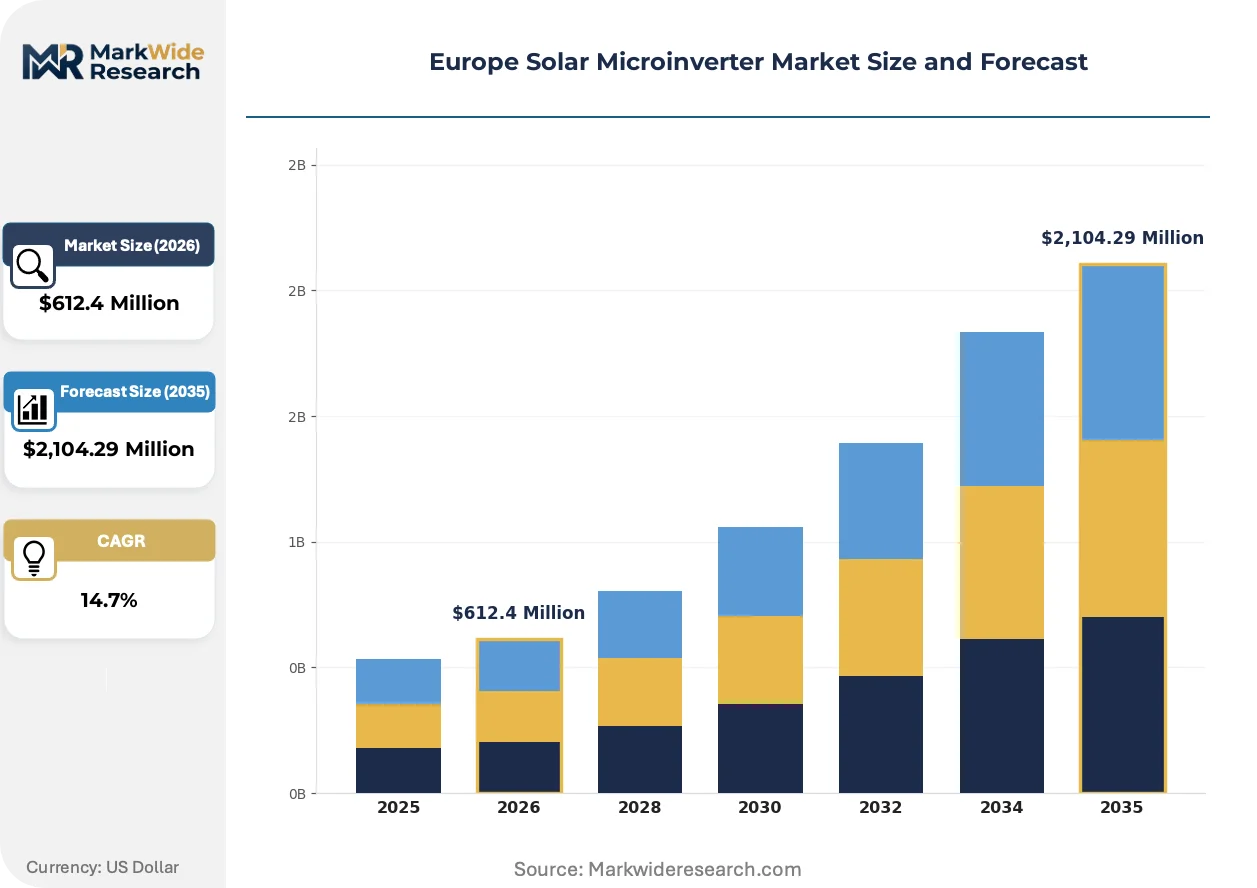
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,104.29 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Multi-Channel, Hybrid Installation Type: Roof-Mounted, Ground-Mounted, BIPV, Off-Grid End User: Residential, Commercial, Industrial, Utilities Technology: DC-AC Conversion, MPPT, Smart Monitoring, Wireless Communication |
| Companies Covered | Sungrow Power Supply, Delta Electronics, Enphase Energy, Hitachi, Canadian Solar, SolarEdge Technologies, Huawei Technologies, Sensata Technologies, SMA Solar Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Solar Microinverter Market Strategic Shifts & Innovations
Digital twin architectures and predictive analytics are decoupling hardware margins from long-term service revenue as European installers prioritize lifecycle value capture over upfront equipment procurement.
GaN-based switching topologies are overtaking silicon IGBT designs in next-generation microinverters by enabling 50kHz-plus switching frequencies that shrink magnetic component volume by 40%. German and Dutch residential installers are specifying these units for space-constrained rooftop configurations. The technology is compressing bill-of-material costs for 2kW-rated single-phase units while pushing peak efficiency toward 98%.
The EU F-Gas Regulation's staged phase-down of hydrofluorocarbon coolants is mandating air-cooled thermal architectures for outdoor-rated power electronics. Manufacturers are redesigning heat sinks and enclosure sealing to maintain IP65 ratings without refrigerant-based cooling. Southern European markets with ambient temperatures exceeding 40°C face the steepest engineering constraints and are driving adoption of dielectric-fluid immersion prototypes.
Installer purchasing cooperatives in France and Belgium are consolidating procurement volumes to extract pricing concessions and technical support commitments from microinverter suppliers. These buying groups now represent 30-40% of residential channel volume in Benelux markets, compressing distributor margins and forcing direct manufacturer engagement. The shift is most visible in Flanders, where regional installer associations have established pooled warehousing and logistics infrastructure.
Europe Solar Microinverter Market Segmentation
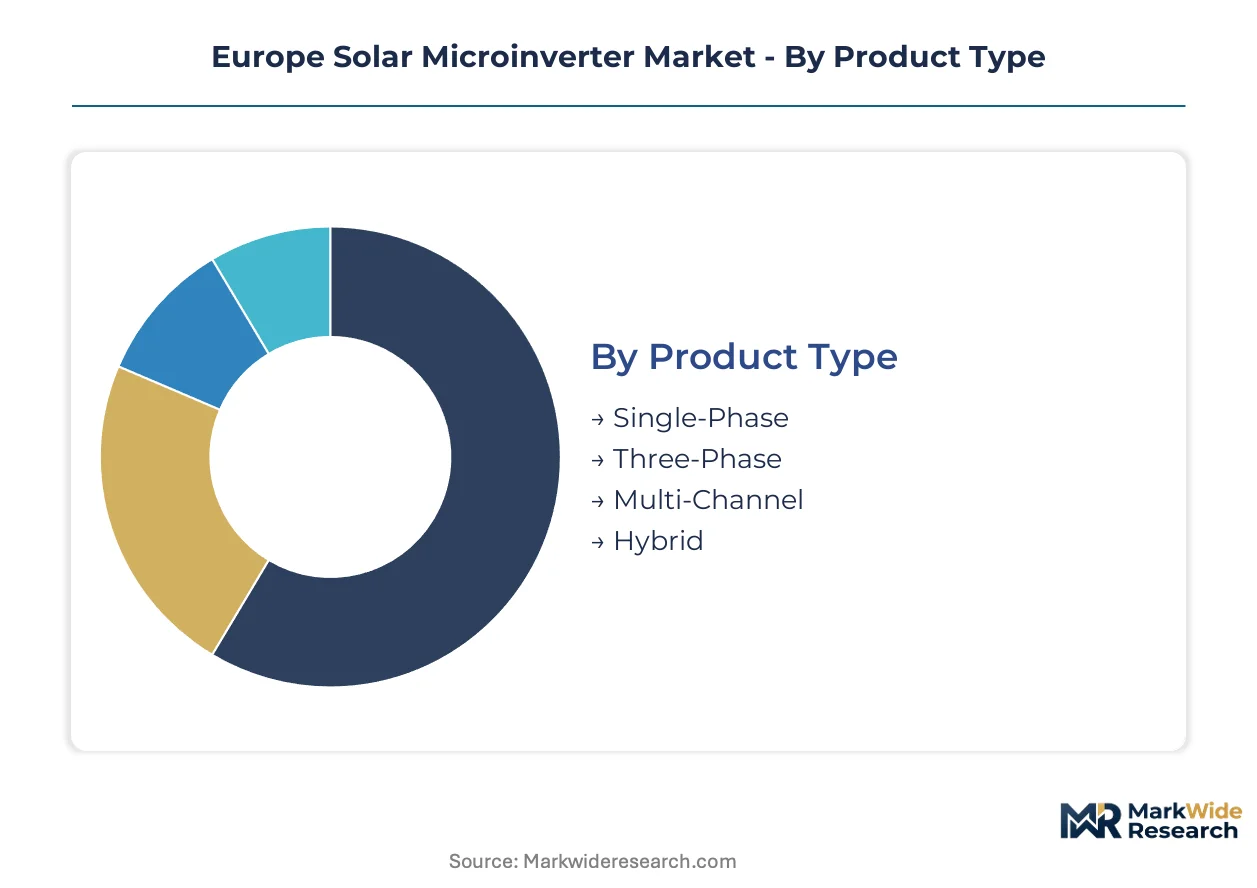
Product architecture in the Europe solar microinverter market fragments across power rating thresholds, mounting configurations, and grid-interconnection requirements. Installers select configurations based on rooftop constraints, regulatory interconnection standards, and storage integration roadmaps.
Product Type:
Single-phase units dominate volume shipments while three-phase variants command premium positioning in commercial deployments.
- Single-Phase:Rated between 250W and 800W, these compact units integrate beneath individual photovoltaic modules on residential rooftops. German and Italian installers specify single-phase microinverters for sub-10kW systems where grid codes mandate module-level rapid shutdown. Mature deployment sits with single-phase units across established Southern European markets. Newer deployment is concentrated in three-phase configurations as commercial project scales expand.
- Three-Phase:Delivering 1.2kW to 2kW per unit, three-phase microinverters target small commercial rooftops and agricultural installations above 30kW aggregate capacity. Spanish and Dutch project developers favor these units for three-phase grid connections that avoid phase-balancing equipment. CE marking under the Low Voltage Directive and compliance with Germany's Bundesnetzagentur grid codes shape certification requirements.
- Multi-Channel:Dual and quad-channel architectures reduce per-watt installation labor by serving two to four modules through a single enclosure.
- Hybrid:Battery-ready DC coupling enables storage attachment without separate charge controller hardware, capturing premium positioning as residential storage penetration climbs.
Single-phase architectures anchor residential volume. Hybrid configurations are expanding most quickly as storage attachment rates accelerate across Germany and Austria.
Installation Type:
Mounting configuration determines thermal management requirements, enclosure IP ratings, and cabling topologies for European deployments.
- Roof-Mounted:Direct module attachment beneath framed photovoltaic panels exposes electronics to ambient temperature cycling and humidity. Southern European markets with summer peaks exceeding 40°C drive demand for enhanced heat-sink designs and dielectric-fluid immersion prototypes. Mature deployment sits with roof-mounted systems across Germany, Italy, and Spain. Newer deployment is concentrated in building-integrated configurations as architectural PV specifications proliferate.
- Ground-Mounted:Elevated rack installations in commercial and agricultural settings permit passive cooling airflow and simplified maintenance access. French and Polish ground-mount projects favor microinverters over string architectures when shading from terrain or vegetation creates mismatch conditions.
- BIPV:Building-integrated photovoltaic applications demand ultra-low profile enclosures that fit within curtain-wall or roofing material thickness constraints.
- Off-Grid:Standalone systems for remote Alpine cabins and Mediterranean island installations require integrated battery management and load-shedding controls.
Roof-mounted systems retain volume leadership. BIPV integration is gaining share fastest as EU Green Deal building renovation mandates expand.
End User:
Customer scale thresholds determine power aggregation strategies, monitoring sophistication, and service contract structures.
- Residential:Single-family and multi-family rooftop owners prioritize granular panel-level monitoring and rapid fault isolation over maximum efficiency. German residential attachment rates exceed 15% in key postal codes, while Polish and Romanian markets remain below 5% penetration. Mature deployment sits with residential end users across Western European markets. Newer deployment is concentrated in commercial segments as small-business solar financing instruments mature.
- Commercial:Small and medium enterprises with 30kW to 250kW rooftop capacity balance installation cost against operational visibility. Belgian and Dutch commercial installers specify microinverters for retail and logistics building portfolios where shading from HVAC equipment creates persistent mismatch.
- Industrial:Manufacturing facilities with flat-roof assets above 250kW face string inverter competition on pure cost grounds.
- Utilities:Distributed generation portfolios and community solar programs represent emerging procurement channels for aggregated microinverter deployments.
Residential customers anchor current revenue. Commercial end users are climbing the fastest as installer purchasing cooperatives consolidate procurement volumes.
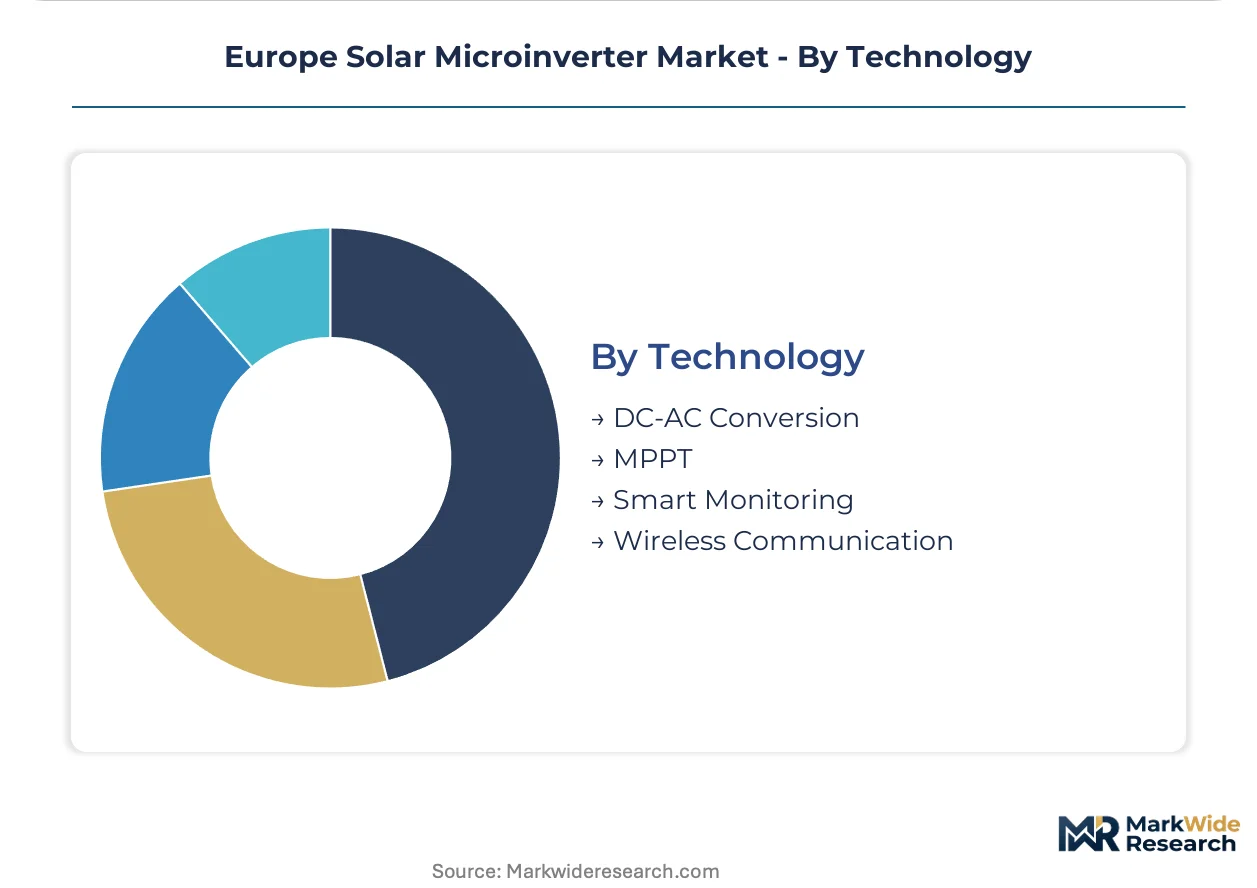
Technology:
Functional subsystem differentiation separates commodity conversion hardware from value-added intelligence layers.
- DC-AC Conversion:Silicon IGBT and emerging GaN-based switching topologies define efficiency ceilings and magnetic component volume. GaN devices enabling 50kHz-plus switching frequencies are compressing bill-of-material costs for next-generation designs. Mature deployment sits with conventional DC-AC conversion across price-sensitive market tiers. Newer deployment is concentrated in smart monitoring integration as remote diagnostics become standard specification.
- MPPT:Module-level maximum power point tracking isolates shading and soiling losses to individual panels, delivering 5-25% energy harvest gains over string architectures in partially shaded conditions.
- Smart Monitoring:Cloud-connected firmware enables predictive maintenance, performance benchmarking, and subscription-based service revenue streams.
- Wireless Communication:Zigbee, Sub-GHz, and power-line carrier protocols eliminate DC cabling between module and aggregation gateway.
MPPT functionality is universal across deployed base. Smart monitoring layers are expanding most quickly as installers prioritize lifecycle value capture over upfront equipment margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich's solar technology corridor anchors European microinverter engineering talent, with Bavarian research institutes feeding product development pipelines for deployment across Southern European rooftops.
Germany
Residential rooftop installations in Bavaria and Baden-Württemberg drive procurement volumes as homeowners optimize self-consumption economics. Bundesnetzagentur grid codes mandate module-level rapid shutdown capabilities that favor microinverter architectures over string alternatives. The Munich-Stuttgart industrial corridor concentrates power electronics engineering expertise for thermal management and magnetics design.
Italy
High irradiance levels across Lombardy and Veneto improve payback periods for premium module-level electronics in agricultural and commercial rooftops. CEI 0-21 interconnection standards shape certification requirements for distributed generation equipment. Installer networks in Milan and Bologna prioritize granular monitoring capabilities for portfolio management.
Spain
RD 244 grid regulations and abundant solar resources in Andalusia and Extremadura accelerate commercial rooftop deployments above 30kW capacity. Three-phase microinverter specifications dominate procurement for small-business and agricultural installations. Valencia's port logistics infrastructure supports component import flows for Iberian distribution networks.
Netherlands
Installer purchasing cooperatives in Flanders and Randstad consolidate procurement volumes for retail and logistics building portfolios. Phase-balancing requirements in dense urban grids favor three-phase microinverter configurations. Eindhoven's high-tech manufacturing ecosystem supplies magnetic components and thermal management subsystems.
Poland
Sub-5% residential solar attachment rates in Masovian and Silesian Voivodeships present expansion opportunities as grid-parity economics improve. EU Green Deal funding mechanisms and nascent national subsidy frameworks accelerate deployment timelines. Warsaw's emerging installer networks adopt module-level electronics for shading mitigation in urban rooftop constraints.
Europe Solar Microinverter Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the European microinverter value chain. The vendor base clusters around three strategic archetypes: integrated power electronics conglomerates with captive semiconductor sourcing, specialized solar inverter pure-plays with software-centric service models, and diversified industrial conglomerates leveraging manufacturing scale. Dominant competitive moves include backward integration into wide-bandgap semiconductor supply and geographic expansion through installer channel partnerships.
Among US-based pure-plays, Enphase Energy exemplifies the software-anchored archetype with recurring revenue platforms. Delta Electronics and SMA Solar Technology represent divergent strategic positions—Taiwanese manufacturing scale versus German engineering intensity. These three anchors illustrate how competitive positioning splits between service-layer monetization and hardware cost leadership.
| Leading Market Players |
|---|
| Sungrow Power Supply |
| Delta Electronics |
| Enphase Energy |
| Hitachi |
| Canadian Solar |
| SolarEdge Technologies |
| Huawei Technologies |
| Sensata Technologies |
| SMA Solar Technology |
| Others |
Cost & Logistics Intelligence
Silicon carbide wafer price indices cascade through European microinverter manufacturing into three distinct pricing tiers, with wide-bandgap semiconductor feedstock volatility compressing margins at the premium efficiency threshold while air-cooled thermal redesigns under the F-Gas Regulation add bill-of-material complexity across all tiers.
Pricing Analysis
Margin tightening in the premium single-phase tier reflects silicon carbide substrate cost volatility and GaN switching topology adoption premiums. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked cybersecurity-certified units from basic rapid-shutdown-compliant hardware and uncertified import alternatives. Cost-down pressure on economy-tier Asian imports accelerates because installer purchasing cooperatives in Flanders and the Randstad extract volume concessions. Residential rooftop buyers in Germany and Italy exhibit lowest price sensitivity, prioritizing module-level monitoring and rapid shutdown compliance, while Polish and Romanian installers remain most price-sensitive, delaying premium microinverter adoption until grid-parity economics mature.
Supply Chain Analysis
Reverse-logistics networks for failed microinverter units remain underdeveloped across Europe, with most end-of-life electronics flowing to general e-waste streams rather than component recovery or remanufacturing channels. Magnetic component and capacitor supply chains concentrate in Taiwan and mainland China, exposing European assemblers to trans-shipment risk and tariff exposure. Wide-bandgap semiconductor substrates draw from Japanese and American wafer suppliers, while aluminum heat-sink extrusions and dielectric cooling fluids source from German and Dutch chemical processors. Single-source vulnerability sits with Taiwanese power semiconductor foundries serving multiple competing inverter brands. Distribution runs through national distributor networks and direct manufacturer engagement with installer purchasing cooperatives, bypassing traditional electrical wholesale channels in Benelux markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide-bandgap semiconductor foundry capacity constraints prop microinverter pricing power, with silicon carbide wafer supply bottlenecks extending lead times for 96%-plus efficiency designs and sustaining premium tier positioning.
For Market Incumbents: Cement grid-forming inverter capabilities and cybersecurity firmware certification as defensive moats against string inverter substitution in commercial segments above 50kW. Backward integration into GaN semiconductor sourcing or captive magnetics production in the Munich-Stuttgart corridor reduces exposure to East Asian supply chain volatility. Prioritize direct engagement with installer purchasing cooperatives in Flanders and the Randstad to defend channel position against distributor margin compression. For New Entrants and Emerging Players: The 40-60% price-point gap between premium German-engineered units and economy-tier Asian imports creates entry space for mid-market hybrid microinverters with battery-ready DC coupling. Eastern European rooftop underpenetration in Poland, Romania, and Bulgaria offers the most penetrable geography, with sub-5% residential solar attachment rates and improving subsidy frameworks. Pursue white-label partnerships with established EPC contractors in Warsaw and Bucharest to bypass incumbent distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-anchored microinverter pure-plays with recurring monitoring revenue streams in Southern European markets. Long-term viability across the next decade hinges on storage attachment rate trajectories and CE marking cybersecurity mandate compliance timelines. Monitor F-Gas Regulation phase-down enforcement intensity and Bundesnetzagentur grid code harmonization progress as inflection indicators for hardware redesign cycles and certification cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Backward Integration | Captive sourcing from Japanese wafer suppliers insulates margin from feedstock volatility. |
| Cybersecurity Firmware Certification | CE marking under incoming EU network codes creates compliance moats against uncertified imports. |
| Installer Cooperative Direct Engagement | Bypassing distributor layers in Benelux captures volume concessions from consolidated procurement. |
| Hybrid Battery-Ready Architecture Launch | DC-coupled storage integration captures attachment revenue as German residential penetration climbs. |
| Eastern European Channel Partnership | Warsaw and Bucharest EPC relationships accelerate penetration in sub-5% attachment markets. |
Research Approach
Multi-period observation of module-level power electronics procurement volumes, installer network expansion, and grid code certification timelines anchored the trend analysis, supplemented by interviews with EPC project developers, utility interconnection officers, inverter product managers, and magnetic component procurement leads. Secondary validation drew from Bundesnetzagentur certification databases, CE marking registries under the Low Voltage Directive, EU Green Deal implementation progress reports, and customs trade data for power semiconductor imports. Bottom-up aggregation of national deployment statistics and top-down cross-check against EU solar capacity targets ensured triangulation integrity.
Segment-weighting across product type, installation configuration, end-user scale, and technology subsystem shaped the analytical framework across the projection horizon. Single-phase, three-phase, multi-channel, and hybrid architectures were modeled separately against residential, commercial, and industrial demand curves. DC-AC conversion efficiency tiers, MPPT functionality penetration, and smart monitoring attachment rates provided industry-specific forecast inputs. CAGRs were derived from segment-level growth rate blending with macroeconomic sensitivity testing.
Inputs from Bundesnetzagentur and CEI 0-21 certification databases were available through the study window; gaps in real-time installer purchasing cooperative transaction data introduce uncertainty bands around channel volume estimates. Forecasts reflect documented assumptions regarding F-Gas Regulation enforcement timelines and REPowerEU funding disbursement rates. Practitioners should monitor silicon carbide wafer spot price movements and cybersecurity mandate implementation notices for early signals of cost structure and compliance burden shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Turkey Solar Energy Market
Solar Power Systems
Bifacial Solar Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Portugal Solar Energy Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Photovoltaic Mounting System Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Europe Solar Photovoltaic (PV) Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Bifacial Solar Panels Market