
 Malaysia Power EPC Market | 2026-2036
Malaysia Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Power EPC Market Foresight
Malaysia's National Energy Transition Roadmap is pivoting the power EPC sector toward renewable-heavy project portfolios and raising capital requirements for fossil-fuel participation. Scatec ASA leverages its solar development track record across Southeast Asian utility-scale auctions. Sunway Construction Group Bhd anchors domestic civil and electrical infrastructure capabilities for hybrid plant integration. Kpower Berhad specializes in biomass and small-hydro configurations that align with feed-in tariff structures.
Power EPC encompasses the integrated engineering, procurement, and construction of electricity generation facilities, spanning turbine installation, switchyard configuration, grid interconnection at 132 kV and above, and performance testing to achieve commercial operation date guarantees. The project type dimension shows solar power EPC commanding the fastest contract velocity as utility providers and industrial consumers procure behind-the-meter and grid-scale photovoltaic capacity under Malaysia's net energy metering scheme. Within service type, commissioning activities carry disproportionate margin pools due to specialized grid code compliance testing and reliability demonstration requirements that few local contractors can self-perform.
The Energy Commission of Malaysia and the Sustainable Energy Development Authority shape project authorization through licensing, tariff approval, and renewable energy certificate frameworks that determine developer returns. The Department of Standards Malaysia enforces MS IEC 61400 and MS 1839 technical standards for wind and solar plant safety and performance. Stakeholders must monitor how the Ministry of Economy's carbon pricing signals and green financing taxonomy redirect procurement priorities across Peninsular Malaysia and East Malaysian state grids.
Market Dynamics
Malaysia's National Energy Transition Roadmap is forcing power EPC contractors to restructure project portfolios toward solar and biomass while phasing out coal-linked engineering competencies.
Growth Catalysts
- Net Energy Metering Scheme:Industrial facilities in Peninsular Malaysia are procuring behind-the-meter solar capacity, accelerating contract velocity for distributed generation EPC packages.
- Data Center Load Expansion:Hyperscale operators are commissioning captive gas and solar hybrid plants to meet reliability requirements under Malaysia's green financing taxonomy.
- Feed-in Tariff Structures:Biomass and small-hydro configurations in East Malaysian states unlock predictable revenue streams for EPC firms with specialized civil capabilities.
Market Restraints
- Grid Interconnection Queues:Tenaga Nasional Berhad's 132 kV and above switchyard capacity constraints delay commercial operation date guarantees for utility-scale solar farms.
- Imported Module Dependency:Solar photovoltaic supply chains concentrate in Southeast Asian manufacturing hubs outside Malaysia, exposing EPC margins to shipping cost volatility.
- Fossil-Fuel Capital Exclusion:Green financing taxonomy criteria restrict lending for combined-cycle gas turbine projects, compressing addressable market for thermal EPC specialists.
Strategic Opportunities
- East Malaysian State Grids:Sarawak and Sabah present underpenetrated terrain for run-of-river hydro and biomass EPC contracts outside Peninsular Malaysia's competitive auction environment.
- Battery Energy Storage Integration:Solar-plus-storage configurations are emerging as a distinct procurement category under the Sustainable Energy Development Authority's capacity incentive frameworks.
- Commissioning Service Unbundling:Grid code compliance testing and reliability demonstration requirements create specialized margin pools that few local contractors self-perform.
Industry Challenges
- Grid Code Certification Timeline:MS IEC 61400 and MS 1839 compliance testing for renewable plant interconnection extends project handover schedules beyond original EPC contract durations.
- Multidisciplinary Talent Scarcity:Hybrid plant integration demands simultaneous civil, electrical, and power electronics expertise that Malaysia's engineering labor pool supplies unevenly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Power EPC Market |
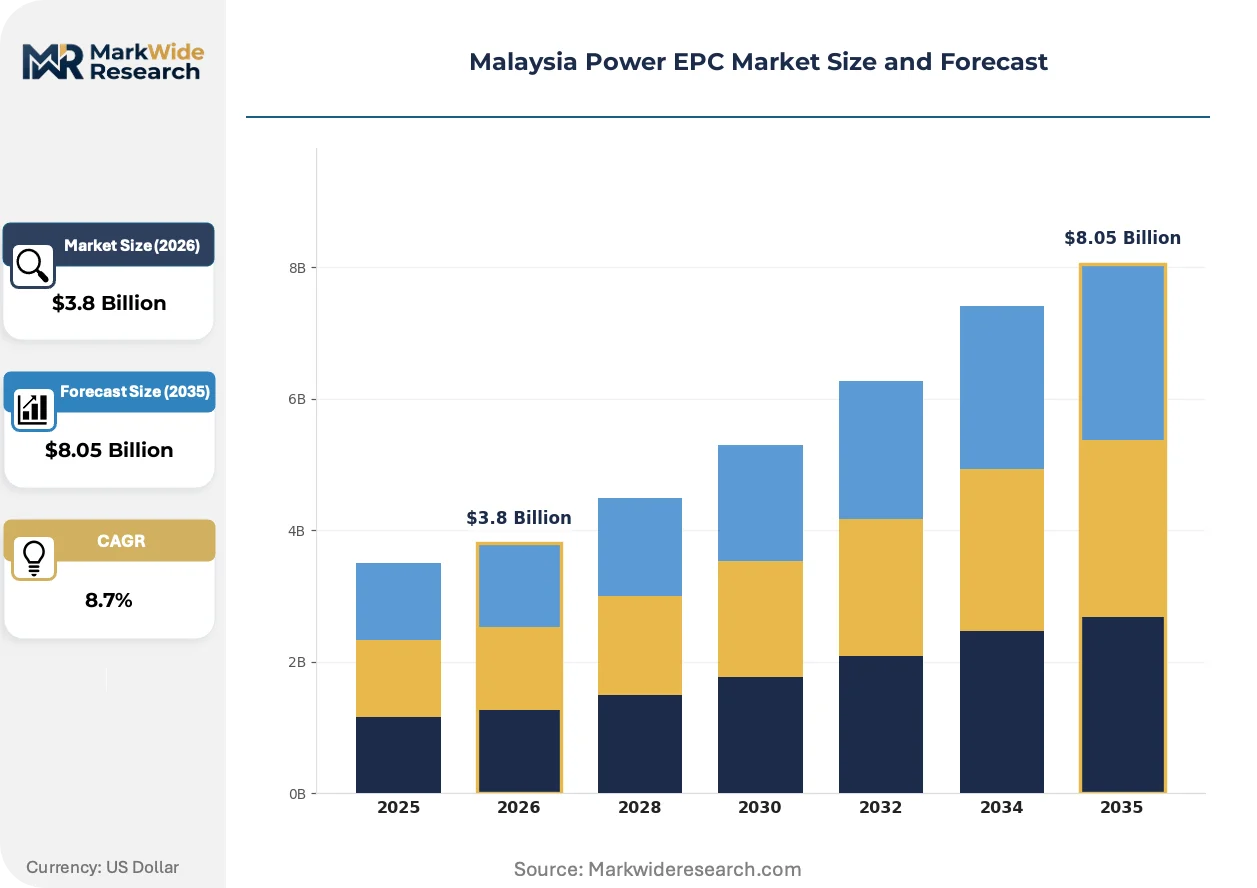
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Thermal Power, Hydroelectric Power, Solar Power, Wind Power Service Type: Design, Procurement, Construction, Commissioning Technology: Conventional, Renewable, Hybrid, Smart Grid End User: Utility Providers, Industrial Consumers, Government, Commercial Sector |
| Companies Covered | Scatec ASA, General Electric, Solarvest Holdings, Sumitomo Corporation, Toshiba Group, Sunway Construction Group Bhd, Kpower Berhad, AFRY AB, Cypark Resources Berhad, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Power EPC Market Shifts & Advancements
Digital twin modeling and modular construction methods are compressing project delivery timelines while raising technical barriers to entry for traditional EPC contractors.
String inverter architectures with integrated power electronics are consolidating market share in Malaysia's utility-scale solar segment. IPP developers favor these configurations for their reduced balance-of-system costs and simplified maintenance protocols. This technology shift is consolidating procurement decisions around a narrower set of EPC partners with electrical systems integration depth.
Malaysia's Sustainable Energy Development Authority has tightened renewable energy certificate verification standards, forcing EPC contractors to embed granular production monitoring into plant designs. Industrial offtakers now require sub-hourly generation data for scope two emissions accounting. Solar EPC contracts in Peninsular Malaysia's industrial corridors are absorbing these compliance costs into commissioning phase deliverables.
Hyperscale data center operators are bypassing traditional utility procurement channels to negotiate directly with EPC firms for captive power plants. This disintermediation concentrates contract value with integrated engineering houses capable of delivering gas-solar hybrid configurations. The pattern is most visible in Selangor and Johor, where cloud infrastructure investment clusters around dedicated substation capacity.
Malaysia Power EPC Market Segmentation
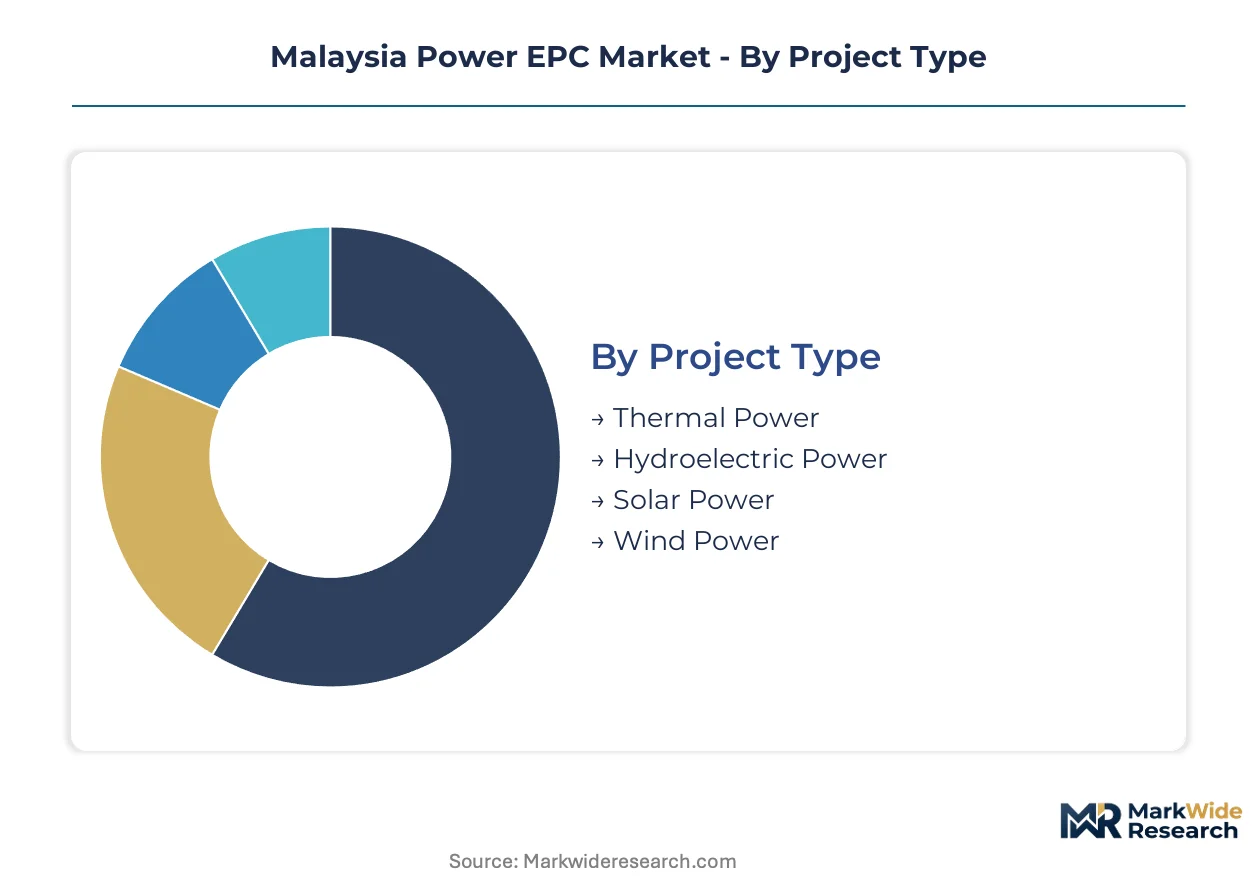
Malaysia's power EPC market fragments across four distinct dimensions that determine contractor capability requirements and regulatory exposure. Project type dictates the engineering discipline mix, while service type controls margin distribution through specialized commissioning protocols. Technology and end-user segments further stratify procurement patterns across Peninsular Malaysia's industrial corridors and East Malaysian state grids.
Project Type:
Each project type carries distinct certification burdens under Malaysia's Department of Standards Malaysia and Sustainable Energy Development Authority frameworks. Thermal and hydroelectric installations face lengthier environmental impact assessments, while solar and wind configurations trigger renewable energy certificate verification protocols.
- Solar Power:Photovoltaic installations dominate contract velocity across utility-scale auctions and net energy metering schemes. Peninsular Malaysia's industrial facilities in Selangor and Johor are procuring behind-the-meter capacity to meet scope two emissions targets under the green financing taxonomy. Grid interconnection at 132 kV and above requires Tenaga Nasional Berhad switchyard coordination that extends commercial operation timelines.
- Thermal Power:Combined-cycle gas turbine and captive power plants serve hyperscale data center reliability requirements. The Ministry of Economy's carbon pricing signals and green financing restrictions are compressing addressable market scope for coal-linked engineering competencies. Contractors must navigate fossil-fuel capital exclusion criteria while maintaining gas turbine installation expertise.
- Hydroelectric Power:Run-of-river configurations in Sarawak and Sabah unlock feed-in tariff structures outside Peninsular Malaysia's competitive auction environment. Civil works intensity demands specialized tunneling and dam construction capabilities that concentrate among regional infrastructure specialists.
- Wind Power:MS IEC 61400 compliance testing for turbine safety and performance creates technical barriers for local contractors. Limited wind resource availability restricts project economics to specific coastal and highland zones in East Malaysian states.
Solar Power sits at the top of the volume ranking, with Wind Power climbing the fastest as coastal resource assessments advance.
Service Type:
Service type segmentation tracks cost tier differentiation from front-end engineering through operational handover. Design and procurement phases absorb capital-intensive labor and equipment sourcing exposure, while construction and commissioning phases concentrate execution risk and margin realization.
- Commissioning:Grid code compliance testing and reliability demonstration requirements create specialized margin pools that few Malaysian contractors self-perform. MS IEC 61400 and MS 1839 technical standards enforcement extends project handover schedules beyond original contract durations. Sub-hourly generation data integration for renewable energy certificate verification now absorbs additional compliance costs into deliverables.
- Construction:Civil and electrical infrastructure execution anchors domestic contractor capabilities for hybrid plant integration. Modular construction methods are compressing delivery timelines while raising technical barriers for traditional EPC firms. Balance-of-system costs drive procurement decisions around electrical systems integration depth.
- Procurement:Solar photovoltaic module sourcing concentrates in Southeast Asian manufacturing hubs outside Malaysia, exposing margins to shipping cost volatility. String inverter architectures with integrated power electronics are consolidating market share through reduced maintenance protocols.
- Design:Digital twin modeling capabilities differentiate integrated engineering houses from conventional design-build contractors. Hybrid gas-solar configurations for captive power plants demand simultaneous civil, electrical, and power electronics expertise.
Construction commands the largest revenue share by phase, with Commissioning expanding most quickly as grid code certification complexity intensifies.
Technology:
Technology segmentation reflects application maturity across Malaysia's National Energy Transition Roadmap implementation stages. Conventional thermal baseload is yielding procurement priority to renewable and hybrid configurations, while smart grid integration emerges as a distinct capability requirement.
- Renewable:Utility-scale solar and biomass configurations align with Sustainable Energy Development Authority capacity incentive frameworks. Feed-in tariff structures in East Malaysian states provide predictable revenue streams for specialized civil contractors.
- Hybrid:Gas-solar and solar-plus-storage configurations are emerging as distinct procurement categories for industrial offtakers and data center operators. Battery energy storage integration demands power electronics expertise that Malaysia's engineering labor pool supplies unevenly.
- Conventional:Combined-cycle gas turbine projects face green financing taxonomy restrictions that compress thermal EPC specialist addressable markets. Reliability requirements for hyperscale operators sustain limited procurement activity in Selangor and Johor corridors.
- Smart Grid:Grid modernization investments concentrate around 132 kV and above switchyard upgrades and digital substation deployments. Tenaga Nasional Berhad interconnection queue management creates capacity constraints for utility-scale renewable integration.
Renewable technology holds the dominant procurement share, with Hybrid configurations gaining share fastest as storage economics improve.
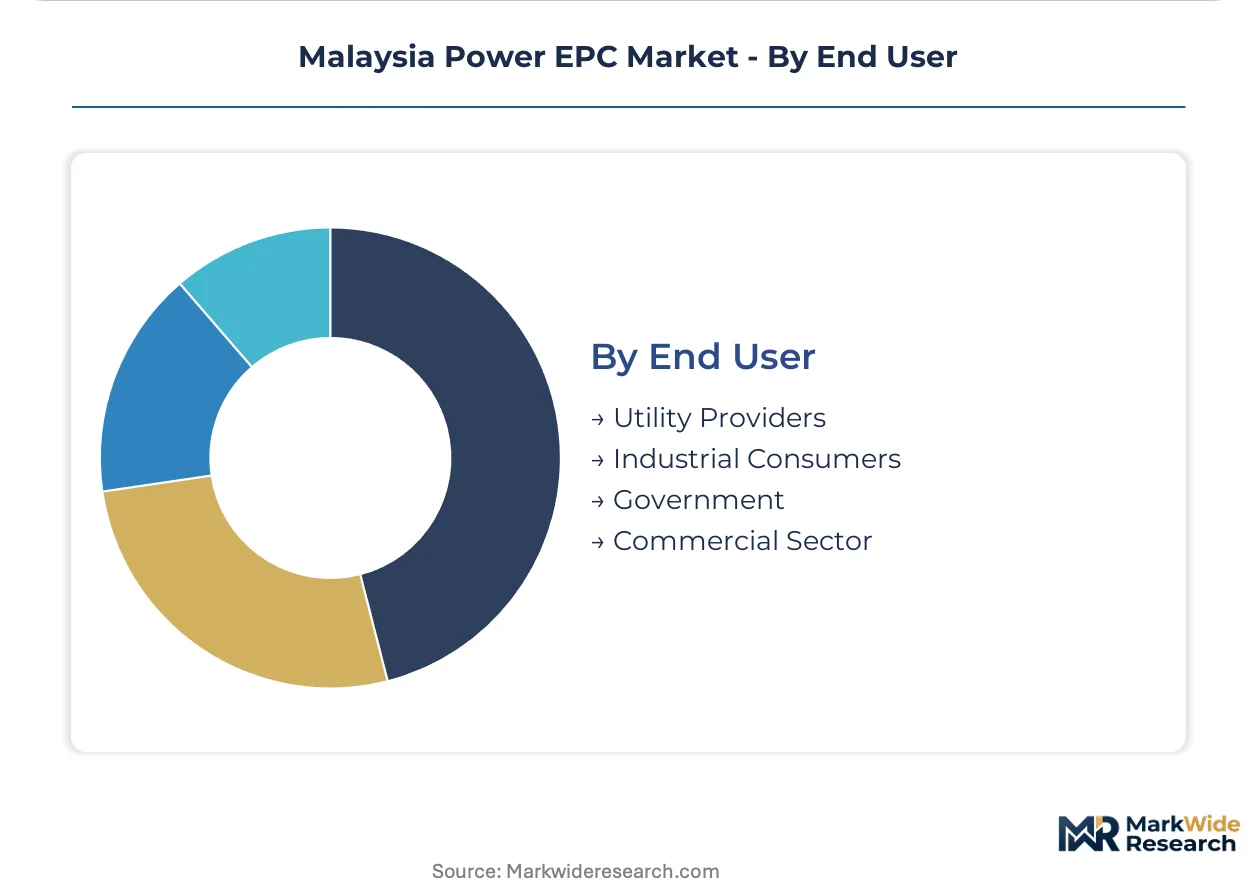
End User:
End user segmentation maps customer type to project scale, financing structure, and technical specification intensity. Utility providers anchor grid-scale procurement through regulated auctions, while industrial consumers drive behind-the-meter distributed generation expansion.
- Industrial Consumers:Manufacturing facilities and hyperscale data center operators are bypassing traditional utility channels to negotiate directly with EPC firms for captive power plants. Net energy metering scheme participation accelerates contract velocity for distributed solar packages across Peninsular Malaysia's industrial corridors.
- Utility Providers:Tenaga Nasional Berhad and state grid operators procure utility-scale capacity through competitive auctions with renewable energy certificate requirements. Grid interconnection queue management creates switchyard capacity constraints that delay commercial operation date guarantees.
- Government:Public sector procurement concentrates on rural electrification and state-owned generation assets in East Malaysian states. Feed-in tariff administration through the Sustainable Energy Development Authority shapes developer return expectations for biomass and small-hydro configurations.
- Commercial Sector:Office buildings and retail facilities participate in net energy metering at smaller scale than industrial counterparts. Scope two emissions accounting requirements are absorbing granular production monitoring costs into solar EPC contract specifications.
Industrial Consumers lead absolute contract value, with Utility Providers showing the steepest expansion trajectory as auction volumes increase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's engineering talent concentrates in Peninsular Malaysia's industrial corridors, where electrical and civil specialists cluster around utility-scale solar development and data center captive power projects. This workforce distribution shapes contract velocity and capability availability across the federation's two distinct grid systems.
Selangor
Hyperscale data center operators in Cyberjaya and Shah Alam negotiate directly with EPC firms for gas-solar hybrid captive plants. The Ministry of Economy's green financing taxonomy redirects procurement toward renewable-heavy configurations. Grid interconnection queues at Tenaga Nasional Berhad's 132 kV switchyards delay commercial operation timelines for utility-scale solar farms.
Johor
Cloud infrastructure investment clusters around dedicated substation capacity in Iskandar Malaysia. Net energy metering scheme participation accelerates contract velocity for distributed solar packages across manufacturing facilities. The Sustainable Energy Development Authority's capacity incentive frameworks attract battery energy storage integration proposals.
Sarawak
Run-of-river hydro configurations unlock feed-in tariff structures outside Peninsular Malaysia's competitive auction environment. Specialized tunneling and dam construction capabilities concentrate among regional infrastructure specialists. The state grid operator procures biomass and small-hydro capacity through predictable revenue mechanisms.
Sabah
Biomass EPC contracts align with feed-in tariff administration for agricultural waste-to-energy projects. Civil works intensity demands capabilities that Malaysia's engineering labor pool supplies unevenly. Rural electrification programs concentrate public sector procurement on state-owned generation assets.
Malaysia Power EPC Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Malaysia's power EPC sector, creating a tiered structure where capability breadth determines contract access. The market fragments across integrated engineering houses, domestic construction groups, and international technology providers. Three archetypes dominate: renewable specialists with solar development track records, diversified contractors with civil-electrical integration depth, and international equipment suppliers with commissioning expertise. Competitive moves center on strategic partnerships for hybrid plant integration and portfolio diversification into battery energy storage.
Among Norway-based renewable developers, Scatec ASA exemplifies the utility-scale solar specialist archetype through its Southeast Asian auction participation. Sunway Construction Group Bhd represents the integrated domestic contractor model with hybrid plant civil-electrical capabilities. Kpower Berhad occupies a position within the biomass and small-hydro specialization tier serving East Malaysian feed-in tariff structures.
| Leading Market Players |
|---|
| Scatec ASA |
| General Electric |
| Solarvest Holdings |
| Sumitomo Corporation |
| Toshiba Group |
| Sunway Construction Group Bhd |
| Kpower Berhad |
| AFRY AB |
| Cypark Resources Berhad |
| Others |
Supply & Pricing Matrix
Industrial offtakers in Selangor and Johor demanding integrated commissioning services with sub-hourly generation data compliance are forcing EPC contractors to unbundle specialized grid code testing from standard construction packages. This specification shift concentrates pricing power with firms possessing MS IEC 61400 and MS 1839 certification capabilities while compressing margins for pure-play civil contractors.
Pricing Analysis
The bundled-vs-unbundled service split defines Malaysia's power EPC pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates integrated engineering houses with digital twin capabilities from conventional design-build firms and basic civil subcontractors. Price differentiation rests on certification depth and after-sales service bundling. Cost compression in the standard tier is intensifying because string inverter standardization reduces electrical systems differentiation. Utility providers show the highest price sensitivity due to competitive auction pressures, while hyperscale data center operators accept premium pricing for reliability guarantees.
Supply Chain Analysis
Dual-sourcing requirements for solar photovoltaic modules mandate that EPC contractors qualify suppliers across Vietnam, Thailand, and Malaysia's domestic assembly plants. Raw material dependencies center on polysilicon feedstock, aluminum framing, and power electronics components. Single-source vulnerability concentrates in Southeast Asian manufacturing hubs outside Malaysia, exposing project margins to shipping cost volatility. Distribution runs through Tenaga Nasional Berhad's grid interconnection queues for utility-scale projects and direct bilateral negotiations for captive industrial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's power EPC sector has entered a late-cycle quality phase where premium specifications around grid code compliance and hybrid integration command sustained margin premiums. The shift from commodity solar installation toward gas-solar captive plants and battery energy storage integration favors contractors with multidisciplinary depth over volume-driven pure-plays.
For Market Incumbents: Hedge against fossil-fuel capital exclusion by accelerating renewable-heavy portfolio restructuring and securing commissioning certification lock-in. Threat substitution from international technology providers with proprietary grid code testing equipment compresses addressable margin pools for domestic firms. Priority lever: backward integration into power electronics assembly to capture balance-of-system value. For New Entrants and Emerging Players: Capture white-space in Sarawak and Sabah run-of-river hydro and biomass configurations where feed-in tariff structures reduce competitive auction intensity. The most penetrable terrain sits with specialized civil capabilities for tunneling and dam construction that Peninsular Malaysia's engineering labor pool supplies unevenly. Go-to-market angle: partnership with regional infrastructure specialists for East Malaysian state grid access. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated engineering houses possessing simultaneous civil, electrical, and power electronics expertise for hybrid plant delivery. Long-term viability over the next decade hinges on exposure to data center captive power expansion and battery energy storage integration. Acquisition target archetype: commissioning specialists with MS IEC 61400 certification depth. Signal to watch: Sustainable Energy Development Authority capacity incentive framework revisions that accelerate solar-plus-storage procurement categories.| Strategic Initiative | Industry Significance |
|---|---|
| Commissioning Certification Investment | MS IEC 61400 and MS 1839 compliance capabilities unlock specialized margin pools that few local contractors self-perform. |
| Hybrid Plant Integration Capability | Gas-solar and solar-plus-storage configurations address hyperscale data center reliability requirements under Malaysia's green financing taxonomy. |
| East Malaysian Geographic Expansion | Sarawak and Sabah feed-in tariff structures provide predictable revenue mechanisms outside Peninsular Malaysia's competitive auction environment. |
| Battery Energy Storage Partnership | Power purchase agreements with industrial offtakers leverage Sustainable Energy Development Authority capacity incentive frameworks. |
| Digital Twin Modeling Adoption | Advanced simulation capabilities differentiate integrated engineering houses from conventional design-build contractors in project delivery timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with IPP project developers, EPC contractors, utility planning officers, and grid operators with secondary validation. Secondary sources included Energy Commission of Malaysia licensing databases, Sustainable Energy Development Authority auction records, Tenaga Nasional Berhad interconnection queue filings, and Department of Standards Malaysia technical specifications. Bottom-up project pipeline aggregation and top-down sectoral expenditure analysis provided cross-verification.
Historical reference periods anchored the projection horizon to documented commercial operation date achievements and contract award velocities across the analysis window. Segmentation dimensions modeled encompassed project type, service type, technology category, and end-user archetype alongside regulatory framework differentiation between Peninsular Malaysia and East Malaysian state grids. CAGRs were derived from contract value trajectories and capacity installation forecasts, incorporating feed-in tariff administration changes and green financing taxonomy evolution as industry-specific inputs.
Underlying measurement precision varies by segment; utility-scale solar and thermal power carry tighter precision than emerging wind and battery storage categories due to project development database depth. Forecasts reflect assumptions around grid interconnection queue resolution timelines and module import cost stability. Deviation in Ministry of Economy carbon pricing signal intensity or Sustainable Energy Development Authority incentive framework revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Residential Portable Inverter Generator Market
Power
Distributed Buoyancy Modules Market
Power
North America CHP Market
Power
Sudan Power EPC Market
Power
Green UPS Market
Power
Marine Thermal Fluid Heaters Market
Power
Solar UPS Market
Power
Wind Turbine Drivetrain Market
Power
Brunei Power Market
Power
Kuwait Power Market
Power
LNG Power Barge Market
Power
Smart Power Market
Power
Temporary Load Bank Rental Market
Power
Direct Current Power System Market
Power
Europe Power Market
Power
Rotating Phase Converter Market