
 Asia-Pacific Air-Insulated Switchgear Market | 2026-2036
Asia-Pacific Air-Insulated Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Air-Insulated Switchgear Market Insights
Aftermarket service revenue is reconfiguring margin distribution across the Asia-Pacific Air-Insulated Switchgear Market. ABB Ltd. leverages its regional service network to capture recurring maintenance contracts. Larsen & Toubro Limited anchors its position through domestic manufacturing scale in India. Toshiba Corporation specializes in compact medium-voltage designs for space-constrained urban substations.
Air-insulated switchgear employs atmospheric air as the dielectric medium between live conductors and grounded enclosures, typically rated for voltages from 1 kV to 52 kV with metal-clad construction and withdrawable circuit breaker modules. The equipment serves primarily to protect, control, and isolate electrical circuits in power distribution networks. Medium voltage switchgear dominates current installation volumes across the region, while modular product configurations represent the fastest-expanding segment as utilities seek scalable substation upgrades. Indoor installation types command premium positioning in densely populated Japanese and South Korean urban corridors where land scarcity restricts outdoor substation footprints.
India's Central Electricity Authority mandates BIS certification for switchgear deployed in utility networks, tightening product standards and filtering non-compliant suppliers from public tenders. China's SAMR enforces GB standards for arc fault containment and insulation coordination, compelling manufacturers to redesign enclosure geometries. Japan's METI energy efficiency directives for distribution equipment shape procurement specifications among regional utilities. Stakeholders must monitor how divergent national certification timelines affect cross-border product platform strategies.
Market Dynamics
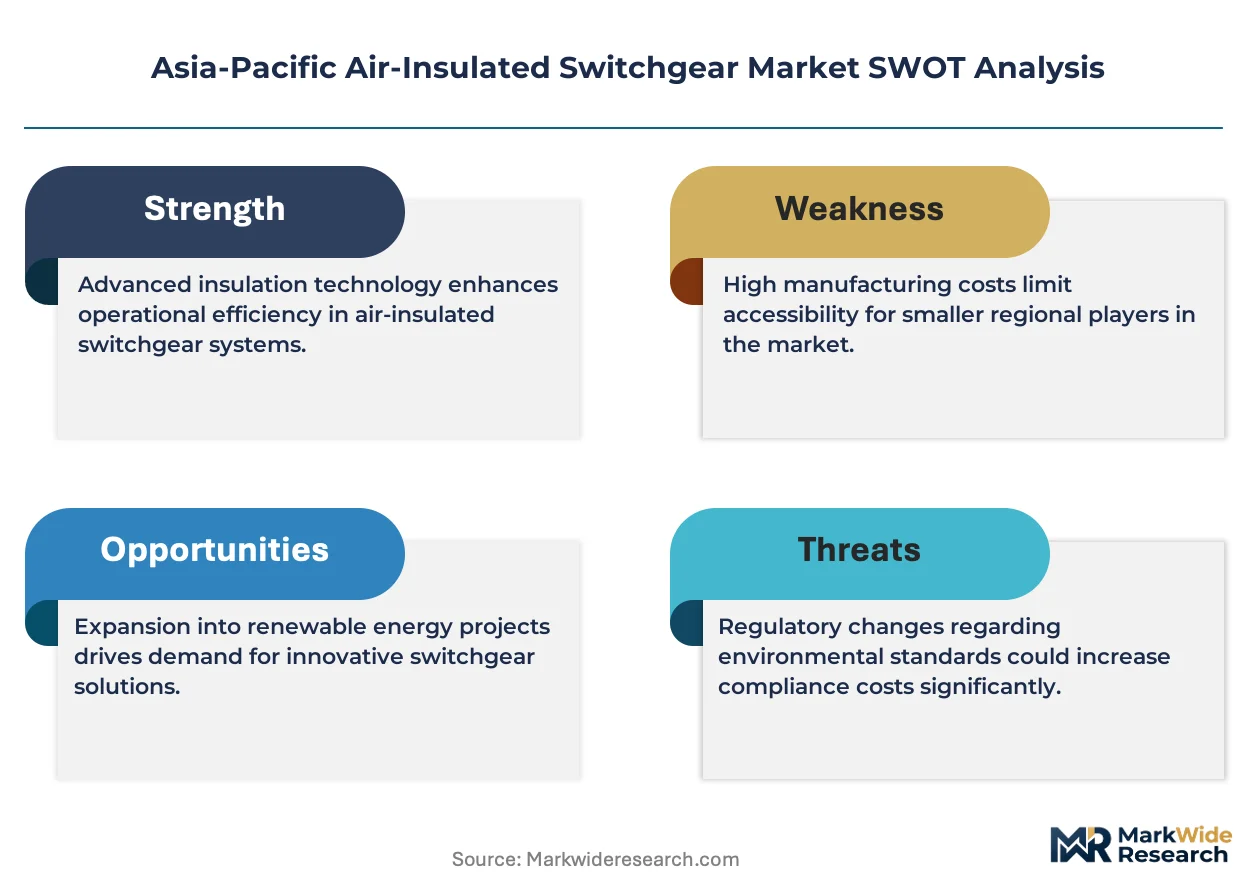
India's PLI scheme for power equipment and China's dual carbon goals are redirecting procurement toward higher-efficiency switchgear designs, compressing the competitive window for legacy manufacturers while elevating certified suppliers into premium tender categories.
Growth Catalysts
- Industrial Electrification:India's western states and China's coastal provinces accelerate factory power upgrades, pulling medium-voltage switchgear into heavy manufacturing clusters. Steel, cement, and chemical plants drive replacement cycles.
- CEA BIS Certification Mandate:India's Central Electricity Authority tightens product standards for utility networks, filtering non-compliant suppliers from public tenders and consolidating procurement toward certified domestic manufacturers.
- Urban Load Center Expansion:Southeast Asian utilities build grid infrastructure to serve concentrated metropolitan demand, prioritizing compact indoor installations where land scarcity restricts outdoor substation footprints.
Market Restraints
- Copper and Steel Input Volatility:Raw material price swings compress fabrication margins for enclosure and conductor assemblies, forcing manufacturers to absorb cost spikes or risk tender disqualification.
- Technical Limitation on Voltage Ratings:Air-insulated designs face dielectric constraints above 52 kV, ceding high-voltage substation opportunities to gas-insulated alternatives in transmission-heavy applications.
- Regulatory Fragmentation:Divergent national certification timelines across BIS, GB standards, and METI directives complicate cross-border product platform strategies for multinational suppliers.
Strategic Opportunities
- Modular Substation Upgrades:Utilities across Thailand, Vietnam, and Indonesia seek scalable switchgear configurations for phased infrastructure rollout, creating white space for flexible product architectures.
- Aftermarket Service Unbundling:Recurring maintenance contracts separate from equipment sales, allowing service-network owners to capture margin pools independent of manufacturing scale.
- Smart Grid Convergence:Integration of switchgear with digital monitoring and predictive diagnostics opens new specification categories among advanced utilities in Japan and South Korea.
Industry Challenges
- Arc Fault Containment Engineering:China's SAMR enforces redesigned enclosure geometries for GB-standard compliance, extending R&D cycles and testing expenditures for market entry.
- Legacy System Integration:Withdrawable circuit breaker modules must interface with decades-old substation control architectures, complicating commissioning and raising field engineering costs.
- Certification Timeline Compression:Accelerated tender schedules clash with multi-month BIS and GB approval processes, disadvantaging suppliers without pre-certified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Air-Insulated Switchgear Market |
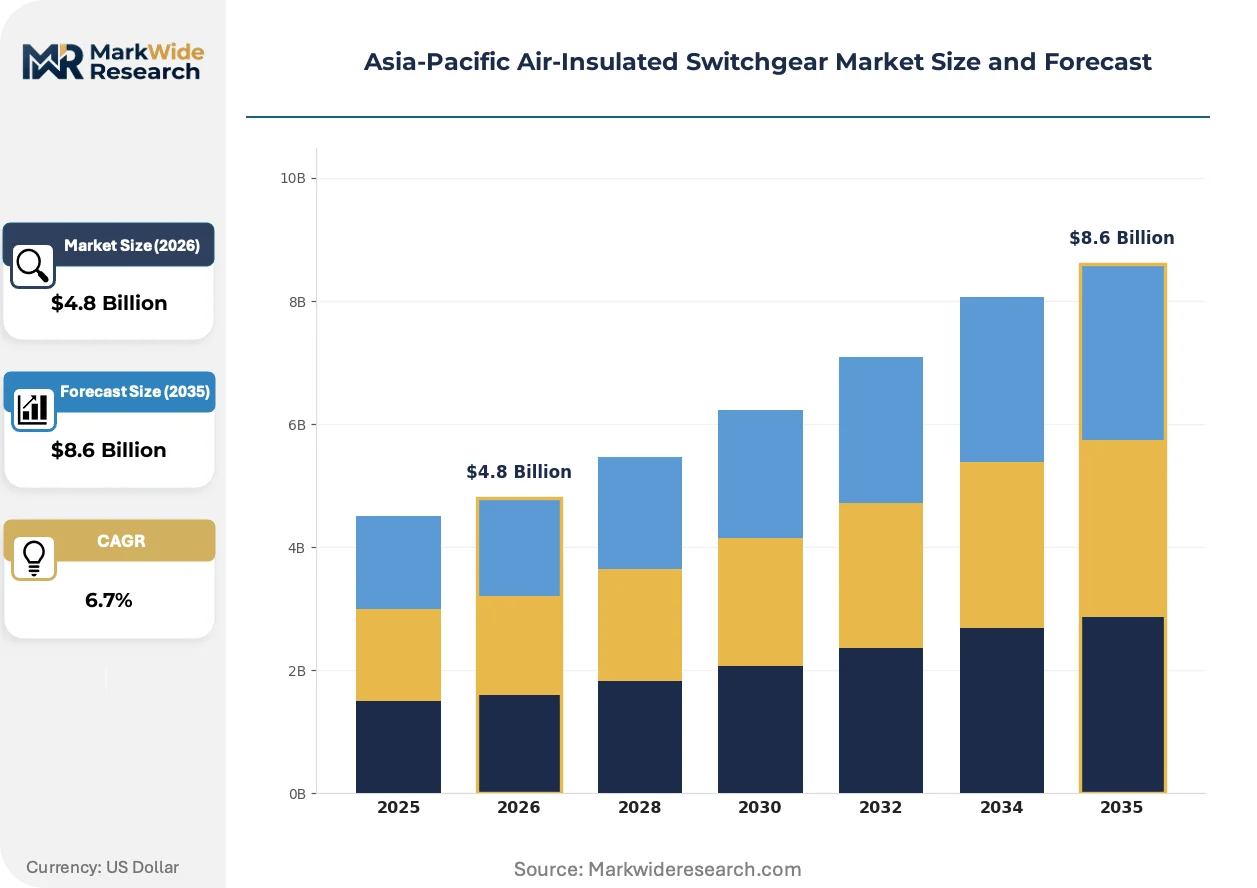
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage, High Voltage, Compact, Modular Installation Type: Indoor, Outdoor, Substation, Industrial End User: Utilities, Manufacturing, Energy, Commercial Control Technology: Manual, Automatic, Remote, Hybrid |
| Companies Covered | General Electric Company, Toshiba Corporation, ABB Ltd., Larsen & Toubro Limited, Eaton Corporation PLC, Schneider Electric SE, Mitsubishi Electric Corporation, Bharat Heavy Electricals Limited, Siemens AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Air-Insulated Switchgear Market Trends and Innovations
Digitalization and material efficiency are compressing traditional switchgear form factors while elevating predictive maintenance capabilities. These shifts reconfigure how utilities specify, procure, and operate distribution infrastructure across the region.
Gas-insulated switchgear is collapsing the addressable market for air-insulated alternatives above 36 kV. Transmission utilities in China and India specify GIS for urban substations where footprint constraints override cost sensitivity. This displacement concentrates AIS demand in distribution networks below 36 kV, reshaping manufacturer R&D allocation toward compact medium-voltage designs.
Japan's METI energy efficiency directives for distribution equipment shape procurement specifications among regional utilities. These mandates accelerate retirement of aging switchgear with elevated no-load losses. Manufacturers respond with optimized magnetic core materials and low-resistance contact systems targeting premium-tier municipal tenders.
Service contracts now unbundle from equipment sales across Southeast Asian utility procurement. State grids in Thailand and Vietnam specify multi-year maintenance agreements separately from capital purchases, shifting vendor relationships toward lifecycle performance guarantees. This reconfiguration favors suppliers with established regional service footprints over pure equipment exporters.
Asia-Pacific Air-Insulated Switchgear Market Segmentation
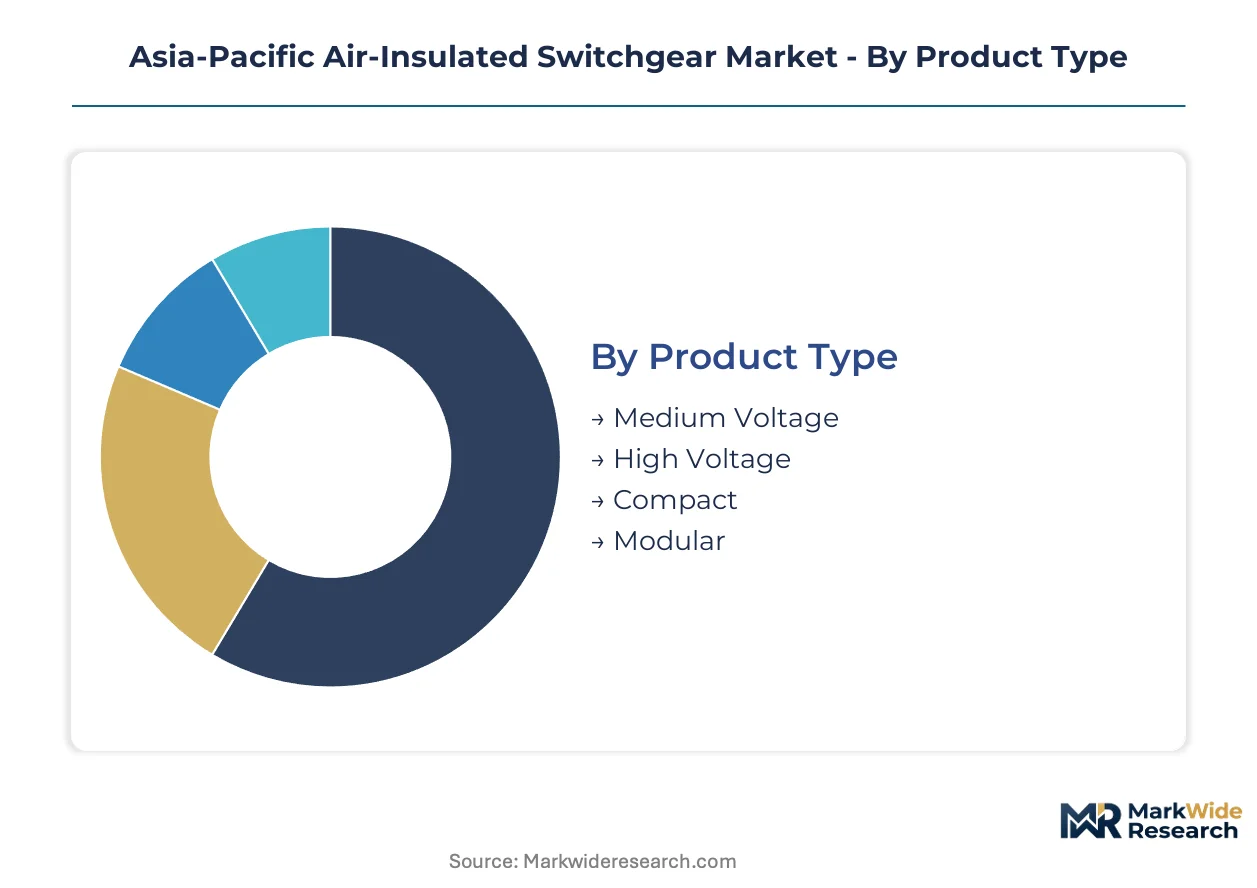
Segmentation in the Asia-Pacific Air-Insulated Switchgear Market reveals how procurement cycles and specification requirements diverge across voltage classes, installation environments, and control architectures. Understanding these divisions exposes where margin pools concentrate and which configurations face the steepest competitive pressure.
Product Type:
Medium voltage switchgear turns over on 15-20 year replacement cycles tied to distribution network planning, while modular designs refresh fastest as utilities pursue phased substation expansions.
- Medium Voltage:Rated between 1 kV and 52 kV with metal-clad construction and withdrawable circuit breaker modules. Demand concentrates in India's western states and China's coastal provinces where steel, cement, and chemical plants drive replacement cycles amid industrial electrification acceleration.
- Modular:Scalable configurations enabling phased infrastructure rollout across Southeast Asian utility networks. Thailand, Vietnam, and Indonesia specify these for substation upgrades where capital deployment must align with load growth trajectories, creating white space for flexible product architectures.
- High Voltage:Designs above 36 kV face displacement by gas-insulated alternatives in transmission-heavy applications.
- Compact:Space-constrained designs for urban substations in Japanese and South Korean metropolitan corridors.
Medium voltage anchors the volume base while modular gains share at the steepest rate.
Installation Type:
Cost tiers separate premium indoor installations from standard outdoor deployments, with substation configurations commanding the highest specification density per unit.
- Indoor:Premium-positioned configurations for densely populated Japanese and South Korean urban corridors where land scarcity restricts outdoor substation footprints and METI energy efficiency directives shape procurement specifications.
- Outdoor:Standard deployments in rural distribution networks across India and Southeast Asia where land availability reduces enclosure complexity.
- Substation:Integrated switchgear bays for utility-scale infrastructure in China and India.
- Industrial:Heavy-duty enclosures for manufacturing clusters requiring arc fault containment under China's SAMR GB standards.
Outdoor configurations dominate unit shipments while indoor installations capture the widest margin spreads.
End User:
Application intensity varies sharply—utilities run 24/7 critical infrastructure while commercial installations see lighter duty cycles and longer effective lifespans.
- Utilities:State grids and distribution companies across India, Thailand, and Vietnam specify BIS-certified equipment for public tenders. India's Central Electricity Authority mandates certification compliance, filtering non-compliant suppliers and consolidating procurement toward certified domestic manufacturers.
- Manufacturing:Steel, cement, and chemical plants in India's western states and China's coastal provinces accelerate factory power upgrades, pulling medium-voltage switchgear into heavy manufacturing clusters with demanding arc containment requirements.
- Energy:Power generation facilities requiring isolation and control capabilities.
- Commercial:Office and retail installations with lower switching frequency and reduced fault current exposure.
Utilities anchor the revenue base while manufacturing expands most quickly.
Control Technology:
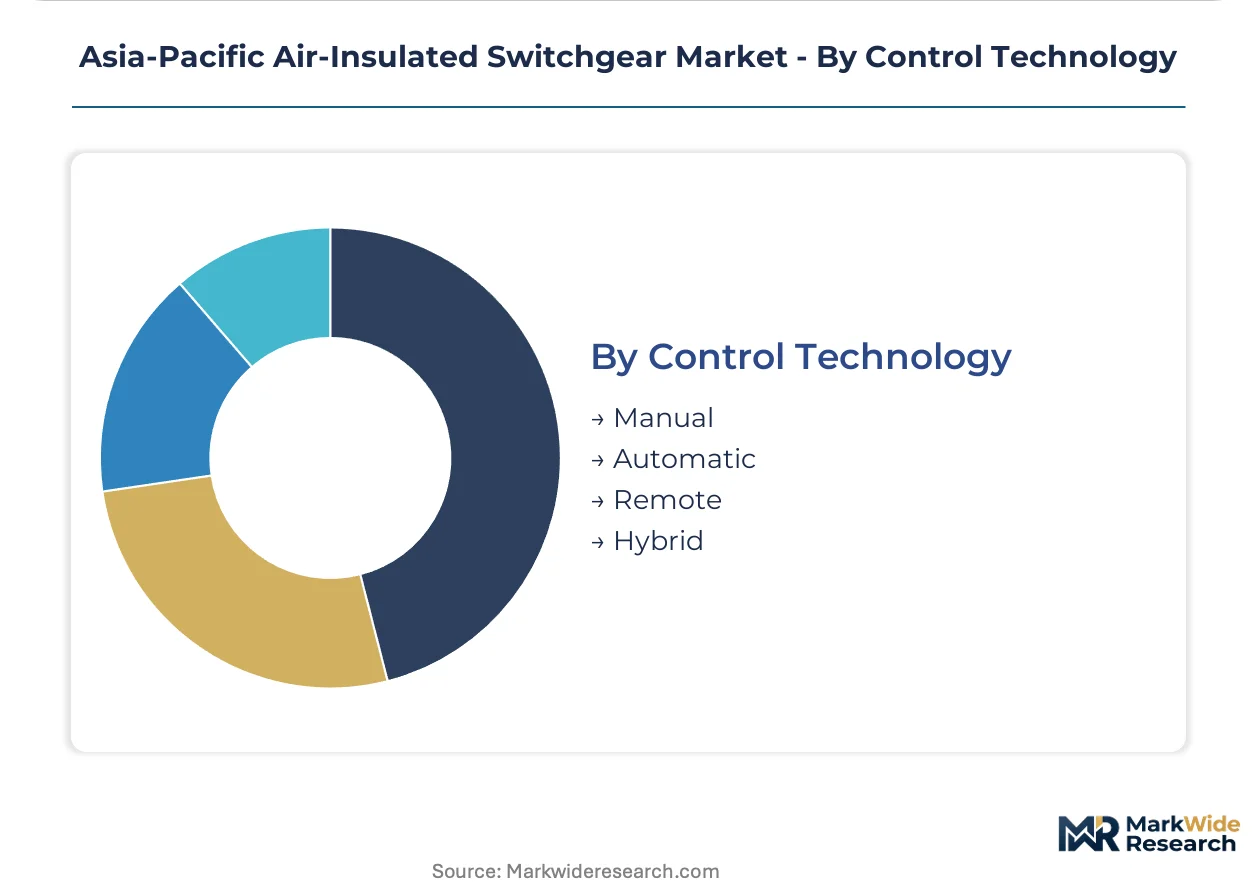
Customer sophistication stratifies this category—advanced utilities in Japan and South Korea specify digital-ready architectures while basic manual controls persist in cost-sensitive deployments.
- Automatic:Self-acting protection and reclosure systems for urban distribution networks. Integration with digital monitoring and predictive diagnostics opens new specification categories among advanced utilities in Japan and South Korea pursuing smart grid convergence.
- Remote:SCADA-compatible architectures enabling centralized grid operations. State grids in Thailand and Vietnam specify these for multi-year maintenance agreements tied to lifecycle performance guarantees.
- Manual:Operator-dependent switching for rural and backup applications.
- Hybrid:Configurations combining local automatic operation with remote override capabilities.
Manual controls retain the largest installed base while remote architectures climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switchgear manufacturing capacity concentrates in China and India, with fabrication clusters serving domestic utility procurement and export demand across Southeast Asia. Japanese and South Korean producers occupy specialized niches in compact urban designs.
China
Coastal provinces in Jiangsu and Guangdong drive industrial electrification across steel, cement, and chemical manufacturing clusters. SAMR enforces GB standards for arc fault containment, compelling enclosure redesigns for market entry. Shanghai and Shenzhen municipal utilities specify compact indoor switchgear where land scarcity restricts substation footprints.
India
Western states of Maharashtra and Gujarat accelerate factory power upgrades in heavy manufacturing corridors. CEA mandates BIS certification for utility network deployment, filtering non-compliant suppliers from public tenders. Mumbai and Ahmedabad industrial zones pull medium-voltage switchgear into replacement cycles amid capacity expansion.
Japan
METI energy efficiency directives for distribution equipment shape procurement specifications among regional utilities. Tokyo and Osaka metropolitan corridors prioritize compact indoor installations where land constraints override cost considerations. Kansai Electric and Tokyo Electric Power specify low-loss designs targeting premium-tier municipal tenders.
South Korea
Seoul Capital Area utilities demand space-constrained switchgear configurations for dense urban substations. KEPCO procurement guidelines emphasize digital-ready architectures for smart grid integration. Busan-Ulsan industrial complexes require heavy-duty enclosures for manufacturing cluster electrification.
Vietnam
State Grid of Vietnam expands transmission infrastructure to serve manufacturing relocation from China. EVN procurement specifies modular switchgear configurations for phased capital deployment. Ho Chi Minh City and Hanoi load centers drive indoor installation demand where urban land values restrict outdoor substation development.
Asia-Pacific Air-Insulated Switchgear Market Competitive Landscape
Diversified industrial conglomerates and specialized electrical equipment manufacturers split the market across distinct capability vectors. The vendor base organizes around three strategic archetypes: integrated infrastructure conglomerates with captive utility relationships, pure-play switchgear specialists leveraging manufacturing scale, and technology licensors monetizing design IP through regional partnerships. Competitive moves center on certification pre-positioning ahead of tender windows and service network expansion to capture recurring maintenance revenue.
Within the integrated infrastructure tier, Larsen & Toubro Limited and Bharat Heavy Electricals Limited anchor domestic manufacturing positions in India. ABB Ltd. exemplifies the technology-licensor archetype, leveraging regional service footprints to capture aftermarket contracts separate from equipment sales. These three entities represent distinct strategic postures: scale-driven fabrication, state-backed utility integration, and lifecycle service unbundling.
| Leading Market Players |
|---|
| General Electric Company |
| Toshiba Corporation |
| ABB Ltd. |
| Larsen & Toubro Limited |
| Eaton Corporation PLC |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Bharat Heavy Electricals Limited |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
Jiangsu and Guangdong fabrication clusters anchor regional supply capacity, concentrating enclosure and conductor assembly output within 200 kilometers of Shanghai and Shenzhen port infrastructure. This geographic density grants domestic Chinese manufacturers freight-cost advantages over Southeast Asian importers, compressing landed-price differentials for Thai and Vietnamese utility tenders while elevating margin pressure on non-integrated foreign suppliers.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture across the Asia-Pacific Air-Insulated Switchgear Market, with multi-year maintenance agreements unbundling from equipment sales in Thai and Vietnamese state grid procurement. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels stratifies tender participation, with BIS and GB certification tiers commanding 15-25% uplifts. Cost compression in standard-tier equipment is intensifying because copper and steel input volatility forces manufacturers to absorb margin erosion or risk disqualification. Rural distribution utilities in India and Indonesia exhibit highest price sensitivity, while Japanese metropolitan utilities prioritize low-loss designs with minimal cost elasticity.
Supply Chain Analysis
Contract manufacturing concentrates among domestic Chinese electrical equipment specialists and Indian heavy engineering conglomerates with captive fabrication facilities. Supply draws from China, India, and South Korea for enclosure stampings, conductor assemblies, and vacuum interrupter modules. Raw material dependencies center on copper cathode, electrical-grade steel, and silver-based contact alloys. Single-source vulnerability in vacuum interrupter supply from Japanese and European specialists creates bottleneck risk for arc containment compliance. Distribution runs through direct utility procurement channels in India and China, with EPC contractors and industrial distributors serving manufacturing cluster demand across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Air-Insulated Switchgear Market represents a high-growth infrastructure disruption as China's dual carbon goals and India's PLI scheme simultaneously redirect procurement toward higher-efficiency designs and certified domestic manufacturing.
For Market Incumbents: Build certification moats by pre-positioning BIS and GB platform approvals ahead of accelerated tender schedules, compressing competitive windows for legacy suppliers without pre-certified architectures. Defensive consolidation should prioritize backward integration into electrical-grade steel and copper processing to neutralize raw material volatility, while expanding regional service footprints to capture unbundled maintenance revenue from Thai and Vietnamese state grids. Gas-insulated switchgear displacement above 36 kV threatens high-voltage revenue pools, necessitating R&D reallocation toward compact medium-voltage modular designs. For New Entrants and Emerging Players: Vietnam's manufacturing relocation corridor offers underpenetrated white space as State Grid of Vietnam expands transmission infrastructure with modular procurement specifications. Target modular switchgear configurations for phased capital deployment in Indonesian utility networks, where load growth trajectories outpace domestic manufacturing capacity. Partner with established EPC contractors for channel access rather than competing for direct utility certification, leveraging project-based specification influence to bypass multi-month approval timelines. For Investors and Strategic Acquirers: Long-term, this sits as a service-network infrastructure play because recurring maintenance contracts separate from equipment sales, generating annuity-like revenue independent of capital expenditure cycles. Acquisition targets should prioritize regional service footprint owners with established Thai, Vietnamese, and Indonesian maintenance contracts over pure manufacturing scale. Monitor CEA BIS certification timeline compression and SAMR GB standard enforcement as inflection indicators for competitive consolidation toward certified domestic platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Positioning | CEA BIS and SAMR GB approvals ahead of tender windows lock out non-compliant competitors from premium procurement categories. |
| Backward Integration into Raw Materials | In-house copper and steel processing neutralizes input volatility that compresses fabrication margins for enclosure assemblies. |
| Regional Service Network Expansion | Established maintenance footprints in Thailand and Vietnam capture unbundled recurring revenue separate from capital equipment sales. |
| Modular Product Architecture Development | Scalable configurations align with EVN and PLN phased infrastructure rollout requirements across Southeast Asian load centers. |
| Smart Grid Digital Integration | SCADA-compatible and predictive diagnostic capabilities open specification categories among KEPCO and advanced Japanese utilities. |
Research Methodology
A spread of perspectives from utility planning officers, EPC contractor procurement leads, switchgear manufacturing executives, and aftermarket service managers converged on the working assumptions underlying this analysis. Primary field engagement combined structured interviews with secondary validation against CEA tender documentation, SAMR regulatory filings, METI efficiency directives, and customs trade data for electrical equipment imports. Bottom-up unit shipment estimates triangulated against top-down utility capital expenditure disclosures across the analysis window.
Demand-supply balance modeling anchored forecast outputs, with segmentation across voltage class, installation environment, end-use application, and control technology dimensions. CAGRs derived from replacement cycle analysis tied to distribution network planning horizons, industrial electrification trajectories, and regulatory compliance deadlines. Key inputs included BIS certification timeline data, GB standard revision schedules, and PLI scheme disbursement patterns for power equipment manufacturing.
Practitioners should monitor raw material price volatility, regulatory certification timeline compression, and GIS displacement rates above 36 kV for early signals requiring forecast revision. Quarterly review of CEA tender award patterns, SAMR enforcement actions, and Southeast Asian utility capital deployment schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Hazardous Location Motor Starters Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Carbon Brush Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
Solar Combiner Boxes Market