
 Pervious Concrete Market | 2026-2036
Pervious Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Pervious Concrete Market Analytics
Modular specification packages that bundle pervious concrete with subsurface drainage aggregates and geotextile fabrics is pivoting procurement decisions toward integrated system contracts rather than material-only purchases. Cemex S.A.B. de C.V. leverages its vertically integrated cement-to-concrete network to control raw material quality for high-porosity mixes. Heidelberg Materials anchors European municipal specifications through its technical consulting services for stormwater compliance. Sika AG differentiates via admixture formulations that enhance freeze-thaw durability in cold-climate installations.
Pervious concrete is a specialized hydraulic cementitious composite containing minimal fine aggregate, typically with 15-25% void content by volume, engineered to permit water infiltration rates exceeding hundreds of inches per hour while supporting vehicular loads. Its primary purpose is to mitigate urban runoff volume, reduce combined sewer overflow events, and replenish groundwater tables in built environments. Traditional pervious concrete occupies the largest installed base due to decades of performance data and lower material costs, though reinforced pervious concrete is gaining share in heavy-duty parking and roadway applications where structural capacity constraints limit conventional formulations. Pavements and parking lots together constitute the dominant application cluster, with municipalities and construction companies representing the most concentrated end-user demand pools.
The EPA's NPDES program and state-level MS4 permits shape product standards by mandating post-construction stormwater controls that favor permeable surfaces over impervious alternatives. ASTM C1701 for infiltration rate testing and ACI 522 for pervious concrete construction provide the technical benchmarks that determine specification eligibility and warranty terms. Stakeholders must monitor evolving state-level low-impact development mandates and green infrastructure incentive programs that will determine which regional markets expand specification requirements fastest.
Market Dynamics
Modular stormwater system contracts are displacing material-only procurement across municipal infrastructure, bundling pervious concrete with subsurface drainage aggregates and geotextile fabrics into single-source specifications that favor vertically integrated suppliers.
Growth Catalysts
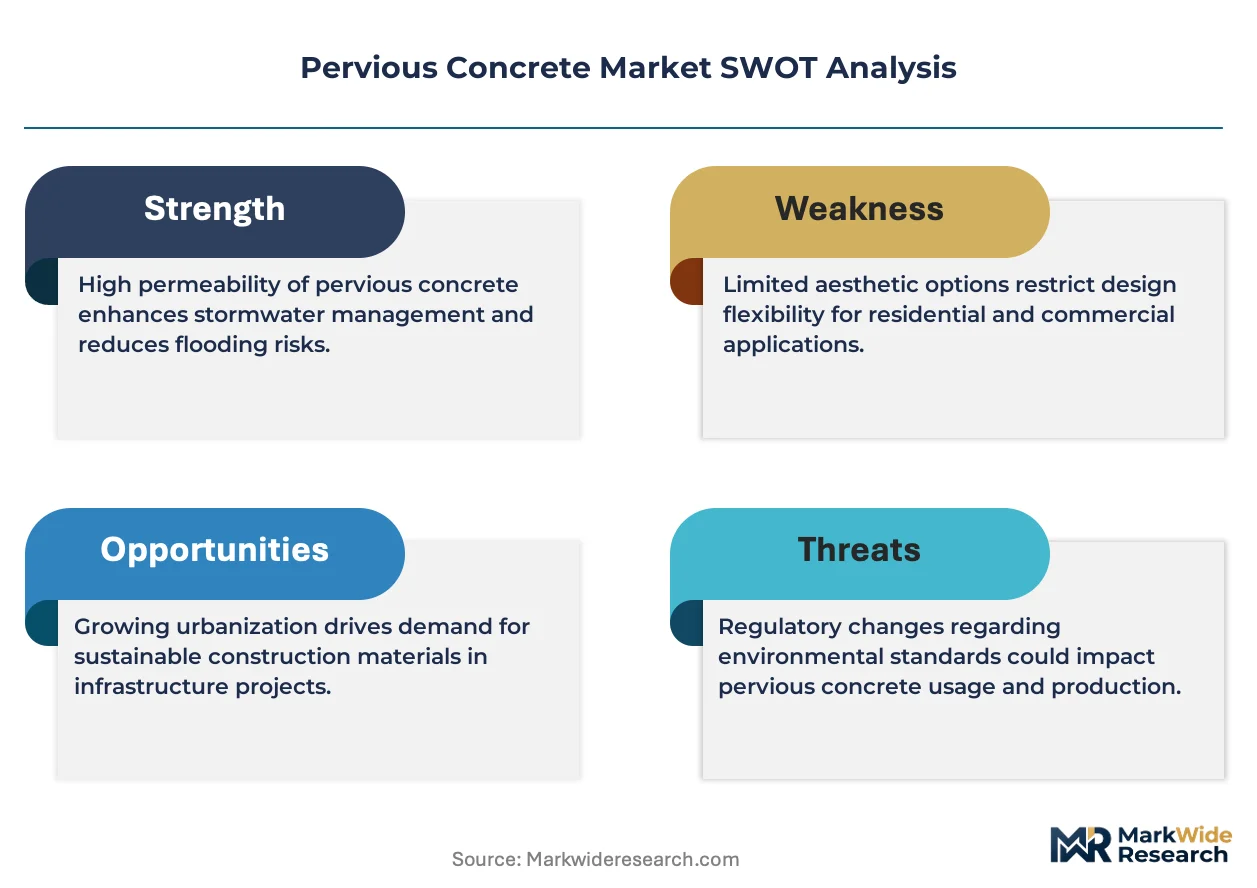
- EPA NPDES Enforcement:Municipal separate storm sewer system permits mandate post-construction runoff controls, accelerating permeable surface specifications in urban redevelopment zones.
- Sun Belt Urbanization:Rapid population growth across Arizona, Texas, and Florida strains conventional drainage capacity during episodic rainfall events.
- Groundwater Recharge Mandates:State-level aquifer protection statutes in California and Colorado require infiltration-focused surface designs for new commercial development.
Market Restraints
- Portland Cement Cost Volatility:Energy-intensive clinker production exposes mixers to natural gas and electricity price swings that compress margin on low-fines formulations.
- Specialized Contractor Scarcity:Installation quality depends on certified flatwork crews trained in rapid-placement techniques, with qualified labor concentrated in coastal metropolitan markets.
- Asphalt Pervious Pavement Substitution:Open-graded friction course alternatives compete for parking lot applications where load-bearing requirements remain modest.
Strategic Opportunities
- Midwest Freeze-Thaw Expansion:Admixture-enhanced cold-climate formulations open specification opportunities in Minnesota, Wisconsin, and Michigan where thermal durability previously limited adoption.
- Green Infrastructure Incentives:State revolving fund set-asides for low-impact development projects subsidize permeable pavement installation in combined sewer overflow priority areas.
- Reinforced Heavy-Duty Segments:Polymer-modified and fiber-reinforced variants penetrate commercial trucking terminals and logistics hubs requiring structural capacity beyond conventional void ratios.
Industry Challenges
- ASTM C1701 Testing Standardization:Infiltration rate measurement variability between field and laboratory conditions creates warranty disputes and specification ambiguity.
- Clogging Prevention Maintenance Protocols:Vacuum sweeping frequency and sediment load monitoring require owner education that extends project handoff timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pervious Concrete Market |
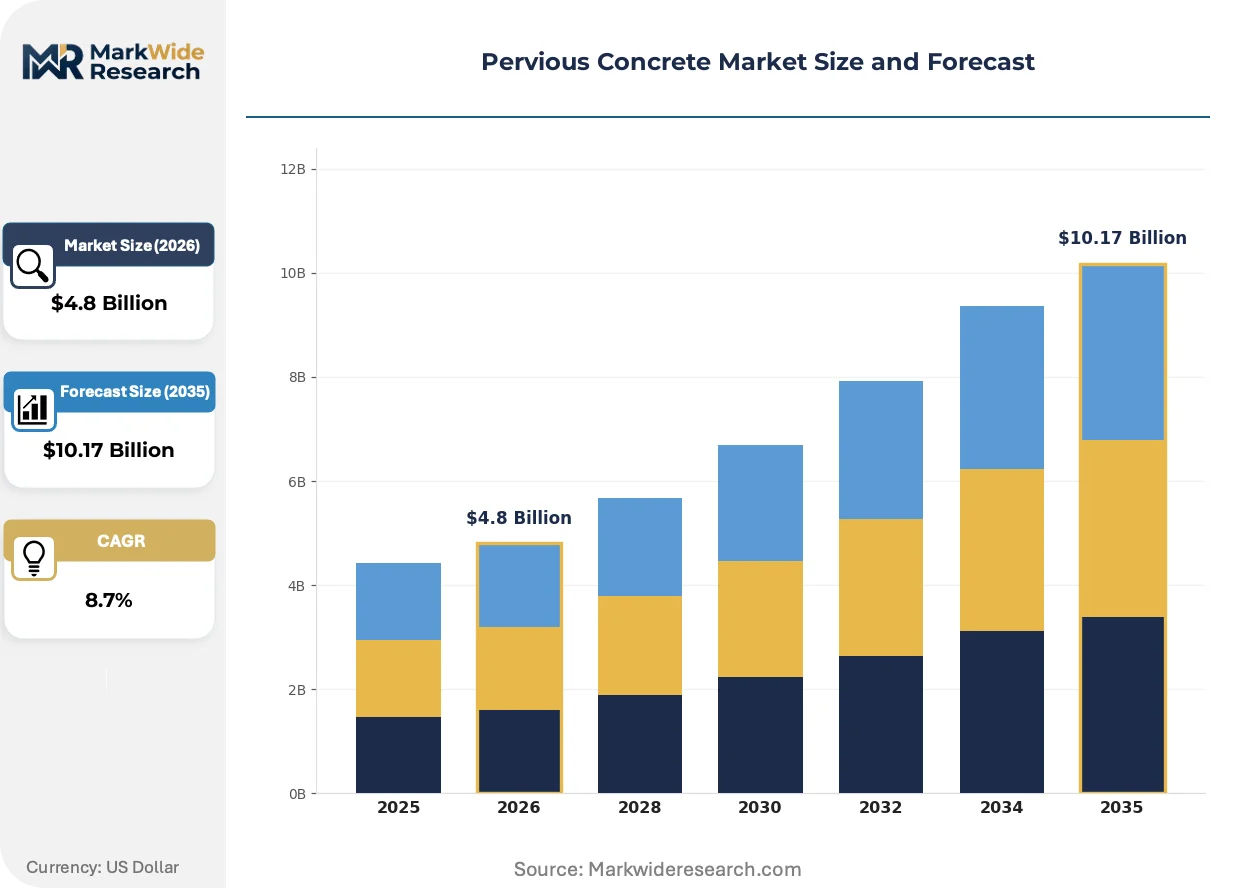
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Pervious Concrete, Reinforced Pervious Concrete, Porous Concrete, Flexible Pervious Concrete Application: Pavements, Parking Lots, Sidewalks, Roads End User: Construction Companies, Municipalities, Residential Developers, Landscaping Firms Distribution Channel: Direct Sales, Online Retail, Distributors, Contractors |
| Companies Covered | Cemex S.A.B. de C.V., CRH, Heidelberg Materials, Holcim, Sika AG, BASF SE, Boral Limited, UltraTech Cement Limited, Chaney Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pervious Concrete Market Evolving Landscape
Digital placement control and admixture chemistry are compressing installation variability while extending service life into harsher climate zones previously considered unsuitable for porous concrete applications.
Self-consolidating pervious concrete is automating placement consistency across large-format commercial slabs. Municipal stormwater contractors in Florida and Georgia are specifying the rheology-modified mixes for airport taxiway shoulders and distribution center aprons where manual strike-off quality proved inconsistent. The technology is automating crew-size reduction and surface tolerance achievement that previously demanded veteran flatwork specialists.
The EPA's MS4 permit renewal cycle is tightening post-construction stormwater control requirements for new development and redevelopment thresholds. Industrial facilities in Texas and California face expanded monitoring and reporting obligations that elevate permeable pavement from optional credit to compliance necessity. Heavy manufacturing and warehousing developers in Houston and Los Angeles are responding by embedding pervious concrete into site plans earlier in the entitlement process.
Integrated system procurement is consolidating vendor relationships around single-source accountability for infiltration performance. Municipal capital programs in Phoenix and Miami are displacing multi-contractor arrangements that separated concrete supply from drainage aggregate and geotextile specification. Design-build stormwater contractors in the Sun Belt corridor are capturing bundled contracts that internalize subsurface engineering risk and accelerate project closeout timelines.
Pervious Concrete Market Segmentation
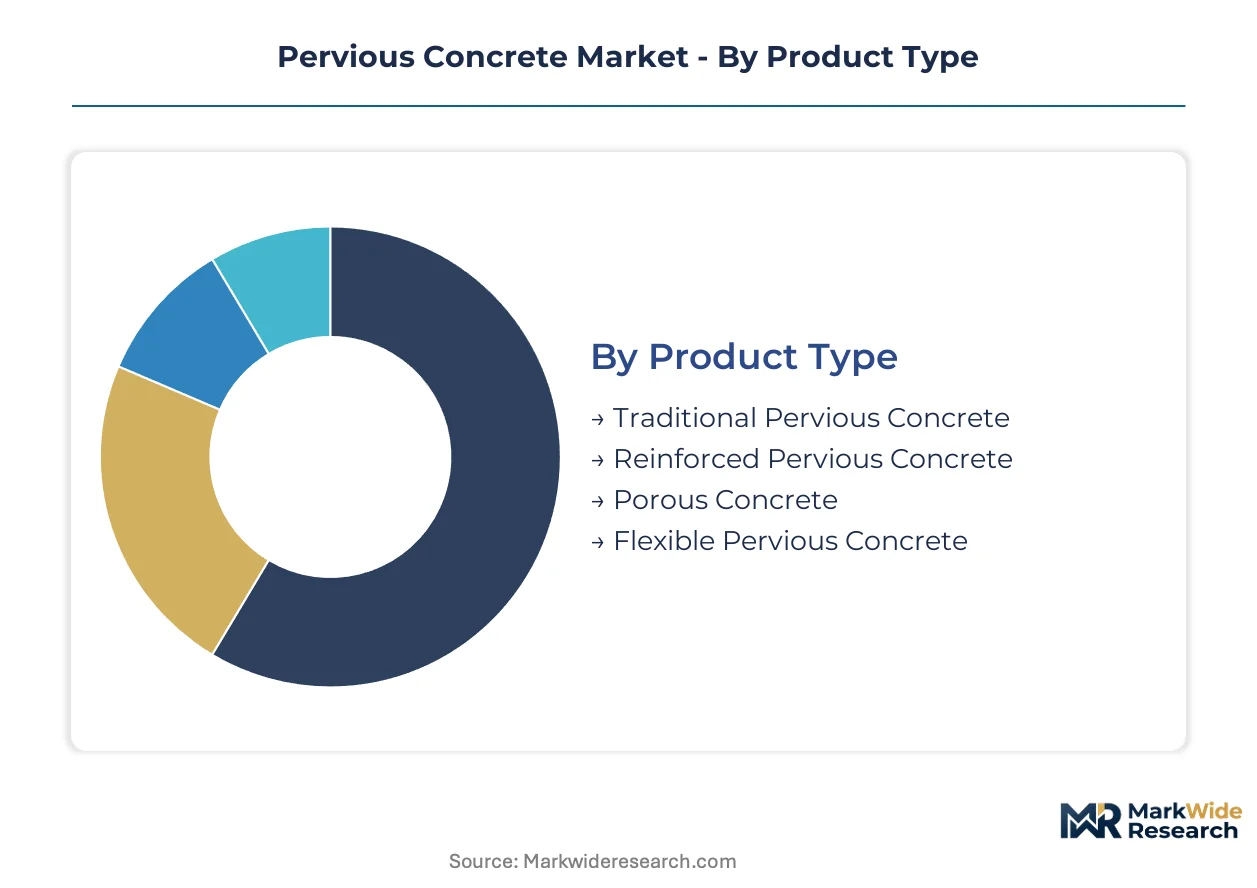
Pervious concrete specification hinges on matching void structure to load requirements and infiltration targets. Segmentation reveals where formulation trade-offs concentrate margin and which procurement channels capture bundled system contracts.
Product Type:
Replacement cycles vary dramatically across product categories, with traditional formulations facing pressure from reinforced variants in heavy-traffic retrofits.
- Traditional Pervious Concrete:Standard hydraulic cementitious composite with 15-25% void content delivers infiltration rates exceeding 100 inches per hour for pedestrian and light-vehicular applications. Municipal parking lots in Phoenix and Miami specify this grade for cost-sensitive installations where structural loads remain modest and maintenance protocols emphasize vacuum sweeping.
- Reinforced Pervious Concrete:Polymer-modified and fiber-reinforced formulations achieve compressive strengths above 4,000 psi while maintaining 15-20% void ratios. Logistics terminals in Houston and distribution centers across Dallas-Fort Worth are upgrading to this grade as forklift traffic and heavy truck volumes exceed conventional capacity limits.
- Porous Concrete:Coarse-aggregate dominant mix with reduced cement paste fraction targets rapid drainage in recreational and secondary roadway applications.
- Flexible Pervious Concrete:Polymer-elasticized binder systems accommodate substrate movement in freeze-thaw climates and expansive soil zones.
Traditional pervious concrete sits at the top of the volume ranking, with reinforced pervious concrete climbing the fastest.
Application:
Cost-tier differentiation separates high-specification commercial installations from standardized municipal deployments.
- Pavements:Public walkway and plaza installations prioritize surface aesthetics alongside infiltration performance. Urban redevelopment zones in Los Angeles and Seattle specify colored and exposed-aggregate finishes for pedestrian corridors where stormwater credits offset material premiums.
- Parking Lots:Commercial and retail surface parking represents the largest single application volume. Big-box retailers in Texas and Florida are embedding pervious concrete into site plans to meet EPA NPDES post-construction runoff controls and secure entitlement approvals.
- Sidewalks:Residential and neighborhood connector installations emphasize rapid placement and minimal curing disruption.
- Roads:Low-volume residential streets and shoulder applications test structural limits of conventional void ratios.
Parking lots dominate current specification volume, with pavements gaining share fastest in urban infill districts.
End User:
Customer-type concentration shapes procurement complexity, with municipalities demanding bundled accountability and developers prioritizing speed-to-certificate.
- Construction Companies:General and specialty contractors executing design-build stormwater projects capture integrated system contracts. Firms in the Sun Belt corridor are internalizing geotechnical and drainage engineering to offer single-source pervious pavement performance warranties.
- Municipalities:City and county capital programs drive specification standardization through master agreements. Phoenix, Miami, and Austin municipal stormwater divisions are consolidating vendor relationships around infiltration-rate guarantees that subsume concrete, aggregate, and geotextile accountability.
- Residential Developers:Master-planned community builders leverage permeable pavement for green building certification credits.
- Landscaping Firms:Commercial grounds maintenance contractors specify pervious concrete for aesthetic hardscape integration.
Municipalities anchor the demand base by contract value, with construction companies expanding their share fastest through design-build consolidation.
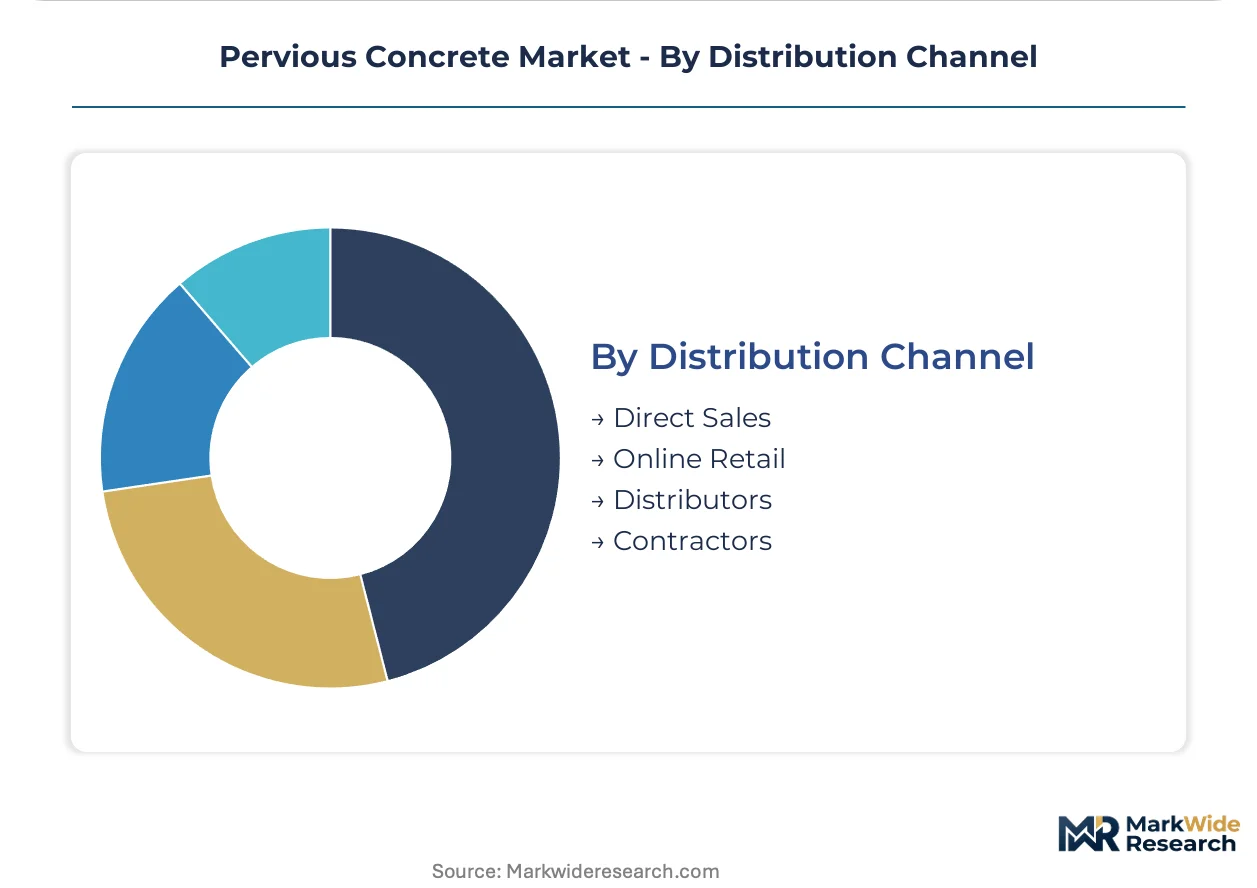
Distribution Channel:
Supply concentration favors direct relationships for large-format projects, while fragmented contractor networks handle residential and small-commercial placement.
- Direct Sales:Ready-mix producers with captive cement supply and technical service capabilities capture major infrastructure and commercial contracts. Vertically integrated suppliers in Texas and Arizona control raw material quality for high-porosity mixes and embed admixture dosing at the plant level.
- Distributors:Regional building material wholesalers stock bagged admixtures and specialty aggregates for contractor pickup. Distributor networks in Florida and Georgia extend reach into secondary markets where ready-mix plant density remains thin.
- Online Retail:E-commerce platforms handle small-volume admixture and maintenance equipment sales.
- Contractors:Installation crews sourcing materials on behalf of project owners capture margin on material markup.
Direct sales command the highest transaction values, with distributors extending geographic coverage most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pervious concrete technology achieved commercial scale in the United States during the 1970s, when Florida municipalities first deployed porous pavements to address coastal flooding. The material's diffusion pattern follows stormwater regulation intensity and urbanization pressure across temperate and subtropical zones.
United States
Sun Belt metropolitan expansion drives specification volume, with Phoenix, Miami, and Austin municipal stormwater programs consolidating vendor relationships around bundled system contracts. The EPA's NPDES MS4 permit renewal cycle tightens post-construction runoff controls for industrial facilities in Houston and Los Angeles. Texas and Florida ready-mix producers with captive cement supply dominate regional procurement through plant-level admixture dosing.
Germany
Heidelberg Materials anchors municipal specifications through technical consulting services for stormwater compliance across the Rhine-Ruhr and Bavarian urban corridors. The EU Green Deal's urban runoff reduction targets and Germany's Federal Water Act implementation accelerate permeable surface mandates in Stuttgart and Hamburg redevelopment zones. Cold-climate admixture development concentrates in Baden-Württemberg research clusters.
China
Sponge City construction targets in Wuhan, Shenzhen, and Shanghai create concentrated demand for high-infiltration pavement systems. The Ministry of Ecology and Environment's urban stormwater management guidelines and provincial dual carbon implementation timelines favor permeable infrastructure in Yangtze River Delta megacities. State-owned construction conglomerates in Jiangsu and Zhejiang provinces integrate pervious concrete into municipal design-build contracts.
India
Bengaluru and Hyderabad municipal corporations specify pervious concrete for groundwater recharge in water-stressed granite terrain. The Central Pollution Control Board's urban runoff guidelines and state-level aquifer protection statutes in Maharashtra and Karnataka mandate infiltration-focused surface designs for commercial development. UltraTech Cement Limited's national ready-mix network captures specification standardization across western and southern state capitals.
Australia
Sydney and Melbourne council stormwater harvesting programs drive permeable pavement adoption in combined sewer overflow priority areas. State revolving fund set-asides for low-impact development projects subsidize installation in Queensland and New South Wales coastal municipalities. Boral Limited's eastern seaboard production footprint controls raw material quality for high-porosity mixes in subtropical climate zones.
Pervious Concrete Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technical service intensity and system bundling capability. The vendor base organizes into three tiers: multinational cement-to-concrete conglomerates with captive raw material supply, regional ready-mix specialists with stormwater engineering partnerships, and admixture formulators with freeze-thaw durability IP. Consolidation pressure favors backward integration into cement production and forward integration into drainage system design.
Among multinational building materials conglomerates, Cemex S.A.B. de C.V., Heidelberg Materials, and Holcim occupy positions defined by vertical network control from clinker production through placement technical service. Sika AG and BASF SE represent the admixture-specialist archetype, anchoring formulation differentiation in cold-climate and self-consolidating variants. These five entities exemplify the competitive tension between material-only supply and integrated system accountability that is displacing multi-contractor procurement across municipal infrastructure programs.
| Leading Market Players |
|---|
| Cemex S.A.B. de C.V. |
| CRH |
| Heidelberg Materials |
| Holcim |
| Sika AG |
| BASF SE |
| Boral Limited |
| UltraTech Cement Limited |
| Chaney Enterprises |
| Others |
Value Network & Pricing Analysis
Portland cement feedstock costs cascade through three distinct pricing tiers for pervious concrete, with energy-intensive clinker production anchoring the upstream cost base and municipal procurement bundling reshaping downstream margin capture. Natural gas and electricity price volatility in cement kilns transmits directly to ready-mix pricing, while admixture-enhanced cold-climate formulations command structural premiums over standard void-ratio mixes in freeze-thaw zones.
Pricing Analysis
Project-based contract pricing dominates municipal and commercial installations, with procurement bundling pervious concrete, drainage aggregates, and geotextile fabrics into single-source accountability packages. Price differentiation rests on void-ratio certification and freeze-thaw durability grading, with polymer-modified reinforced formulations capturing premium positioning over traditional 15-25% void content grades. Cost compression in standard formulations is intensifying because of Portland cement price volatility and qualified contractor scarcity in secondary markets. Municipal stormwater programs exhibit lowest price sensitivity due to compliance-driven specification mandates, while residential developers demonstrate highest sensitivity as green building credits compete against hardscape alternatives.
Supply Chain Analysis
Domestic-content requirements in US federal infrastructure spending and comparable local-content mandates in China and India are reshaping sourcing patterns for cementitious raw materials. Supply concentrates in the United States, China, and Germany, with captive cement production anchoring regional ready-mix networks. Raw material dependencies center on Portland cement clinker, coarse aggregates, and specialty admixtures for freeze-thaw durability. Single-source vulnerability in qualified flatwork contractor networks creates placement bottlenecks during peak construction seasons. Distribution runs through vertically integrated ready-mix producers for large-format projects, with regional distributors extending coverage into secondary markets where plant density remains thin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pervious concrete offers margin expansion through admixture-enabled premium tier migration and automated placement technologies that compress labor intensity. Cold-climate formulation penetration and self-consolidating mix adoption represent the primary cost-down and price-up vectors respectively.
For Market Incumbents: Extend technical service capabilities into bundled stormwater system design to defend against design-build contractor consolidation. Cement-to-concrete conglomerates should deepen backward integration into specialty aggregate sourcing for high-porosity mixes. Freeze-thaw admixture IP represents the critical defensive moat as Minnesota, Wisconsin, and Michigan specifications tighten. For New Entrants and Emerging Players: Launch via regional distributor partnerships targeting secondary Sun Belt markets where ready-mix plant density remains insufficient for incumbent coverage. Municipal parking lot retrofits in Texas and Florida offer the most penetrable application cluster, with vacuum sweeping maintenance contracts providing recurring revenue attachment. Self-consolidating pervious concrete placement services for airport and logistics apron projects enable differentiation without captive cement production. For Investors and Strategic Acquirers: Consolidation pressure builds where admixture formulators lack captive cement supply and regional ready-mix specialists miss stormwater engineering partnerships. Long-term viability favors vertically integrated networks with plant-level dosing capabilities and infiltration-rate warranty authority. The signal to watch is EPA NPDES permit renewal stringency in industrial facility categories, which converts permeable pavement from optional credit to compliance necessity.| Strategic Initiative | Industry Significance |
|---|---|
| Admixture R&D Partnership | Sika AG and BASF SE anchor freeze-thaw durability IP in cold-climate expansion zones. |
| Backward Integration into Aggregates | Cemex S.A.B. de C.V. controls coarse aggregate quality for high-void-ratio mix consistency. |
| Design-Build Stormwater Contracting | Construction firms in Phoenix and Miami internalize geotechnical risk for single-source accountability. |
| Automated Placement Technology Deployment | Self-consolidating pervious concrete reduces crew-size requirements in Florida airport projects. |
| Maintenance Service Bundling | Vacuum sweeping protocols extend project handoff timelines and create recurring revenue streams. |
Research Methodology
Multiple input streams — primary interviews with ready-mix plant managers, municipal stormwater engineers, and admixture R&D directors, alongside secondary validation through EPA NPDES permit databases, ASTM standard documentation, and state revolving fund allocation records — were reconciled through bottom-up and top-down triangulation. Field perspectives from certified flatwork contractors in Texas, Florida, and Arizona informed placement quality variability and labor scarcity dynamics. Trade data on Portland cement and coarse aggregate movements supplemented supply chain concentration analysis.
Segmentation-level volume and value outputs were modeled across product type, application, end user, and distribution channel dimensions, with regional regulatory intensity serving as an additional industry-specific forecast input. CAGRs were derived from regression analysis of historical specification penetration rates against stormwater compliance mandate expansion timelines. Infiltration rate testing standardization progress and clogging prevention maintenance protocol adoption curves informed service-life extension assumptions.
Several conditions sit outside the modeled scope, including abrupt Portland cement price shocks from energy market disruption, ASTM C1701 field-laboratory testing variance resolution, and alternative permeable pavement technology substitution acceleration. Forecasts reflect documented assumptions regarding EPA enforcement continuity and municipal capital program stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Roofing Liners Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
Thin Wall Mould Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Fire Rated Glass Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
North America Prefab Wood Building Market