
 Composite Insulated Panels Market | 2026-2036
Composite Insulated Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Insulated Panels Market Analysis
Advanced polyurethane blowing agent chemistry is rewriting material specifications across the composite insulated panels industry. Kingspan Group leverages its European manufacturing footprint to supply low-GWP panel systems to cold chain operators. Owens Corning anchors North American demand through its fiberglass-facing innovations that improve thermal bridging performance. Metl-Span competes on speed-to-market with regionally distributed coil-coating and foaming lines.
Composite insulated panels are factory-engineered sandwich structures comprising rigid insulation cores bonded to metal or composite facings, typically achieving R-values from R-16 to R-48 depending on core thickness and material density. Their primary purpose is to deliver continuous thermal envelopes for temperature-controlled buildings while eliminating field-installed cavity insulation. Wall panels dominate volume in commercial and industrial construction where speed of erection drives project economics. Cold storage applications represent the fastest-growing segment as food safety regulations tighten and e-commerce grocery fulfillment expands. Mineral wool cores command premium positioning in fire-rated assemblies for high-occupancy structures where ASTM E84 Class A surface burning characteristics are mandated.
The EPA SNAP program restricts hydrofluorocarbon blowing agents in polyurethane production, compelling reformulation across US-based panel lines. REACH and the EU F-Gas Regulation impose parallel constraints on European manufacturers, while China's MEE enforces dual carbon goals that elevate energy efficiency standards for imported building envelope components. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps as thermal performance benchmarks tighten.
Market Dynamics
Polyurethane core chemistry is undergoing forced reformulation as regulatory bodies worldwide phase down high-GWP blowing agents, compressing supplier margins while elevating capital requirements for compliant production lines. This regulatory pressure cascades through specification sheets, procurement contracts, and manufacturing footprints simultaneously.
Growth Catalysts
- EU F-Gas Regulation phase-down:Pentane and hydrofluoroolefin formulations are capturing specification share as manufacturers retool foaming lines to meet GWP thresholds. Cold storage operators in Germany and the Netherlands are locking in long-term supply agreements for compliant panels.
- E-commerce grocery fulfillment expansion:Temperature-controlled last-mile infrastructure is pulling insulated panel volumes into urban logistics hubs. Automated fulfillment centers specify R-32 to R-48 wall assemblies to minimize refrigeration load.
- Mineral wool core innovation:Fire-rated assemblies achieving ASTM E84 Class A surface burning characteristics are penetrating high-occupancy commercial structures where code officials mandate non-combustible insulation.
Market Restraints
- MDI and polyol feedstock volatility:Petrochemical input costs swing panel pricing unpredictably, constraining project budgeting for general contractors on fixed-price contracts.
- European manufacturing concentration:Kingspan and Isopan anchor production in Germany and Italy, creating geographic supply risk for Central European distribution networks during transport disruptions.
- Structural substitution by precast concrete:Mass timber and insulated concrete sandwich panels are capturing envelope share in mid-rise commercial where thermal mass and fire rating converge.
Strategic Opportunities
- India cold chain infrastructure gaps:Post-harvest food loss mandates under FSSAI guidelines are opening specification windows for polyurethane-core panels in controlled-atmosphere warehouses near Mumbai and Delhi.
- Integrated photovoltaic-thermal facades:BIPV sandwich panels combining insulation with energy generation are hybridizing product categories for net-zero commercial retrofits.
- US EPA SNAP program compliance services:Technical consulting and certification support for HFC phase-out is creating recurring revenue streams adjacent to physical panel sales.
Industry Challenges
- Refrigeration system integration complexity:Panel specification must coordinate with CO2 and ammonia refrigeration infrastructure, requiring cross-disciplinary engineering competence that remains scarce in contractor networks.
- Multi-jurisdiction certification timelines:ASTM, EN, and GB standard divergence forces manufacturers to maintain parallel testing protocols, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Insulated Panels Market |
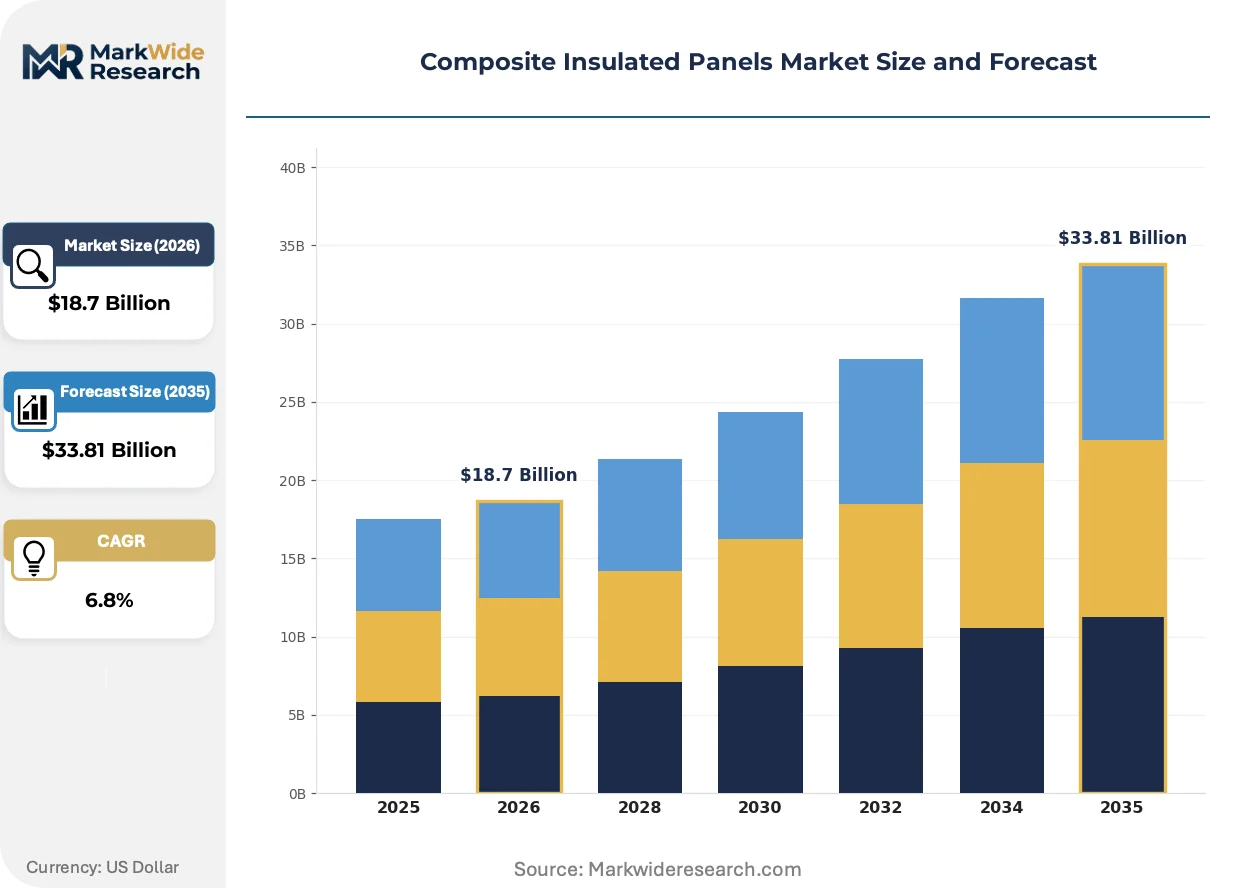
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Panels, Roof Panels, Ceiling Panels, Flooring Panels Material: Polyurethane, Polystyrene, Mineral Wool, Other Insulation Application: Residential, Commercial, Industrial, Cold Storage End User: Contractors, Builders, Architects, Manufacturers |
| Companies Covered | Owens Corning, Nucor Building System, Kingspan Group, Balex-Metal, Isopan, Metl-Span, ArcelorMittal, Manni Group, PFB Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Insulated Panels Market Emerging Trajectories
Material science convergence and regulatory chemistry mandates are compressing product development cycles while opening specification windows for novel core and facing combinations. Panel manufacturers are repositioning as thermal envelope system integrators rather than commodity suppliers.
Vacuum-insulated panel (VIP) technology is hybridizing with conventional polyurethane cores in hybrid sandwich configurations for ultra-low-temperature pharmaceutical distribution. Biologics manufacturers in Switzerland and Singapore are specifying these assemblies for minus-80-degree Celsius stability corridors. The structural consequence is a bifurcation between cost-optimized food cold chain panels and premium pharmaceutical-grade envelope systems.
REACH authorization requirements for flame retardants are forcing reformulation of facing adhesives and core additives across European production lines. Manufacturers are migrating to halogen-free intumescent coatings to maintain CE marking compliance. High-occupancy healthcare and education construction in France and the Benelux is absorbing first volumes of certified assemblies.
Design-build procurement consolidation is compressing specification influence from distributed architects toward integrated contractors with captive engineering. Cold storage developers in the US Sun Belt are bundling panel supply with refrigeration and controls in single-source contracts. This channel shift elevates turnkey capability over unit pricing in vendor selection criteria.
Composite Insulated Panels Market Segmentation
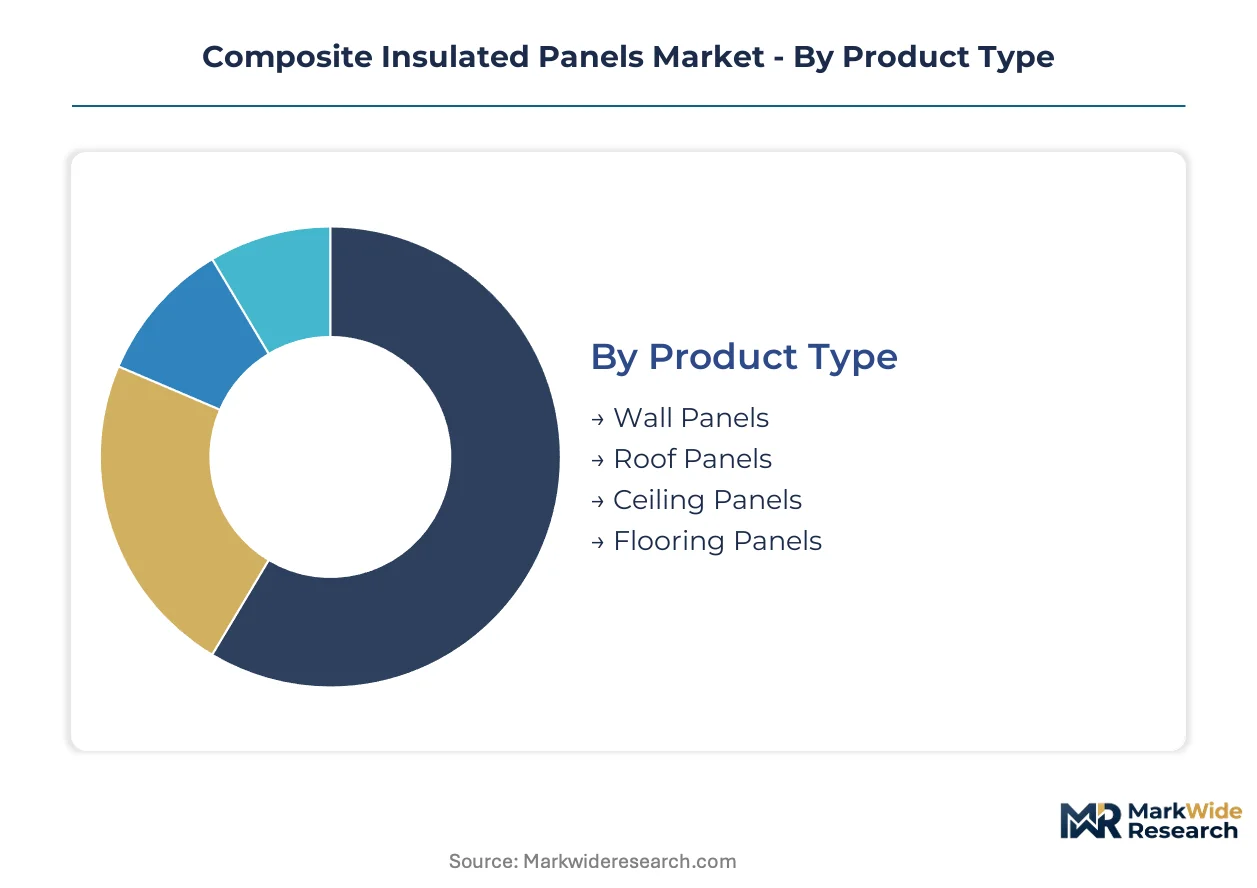
Composite insulated panels serve distinct thermal envelope functions across building types, with specification cycles varying dramatically between speculative commercial construction and engineered cold storage projects. Material chemistry and facing configurations further fragment procurement patterns as regulatory mandates reshape acceptable core formulations.
Product Type:
Wall panels turn inventory fastest in speculative commercial builds, while flooring panels sit longest in specification pipelines due to structural engineering review cycles.
- Wall Panels:Factory-engineered vertical envelope assemblies achieving R-16 to R-48 thermal resistance depending on core thickness. Cold storage developers in Germany and the Netherlands are locking in multi-year supply agreements for R-32 and R-48 wall systems to meet tightening energy efficiency mandates under EU F-Gas Regulation phase-down schedules.
- Roof Panels:Structural sandwich configurations spanning purlin-to-purlin loads with integrated vapor barriers. Automated fulfillment centers across the US Sun Belt specify high-R roof assemblies to minimize refrigeration energy density in temperature-controlled last-mile facilities.
- Ceiling Panels:Suspended or direct-deck applications for interior climate separation in food processing and pharmaceutical clean rooms.
- Flooring Panels:Load-bearing insulated deck systems for raised cold storage platforms and mezzanine structures requiring point-load capacity.
Wall panels dominate installed base across commercial and industrial construction. Cold storage roof panels are where expansion concentrates as e-commerce grocery fulfillment scales temperature-controlled infrastructure.
Material:
Cost tiers separate commodity polystyrene from premium mineral wool, with polyurethane occupying the volume-midpoint where blowing agent reformulation is compressing supplier margins.
- Polyurethane:Closed-cell rigid foam cores delivering highest R-value per inch with factory-laminated metal or composite facings. REACH authorization requirements for flame retardants and EPA SNAP restrictions on HFC blowing agents are forcing simultaneous reformulation of European and North American production lines toward pentane and hydrofluoroolefin chemistries.
- Polystyrene:Expanded or extruded bead foam cores serving cost-sensitive applications with moderate thermal performance. General contractors on fixed-price commercial builds in India specify polystyrene-core panels where capital constraints outweigh long-term energy efficiency targets.
- Mineral Wool:Non-combustible fiber cores achieving ASTM E84 Class A surface burning characteristics for high-occupancy healthcare and education construction in France and the Benelux.
- Other Insulation:Vacuum-insulated panel hybrids and bio-based foam formulations penetrating ultra-low-temperature pharmaceutical distribution corridors.
Polyurethane commands the broadest specification footprint across end-use segments. Mineral wool is gaining share fastest in fire-rated assemblies where building codes mandate non-combustible insulation.
Application:
Volume concentrates in industrial construction, while margin pools deepest in cold storage where thermal performance guarantees command specification premiums.
- Residential:Limited penetration in single-family and multifamily construction due to cost premiums over conventional cavity insulation and site-built framing.
- Commercial:Office, retail, and institutional envelopes where speed of erection drives project economics and design-build procurement consolidates specification authority.
- Industrial:Manufacturing facilities and warehouses specifying standard R-16 to R-24 wall and roof assemblies for basic climate control.
- Cold Storage:Temperature-controlled warehouses and distribution centers requiring R-32 to R-48 thermal envelopes with integrated refrigeration coordination. Post-harvest food loss mandates under India's FSSAI guidelines are opening specification windows for polyurethane-core panels in controlled-atmosphere warehouses near Mumbai and Delhi.
Industrial applications anchor current volume. Cold storage is climbing the fastest as food safety regulations tighten and automated fulfillment infrastructure expands.
End User:
Procurement influence is shifting from distributed architects toward integrated contractors with captive engineering capabilities.
- Contractors:Design-build and general contracting firms bundling panel supply with refrigeration, controls, and erection services in single-source contracts.
- Builders:Production homebuilders and multifamily developers with limited current adoption due to cost and customization constraints.
- Architects:Specification authority compressing as procurement consolidates, though retained for high-occupancy and fire-rated assemblies requiring code compliance documentation.
- Manufacturers:Original equipment manufacturers integrating panels into modular building systems and prefabricated envelope subassemblies.
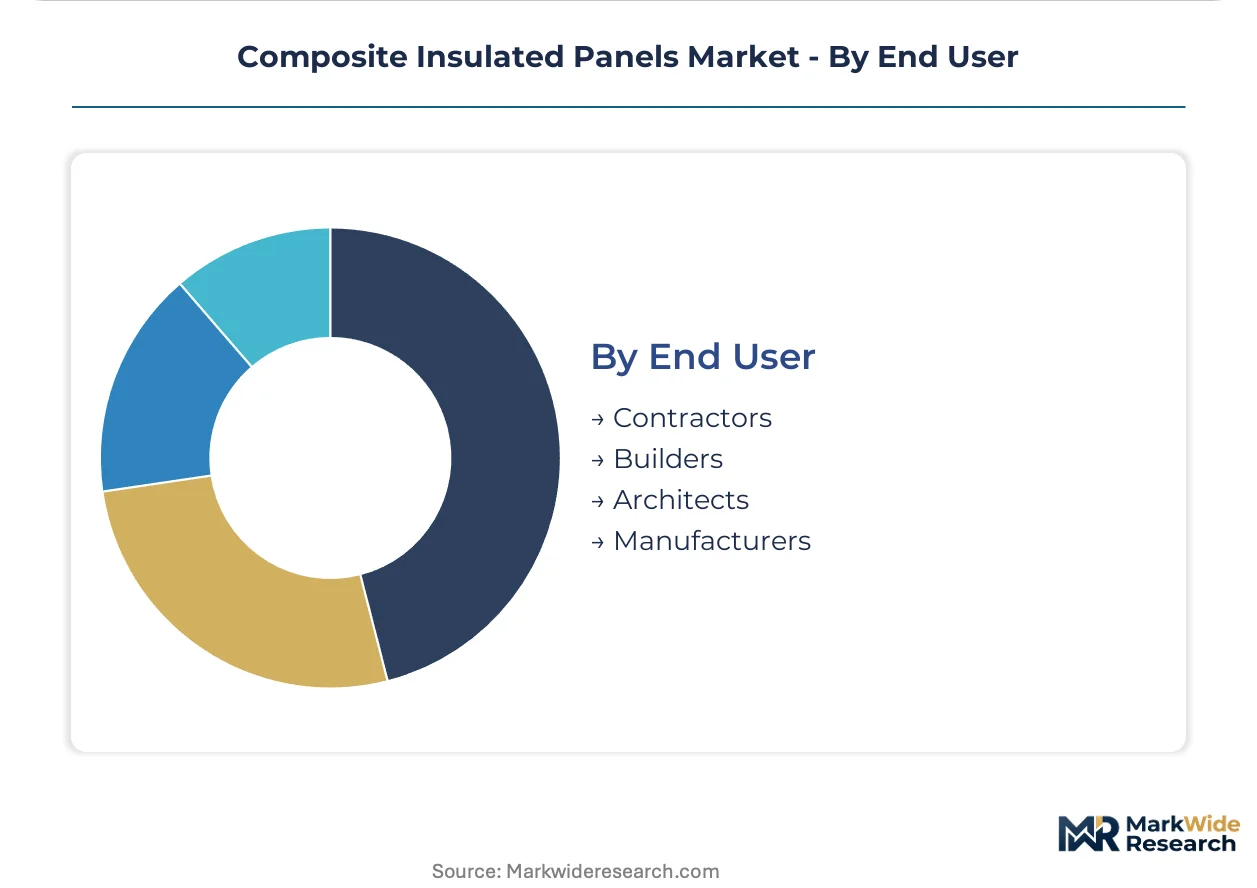
Contractors dominate procurement volume in cold storage and industrial segments. Manufacturers represent the steepest expansion trajectory as modular construction and prefabricated envelope systems gain adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export polyurethane-core panels to cold storage operators across Central Europe and the Netherlands, while US fabricators supply Sun Belt fulfillment centers through regionally distributed coil-coating networks.
Germany
Cold storage developers in the Rhine-Ruhr corridor are locking in multi-year supply agreements for R-32 and R-48 wall systems. The EU F-Gas Regulation is accelerating shifts toward pentane and hydrofluoroolefin formulations. Kingspan and Isopan anchor manufacturing clusters near Düsseldorf serving distribution networks into Poland and the Czech Republic.
United States
Automated grocery fulfillment centers across Texas, Arizona, and Florida are specifying high-R roof assemblies to minimize refrigeration load density. The EPA SNAP program restricts hydrofluorocarbon blowing agents in polyurethane production, compelling reformulation across domestic panel lines. Owens Corning anchors demand through fiberglass-facing innovations manufactured in the Southeast.
India
Post-harvest food loss mandates under FSSAI guidelines are opening specification windows for controlled-atmosphere warehouses near Mumbai and Delhi. The Bureau of Indian Standards enforces energy efficiency benchmarks for imported building envelope components. Cold chain infrastructure gaps in Maharashtra and Gujarat are pulling panel volumes into temperature-controlled storage near agricultural procurement zones.
Netherlands
Rotterdam port logistics operators are scaling adoption of low-GWP panel systems to meet tightening energy efficiency mandates under EU Green Deal implementation schedules. ECHA REACH authorization requirements for flame retardants are forcing reformulation of facing adhesives across Dutch distribution channels. Cold storage clusters in the Randstad are absorbing first volumes of pentane-foamed assemblies.
China
E-commerce grocery fulfillment expansion in the Yangtze River Delta is pulling insulated panel volumes into urban logistics hubs near Shanghai and Hangzhou. The Ministry of Ecology and Environment enforces dual carbon goals that elevate energy efficiency standards for building envelope components. GB standard divergence from ASTM and EN protocols forces manufacturers to maintain parallel testing protocols for export-bound production.
Composite Insulated Panels Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three archetypes: vertically integrated multinationals with captive coil-coating and foaming lines, regional fabricators competing on speed-to-market through distributed manufacturing, and technology licensors supplying blowing agent chemistry and facing adhesives. Dominant competitive moves include backward integration into polyol and MDI feedstock security, and geographic expansion through acquisition of regional panel fabricators.
Within the multinational tier, Kingspan Group and Owens Corning occupy positions as scale-driven envelope system integrators, while Metl-Span exemplifies the North American regional fabricator archetype competing on project turnaround velocity. Isopan represents the European specialist position anchored in Italian and German manufacturing footprints. These three names illustrate how competitive positioning stratifies across global reach, regional density, and application-specific engineering depth.
| Leading Market Players |
|---|
| Owens Corning |
| Nucor Building System |
| Kingspan Group |
| Balex-Metal |
| Isopan |
| Metl-Span |
| ArcelorMittal |
| Manni Group |
| PFB Corporation |
| Others |
Supply Flow & Price Mechanics
German and Italian polyurethane core manufacturing clusters concentrate upstream supply for low-GWP panel systems, anchoring margin pools with cold storage operators in the Netherlands and Poland who lock in multi-year offtake agreements. This geographic concentration of compliant foaming capacity shapes downstream pricing power across Central European distribution networks.
Pricing Analysis
Prior-generation hydrofluorocarbon-blown polyurethane panels trade at commodity benchmarks, current-generation pentane-foamed systems command certification premiums, and next-generation hydrofluoroolefin formulations price at prototype premiums. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade VIP hybrids from commercial cold chain panels and cost-optimized polystyrene-core alternatives. Cost compression in standard-tier polyurethane stems from MDI and polyol feedstock volatility. Cold storage developers exhibit lowest price sensitivity due to thermal performance guarantees, while Indian commercial builders on fixed-price contracts show highest sensitivity.
Supply Chain Analysis
Tariff exposure between China and key export destinations for building envelope components dominates supply chain risk assessment for panel manufacturers. Production gravity centers on Germany, Italy, and the United States for polyurethane-core fabrication. Raw material dependencies draw from petrochemical feedstocks including MDI, polyol resins, and steel coil for metal facings. Single-source vulnerability concentrates in specialized blowing agent chemistry licensed from technology providers. Distribution runs through design-build contractors bundling panel supply with refrigeration and erection services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA SNAP, EU F-Gas, and China's MEE dual carbon goals is fragmenting specification standards, creating niche opportunities for regionally specialized panel fabricators and compliance service providers.
For Market Incumbents: Insulate market position by securing captive polyol and MDI feedstock agreements to buffer margin compression from petrochemical volatility. Invest in parallel ASTM, EN, and GB certification testing capabilities to compress product launch cycles as multi-jurisdiction standards diverge. Backward integration into low-GWP blowing agent chemistry licensing anchors differentiation against commodity panel imports. For New Entrants and Emerging Players: Establish a beachhead in India's controlled-atmosphere warehouse segment where FSSAI post-harvest loss mandates are opening specification windows ahead of domestic manufacturing scale-up. Target turnkey thermal envelope integration services for US Sun Belt automated fulfillment centers where design-build procurement consolidates vendor selection around single-source capability rather than unit pricing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabricators in North America and Western Europe holding distributed coil-coating networks but lacking compliant chemistry partnerships. The five-to-ten-year viability window favors targets with established pentane or hydrofluoroolefin foaming lines already operational. Watch for EU F-Gas Regulation enforcement actions as the inflection signal accelerating stranded inventory write-downs among laggard producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agent Chemistry | Captive supply of pentane and hydrofluoroolefin formulations locks in EU F-Gas compliance. |
| Parallel Certification Investment | Simultaneous ASTM, EN, and GB testing compresses launch cycles for multi-jurisdiction panel sales. |
| Turnkey Thermal Envelope Bundling | Single-source contracts combining panels with refrigeration and controls elevate vendor stickiness. |
| Regional Fabricator Acquisition | Geographic density in Texas, Arizona, and Florida shortens lead times for Sun Belt fulfillment centers. |
| Pharmaceutical-Grade VIP Hybrid Development | Ultra-low-temperature biologics distribution commands specification premiums in Switzerland and Singapore. |
Methodological Framework
Cross-validation between cold storage developer interviews and customs trade data anchors the qualitative findings in this analysis. Primary fieldwork engaged plant managers at polyurethane foaming facilities, procurement leads at refrigerated warehouse operators, technical R&D directors at facing adhesive suppliers, and channel partners in European distribution networks. Secondary sources included SEC 10-K filings from publicly traded building materials firms, Cefic chemical production statistics, and ECHA REACH authorization databases. Bottom-up panel shipment data and top-down construction spending estimates were triangulated to bound volume ranges.
Calibration against historical growth trajectories in cold chain infrastructure and e-commerce fulfillment capex informs the projection framework across the analysis window. Segmentation dimensions modeled include core material chemistry, facing configuration, thermal performance tier, application type, and regional regulatory cluster. CAGRs were derived from slope analysis of adoption curves in comparable building envelope technologies. Industry-specific forecast inputs incorporate EU F-Gas phase-down schedules and EPA SNAP enforcement timelines.
Stress conditions across MDI price volatility, transport disruption severity, and regulatory acceleration scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about substitution elasticity between polyurethane and mineral wool cores. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
Metal Roofing Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
South Africa Wall Putty Market
Building & Construction Materials
Glass Curtain Wall Market
Building & Construction Materials
North America Cross-Laminated Timber Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market