
 Global Steel Pipe Piles Market | 2026-2036
Global Steel Pipe Piles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Steel Pipe Piles Market Outlook
High-strength steel formulation and automated submerged-arc welding is tilting fabrication economics toward spiral welded and large-diameter product lines. ArcelorMittal leverages integrated blast furnace capacity to anchor supply security for European offshore wind contractors. Nippon Steel Corporation sustains technical leadership in ultra-thick wall seamless pipe for seismic-zone foundations. EVRAZ dominates tubular product output across Siberian and North American mills, competing on raw material self-sufficiency.
Steel pipe piles are hollow cylindrical structural elements, typically manufactured from carbon or low-alloy steel with wall thicknesses ranging from 6 mm to over 100 mm, driven or drilled into subsurface strata to transfer structural loads to bearing layers. Spiral welded configurations command volume leadership in marine and infrastructure applications due to cost-efficient continuous forming from coiled strip, while seamless grades capture premium positioning in high-load, fatigue-critical bridge and oil platform legs where absence of longitudinal weld seams enhances structural integrity. Corrosion-resistant alloy cladding and epoxy barrier coatings represent the fastest-expanding specification tier as asset owners extend design life requirements for submerged and splash-zone installations.
ISO 12944 coating durability standards, Eurocode 3 structural design provisions, and China's GB/T 50205 steel structure acceptance criteria collectively govern material qualification, weld inspection protocols, and corrosion protection mandates across major demand centers. Japan's METI enforces JIS G 3444 general structural tube standards that restrict import eligibility and shape domestic procurement patterns for public works. Stakeholders must monitor evolving carbon border adjustment mechanisms and embodied-carbon disclosure rules that threaten to reclassify supply sources and reshape contract qualification criteria for publicly funded infrastructure.
Market Dynamics
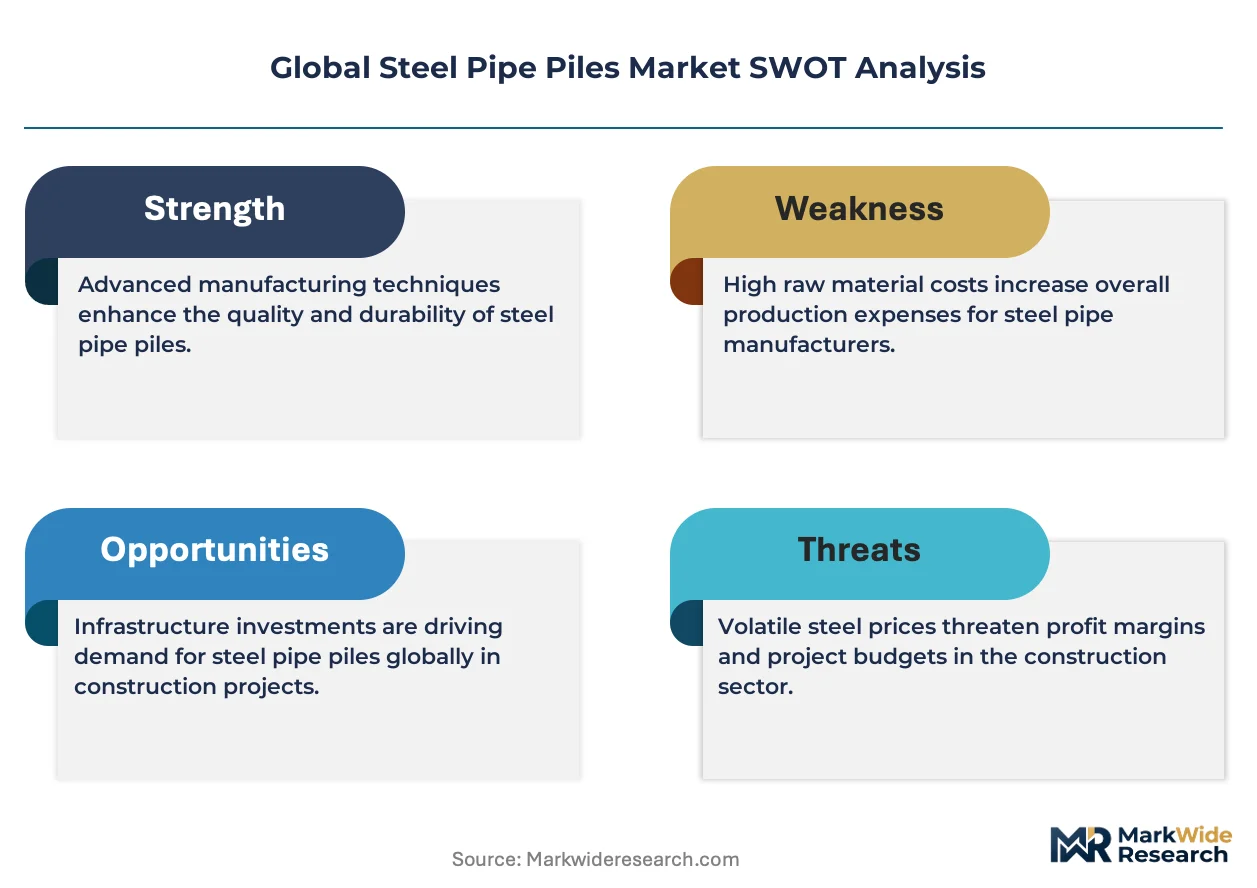
Offshore wind farm developers are compressing foundation installation windows, forcing fabricators to pre-qualify large-diameter spiral welded pipe against fatigue specifications that previously applied only to oil platform legs. This specification compression is redrawing supplier qualification tiers.
Growth Catalysts
- EU Green Deal offshore wind targets:National auction rounds in Germany, Denmark, and the Netherlands mandate turbine foundation delivery contracts that specify corrosion-resistant alloy grades, pulling mill capacity toward marine-certified product lines.
- China's coastal megaproject pipeline:Port expansions in Guangdong and Zhejiang provinces consume substantial tonnage of driven pipe piles, with state-owned developers consolidating procurement to secure domestic mill allocation.
- Automated submerged-arc welding:Continuous forming from coiled strip is compressing fabrication economics for spiral welded configurations, enabling cost parity with longitudinal seam alternatives in diameters exceeding 2 meters.
Market Restraints
- Scrap-to-billet cost volatility:Electric arc furnace operators face margin compression when ferrous scrap prices spike, limiting price competitiveness against integrated blast furnace producers in long-diameter categories.
- Seamless capacity concentration:Ultra-thick wall seamless pipe for seismic-zone foundations relies on a narrow base of Japanese and German mill sources, creating supply security exposure for bridge contractors in high-load applications.
- Carbon border adjustment mechanisms:Embodied-carbon disclosure rules threaten to reclassify import eligibility for publicly funded infrastructure, disadvantaging suppliers without verified emissions documentation.
Strategic Opportunities
- Floating offshore wind foundations:Emerging tension-leg and semi-submersible platform designs require specialized tubular joints that diverge from conventional driven pile specifications, opening white space for fabrication specialists.
- Corrosion-resistant alloy cladding:Splash-zone installations in the North Sea and Gulf of Mexico are extending design life requirements, creating specification tier expansion for thermally sprayed aluminum and epoxy barrier coating systems.
- India's port modernization:Sagarmala infrastructure corridors and new container terminals under the Ministry of Ports, Shipping and Waterways represent underpenetrated demand for large-diameter marine piles.
Industry Challenges
- Multi-standard weld inspection protocols:Fabricators serving cross-border projects must maintain simultaneous accreditation to ISO 12944 coating durability standards, Eurocode 3 structural provisions, and China's GB/T 50205 acceptance criteria, extending qualification timelines.
- Fatigue testing capacity:Pre-qualification of large-diameter pipe for offshore wind foundations requires full-scale cyclic load testing facilities that remain scarce outside specialized marine research centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Steel Pipe Piles Market |
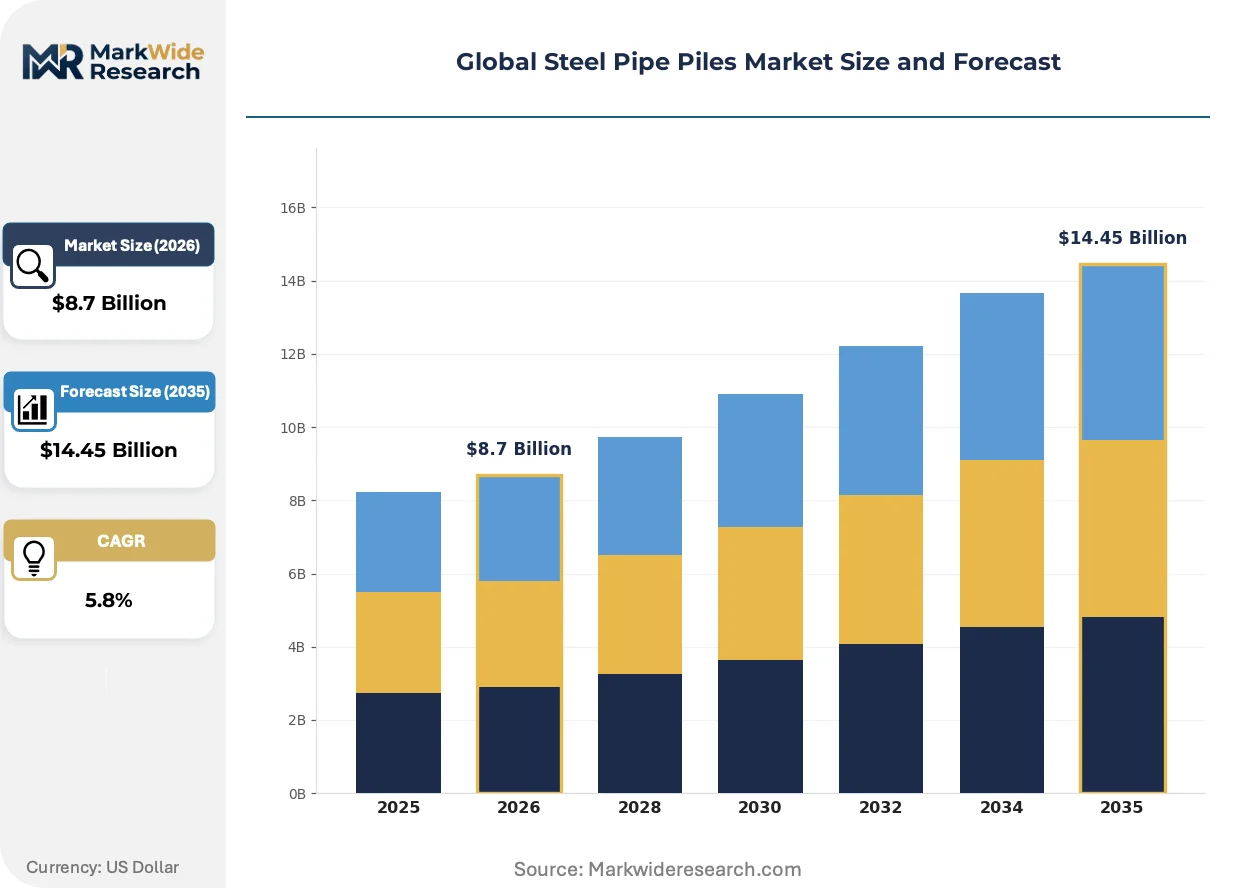
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Welded, Spiral Welded, Seamless, Corrosion-Resistant Application: Marine Structures, Foundations, Retaining Walls, Bridge Construction End User: Construction, Oil & Gas, Transportation, Infrastructure Size: Small Diameter, Medium Diameter, Large Diameter, Custom Size |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, JFE Steel Corporation, TMK IPSCO, EVRAZ, Zekelman Industries, Meever, ESC Group, Northwest Pipe Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Steel Pipe Piles Market Strategic Shifts
Fabrication technology and regulatory disclosure requirements are converging to reshape competitive positioning. Specification complexity is rising faster than standardization can accommodate.
Hybrid manufacturing processes combining spiral welded forming with seamless-grade heat treatment are hybridizing product category boundaries. Offshore wind EPC contractors in the North Sea basin are specifying these intermediate grades for transition piece connections that must withstand both fatigue cycling and installation impact loads. The technology is hybridizing procurement patterns, enabling single-source contracting for foundation packages that previously required tiered supplier management.
The EU Green Deal's embodied carbon disclosure mandates are forcing mill-level emissions verification across European offshore wind supply chains. Contractors bidding for state-backed auction rounds must now submit cradle-to-gate carbon intensity data that disqualifies sources above threshold levels. German and Danish developers are responding by tightening pre-qualification criteria to exclude suppliers without third-party verified Environmental Product Declarations.
Buyers are consolidating procurement through long-term offtake agreements that displace spot-market purchasing for foundation steel. Major offshore wind developers in Taiwan and South Korea are locking in multi-year mill commitments to secure allocation during capacity-constrained periods. This pattern is most visible in markets where auction schedules concentrate demand into narrow delivery windows, compressing supplier selection cycles and favoring fabricators with demonstrated execution track records.
Global Steel Pipe Piles Market Segmentation
Steel pipe pile specification tiers diverge sharply across load-bearing requirements and environmental exposure conditions. Procurement patterns fragment between cost-driven infrastructure tenders and performance-critical offshore wind foundations.
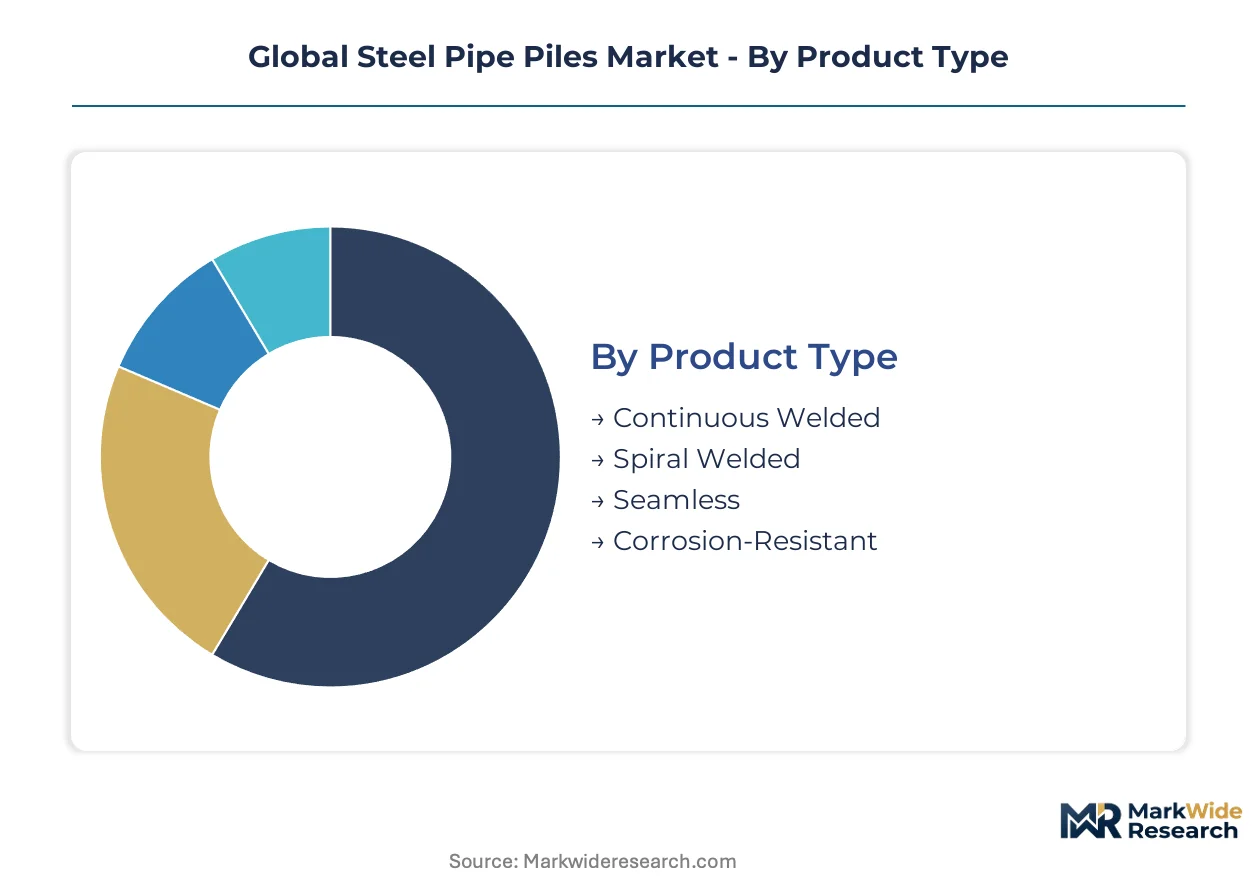
Product Type:
Mature continuous forming technologies dominate volume production, while emerging alloy formulations capture specification premiums in corrosive environments.
- Spiral Welded:Continuous forming from coiled strip enables diameters exceeding 2 meters with wall thicknesses from 8 mm to 50 mm. Marine contractors in the North Sea and Gulf of Mexico specify these configurations for offshore wind monopile foundations where automated submerged-arc welding ensures fatigue-rated seam integrity.
- Seamless:Hot-rolled or extruded construction eliminates longitudinal weld seams entirely, delivering uniform circumferential strength for seismic-zone bridge piers and oil platform legs. Japanese and German mill sources concentrate capacity for ultra-thick wall grades above 75 mm, creating supply security exposure for high-load applications.
- Continuous Welded:Electric resistance welding of skelp strip suits small-to-medium diameter piles for general foundation work where cost minimization outweighs fatigue performance.
- Corrosion-Resistant:Alloy-clad or epoxy-coated variants address splash-zone exposure in port installations and coastal infrastructure, with thermally sprayed aluminum systems extending design life requirements.
Spiral welded configurations retain volume leadership; corrosion-resistant grades hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity foundation work from premium marine engineering specifications.
- Marine Structures:Port quay walls, jetty piles, and offshore wind turbine foundations demand large-diameter spiral welded or seamless pipe with certified impact toughness and cathodic protection compatibility. German and Danish auction rounds mandate marine-certified product lines with third-party weld inspection.
- Foundations:Building and industrial structure piles utilize continuous welded and small-diameter spiral configurations where static load transfer dominates over cyclic fatigue considerations.
- Bridge Construction:Seismic design codes in Japan and California drive specification of seamless ultra-thick wall pipe for moment-resisting pier foundations subject to lateral spreading.
- Retaining Walls:Sheet pile and soldier pile applications consume medium-diameter welded pipe for earth retention systems in urban excavation and highway widening projects.
Marine structures command the highest specification tier; foundation applications generate the broadest volume base.
End User:
Customer type determines procurement channel structure, from spot-market purchasing to multi-year offtake agreements.
- Infrastructure:State-owned developers in China and India consolidate procurement for port expansions and coastal megaprojects, locking in domestic mill allocation through framework contracts.
- Construction:Private contractors bid infrastructure tenders on thin margins, favoring continuous welded and standard spiral grades without premium corrosion protection.
- Oil & Gas:Platform jacket legs and subsea pipeline supports require seamless or high-grade spiral welded pipe with sour service resistance and full-body ultrasonic testing.
- Transportation:Bridge authorities in seismic zones specify seamless pipe for critical load paths while accepting welded alternatives for approach spans.
Infrastructure end users drive consolidation in procurement patterns; oil and gas maintains the most stringent qualification barriers.
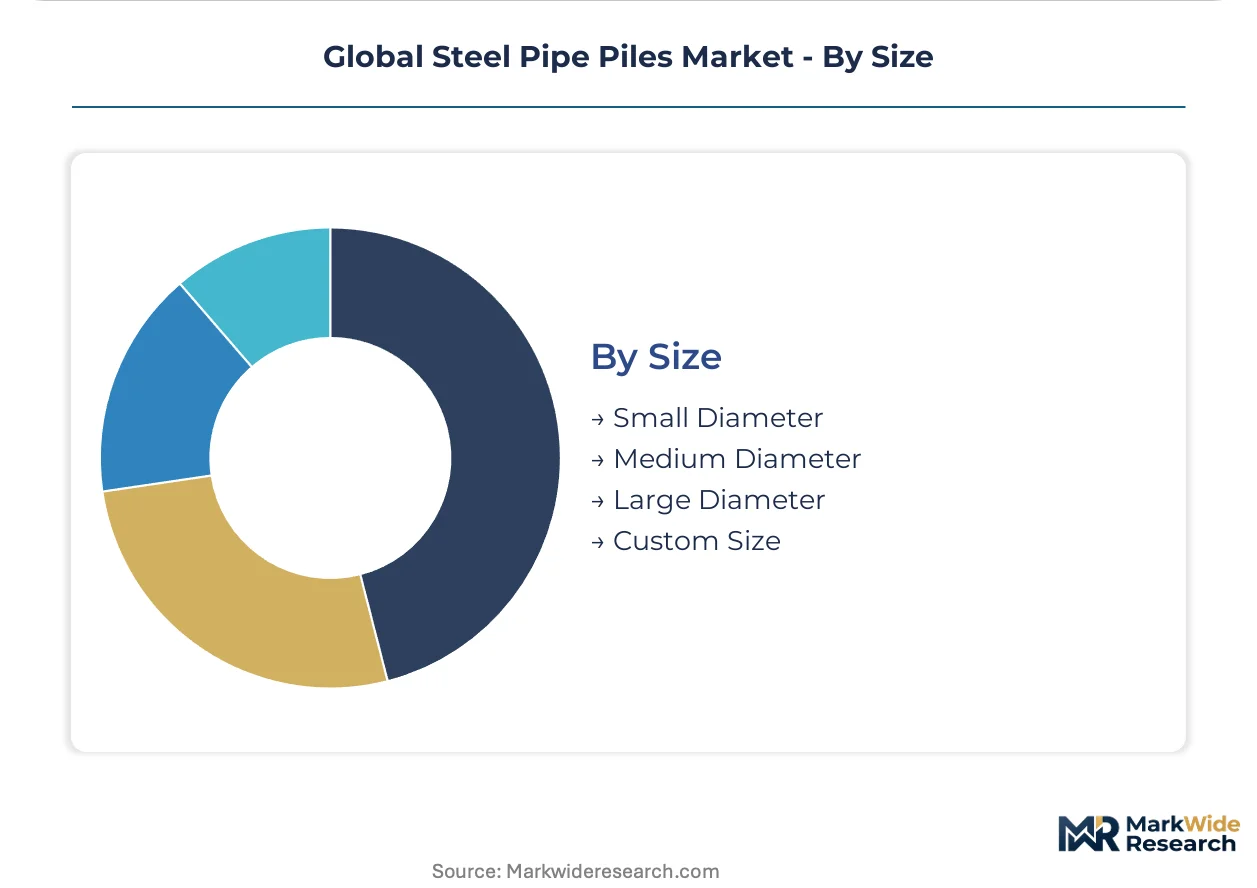
Size:
Supply concentration intensifies at diameter extremes, with mid-range categories facing commoditization pressure.
- Large Diameter:Exceeding 1.5 meters outer diameter, these piles serve offshore wind monopiles and major port quay walls where spiral welded forming from heavy coil is cost-optimized. Fabrication capacity concentrates in coastal mills with deep-water shipping access.
- Medium Diameter:400 mm to 1.5 meter range covers general building foundations and bridge piers, with both spiral and continuous welded supply options creating price competition.
- Small Diameter:Below 400 mm, these piles suit light structural loads and temporary works, sourced from regional mini-mills with electric arc furnace feedstock.
- Custom Size:Non-standard diameters and wall thickness ratios serve specialized offshore platform joints and hybrid foundation systems, requiring dedicated mill scheduling.
Large diameter specifications concentrate supply among specialized fabricators; custom sizes gain traction in floating wind foundation prototypes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese mills export large-diameter spiral welded pipe to European offshore wind contractors under EU Green Deal procurement mandates, while Japanese seamless producers supply seismic-grade foundations to Pacific Rim bridge authorities.
China
Coastal megaprojects in Guangdong and Zhejiang provinces consume substantial tonnage for port quay walls and container terminals. The Ministry of Ecology and Environment enforces dual carbon goals that pressure mills to document embodied emissions for state-backed tenders. Qingdao and Tianjin anchor the dominant fabrication clusters where state-owned developers consolidate procurement through framework contracts.
Germany
North Sea offshore wind auction rounds mandate corrosion-resistant alloy grades for monopile foundations, pulling mill capacity toward marine-certified product lines. The EU Green Deal's embodied carbon disclosure rules disqualify suppliers without verified Environmental Product Declarations. Rostock and Bremerhaven host the primary fabrication yards where developers pre-qualify pipe against fatigue specifications.
United States
Gulf of Mexico port expansions and hurricane-resistant coastal infrastructure drive demand for splash-zone protected piles. FERC environmental review processes and Buy America provisions shape contract eligibility for federally funded waterway projects. Houston and New Orleans concentrate marine contractor procurement offices that source from domestic spiral welded mills.
Japan
Seismic-zone bridge foundations and typhoon-resistant coastal structures specify ultra-thick wall seamless pipe for moment-resisting piers. METI enforces JIS G 3444 general structural tube standards that restrict import eligibility and shape domestic procurement patterns for public works. Osaka and Nagoya mill complexes concentrate capacity for fatigue-critical applications.
India
Sagarmala port modernization corridors and new container terminals under the Ministry of Ports, Shipping and Waterways represent expanding demand for large-diameter marine piles. BIS certification requirements and PLI scheme incentives for domestic steel production influence contractor sourcing decisions. Mumbai and Visakhapatnam anchor the emerging fabrication clusters serving western and eastern coastline projects.
Global Steel Pipe Piles Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered qualification tiers. Integrated blast furnace operators anchor supply security for European offshore wind contractors, while electric arc furnace mini-mills compete on spot-market responsiveness for general foundation work. Three archetypes dominate: scale-driven integrated producers, seamless-grade specialists, and corrosion-protection fabricators. Capacity expansion and strategic partnerships constitute the primary competitive moves as fabricators pre-qualify against multi-standard weld inspection protocols.
Among integrated producers, ArcelorMittal anchors European supply security through blast furnace capacity, while Nippon Steel Corporation occupies a position within the seamless-grade specialist tier exemplifying technical leadership in ultra-thick wall configurations. EVRAZ represents the raw material self-sufficiency archetype, with Siberian and North American mill networks competing on captive iron ore and coking coal access. These three entities collectively illustrate the geographic and technological stratification governing foundation steel procurement.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| JFE Steel Corporation |
| TMK IPSCO |
| EVRAZ |
| Zekelman Industries |
| Meever |
| ESC Group |
| Northwest Pipe Company |
| Others |
Value Chain & Pricing Dynamics
Deep-water shipping corridors from Tianjin to Rotterdam transmit freight cost volatility directly into landed price spreads between Asian and European mill sources, compressing margins for distributors while amplifying price differentiation between blast furnace-integrated and electric arc furnace-dependent supply tiers.
Pricing Analysis
The pricing gap between seamless-grade legacy production, current spiral welded continuous forming, and emerging hybrid heat-treated configurations structures contract negotiations across foundation steel procurement. Three-tier pricing stratification across marine-certified premium, standard structural, and economy-grade continuous welded levels reflects divergence in fatigue certification, third-party weld inspection, and corrosion protection bundling. Price differentiation centers on ISO 12944 coating durability tier and full-body ultrasonic testing coverage, with premium marine grades commanding substantial spreads over general foundation alternatives. Cost compression in economy-tier electric arc furnace supply is intensifying because ferrous scrap volatility limits spot-market competitiveness against integrated producers. Infrastructure contractors in India and Southeast Asia exhibit the highest price sensitivity, while North Sea offshore wind developers prioritize supply security over unit cost minimization.
Supply Chain Analysis
Contract manufacturing concentration among coastal Chinese fabricators, Japanese seamless specialists, and German marine-certified yards governs allocation priority for large-diameter spiral welded orders. Geographic supply concentration clusters in China, Japan, and Germany, with secondary capacity emerging in India and the United States. Raw material flows draw from captive iron ore and coking coal access in Siberia, high-grade scrap networks in North America, and alloy element supply from South African chromium and Indonesian nickel sources. Single-source vulnerability concentrates in ultra-thick wall seamless capacity, where Japanese and German mill specialization creates supply security exposure for seismic-zone bridge contractors. Distribution runs through mill-direct framework contracts for state-backed infrastructure, with spot-market intermediaries serving fragmented construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corrosion protection service contracts and inspection-retainer agreements expand faster than bare pipe tonnage, creating recurring-revenue layers that offset commodity steel margin compression for fabrication specialists.
For Market Incumbents: Entrench supply security through backward integration into heavy coil rolling capacity and captive alloy cladding operations, defending against electric arc furnace mini-mills encroaching on standard-grade foundation work. Pre-qualify spiral welded lines against emerging floating wind fatigue specifications before auction windows compress supplier selection cycles. Carbon border adjustment mechanisms threaten to disqualify unverified emission sources from EU public tenders, making third-party Environmental Product Declaration investment a certification lever for European contract eligibility. For New Entrants and Emerging Players: Build out corrosion-resistant alloy cladding capabilities targeting North Sea and Gulf of Mexico splash-zone installations, where design life extension requirements outpace incumbent coating capacity expansion. India's Sagarmala port corridors represent the most penetrable geography, with BIS certification barriers lower than EU marine qualification tiers and state-owned developer procurement consolidating toward framework contract structures. A go-to-market angle anchored in thermally sprayed aluminum system specialization bypasses direct competition with integrated blast furnace operators in commodity spiral welded tonnage. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified steel conglomerates with stranded seamless pipe capacity in seismic-grade niches, where technical specialization supports pricing power independent of commodity steel cycles. Long-term viability over the next decade hinges on positioning within offshore wind foundation supply chains, where auction-schedule demand concentration favors execution-track record over cost minimization. Monitor German and Danish auction round pre-qualification criteria tightening as the inflection signal for supplier tier reclassification.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Certification Investment | Pre-qualification against EU offshore wind fatigue specifications secures auction-round contract eligibility. |
| Corrosion Protection Capability Buildout | Thermally sprayed aluminum and epoxy barrier coating capacity captures splash-zone specification premiums. |
| Backward Integration into Heavy Coil | Captive supply of coiled strip insulates spiral welded fabrication from ferrous scrap volatility. |
| Long-term Offtake Agreement Structuring | Multi-year mill commitments lock in allocation during capacity-constrained auction delivery windows. |
| Emissions Verification Program | Third-party Environmental Product Declarations satisfy EU Green Deal embodied carbon disclosure mandates. |
Study Parameters
Cross-validation between mill shipment data and offshore wind foundation contract awards anchors the qualitative findings, combining primary interviews with marine contractor procurement officers, fabricator technical directors, port authority engineers, and regulatory compliance leads with secondary validation through customs trade records, EU auction round documentation, SEC filings from integrated steel producers, and national steel association production statistics. Bottom-up tonnage aggregation from identified foundation projects triangulates against top-down capacity utilization estimates across major mill complexes.
Calibration against historical price spreads between seamless and spiral welded grades, coupled with verified contract award values for North Sea offshore wind installations, structures the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application load requirement, end-user procurement channel structure, and regional regulatory cluster. CAGRs derive from installed capacity trajectories in offshore wind and coastal infrastructure, cross-referenced with mill expansion announcements and alloy formulation adoption curves for corrosion-resistant specifications.
Stress conditions across ferrous scrap price bands, carbon border adjustment threshold levels, and floating wind foundation specification divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding auction schedule concentration, mill certification timeline stability, and alloy element supply continuity. Quarterly review of EU pre-qualification criteria tightening, Indian BIS certification pathway changes, and Japanese seismic code revision proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Chain Link Fencing Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Steel Roofing Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
North America Rainscreen Cladding Market
Building & Construction Materials
Steel Rebar Market