
 US Geosynthetics Market | 2026-2036
US Geosynthetics Market Size, Share, and Industry Trends Forecast 2026-2036
US Geosynthetics Market Analysis
Polymer formulation science is fragmenting the traditional geosynthetics supply base as high-density polyethylene and polypropylene grades diverge into application-specific performance tiers. Solmax International Inc. leverages its geomembrane specialization to anchor large-scale containment contracts across mining and waste sectors. DuPont de Nemours Inc. sustains materials innovation through advanced polymer R&D pipelines that feed into geotextile and geogrid product lines. Tensar Corporation dominates soil reinforcement segments with proprietary biaxial and triaxial geogrid architectures.
Geosynthetics encompass engineered polymer-based materials—typically polypropylene, polyester, polyethylene, or natural fiber composites—manufactured through extrusion, weaving, or needle-punching processes to provide separation, filtration, reinforcement, or containment functions in civil and environmental engineering. Geomembranes lead value capture due to their critical role in landfill liners and impoundment systems where impermeability standards dictate material selection. Geotextiles represent the volume backbone across drainage and erosion control applications, while geocells are gaining traction in steep slope stabilization and load support scenarios where three-dimensional confinement delivers structural efficiency.
Federal Highway Administration guidelines, EPA Subtitle D landfill regulations, and ASTM D35 standards collectively shape product certification requirements and procurement protocols for infrastructure and environmental projects. State DOT specifications in California, Texas, and Florida incorporate AASHTO M288 geotextile classifications, creating regional compliance thresholds that filter supplier participation. Stakeholders must track evolving EPA coal ash rules and state-level PFAS containment mandates to anticipate specification shifts that will redefine competitive qualification criteria.
Market Dynamics
State transportation agencies are rewriting pavement design manuals to mandate geogrid reinforcement in highway base courses, creating specification-driven demand pull that favors engineered polymer architectures over conventional aggregate stabilization methods.
Growth Catalysts
- FHWA Infrastructure Investment and Jobs Act deployment:Federal highway funding is accelerating geosynthetic adoption in road reconstruction projects across Texas, California, and Florida where DOTs specify AASHTO M288-compliant geotextiles.
- EPA coal ash containment rules:Stricter liner specifications for coal combustion residual impoundments are expanding geomembrane procurement volumes in power generation and utility sectors.
- Polymer formulation science:High-density polyethylene and polypropylene grades are diverging into application-specific performance tiers, enabling engineered solutions for mining leach pads and waste containment.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene and polypropylene resin prices fluctuate with crude oil markets, compressing margin predictability for geomembrane and geotextile manufacturers.
- Supply concentration in Gulf Coast petrochemical corridor:Hurricane disruption risk concentrates resin supply vulnerability, with Texas and Louisiana facilities supplying majority of domestic polymer feedstock.
- Competing ground improvement methods:Deep soil mixing and jet grouting techniques substitute for geogrid reinforcement in certain foundation applications, limiting addressable project scope.
Strategic Opportunities
- Coastal resilience infrastructure:Army Corps of Engineers beach nourishment and levee projects in Florida and Louisiana are specifying geotextile tubes and containers for erosion control.
- PFAS containment mandates:State-level regulations in California and emerging federal rules are driving double-liner system upgrades at industrial facilities and airports.
- Geocell load support systems:Three-dimensional confinement technology is penetrating unpaved access road and rail yard applications where aggregate reduction delivers lifecycle cost advantages.
Industry Challenges
- Geotechnical engineering talent scarcity:Specialized design expertise for geosynthetic-integrated pavement and slope systems remains concentrated among aging practitioner pools, constraining project execution capacity.
- ASTM D35 certification timelines:Extended testing protocols for new polymer formulations delay product commercialization, particularly for high-temperature and chemical resistance grades.
- Legacy specification inertia:Municipal and county engineering departments maintain outdated design standards that exclude modern geogrid and geocell solutions from bid eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Geosynthetics Market |
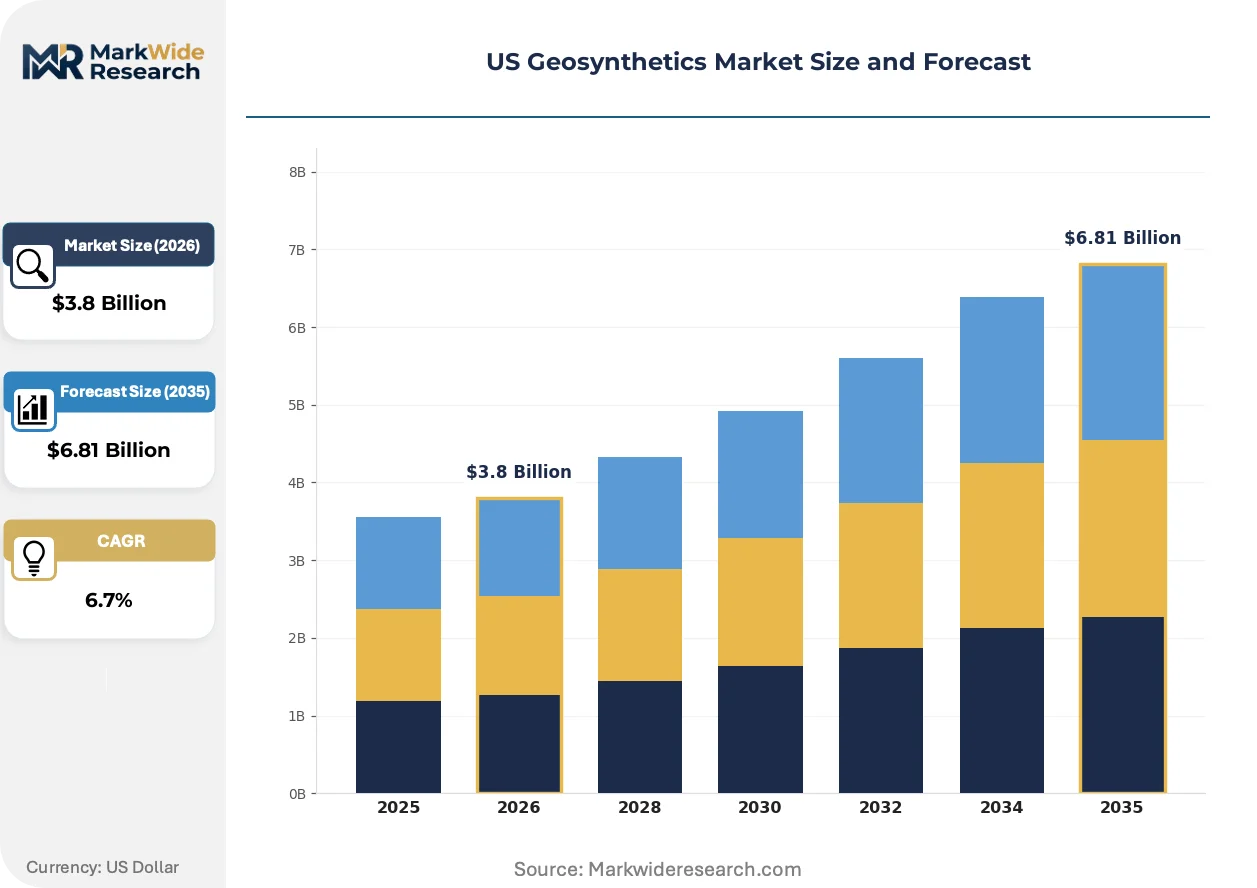
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geotextiles, Geonets, Geocells, Geomembranes Application: Drainage, Erosion Control, Stabilization, Landfill Liners End User: Construction, Environmental, Transportation, Agriculture Material: Polypropylene, Polyester, Polyethylene, Natural Fibers |
| Companies Covered | Advanced Drainage Systems, Inc., NAUE GmbH & Co. KG, Solmax International Inc., DuPont de Nemours Inc., Contech Engineered Solutions LLC, Tensar Corporation, Propex Operating Company LLC, Presto Geosystems, GSE Environmental, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Geosynthetics Market Emerging Trajectories
Digital design tools and predictive material modeling are compressing the specification-to-installation cycle, while regulatory tailwinds around environmental containment reshape product development priorities.
Multiaxial geogrid architectures are virtualizing traditional biaxial reinforcement designs by distributing loads across multiple axes rather than orthogonal directions. State DOTs in Texas and California are specifying these structures for high-traffic highway sections where rutting resistance is critical. The technology is virtualizing conventional aggregate base thickness requirements, reducing material haul volumes and construction carbon intensity.
EPA Subtitle D landfill regulations and emerging coal ash rules are tightening permeability specifications for geomembrane liners. Facility operators must now document seam integrity through electrical leak detection surveys, adding compliance cost but extending service life expectations. Mining and waste management sectors in Arizona and Nevada are responding by specifying thicker HDPE grades and alternative EPDM formulations.
Design-build procurement models are consolidating geosynthetic specification authority into contractor hands rather than owner-engineer relationships. Transportation and energy infrastructure projects in Florida and the Mountain West are seeing bundled material-procurement-installation contracts displace traditional bid-specify-award sequences. This shift concentrates volume with vertically integrated suppliers capable of engineering validation and field installation coordination.
US Geosynthetics Market Segmentation
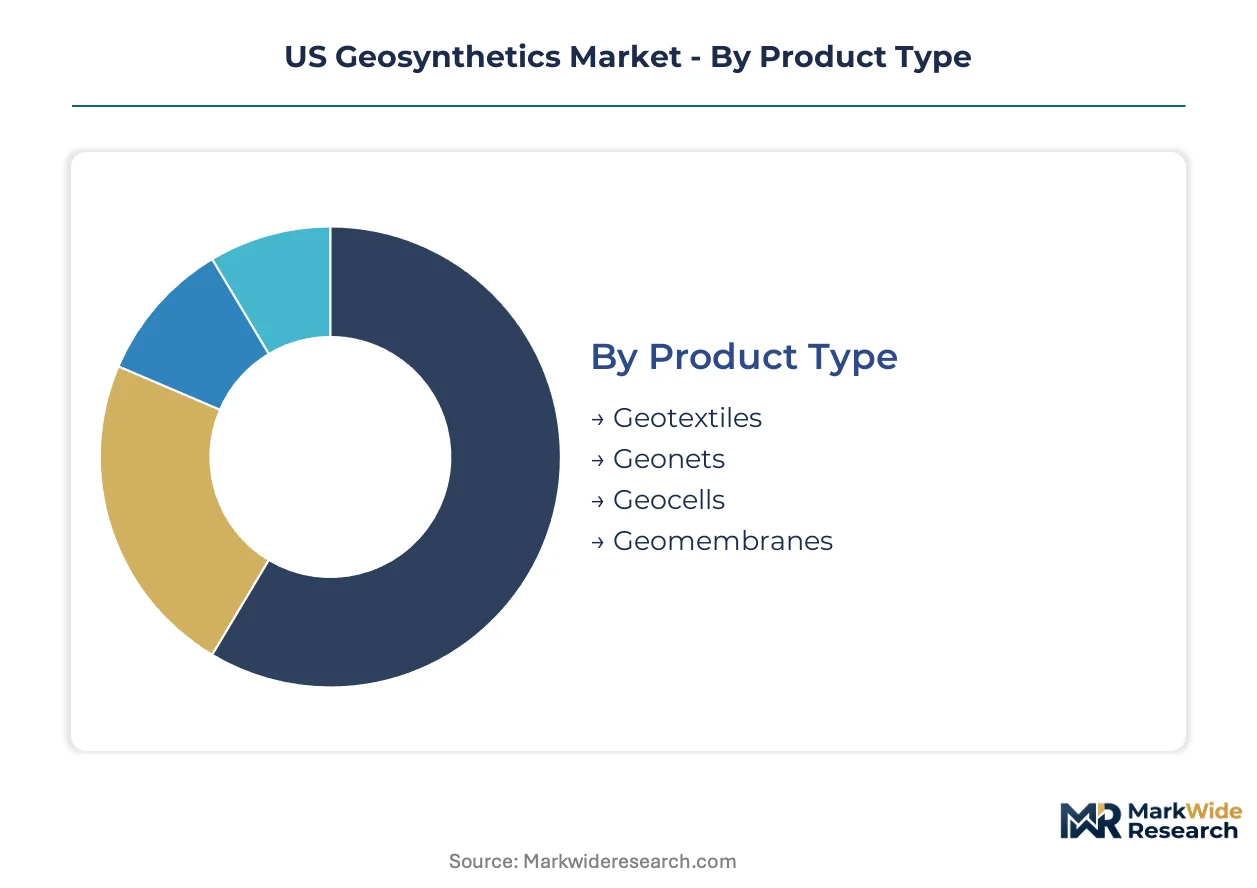
Segmentation in the US geosynthetics market reveals distinct procurement cycles and specification hierarchies that determine supplier positioning. Material chemistry and application criticality create divergent margin profiles across product categories, with infrastructure mandates reshaping volume distribution among end-use sectors.
Product Type:
Replacement cycles vary dramatically across product categories, with drainage and separation materials turning over fastest while containment systems operate on decade-long service horizons.
- Geomembranes:Impermeable HDPE, LLDPE, and EPDM sheets engineered for fluid containment. Demand concentrates in Texas and Florida where EPA coal ash rules and landfill expansion projects mandate double-liner systems with electrical leak detection compliance.
- Geotextiles:Woven and non-woven polypropylene or polyester fabrics providing separation, filtration, and reinforcement. State DOTs in California and Texas specify AASHTO M288-compliant grades for highway drainage and subgrade stabilization, driving consistent procurement volumes through federal infrastructure funding.
- Geocells:Three-dimensional honeycomb confinement systems manufactured from HDPE strips. Steep slope stabilization projects in Appalachian mining regions and coastal erosion control in Louisiana specify these for structural load distribution with reduced aggregate fill.
- Geonets:Bi-planar or tri-planar HDPE drainage cores with high flow capacity. Leachate collection layers in Subtitle D landfills and mining heap leach pads in Nevada and Arizona represent primary demand concentration.
Geotextiles anchor the volume base while geomembranes gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity drainage applications from engineered containment systems with certification-intensive procurement protocols.
- Landfill Liners:Composite barrier systems combining geomembranes with geosynthetic clay liners and geotextile protection layers. Stringent EPA permeability standards and state-level PFAS containment mandates in California are expanding specification complexity and material thickness requirements.
- Stabilization:Geogrid and geocell systems for soil reinforcement in road bases, embankments, and retaining walls. Texas DOT pavement design manuals now mandate geogrid inclusion in highway reconstruction projects, displacing conventional aggregate-only methods.
- Erosion Control:Geotextile tubes, containers, and turf reinforcement mats for shoreline protection and slope stabilization. Army Corps of Engineers beach nourishment projects in Florida and Louisiana specify high-strength woven containers for wave energy dissipation.
- Drainage:Geocomposite and geonet systems for subsurface water management. Commercial and residential construction across the Southeast deploys these for foundation protection and athletic field drainage.
Stabilization commands the largest project scale while landfill liners deliver the highest specification premiums.
End User:
Customer type determines contracting structure, with public infrastructure agencies favoring design-bid-build procurement and private mining operators preferring bundled performance contracts.
- Transportation:State DOTs and federal highway programs specifying geosynthetics for pavement preservation, bridge approaches, and embankment reinforcement. FHWA Infrastructure Investment and Jobs Act deployment is accelerating adoption in Texas, California, and Florida corridors.
- Environmental:Landfill operators, waste management firms, and remediation contractors requiring containment and capping systems. Emerging state-level PFAS regulations are driving liner upgrades at industrial facilities and airports.
- Construction:Residential, commercial, and industrial developers deploying drainage and erosion control materials. Subdivision development and warehouse construction in the Sun Belt generate consistent demand for geotextile and geocell applications.
- Agriculture:Irrigation canal lining, pond containment, and livestock waste management systems. California Central Valley water conservation projects and Florida nutrient management regulations shape regional specification patterns.
Transportation dominates public procurement volume while environmental applications carry the steepest regulatory compliance premiums.
Material:
Supply concentration along the Gulf Coast petrochemical corridor creates geographic vulnerability that shapes material selection and inventory strategies.
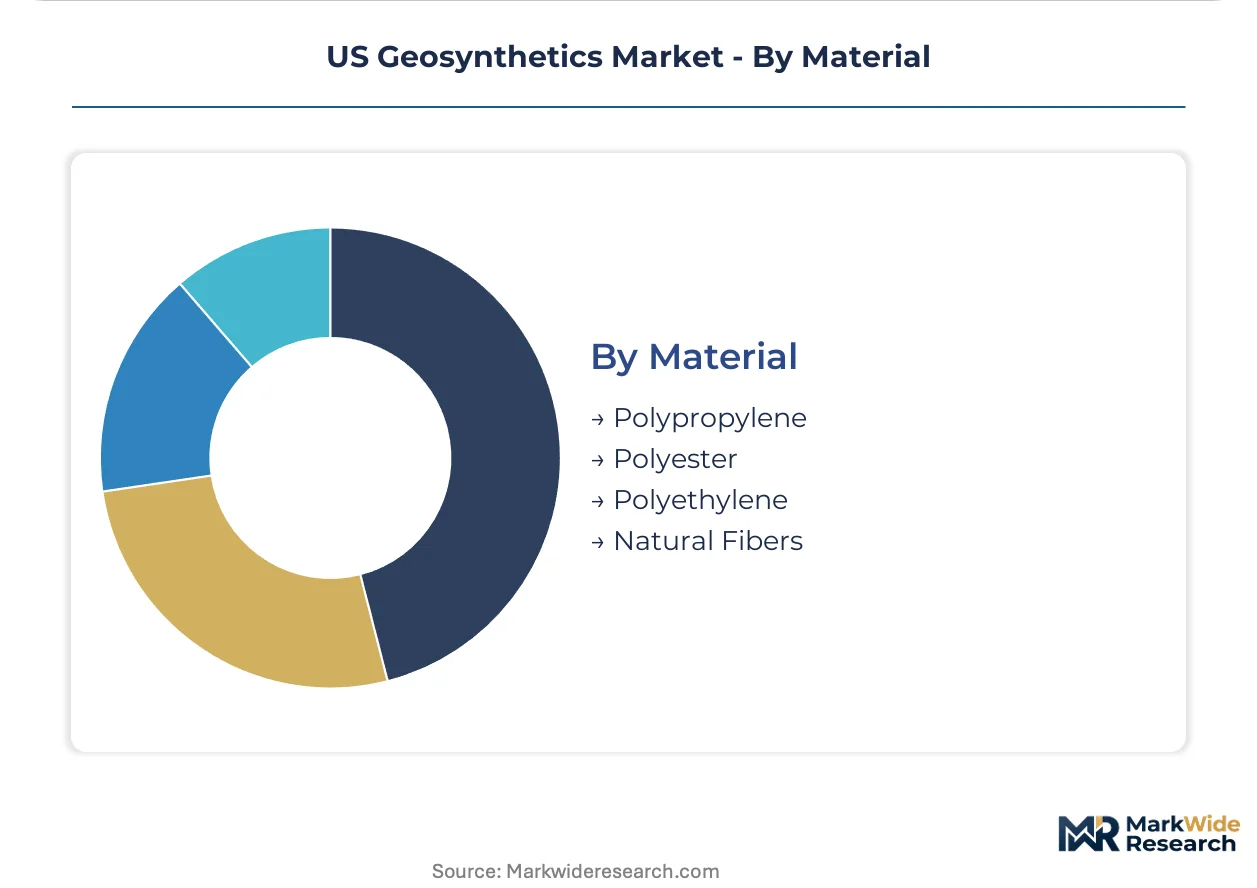
- Polyethylene:HDPE and LLDPE resins dominating geomembrane and geocell production. Mining leach pads in Arizona and Nevada specify high-density grades for chemical resistance and puncture tolerance.
- Polypropylene:Staple fiber and tape yarns for woven and non-woven geotextiles. Highway drainage applications favor polypropylene for its hydrophobic properties and installation durability.
- Polyester:High-tenacity filament yarns for geogrids and reinforcement geotextiles. Soil stabilization projects requiring creep resistance under sustained load specify PET-based architectures.
- Natural Fibers:Jute, coir, and wood fiber composites for temporary erosion control and biodegradable applications. Sensitive ecological restoration projects in coastal zones specify these for vegetation establishment periods.
Polyethylene and polypropylene together anchor supply volume while polyester gains traction in high-performance reinforcement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State DOT procurement offices and EPA regional administrators drive specification authority across the United States, with demand clustering where infrastructure spending intersects with environmental compliance mandates.
Texas
The Texas Department of Transportation mandates geogrid reinforcement in highway base courses through revised pavement design manuals, displacing conventional aggregate-only methods on federally funded reconstruction projects. EPA Region 6 enforces coal ash containment rules that expand geomembrane procurement for utility impoundments. The Gulf Coast petrochemical corridor around Houston and Beaumont concentrates HDPE resin supply for domestic geomembrane production.
California
Caltrans specifications incorporate AASHTO M288 geotextile classifications for drainage and subgrade stabilization across Interstate corridor maintenance programs. The State Water Resources Control Board enforces PFAS containment mandates that drive double-liner system upgrades at industrial facilities and airports. The Central Valley agricultural belt generates consistent demand for irrigation canal lining and livestock waste management systems.
Florida
The Florida Department of Transportation accelerates geosynthetic adoption in road reconstruction projects funded through federal infrastructure allocations. Army Corps of Engineers beach nourishment programs specify geotextile tubes and containers for coastal erosion control along the Atlantic and Gulf shorelines. The South Florida Water Management District deploys geosynthetics in levee and flood control infrastructure across the Everglades restoration footprint.
Arizona and Nevada
Mining operators in the Copper Belt and Gold Belt specify high-density polyethylene geomembranes for heap leach pads and process pond containment where chemical resistance and puncture tolerance are critical. EPA Region 9 enforces Subtitle D landfill regulations that thicken liner specifications for waste facilities serving Phoenix and Las Vegas metropolitan areas. The Intermountain West corridor concentrates mining sector demand that anchors specialized geomembrane procurement cycles.
Louisiana
The Coastal Protection and Restoration Authority specifies geotextile containers and tubes for marsh creation and shoreline stabilization projects across the Mississippi River Delta. EPA Region 6 oversight of petrochemical facility containment drives geomembrane upgrades at refinery and chemical plant sites along the Mississippi River corridor. The Baton Rouge-New Orleans industrial axis generates demand for heavy-duty containment systems serving process water and stormwater management applications.
US Geosynthetics Market Vendor Landscape
Channel-controlling players compete with product-specialist players across specification-driven procurement cycles, creating a tiered structure where scale advantages separate from technical differentiation. The vendor base clusters around three strategic archetypes: integrated polymer producers with captive resin supply, specialized geosynthetic fabricators with installation capabilities, and regional distributors with local specification relationships. Dominant competitive moves include backward integration into polymer compounding operations and strategic partnerships with engineering firms for design-build project bundling.
Among North American integrated players, Advanced Drainage Systems, Inc. and Contech Engineered Solutions LLC occupy positions that exemplify channel control through distribution network density. Solmax International Inc. and Tensar Corporation represent the specialization archetype, with the former anchoring containment-focused positioning and the latter reinforcing soil stabilization expertise. DuPont de Nemours Inc. sits within the materials science tier, leveraging polymer R&D infrastructure that feeds across multiple product categories.
| Leading Market Players |
|---|
| Advanced Drainage Systems, Inc. |
| NAUE GmbH & Co. KG |
| Solmax International Inc. |
| DuPont de Nemours Inc. |
| Contech Engineered Solutions LLC |
| Tensar Corporation |
| Propex Operating Company LLC |
| Presto Geosystems |
| GSE Environmental |
| Others |
Supply Flow & Price Mechanics
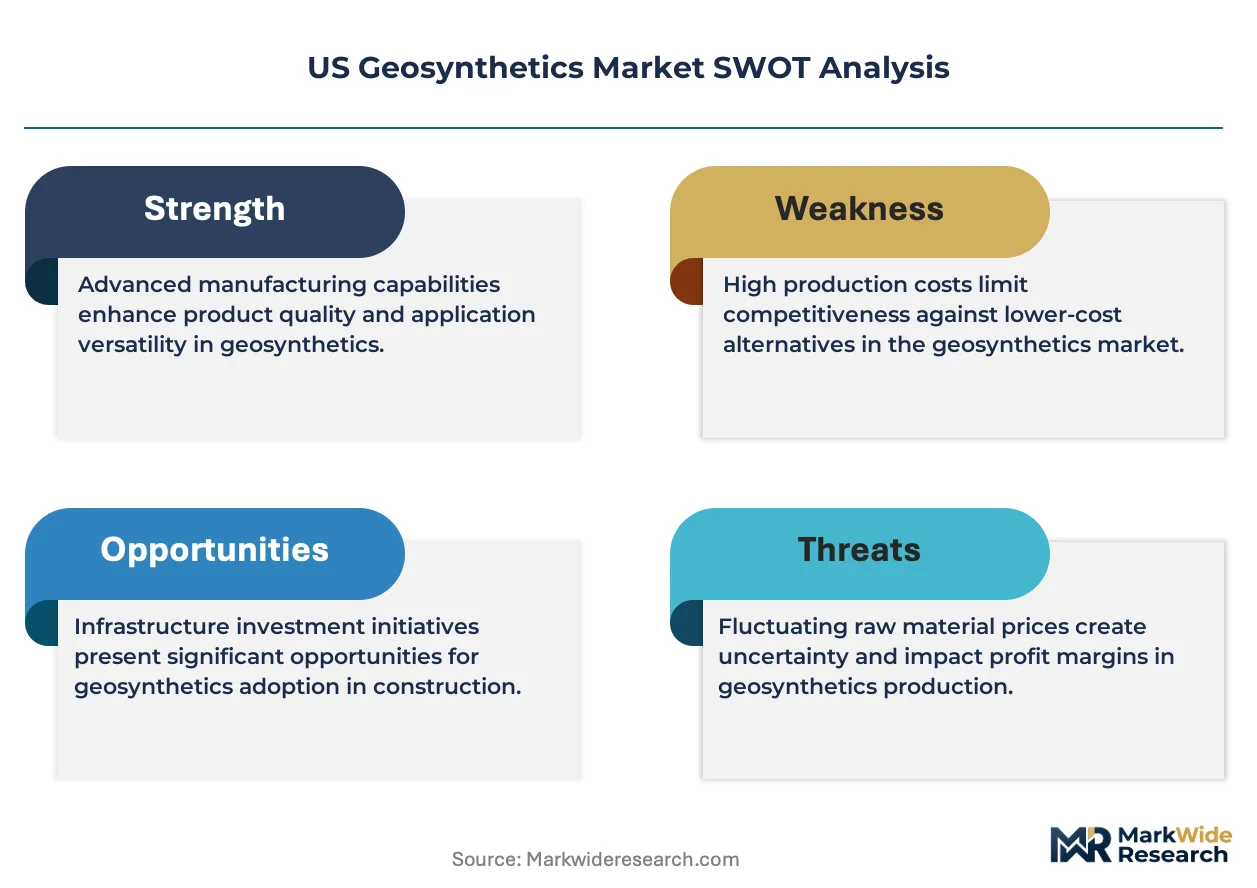
Gulf Coast petrochemical corridor concentration in Texas and Louisiana anchors resin cost volatility, pushing margin pools toward specification-compliant fabricators with captive polymer supply or long-term indexation contracts.
Pricing Analysis
Cost-plus contracts with polyethylene and polypropylene resin indexation dominate procurement between geomembrane fabricators and utility operators. Three-tier pricing structure across premium certification-grade, standard AASHTO M288-compliant, and economy drainage tiers separates qualified suppliers from commodity competitors. Pricing pressure stems from hurricane-driven feedstock disruption in the Gulf Coast corridor. Municipal DOTs exhibit highest price sensitivity while mining operators prioritize chemical resistance over unit cost.
Supply Chain Analysis
Tariff exposure between US resin producers and Asian specialty additive suppliers dominates supply chain risk planning for multiaxial geogrid manufacturers. HDPE and LLDPE resin production concentrates in Texas, Louisiana, and Ohio River Valley petrochemical complexes. Raw material sourcing draws from ethane feedstock cracking, carbon black reinforcement, and UV stabilizer additive streams. Single-source vulnerability sits with Gulf Coast hurricane disruption. Distribution runs through regional stocking yards serving state DOT procurement offices and design-build contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US geosynthetics market functions as a defensive-moat arena where AASHTO M288 certification entrenchment creates switching costs that lock out unqualified suppliers from state transportation procurement cycles.
For Market Incumbents: Build specification-lock moats through accelerated ASTM D35 certification pipelines for high-temperature polymer grades. Deepen backward integration into HDPE compounding operations in Ohio River Valley to offset Gulf Coast concentration risk. Threat vector: geocell substitution in unpaved road applications. Lever: captive resin supply. For New Entrants and Emerging Players: Build out installation-engineering capabilities to capture design-build procurement consolidation in Florida and Mountain West corridors. White-space targets: PFAS double-liner retrofits at California industrial facilities and Army Corps geotextile tube deployments for Louisiana coastal restoration. Go-to-market angle: bundled material-validation-field service contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across geomembrane fabrication as electrical leak detection compliance and thicker HDPE specifications raise equipment thresholds. Long-term viability favors vertically integrated players with polymer R&D infrastructure. Acquisition target archetype: regional fabricators with state DOT specification relationships and untapped geocell production capacity. Signal to monitor: FHWA pavement manual revisions mandating geogrid inclusion in additional state jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive HDPE supply insulates margin from Gulf Coast hurricane volatility. |
| ASTM D35 Certification Acceleration | Fast-tracked high-temperature grades unlock mining leach pad contracts in Nevada. |
| Design-Build Bundling Capability | Integrated engineering-validation-installation captures Florida DOT procurement consolidation. |
| Geocell Load Support Expansion | Three-dimensional confinement penetrates rail yard aggregate reduction applications. |
| PFAS Double-Liner Retrofit Positioning | California State Water Board mandates drive industrial facility containment upgrades. |
Methodological Framework
Operator-level perspectives from state DOT materials engineers, geomembrane fabrication plant managers, mining heap leach pad operators, and environmental containment contractors anchored the qualitative base. Primary fieldwork combined with secondary validation through FHWA specification databases, EPA coal ash rule filings, AASHTO M288 compliance registries, and SEC 10-K disclosures from listed polymer producers. Bottom-up project pipeline enumeration triangulated against top-down resin consumption estimates from Gulf Coast petrochemical reporting.
Scenario-bracketing around infrastructure funding deployment rates and regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application criticality, end-user procurement structure, and regional specification cluster. CAGRs derived from polymer consumption elasticity to highway construction indices and landfill expansion permitting velocity. Industry-specific forecast inputs incorporated electrical leak detection compliance cost trajectories and geogrid pavement design manual adoption curves.
Practitioners should monitor FHWA funding allocation shifts, EPA PFAS rule finalization timelines, and Gulf Coast hurricane season severity for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Hydraulic Door Closer Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
Risers Market
Building & Construction Materials
Concrete Sealer Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Insulated Metal Panels Market
Building & Construction Materials
Basalt Fiber Reinforced Polymer BFRP Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
UPVC Doors and Windows Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Asia-Pacific Gypsum Board Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Europe Gypsum Board Market