
 Porcelain Tiles Market | 2026-2036
Porcelain Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Porcelain Tiles Market Analytics
Italian kiln operators is realigning output toward large-format slabs as energy costs reshape batch economics. Mohawk Industries leverages North American distribution density to sustain premium positioning in the residential channel. RAK Ceramics anchors Middle Eastern supply through integrated clay-to-distribution operations across the UAE. Kajaria Ceramics dominates India's northern states with dedicated capacity for polished and glazed variants.
Porcelain tiles are vitrified ceramic products fired above 1200°C, achieving water absorption below 0.5% and Mohs hardness ratings of 7-8, making them suitable for heavy-traffic flooring and exterior cladding in freeze-thaw climates. Glazed and polished variants command the dominant revenue share in residential flooring, while matte finishes are displacing natural stone in commercial wall cladding across hospitality retrofits. The countertops application segment records the fastest expansion as thin large-format slabs penetrate kitchen and bathroom surfaces previously served by quartz and granite.
ISO 13006 classification governs dimensional tolerances and breaking strength thresholds for international trade, while CE marking under the EU Construction Products Regulation mandates fire reaction and slip resistance declarations for European market access. India's BIS certification enforces IS 15622 standards for water absorption and flexural strength on domestic producers and importers alike. Stakeholders must track evolving EPD requirements and embodied carbon disclosures as green building codes tighten procurement specifications across major construction markets.
Market Dynamics
Digital inkjet printing is decentralizing production economics across ceramic manufacturing clusters, allowing smaller batch runs and faster design turnover while compressing the capital requirements that once favored massive rotary press installations.
Growth Catalysts
- Urban migration across Southeast Asia:Residential construction in Vietnam, Indonesia, and the Philippines absorbs rising tile volumes as infrastructure budgets expand fastest in these markets.
- ISO 13006 classification harmonization:Dimensional tolerance and breaking strength standards reduce technical barriers to cross-border trade and simplify specification for international projects.
- Thin large-format slab technology:Countertop applications previously served by quartz and granite now represent an expanding addressable surface for porcelain producers.
Market Restraints
- Natural gas price volatility:Kiln operations above 1200°C require sustained thermal input; European energy costs have reshaped batch economics for Italian operators.
- Clay deposit concentration:Integrated clay-to-distribution operations in the UAE and select Gulf states create geographic supply dependencies for import-dependent markets.
- Ceramic tile substitution in budget residential:Lower-fired ceramic alternatives compete on upfront cost in price-sensitive housing segments across emerging markets.
Strategic Opportunities
- Freeze-thaw exterior cladding in North American retrofits:Mohs hardness ratings of 7-8 and sub-0.5% water absorption position porcelain to displace natural stone in commercial facade renovations.
- EPD and embodied carbon procurement mandates:Green building codes tightening across major construction markets create specification advantages for producers with verified environmental product declarations.
- Matte finish hospitality specification:Commercial wall cladding across hotel retrofits is shifting preference from polished surfaces toward textured, low-glare alternatives.
Industry Challenges
- Digital press technician scarcity:Conventional rotary press expertise does not transfer to inkjet system calibration and color management, creating workforce gaps in manufacturing clusters.
- BIS certification timeline compression:India's IS 15622 enforcement for water absorption and flexural strength requires testing coordination that delays market entry for new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Porcelain Tiles Market |
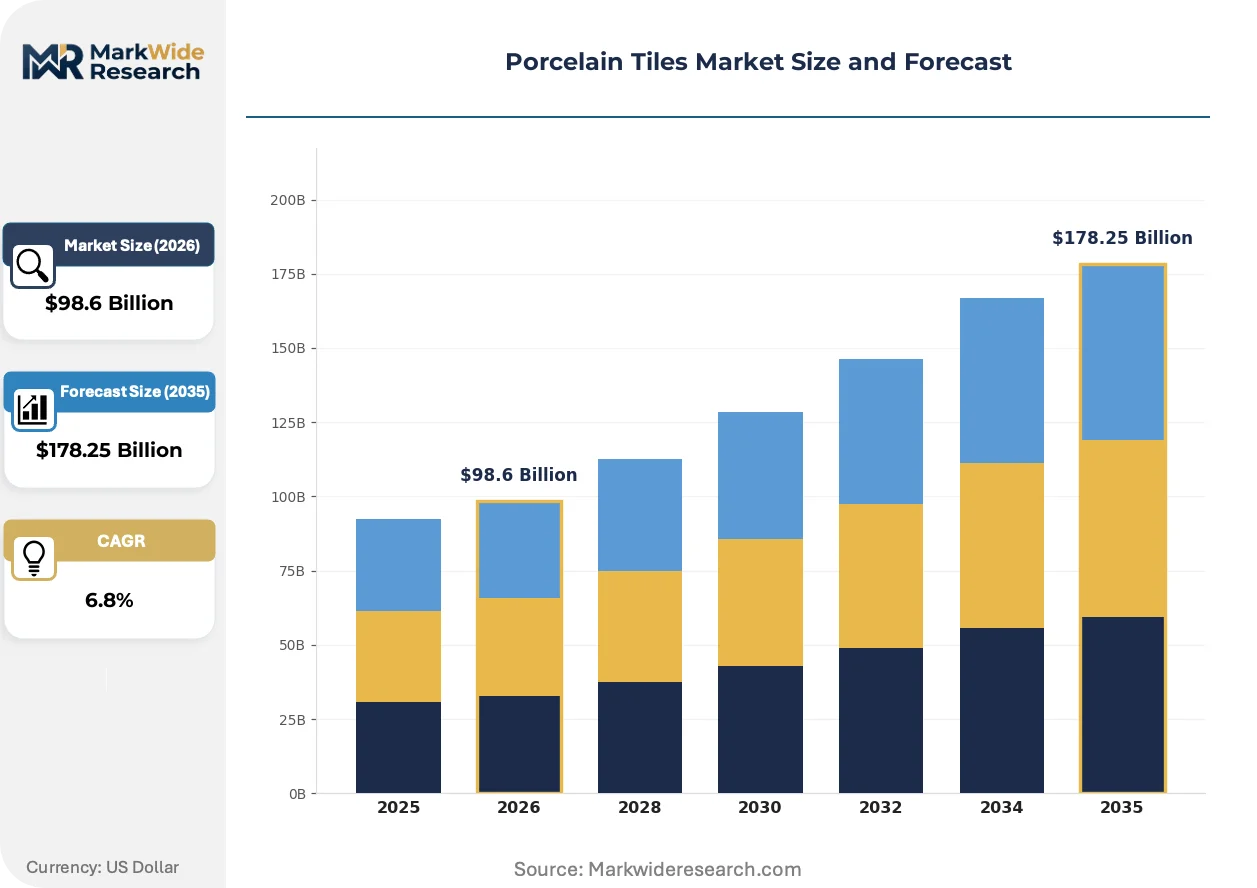
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed, Unglazed, Polished, Matte End User: Residential, Commercial, Industrial, Hospitality Application: Flooring, Wall Cladding, Countertops, Bathroom Fixtures Design Style: Traditional, Modern, Rustic, Contemporary |
| Companies Covered | Mohawk Industries, RAK Ceramics, Kajaria Ceramics, Porcelanosa Grupo, Atlas Concorde, Grupo Lamosa, SCG Ceramics, Crossville, Florim Ceramiche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Porcelain Tiles Market Evolving Landscape
Production technology and procurement specifications are converging to reshape competitive advantage, with automation and sustainability credentials now determining specification access rather than scale alone.
Digital inkjet printing is decentralizing design-to-production workflows by enabling direct image transfer without screen engraving, allowing hospitality and retail clients to commission custom runs as small as 500 square meters. Boutique hotel chains in Italy and Spain are adopting this capability for property-specific interior schemes. The technology is compressing minimum efficient scale and fragmenting the supplier base that once dominated through rotary press volume.
EU Construction Products Regulation CE marking mandates now require fire reaction and slip resistance declarations for all European market access, with notified bodies expanding testing capacity to address backlog. Italian and Spanish exporters have reorganized quality documentation to maintain specification eligibility. The regulation most affects polished glazed variants where surface treatment alters slip performance characteristics.
Architects and interior designers are consolidating specification authority previously dispersed among contractors and distributors, with large-format slab selection now occurring at schematic design phase rather than finish selection. Design firms in Milan and Barcelona are establishing direct supplier relationships that bypass traditional distribution. This pattern is most visible in premium residential and boutique commercial verticals where surface aesthetics drive project identity.
Porcelain Tiles Market Segmentation
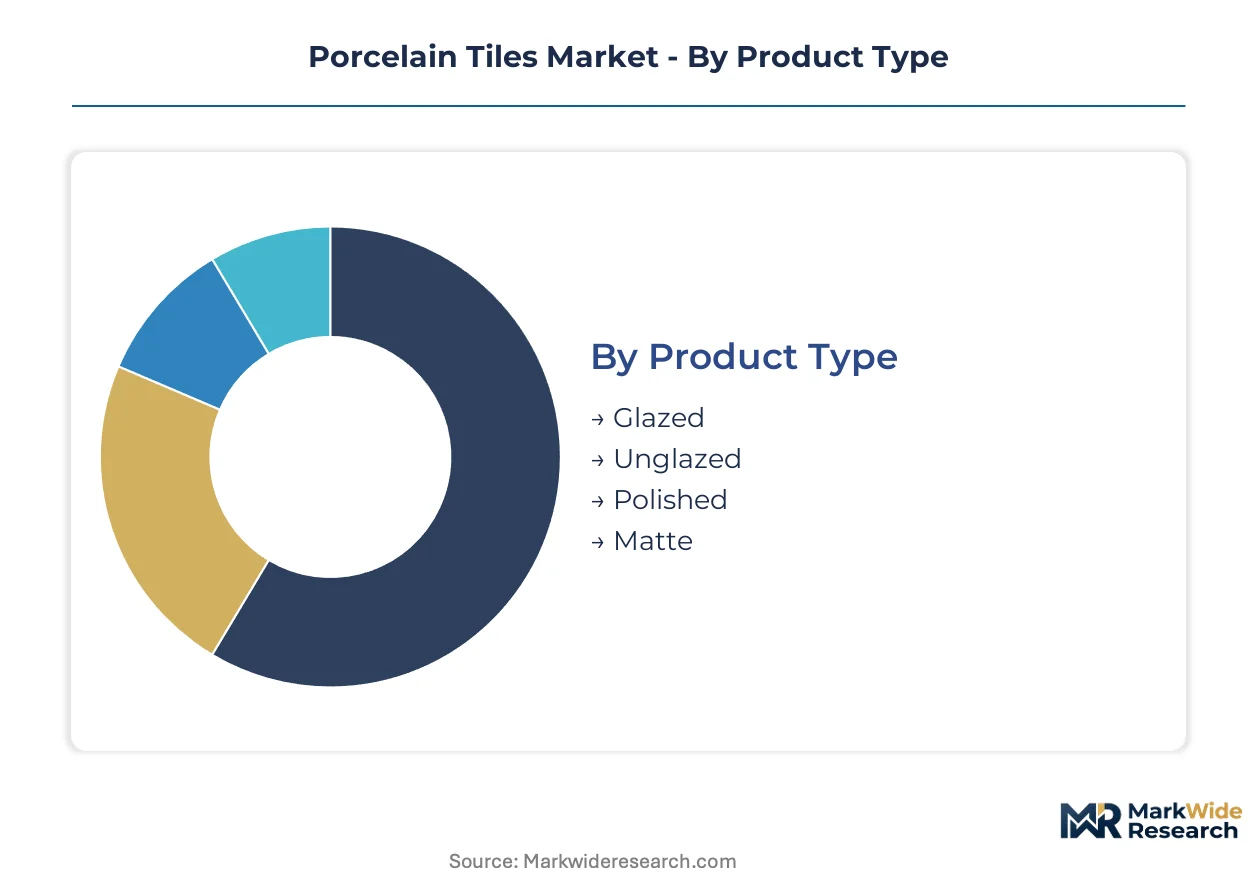
Porcelain tile specification diverges sharply by installation context and surface performance requirements. Manufacturers configure kiln cycles and glaze formulations to match distinct end-use durability thresholds rather than pursuing universal product lines.
Product Type:
Glazed variants function as standalone surface solutions with protective glass layers fused during firing, while unglazed and polished formats embed structural performance directly into the vitrified body.
- Glazed:A glass-based coating fused at high temperature creates stain-resistant, color-stable surfaces. Residential flooring across Vietnam and Indonesia absorbs the largest volumes as urban housing stock expands and finish specifications tighten.
- Polished:Mechanical grinding after firing yields mirror-finish surfaces with Mohs hardness of 7-8 but requires sealant maintenance. Commercial lobby and retail installations in the UAE specify these for premium aesthetic impact despite slip resistance trade-offs.
- Unglazed:Through-body color consistency suits heavy-traffic industrial flooring where surface wear would expose contrasting substrate. Manufacturing facilities across India's northern states specify these for abrasion resistance.
- Matte:Controlled surface roughness achieves R10-R11 slip ratings without glaze layers. Hospitality wall cladding in Spain and Italy is shifting toward these low-glare alternatives for guest room and corridor applications.
Glazed tiles lead volumes today; matte finishes are gaining share fastest.
End User:
Cost tier stratification separates specification authority and procurement channel across user categories.
- Residential:Single-family and multi-family housing dominates absolute consumption. Southeast Asian urban migration—particularly in the Philippines—drives volume absorption as infrastructure budgets channel into mass housing.
- Commercial:Office, retail, and institutional projects specify large-format slabs for accelerated installation. CE marking under EU Construction Products Regulation mandates fire reaction declarations for European commercial access.
- Hospitality:Boutique hotel chains in Milan and Barcelona commission custom digital inkjet runs as small as 500 square meters for property-specific interior schemes. Design firms now specify directly, bypassing traditional distribution.
- Industrial:Chemical resistance and load-bearing capacity prioritize unglazed through-body products. Food processing and pharmaceutical facilities enforce ISO 13006 breaking strength thresholds for safety compliance.
Residential construction anchors volume; hospitality is climbing the fastest.
Application:
Volume concentration versus margin opportunity splits across surface installation types.
- Flooring:The foundational use case spans all hardness ratings and slip classifications. Residential and commercial builders in Indonesia and Vietnam specify these for durability in high-humidity climates.
- Wall Cladding:Reduced thickness requirements enable lighter substrate systems. Matte finishes are displacing natural stone across European hospitality retrofits as EPD and embodied carbon procurement mandates tighten.
- Countertops:Thin large-format slabs—often 6-12mm thickness—penetrate kitchen and bathroom surfaces previously served by quartz and granite. This segment shows steepest expansion trajectory as fabrication techniques mature.
- Bathroom Fixtures:Integrated shower panels and vanity surfaces demand water absorption below 0.5% for freeze-thaw resistance. North American retrofits increasingly specify these for exterior cladding durability.
Flooring commands current volume; countertops show steepest expansion trajectory.
Design Style:
Production batch economics and digital press capability determine which aesthetic categories sustain viable manufacturing.
- Modern:Clean lines and minimal texture dominate new construction specification. Digital inkjet printing enables rapid design turnover without rotary press screen engraving costs.
- Contemporary:Evolving interpretations of current trends require flexible production. Italian kiln operators realign output toward these large-format slabs as energy costs reshape batch economics.
- Traditional:Classic patterns with established color palettes suit restoration and heritage projects. Rotary press volume still serves this segment where design stability justifies capital investment.
- Rustic:Textured surfaces mimicking natural stone or terracotta require specialized glaze formulation. Smaller manufacturing clusters pursue this niche where digital press technician scarcity limits complex production.
Modern styling leads specification volume; contemporary designs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting production investment toward jurisdictions where energy costs, certification timelines, and environmental compliance create measurable cost-of-compliance gaps. Manufacturers are relocating kiln capacity to exploit these divergences.
China
Urban renovation programs in Guangdong and Fujian provinces sustain domestic absorption of polished and glazed variants. GB standards for ceramic tile water absorption and flexural strength govern domestic trade and export qualification. The Foshan manufacturing cluster anchors output realignment toward large-format slabs as energy efficiency mandates tighten kiln economics.
Italy
Boutique hospitality projects across Lombardy and Emilia-Romagna commission custom digital inkjet runs for property-specific interior schemes. CE marking under the EU Construction Products Regulation mandates fire reaction and slip resistance declarations for all European market access. Sassuolo-based kiln operators are consolidating output toward premium large-format production as natural gas price volatility reshapes batch economics.
India
Mass housing construction in Maharashtra and Gujarat absorbs rising volumes of polished and glazed residential flooring. BIS certification enforces IS 15622 standards for water absorption and flexural strength on domestic producers and importers alike. Morbi in Gujarat anchors integrated clay-to-distribution operations serving northern state markets with dedicated capacity for vitrified variants.
Vietnam
Urban migration into Ho Chi Minh City and Hanoi corridors drives residential construction specification for humidity-resistant flooring. The country's national construction standards regulator enforces dimensional tolerance and breaking strength thresholds for building materials procurement. Northern manufacturing zones near Hanoi are attracting kiln investment from regional producers seeking lower energy input costs.
United States
Commercial facade renovation projects across Sun Belt metros specify freeze-thaw resistant exterior cladding for durability in variable climates. EPA and OSHA regulations govern kiln emissions and workplace safety in domestic manufacturing facilities. Tennessee and Georgia distribution hubs are consolidating import volumes from Asian and European sources for residential channel penetration.
Porcelain Tiles Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue thin large-format slab specialization and digital inkjet customization services. The vendor base clusters around three strategic archetypes: integrated clay-to-distribution operators with captive raw material access, design-forward specialists commanding premium specification through architect relationships, and scale-driven manufacturers optimizing rotary press throughput for commodity residential volumes. Competitive moves concentrate on M&A for geographic footprint expansion and technology licensing agreements for digital press capability acquisition.
Among North American fabricators, Mohawk Industries occupies a position exemplifying distribution density advantages in residential channel penetration. RAK Ceramics anchors the integrated operator archetype with UAE-based clay-to-distribution control. Kajaria Ceramics represents the regional scale specialist model with concentrated capacity serving India's northern state markets. These three exemplars illustrate how competitive positioning fragments across geographic specialization, vertical integration depth, and specification channel access rather than converging on uniform scale metrics.
| Leading Market Players |
|---|
| Mohawk Industries |
| RAK Ceramics |
| Kajaria Ceramics |
| Porcelanosa Grupo |
| Atlas Concorde |
| Grupo Lamosa |
| SCG Ceramics |
| Crossville |
| Florim Ceramiche |
| Others |
Value Network & Pricing Analysis
Natural gas input costs cascade through Italian kiln operations into premium large-format slab pricing tiers, while Southeast Asian producers leverage lower thermal energy expenditures to undercut standard-grade exports into residential channels.
Pricing Analysis
Distributor margins compress the effective factory-gate realization for export-bound polished variants by 18-25 percentage points before retail placement. Pricing stratifies across premium, standard, and economy tiers based on Mohs hardness certification and slip resistance ratings under ISO 13006. Cost compression in the standard-grade segment is intensifying as Morbi-based producers expand glazed residential flooring capacity. Budget residential builders exhibit highest price sensitivity, while boutique hospitality specifiers absorb premiums for custom digital inkjet runs.
Supply Chain Analysis
Single-source vulnerability sits with Sassuolo-based kiln operators dependent on Algerian pipeline gas for sustained 1200°C firing cycles. Manufacturing gravity centers on Italy, China, and India, with each cluster drawing from distinct clay deposit geologies. Kaolin, feldspar, and silica sand constitute critical mineral inputs subject to freight cost volatility. Tariff exposure on finished tile imports into North America creates margin pressure for European exporters. Distribution runs through Tennessee and Georgia consolidation hubs serving residential contractors across Sun Belt metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CE marking under the EU Construction Products Regulation operates as a regulatory compounder, mandating fire reaction and slip resistance declarations that filter specification access and consolidate procurement authority among certified producers.
For Market Incumbents: Extend large-format slab capacity in Vietnam and Indonesia to capture urban migration-driven residential volume before local kiln investment matures. Deepen captive clay deposit control in Gujarat to insulate margin structure against raw material freight inflation. Certification investment in EPD documentation secures green building code specification advantages as procurement mandates tighten.
For New Entrants and Emerging Players: Digital inkjet customization capability offers a technology-first wedge into boutique hospitality specification previously locked by Sassuolo design relationships. Target matte-finish wall cladding for European hotel retrofits where architect-direct procurement bypasses established distribution. Pursue thin-slab countertop fabrication partnerships with North American kitchen installers as the fastest-expanding application segment.
For Investors and Strategic Acquirers: Consolidation pressure builds where digital press technician scarcity fragments production quality across smaller manufacturing clusters. Five-to-ten-year viability favors integrated clay-to-distribution operators with captive energy hedging or geographic arbitrage on thermal input costs. Monitor BIS certification timeline compression in India as an inflection signal for import-dependent market entry difficulty.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Press Technology Licensing | Inkjet system acquisition enables batch-size compression for hospitality customization without rotary press capital. |
| Backward Integration into Clay Mining | Captive kaolin and feldspar supply insulates Morbi-based producers against mineral freight volatility. |
| EPD Certification Program | Verified environmental product declarations unlock green building code specification across EU and North American commercial projects. |
| Regional Kiln Capacity Expansion | Hanoi-adjacent manufacturing zones exploit lower Vietnamese energy tariffs versus European natural gas exposure. |
| Architect-Direct Distribution Partnership | Milan and Barcelona design firm relationships bypass traditional tile distributor markups in premium residential verticals. |
Research Methodology
Bottom-up residential and commercial construction modeling reconciled against top-down kiln capacity and trade flow tracking forms the analytical core. Primary interviews with plant managers at Foshan and Morbi manufacturing clusters, procurement leads at UAE distribution operations, and specification directors at Milan design firms combined with secondary validation against customs records, BIS certification registries, and EU Construction Products Regulation notified body disclosures. Trade data from Vietnam's national construction standards regulator and SEC filings from North American building materials distributors anchored supply-side triangulation.
Input-output matrices map product type, end-user category, application surface, and design style against geographic production hub and regulatory compliance tier across the projection horizon. CAGRs derive from segment-level volume elasticities to construction spending and specification substitution patterns. Forecast inputs incorporate natural gas price scenarios for European kiln economics and urban migration projections for Southeast Asian residential absorption.
The model holds under stable regulatory enforcement timelines and energy cost trajectories; deviation in BIS certification compression or EU carbon border adjustment implementation would shift capacity relocation patterns and margin distribution. Forecasts embed assumptions about digital press adoption rates and architect procurement authority consolidation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Geosynthetics Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market
Building & Construction Materials
Lightweight Composite External Access Panels and Doors Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
North America Cast-In-Place Concrete Flooring Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
Asia-Pacific Ready-Mix Concrete Market
Building & Construction Materials
Asia Pacific Sanitaryware Market