
 Global Electric Portable Drill Market | 2026-2036
Global Electric Portable Drill Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Portable Drill Market Analysis
Chinese power tool manufacturing clusters is recalibrating global supply dynamics as domestic producers expand brushless motor capacity and lithium-ion battery integration. Robert Bosch GmbH leverages its Stuttgart engineering base to sustain premium positioning across European professional channels. Makita Corporation anchors its competitive stance through deep cordless platform ecosystems and battery interchangeability across tool categories. Stanley Black & Decker competes through multi-brand portfolio architecture spanning DeWalt professional lines and consumer-facing sub-labels.
An electric portable drill is a handheld motor-driven device engineered to create cylindrical holes in substrates via rotary cutting action, typically employing brushed or brushless DC motors rated between 12V and 60V with chuck capacities from 10mm to 16mm for industrial applications. The tool serves construction trades, manufacturing assembly, and residential maintenance by converting electrical energy into controlled mechanical torque for material penetration and fastener driving. Cordless drills occupy the dominant volume position due to lithium-ion energy density improvements that now match corded performance in medium-duty applications. Hammer drills represent the fastest-expanding product type as masonry-intensive construction spreads across emerging urban corridors. Impact drills command premium pricing in automotive assembly where repetitive torque precision reduces operator fatigue and fastener damage.
The EU F-Gas Regulation and REACH compliance frameworks constrain refrigerant-based cooling systems in battery charging infrastructure, indirectly shaping cordless platform design requirements for European market access. The US OSHA electrical safety standards and FCC electromagnetic emission rules govern motor shielding and charger certification for North American distribution. China's GB standards and MIIT energy efficiency directives set mandatory thresholds for motor performance and standby power consumption in domestic manufacturing. Stakeholders must monitor regulatory divergence between jurisdictions as battery chemistry transitions and recycling mandates reshape product development cycles and aftermarket service obligations.
Market Dynamics
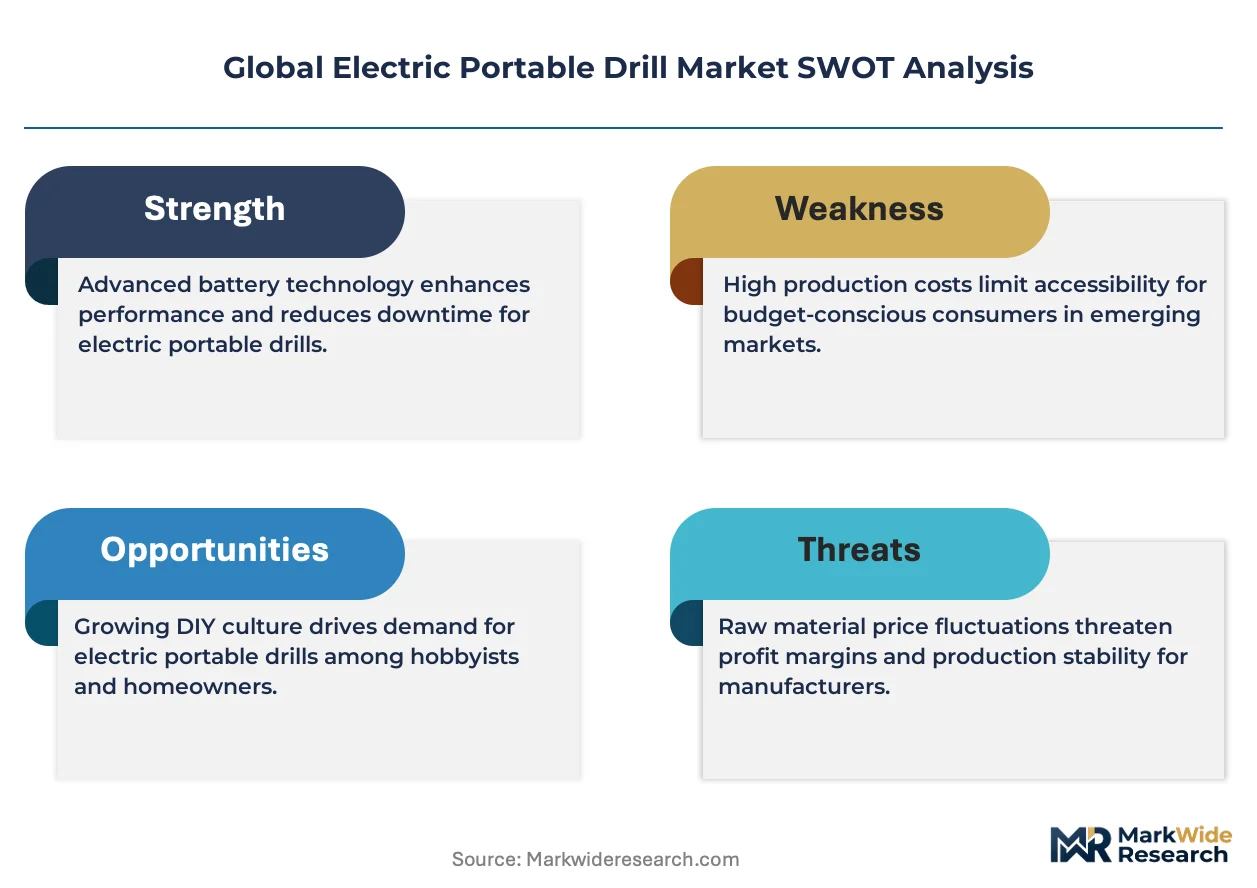
Brushless motor adoption is compressing product lifecycles across mid-tier cordless drill portfolios, forcing manufacturers to recalibrate R&D amortization and platform upgrade cadences.
Growth Catalysts
- Lithium-ion energy density thresholds:Cell chemistry improvements now enable 20V-class cordless drills to match corded torque output in medium-duty applications, eliminating cord dependency for residential renovation contractors.
- EU F-Gas Regulation:Cooling system constraints on battery charging infrastructure are accelerating passive thermal management designs in cordless platforms bound for European distribution.
- China infrastructure stimulus:State-directed construction investment is concentrating demand for hammer drill configurations in masonry-intensive commercial builds across tier-one and tier-two cities.
Market Restraints
- Rare earth magnet supply concentration:Neodymium procurement dependencies on Chinese processing capacity expose brushless motor producers to input cost volatility and export quota uncertainty.
- REACH substance restrictions:ECHA documentation burdens on cobalt-containing battery cathodes extend product registration timelines and compliance overhead for European market entry.
- Technical ceiling in cordless runtime:Thermal dissipation limits in compact drill housings constrain sustained high-torque operation, preserving corded tool relevance in heavy-duty metalworking.
Strategic Opportunities
- India residential electrification:Grid expansion in secondary cities is creating first-time power tool ownership among informal construction laborers previously dependent on manual methods.
- Battery platform interoperability:Cross-brand battery adapter ecosystems represent unclaimed white space as professional users seek to consolidate charger footprints across mixed-vendor tool parks.
- US Inflation Reduction Act:Domestic content incentives for battery cell manufacturing are reshaping sourcing calculus for brands assembling cordless platforms in North American facilities.
Industry Challenges
- Power electronics engineering scarcity:Motor control firmware and MOSFET thermal design expertise sits concentrated within automotive and aerospace talent pools, complicating drill OEM recruitment.
- Multi-jurisdiction certification timelines:Simultaneous FCC, CE, and GB standard compliance testing extends product launch windows by 8-14 months for global platform releases.
- Legacy brushed motor inventory obsolescence:Distributor stock rotation friction intensifies as retailers face write-down pressure on pre-brushless inventory during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Portable Drill Market |
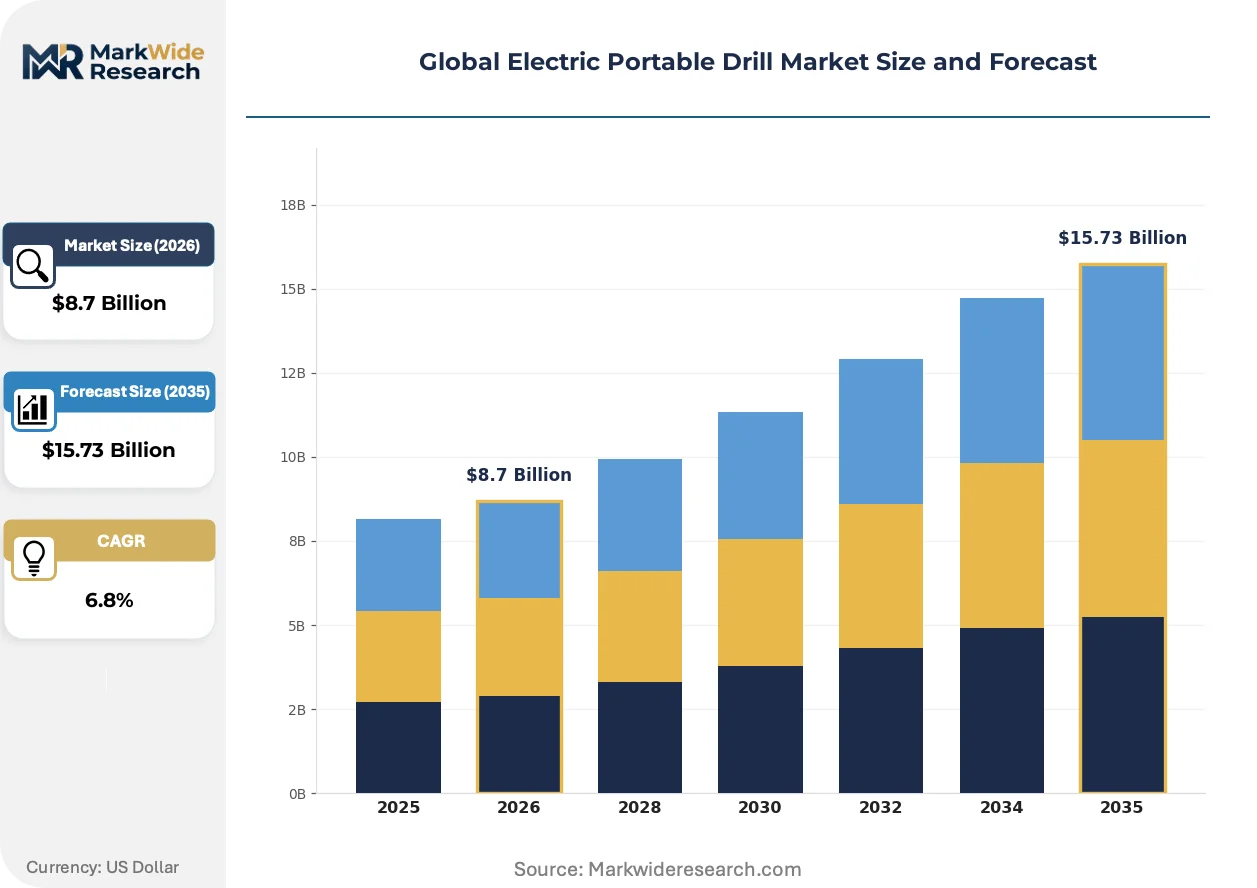
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless Drills, Hammer Drills, Impact Drills, Rotary Drills Power Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage End User: Construction, Manufacturing, DIY, Automotive Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Robert Bosch GmbH, Stanley Black & Decker, Makita Corporation, Techtronic Industries, Hilti Corporation, DeWalt, Hitachi Koki Co., Ltd., Panasonic Corporation, Milwaukee Electric Tool Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Portable Drill Market Emerging Trajectories
Product architecture is fragmenting into interoperable subsystems as battery platforms decouple from tool bodies, enabling subscription-like hardware refresh models and reducing total ownership cost stickiness.
Brushless DC motor control firmware is modularizing into discrete torque-profile libraries that end-users can reflash for material-specific applications. Professional contractors in Germany and Japan are adopting subscription-based motor calibration updates that extend tool versatility without hardware replacement. This architecture is compressing traditional product segmentation boundaries between drill categories.
China's MIIT energy efficiency directives are mandating standby power thresholds below 0.5W for cordless tool chargers, forcing redesign of vampire power circuits in products targeting domestic manufacturing compliance. Domestic producers are integrating active power-factor correction to meet these thresholds, creating divergence from export-oriented charger designs. European-bound SKUs are inheriting these efficiencies as manufacturing lines consolidate.
Buying patterns among North American residential renovators are fragmenting toward direct-to-consumer channels as specialized tool subscription services displace big-box retail for intermittent-use categories. These platforms bundle drill access with consumable replenishment and maintenance, capturing users with low utilization frequency. Similar models are penetrating Australian and UK markets through trade-specific vertical platforms.
Global Electric Portable Drill Market Segmentation
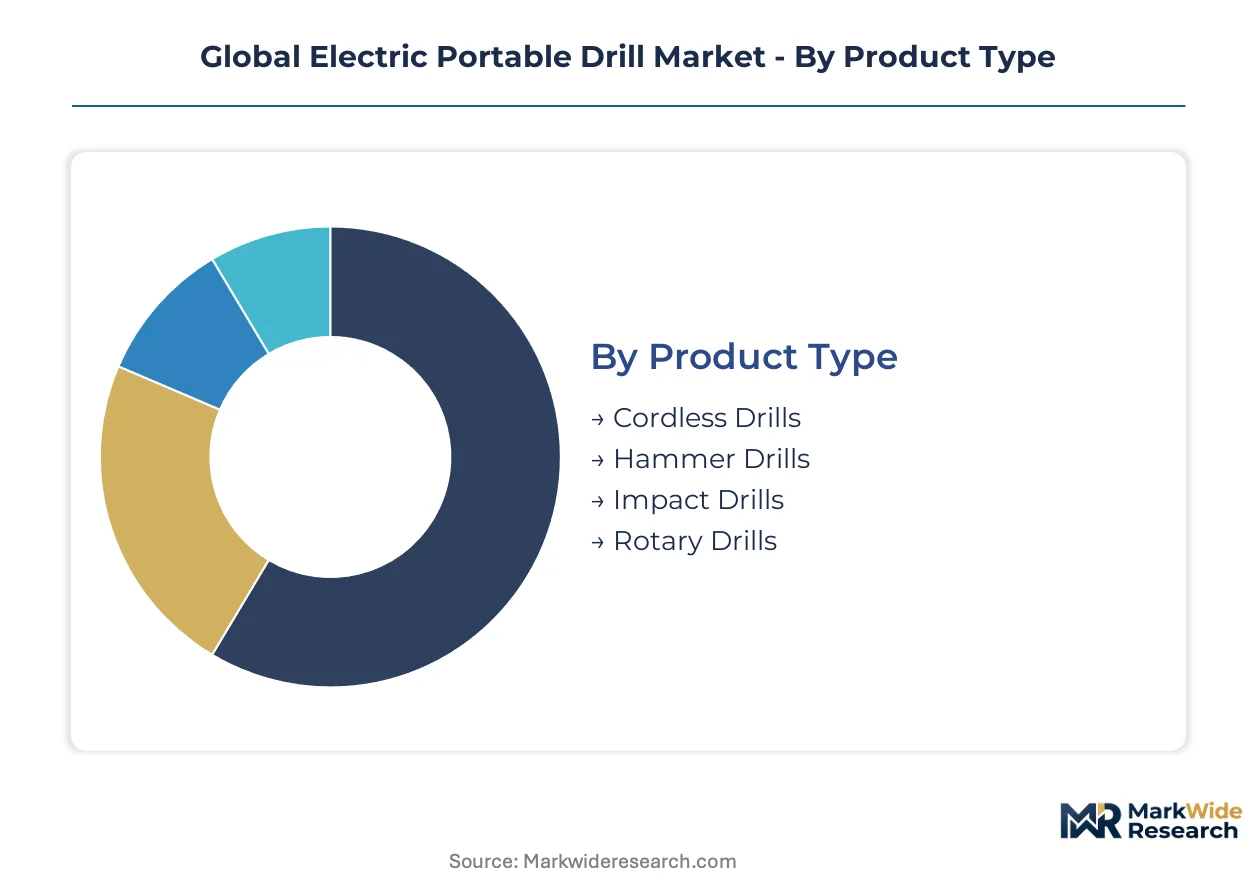
Segmentation in the electric portable drill market reveals how supply chain configuration and technical specifications align with distinct performance requirements. Each dimension exposes different competitive dynamics, from motor engineering choices to channel economics and end-user procurement patterns.
Product Type:
Supply concentration in brushless motor manufacturing favors platforms that can amortize R&D across high-volume cordless configurations.
- Cordless Drills:Lithium-ion battery platforms dominate residential renovation and light commercial work, with 20V-class systems now matching corded torque in medium-duty applications. Demand concentrates among North American DIY consumers and German professional contractors seeking mobility without performance sacrifice.
- Hammer Drills:Pneumatic percussion mechanisms enable masonry penetration in concrete and brick substrates, requiring reinforced gearboxes and specialized chuck assemblies. China infrastructure stimulus is concentrating procurement in tier-one and tier-two cities where commercial construction drives masonry-intensive applications.
- Impact Drills:Deliver high-torque rotary-percussive action for repetitive fastening tasks.
- Rotary Drills:Serve specialized industrial applications requiring sustained high-RPM operation.
Today's leader: Cordless Drills. Tomorrow's challenger: Hammer Drills.
Power Rating:
Cost tier differentiation separates professional-grade platforms from consumer entry points, with voltage class directly determining battery platform compatibility and tool body interchangeability.
- Low Voltage:12V-class systems target residential maintenance and light assembly with compact form factors. Demand concentrates in Japanese and UK household segments where storage constraints favor smaller tool footprints.
- Medium Voltage:18V-20V platforms represent the professional standard for general construction, balancing torque output with battery weight. North American residential contractors and Australian trade professionals drive replacement cycles as brushless retrofits displace legacy brushed inventory.
- High Voltage:36V-60V systems serve heavy-duty metalworking and continuous commercial applications.
- Ultra High Voltage:Specialized industrial configurations for mining and infrastructure projects.
Medium Voltage commands current volume leadership. High Voltage segments are gaining share fastest in commercial metalworking.
End User:
Application-specific duty cycles determine motor thermal design and battery chemistry selection, with construction and manufacturing presenting opposing requirements for intermittent versus continuous operation.
- Construction:Weather-exposed job sites demand sealed housings and rapid battery swap capability. Demand concentrates in China state-directed infrastructure projects and US residential renovation markets where cordless adoption eliminates generator dependency.
- Manufacturing:Assembly line integration requires torque precision and ERP connectivity for tool tracking. German automotive suppliers and Japanese electronics assemblers specify brushless platforms with digital torque feedback and wireless fleet management.
- DIY:Intermittent-use consumers prioritize price accessibility and retail availability.
- Automotive:Collision repair and aftermarket service bays favor compact 12V-class systems for confined-space access.
Construction retains volume primacy. Manufacturing is climbing the fastest as Industry 4.0 integration requirements expand.
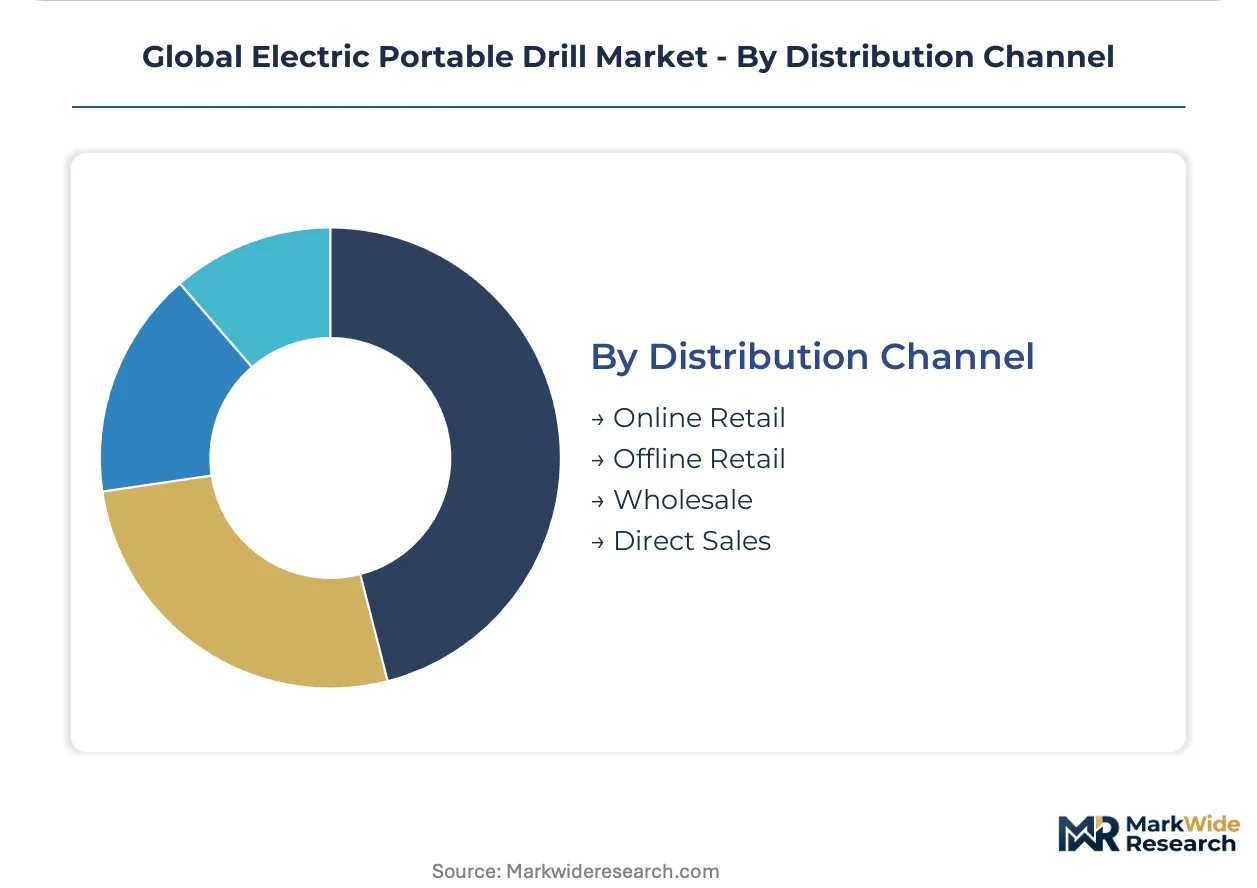
Distribution Channel:
Customer type and purchase frequency shape channel economics, with professional contractors consolidating procurement through trade-specialized routes while DIY consumers fragment across digital and physical touchpoints.
- Online Retail:Direct-to-consumer platforms capture DIY renovators through subscription bundling and consumable replenishment. Australian and UK markets show fastest expansion as specialized tool access services displace traditional retail for intermittent users.
- Offline Retail:Big-box home improvement stores retain professional contractor loyalty through immediate availability and in-person technical support. US and Canadian markets concentrate volume in this channel where same-day pickup eliminates project delay risk.
- Wholesale:Industrial distributors serve manufacturing accounts with volume pricing and integrated procurement systems.
- Direct Sales:OEM field teams target automotive and aerospace accounts with customized fleet solutions.
Offline Retail maintains current dominance. Online Retail presents the steepest expansion trajectory as subscription models penetrate residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is driving production migration toward jurisdictions with lower compliance friction. Manufacturers are relocating charger assembly and battery pack integration to minimize REACH documentation burdens and FCC certification overhead.
United States
Residential renovation contractors are converting to cordless platforms as lithium-ion torque curves match corded alternatives. OSHA electrical safety standards govern motor shielding and charger certification for North American distribution. Tool demand concentrates in Texas and Florida where housing starts and storm recovery cycles sustain replacement purchases.
Germany
Automotive suppliers specify brushless platforms with digital torque feedback for assembly line integration. EU F-Gas Regulation constrains refrigerant-based cooling systems in battery charging infrastructure, accelerating passive thermal management designs. Stuttgart anchors Bosch engineering operations serving premium professional channels across European markets.
China
State-directed infrastructure investment concentrates demand for hammer drill configurations in masonry-intensive commercial builds. MIIT energy efficiency directives mandate standby power thresholds below 0.5W for cordless tool chargers, forcing active power-factor correction integration. Manufacturing clusters in Guangdong and Zhejiang provinces are expanding brushless motor capacity and lithium-ion battery integration.
India
Grid expansion in secondary cities is creating first-time power tool ownership among informal construction laborers previously dependent on manual methods. BIS certification requirements and DGFT import procedures shape market entry pathways for foreign brands. Demand concentrates in Maharashtra and Gujarat where urban residential construction and industrial manufacturing overlap.
Japan
Electronics assemblers and automotive component manufacturers specify brushless platforms with wireless fleet management capabilities. METI efficiency standards and JIS certification protocols govern motor performance and electromagnetic compatibility. Industrial demand clusters in Osaka and Nagoya metropolitan areas where precision manufacturing tolerances require torque-calibrated tooling.
Global Electric Portable Drill Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue battery platform interoperability and subscription-based hardware refresh models. The vendor base separates into three recognizable tiers: premium engineering houses with Stuttgart or Tokyo engineering heritage; volume manufacturers with deep cordless platform ecosystems; and specialized fabricators serving regional trade channels. Strategic archetypes include ecosystem builders amortizing R&D across interchangeable battery platforms, vertical specialists controlling rare earth magnet supply chains, and direct-to-consumer disruptors bypassing traditional retail. Dominant competitive moves include portfolio diversification across voltage classes and geographic expansion through localized assembly partnerships.
Within the premium engineering tier, Robert Bosch GmbH and Makita Corporation exemplify contrasting approaches to sustaining margin position. Bosch leverages its Stuttgart engineering base to anchor premium positioning across European professional channels. Makita occupies a position defined by deep cordless platform ecosystems and battery interchangeability across tool categories. Stanley Black & Decker sits within the multi-brand portfolio architecture segment, spanning professional lines and consumer-facing sub-labels through differentiated channel strategies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Stanley Black & Decker |
| Makita Corporation |
| Techtronic Industries |
| Hilti Corporation |
| DeWalt |
| Hitachi Koki Co., Ltd. |
| Panasonic Corporation |
| Milwaukee Electric Tool Corporation |
| Others |
Supply Flow & Price Mechanics
Premium-standard bifurcation between brushless and brushed motor tiers manifests in divergent margin structures and sourcing footprints across the electric portable drill market. Professional-grade brushless platforms command sustained premium positioning through rare earth magnet integration and firmware-controlled torque calibration, while commodity brushed configurations face cost compression from Chinese manufacturing scale and inventory liquidation pressure during technology transitions.
Pricing Analysis
Distributor margin layers absorb 18-25 points between factory gate and retail shelf across North American and European channels. Three-tier pricing structure across premium, standard, and economy levels separates Bosch and Makita professional lines from mid-tier Techtronic offerings and private-label imports. Pricing pressure stems from lithium-ion cell cost volatility and REACH compliance documentation overhead for cobalt-containing cathodes. DIY consumers exhibit highest price sensitivity, while German automotive assemblers and Japanese electronics manufacturers prioritize torque precision over unit cost.
Supply Chain Analysis
Neodymium magnet supply rests on Chinese rare earth processing concentration, with 85% of global separation capacity located in Jiangxi and Inner Mongolia provinces. Lithium carbonate feeds from Chilean and Australian mining operations, while battery cell fabrication concentrates in South Korea and China. Single-source vulnerability in rare earth magnet procurement exposes brushless motor producers to export quota uncertainty and geopolitical friction. Distribution runs through big-box retail for North American residential contractors and industrial distributors for German manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU F-Gas cooling system constraints and MIIT standby power mandates are accelerating passive thermal management R&D investment across cordless platform portfolios.
For Market Incumbents: To counter rare earth supply concentration risk, secure long-term offtake agreements with Australian and Vietnamese rare earth projects outside Chinese processing orbit. Backward integration into motor control firmware development addresses power electronics engineering scarcity concentrated in automotive talent pools. Prioritize certification investment for simultaneous FCC, CE, and GB compliance to compress 8-14 month launch windows for global platform releases.
For New Entrants and Emerging Players: Battery platform interoperability represents the most penetrable white space as professional users seek cross-brand charger consolidation across mixed-vendor tool parks. Target Indian secondary cities where grid expansion creates first-time power tool ownership among informal construction laborers. Deploy subscription-based hardware access bundling consumable replenishment to bypass entrenched retail distribution.
For Investors and Strategic Acquirers: Consolidation pressure builds where brushless motor R&D amortization demands exceed standalone revenue bases, favoring acquisition of regional specialists with captive rare earth magnet sourcing. Long-term viability favors ecosystem builders with interchangeable battery platforms spanning 10+ tool categories. Watch brushless motor patent litigation filings as inflection indicator for technology transition maturity and defensive moat formation.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Interoperability Development | Cross-brand adapter ecosystems capture professional users seeking charger footprint consolidation. |
| Passive Thermal Management Redesign | EU F-Gas compliance accelerates cordless platform redesign for European market access. |
| Rare Earth Magnet Supply Diversification | Australian and Vietnamese sourcing reduces dependency on Chinese processing capacity. |
| Subscription-Based Hardware Access Launch | Direct-to-consumer channels displace big-box retail for intermittent-use DIY segments. |
| Simultaneous Multi-Jurisdiction Certification | FCC, CE, and GB compliance compression shortens global platform launch timelines. |
Methodological Framework
Bottom-up construction and manufacturing demand modeling reconciled against top-down cordless platform production tracking forms the analytical core of this study. Primary interviews with plant engineers at German automotive suppliers, procurement leads at North American residential contractors, aftermarket service heads at Japanese electronics assemblers, and distribution channel partners in Australian trade supply informed demand-side calibration. Secondary validation drew from MIIT energy efficiency filings, ECHA REACH registration databases, FCC equipment authorization records, and customs trade data on lithium-ion cell imports.
Input-output matrices map voltage class penetration rates against end-use duty cycle requirements across the projection horizon. Segmentation dimensions modeled include product type, power rating tier, end-user application, and distribution channel structure. CAGRs derive from regression analysis of historical platform replacement cycles and lithium-ion energy density improvement trajectories. Forecast inputs incorporate brushless motor adoption curves and infrastructure stimulus allocation patterns in China and India.
The model holds under stable rare earth magnet supply and continued lithium-ion cost decline; deviation in export quota enforcement or cobalt price spikes would shift volume projections. Forecasts reflect documented assumptions on technology transition timelines and regulatory enforcement intensity. A small set of named triggers—neodymium export restrictions, EU battery recycling mandate acceleration, and India BIS certification timeline compression—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Deburring Tool Market
Tools
Land Survey Equipment Market
Tools
Wood Floor Grinding Machine Market
Tools
Oxy-Fuel Torches Market
Tools
2D Laser Cutting Machine Market
Tools
Drill Presses Market
Tools
Tool Storage Market
Tools
Tool Pliers Market
Tools
Gouging Torch Market
Tools
Grinding Machines Market
Tools
Hand and Power Tools Market
Tools
Metal Cutting Machine Market
Tools
Core Shooter Machine Market
Tools
Cordless Power Drill Market
Tools
Portable Heat Press Machine Market
Tools
Portable Tools Market