
 North America Multi Cooker Market | 2026-2036
North America Multi Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
North America Multi Cooker Market Intelligence
Subscription-based appliance leasing is rewriting competitive entry barriers for smaller brands in the North America multi cooker space. Hamilton Beach Brands Holding Co. leverages its mass retail shelf presence to sustain volume leadership across big-box channels. SharkNinja Operating LLC anchors its position through direct-to-consumer content marketing that drives conversion on proprietary platforms. Breville USA Inc. differentiates via premium stainless steel construction and chef-backed recipe ecosystems.
A multi cooker is an electric countertop appliance combining pressure cooking, slow cooking, sautéing, steaming, and warming functions in a single sealed vessel with microprocessor-controlled temperature and pressure regulation. Units typically operate between 800 and 1,500 watts with programmable cycles from 30 minutes to 12 hours, serving residential meal preparation and commercial food service batch operations. Digital cookers lead revenue contribution due to Wi-Fi connectivity and app-based recipe libraries that command price premiums. The food service end user segment shows the fastest structural expansion as restaurants adopt multi cookers to offset persistent line-cook labor gaps. Stainless steel material configurations capture the dominant margin pool because durability claims support extended warranty pricing and reduce return rates.
The U.S. Department of Energy enforces minimum efficiency standards under 10 CFR 430 that constrain wattage ceilings and test procedures for electric cooking appliances. Health Canada and the Canadian Standards Association coordinate electrical safety certifications that govern cross-border product eligibility. The U.S. FDA's Food Code provisions on time-temperature controls indirectly shape commercial unit specifications for restaurants and institutional kitchens. Stakeholders must monitor how pending amendments to DOE test procedures and CSA Group harmonization timelines affect product development cycles and inventory positioning across the U.S.-Canada trade corridor.
Market Dynamics
The U.S. Department of Energy's 10 CFR 430 efficiency standards are compressing wattage ceilings across electric cooking appliances, forcing manufacturers to redesign thermal systems while maintaining output performance. This regulatory pressure intersects with persistent labor shortages in commercial kitchens to reshape procurement priorities across both residential and food service segments.
Growth Catalysts
- DOE Efficiency Mandates:The U.S. Department of Energy's tightening wattage caps under 10 CFR 430 are accelerating R&D investment in low-power heating elements and insulated vessel designs that maintain cooking throughput.
- Food Service Labor Gaps:Restaurants in the U.S. Southeast are deploying multi cookers to offset line-cook shortages, converting batch preparation tasks from skilled labor to programmable automation.
- Wi-Fi Module Integration:Connected cooking platforms are digitizing recipe execution, allowing remote monitoring and consistency control across commercial kitchen chains.
Market Restraints
- Stainless Steel Input Volatility:Grade 304 stainless steel price swings from Asian mills compress margin predictability for manufacturers positioning on durability claims.
- Cross-Border Certification Friction:Health Canada and CSA Group electrical safety requirements create timeline delays for U.S. manufacturers seeking parallel market entry.
- Single-Function Appliance Substitution:Dedicated pressure cookers and rice cookers retain cost advantages at entry price points, limiting multi cooker penetration in budget-conscious segments.
Strategic Opportunities
- Subscription Leasing Models:Appliance-as-a-service platforms are emerging in Canadian urban markets, reducing upfront barriers for younger households and generating recurring revenue streams.
- Commercial Batch Operations:Institutional kitchens in U.S. healthcare and education facilities represent underpenetrated volume demand for 20+ quart programmable units.
- CSA-US Harmonization:Pending alignment between Canadian Standards Association and U.S. test procedures under the USMCA framework could streamline single-SKU North American product strategies.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for microprocessor-controlled pressure regulation lags demand, extending development cycles for smart connectivity features.
- DOE Test Procedure Uncertainty:Pending amendments to Department of Energy measurement protocols complicate inventory positioning and product launch timing across the 2024-2026 window.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Multi Cooker Market |
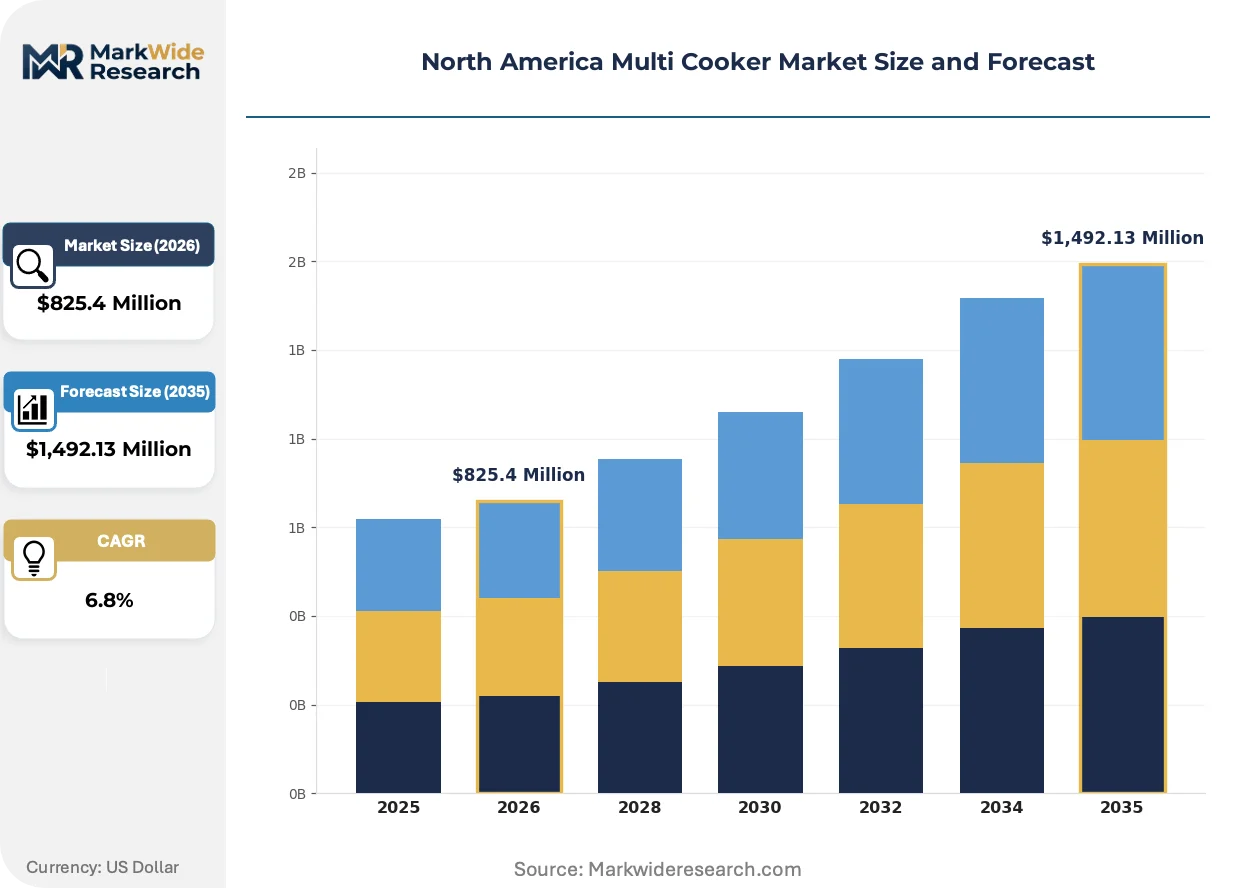
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,492.13 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Cookers, Digital Cookers, Pressure Cookers, Slow Cookers Material: Stainless Steel, Non-stick Coating, Aluminum, Ceramic End User: Household, Commercial, Restaurants, Food Service Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Instant Brands, Breville USA Inc., Hamilton Beach Brands Holding Co., Whirlpool Corporation, SharkNinja Operating LLC, Spectrum Brands Holdings Inc., Panasonic Corporation of North America, National Presto Industries Inc., KitchenAid, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Multi Cooker Market Strategic Shifts & Innovations
Programmable automation is displacing manual oversight in both home and commercial kitchens, while regulatory pressure on energy consumption forces hardware redesign. These forces are converging to reward manufacturers who can deliver connected, efficient appliances without sacrificing cooking performance.
Induction-compatible multi cooker bases are digitizing temperature control precision, replacing resistive heating coils with electromagnetic field systems that respond faster to microprocessor commands. Suburban dual-income households in Texas and California are adopting these units at accelerated rates, drawn by reduced preheat times and finer sauté control. The technology is digitizing the margin structure of the category, allowing manufacturers to command price premiums for precision features previously unavailable in countertop appliances.
The U.S. Department of Energy's evolving 10 CFR 430 test procedures are forcing manufacturers to document standby power draw and active cooking efficiency under standardized load conditions. This industrial consequence is compressing the viable wattage range for new product introductions and disqualifying legacy designs from federal procurement channels. Commercial food service buyers in the U.S. Southeast are responding by prioritizing certified-efficient units in renovation budgets, creating specification-driven demand concentration.
Kitchen renovation cycles are compressing as housing turnover accelerates in suburban markets, shortening replacement timelines for built-in appliance ecosystems. Big-box retail channels are capturing this demand through bundled kitchen suite promotions that position multi cookers as countertop complements to major appliance purchases. This pattern is most visible in California metro corridors where renovation spending and smart home integration preferences converge.
North America Multi Cooker Market Segmentation
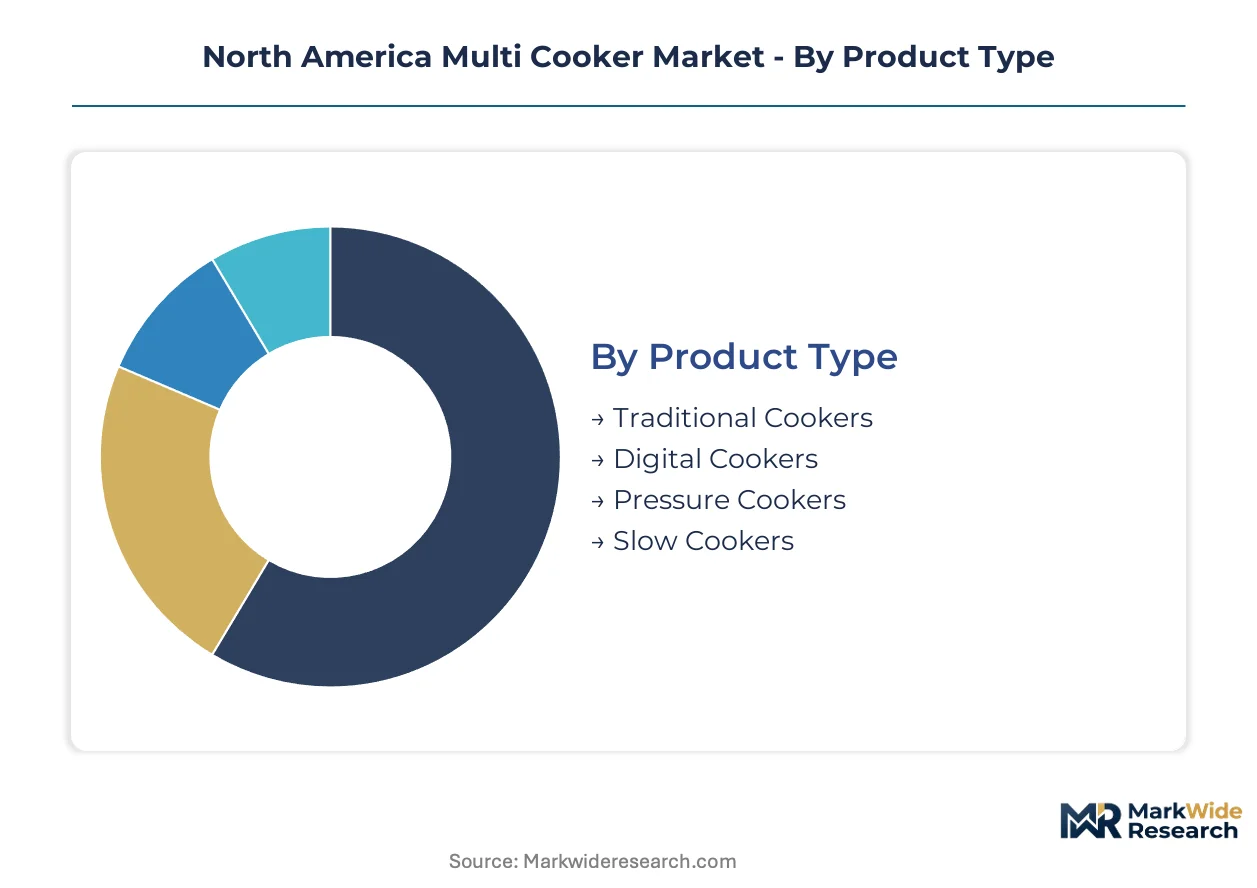
Segmentation in the North America Multi Cooker Market reveals how technology tiers, material durability claims, and channel economics split purchasing behavior across suburban households and labor-constrained commercial kitchens. Understanding these divides exposes where margin pools concentrate and which specifications drive specification-based procurement.
Product Type:
Cost tier stratification separates entry-level mechanical units from connected platforms commanding price premiums through firmware-enabled recipe automation.
- Digital Cookers:Microprocessor-controlled units integrate Wi-Fi modules and app-based recipe libraries. Demand concentrates in California and Texas suburban corridors where dual-income households prioritize remote monitoring and meal scheduling flexibility.
- Pressure Cookers:Sealed-vessel designs with programmable pressure regulation accelerate cooking cycles for protein-intensive meal preparation. The U.S. Southeast food service segment is adopting these units fastest to compress batch preparation timelines amid persistent line-cook shortages.
- Traditional Cookers:Mechanical timer-based units without connectivity serve budget-conscious replacement cycles.
- Slow Cookers:Low-wattage thermal designs emphasize extended unattended operation for home meal planning.
Digital Cookers holds installed capacity. Pressure Cookers is rotating up the share rankings.
Material:
Margin capture in material selection hinges on durability claims that support extended warranty pricing and reduce return rates across high-use commercial environments.
- Stainless Steel:Grade 304 and 316 vessels resist corrosion under repeated pressure cycling and acidic food exposure. The U.S. food service channel specifies these configurations to satisfy FDA Food Code time-temperature documentation requirements and minimize replacement frequency.
- Non-stick Coating:Polymer-based interior surfaces reduce oil requirements and simplify cleaning for residential users prioritizing convenience over thermal longevity.
- Aluminum:Lightweight die-cast bases improve thermal conductivity at lower price points, common in entry digital units.
- Ceramic:Chemical-free interior coatings appeal to health-positioned brands targeting wellness-focused consumer segments.
Stainless Steel commands the dominant margin pool. Ceramic is gaining share fastest among specialty-positioned brands.
End User:
Customer type determines volume scale, specification complexity, and procurement decision-making authority across residential and institutional buying centers.
- Food Service:Institutional kitchens in U.S. healthcare and education facilities deploy 20+ quart programmable units for batch protein and grain preparation. The segment is climbing the fastest as labor shortages force automation conversion of skilled cooking tasks.
- Restaurants:Independent and chain operators in the U.S. Southeast specify multi cookers during renovation cycles to reduce line-cook headcount without sacrificing output consistency.
- Household:Suburban dual-income families in California and Texas metro areas drive replacement demand through kitchen renovation triggers.
- Commercial:Corporate cafeteria and hospitality operations represent mid-volume procurement with standardized equipment specifications.
Household holds installed capacity. Food Service is rotating up the share rankings.
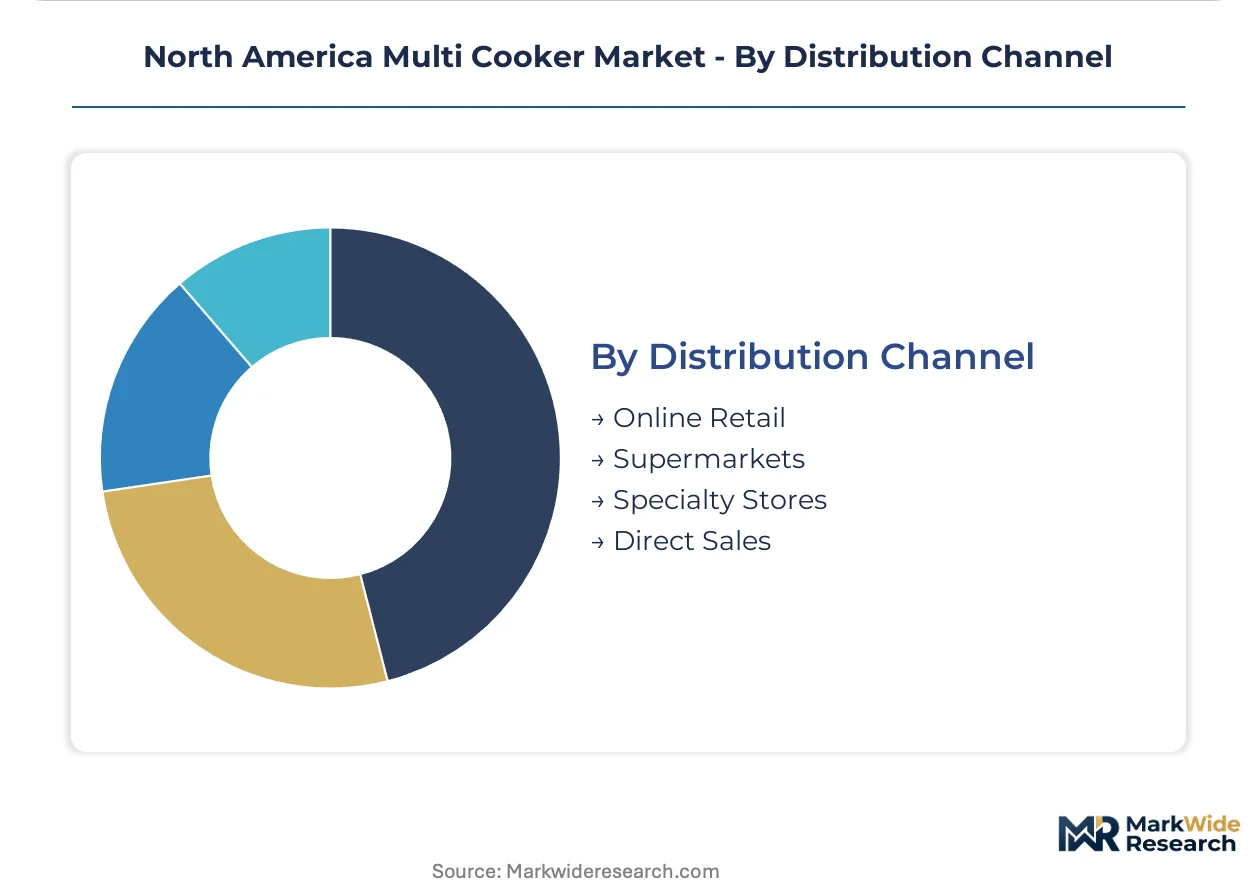
Distribution Channel:
Supply concentration in channel economics shapes how manufacturers balance margin capture against volume velocity and brand positioning control.
- Online Retail:Direct-to-consumer platforms enable firmware update delivery and subscription recipe service attachment. SharkNinja and comparable brands leverage proprietary digital storefronts to bypass retail margin extraction.
- Supermarkets:Mass retail shelf presence sustains volume leadership for brands like Hamilton Beach through impulse placement and bundled kitchen suite promotions.
- Specialty Stores:Sur La Table and Williams Sonoma channels support premium stainless steel positioning through tactile demonstration and chef-backed recipe ecosystem marketing.
- Direct Sales:B2B institutional procurement for healthcare and education facilities runs through manufacturer sales teams with specification engineering support.
Supermarkets holds installed capacity. Online Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Department of Energy's 10 CFR 430 efficiency mandates are compressing wattage ceilings across electric cooking appliances, while Health Canada coordinates electrical safety certifications with CSA Group. These regulatory frameworks are reshaping procurement priorities and product development cycles across the continent.
United States
Dual-income households in suburban Texas and California corridors are accelerating adoption of programmable digital units with Wi-Fi connectivity. The DOE's tightening appliance efficiency standards under 10 CFR 430 are forcing manufacturers toward lower-wattage thermal system redesigns. Kitchen renovation spending in the U.S. Southeast is converging with food service labor shortages to drive specification-driven demand for certified-efficient multi cookers.
Canada
CSA Group electrical safety certifications govern cross-border product eligibility and create timeline considerations for manufacturers seeking parallel market entry. Health Canada coordinates with the U.S. on harmonization timelines under the USMCA framework, potentially streamlining single-SKU North American strategies. Subscription-based appliance leasing platforms are emerging in Canadian urban markets, reducing upfront barriers for younger households.
Mexico
Manufacturing assembly operations in northern border states are positioning to supply North American demand as U.S. import regulations tighten. Mexico's national energy efficiency standards for household appliances create compliance requirements for products entering the domestic market. Industrial clusters in Nuevo León are developing component supply relationships with U.S.-based brands seeking nearshored production alternatives.
North America Multi Cooker Market Key Industry Players
Channel-controlling players compete with product-specialist players across a bifurcated structure where mass retail shelf presence and direct-to-consumer platforms represent distinct competitive vectors. The vendor base stratifies between volume-driven manufacturers with big-box relationships and premium-positioned specialists emphasizing chef-backed recipe ecosystems. Two strategic archetypes dominate: mass-market brands leveraging retail distribution density, and digitally native operators converting content marketing through proprietary platforms. Competitive moves center on subscription leasing model experimentation and firmware-enabled service attachment to hardware sales.
Within the mass retail tier, Hamilton Beach Brands Holding Co. and SharkNinja Operating LLC exemplify contrasting channel strategies, with the former anchoring big-box volume leadership and the latter driving conversion through direct-to-consumer digital storefronts. Breville USA Inc. occupies a premium positioning anchored by stainless steel construction claims and culinary professional endorsement networks. These three entities collectively illustrate how manufacturers are navigating the tension between retail margin extraction and proprietary platform control.
| Leading Market Players |
|---|
| Instant Brands |
| Breville USA Inc. |
| Hamilton Beach Brands Holding Co. |
| Whirlpool Corporation |
| SharkNinja Operating LLC |
| Spectrum Brands Holdings Inc. |
| Panasonic Corporation of North America |
| National Presto Industries Inc. |
| KitchenAid |
| Others |
Cost & Logistics Intelligence
Grade 304 stainless steel price volatility from Asian mills compresses margin predictability and forces manufacturers to stratify pricing tiers around durability claims while reshaping sourcing strategies toward tariff-resilient supply corridors.
Pricing Analysis
Certification level under DOE 10 CFR 430 and CSA electrical safety standards creates the primary spread between premium connected units and entry mechanical designs. Three-tier pricing structure across premium, standard, and economy levels anchors on wattage efficiency credentials and Wi-Fi module integration. Cost compression in the economy tier intensifies because single-function appliance substitutes retain price advantages. Food service buyers in the U.S. Southeast exhibit lowest price sensitivity due to labor-cost offset calculations, while budget-conscious household segments in suburban Texas and California drive entry-tier volume.
Supply Chain Analysis
Grade 304 and 316 stainless steel feedstock draws from Chinese, Indian, and South Korean mill operations, with electromagnetic induction components sourced from Taiwanese and Japanese electronics manufacturers. Microprocessor-controlled pressure regulation systems rest on firmware engineering talent concentrated in U.S. and Canadian technology corridors. Single-source vulnerability concentrates in Asian stainless supply given limited North American melt capacity. Distribution runs through big-box retail channels for volume brands and proprietary digital storefronts for direct-to-consumer operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering scarcity for microprocessor-controlled pressure regulation extends development cycles and creates acquisition opportunities for teams with embedded systems expertise.
For Market Incumbents: Build certification moats around DOE 10 CFR 430 efficiency credentials and CSA harmonization readiness to disqualify smaller competitors from federal procurement channels. Expand in-house production of low-wattage heating elements to reduce Grade 304 stainless exposure. Anchor shelf presence through bundled kitchen suite promotions at mass retail to defend against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Pursue subscription leasing models in Canadian urban corridors where upfront cost barriers constrain younger household penetration. Target institutional kitchens in U.S. healthcare and education facilities as the most penetrable white-space segment given underdeployment of 20+ quart programmable units. Lead with app-based recipe ecosystem attachment to hardware sales rather than competing on unit economics. For Investors and Strategic Acquirers: Firmware-capable appliance engineering teams with Health Canada certification track records represent priority acquisition archetypes given talent scarcity and cross-border regulatory complexity. Long-term viability hinges on recurring revenue attachment rates from connected cooking platforms rather than hardware margin sustainability. Monitor CSA-US harmonization timeline announcements as inflection indicators for single-SKU North American product strategy viability.| Strategic Initiative | Industry Significance |
|---|---|
| CSA-US Harmonization Investment | Streamlines single-SKU strategies across the U.S.-Canada trade corridor under USMCA alignment. |
| Subscription Leasing Platform Launch | Reduces upfront barriers for younger Canadian households while generating recurring firmware service revenue. |
| Low-Wattage Thermal System R&D | Positions products ahead of DOE 10 CFR 430 wattage ceiling compressions in federal procurement. |
| Food Service Channel Expansion | Captures specification-driven demand from labor-constrained U.S. Southeast restaurant renovation cycles. |
| Induction-Compatible Base Introduction | Commands price premiums from Texas and California dual-income households seeking precision temperature control. |
Research Approach
Operator-level perspectives from multi-cooker product managers, big-box retail category buyers, commercial kitchen equipment procurement officers, and firmware engineering directors anchored the qualitative base. These primary insights combined with secondary validation from DOE 10 CFR 430 docket filings, CSA Group certification databases, U.S. Census Bureau kitchen renovation spending data, and Health Canada appliance safety notices. Bottom-up unit shipment modeling and top-down consumer expenditure analysis provided triangulation across the analysis window.
Scenario-bracketing around DOE efficiency mandate implementation timelines and food service labor shortage persistence framed the analytical approach. Segmentation dimensions modeled include product type tier, material grade configuration, end-user category, and distribution channel concentration. CAGRs derived from installed base replacement cycles and renovation-triggered demand elasticity. Industry-specific forecast inputs incorporated stainless steel price volatility indices and Wi-Fi module cost curves.
Macroeconomic conditions sit as an overlay; deviation in suburban housing turnover rates and food service wage inflation would shift the trajectory. Forecasts reflect assumptions about regulatory harmonization progress and commodity input stability. Cross-checking against DOE appliance shipment databases and CSA certification issuance records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Nugget Ice Machines Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market
Food Processing Equipment
Seafood Processing Equipment Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Electric Brewing System Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Portioning Machines Market
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Global Industrial Bakery Processing Equipment Market
Food Processing Equipment
Commercial Oven for Bakery Market