
 Seafood Processing Equipment Market | 2026-2036
Seafood Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Seafood Processing Equipment Market Intelligence
The rising consumer preference for value-added frozen seafood and ready-to-eat items is restructuring equipment demand away from basic, high-volume filleting lines. Marel leverages its expertise in integrated processing solutions to capture this trend. BAADER Group sustains its leadership in high-precision filleting and gutting machinery. Meanwhile, GEA Group Aktiengesellschaft competes on the strength of its thermal processing and freezing units, which are critical for the frozen segment.
Seafood processing equipment encompasses a range of machinery designed to handle, prepare, and package fish and other aquatic organisms for commercial sale. These systems utilize technologies like ultrasonic cutting to ensure precise portions and minimize waste, adhering to strict quality control. While filleting machines represent a large and mature equipment category, growth is concentrating in systems integrating automated control and vision inspection. Advanced packaging machines, particularly for vacuum packaging, are also critical for extending shelf life and meeting retail standards.
Food safety mandates from bodies like the US FDA and the European Food Safety Authority (EFSA) dictate equipment design, emphasizing hygienic materials and ease of cleaning. International standards such as ISO 22000 further influence requirements for traceability and process control across the supply chain. For equipment manufacturers and seafood processors, the key strategic decision involves calibrating the level of automation investment against regional labor costs and evolving food safety compliance risks.
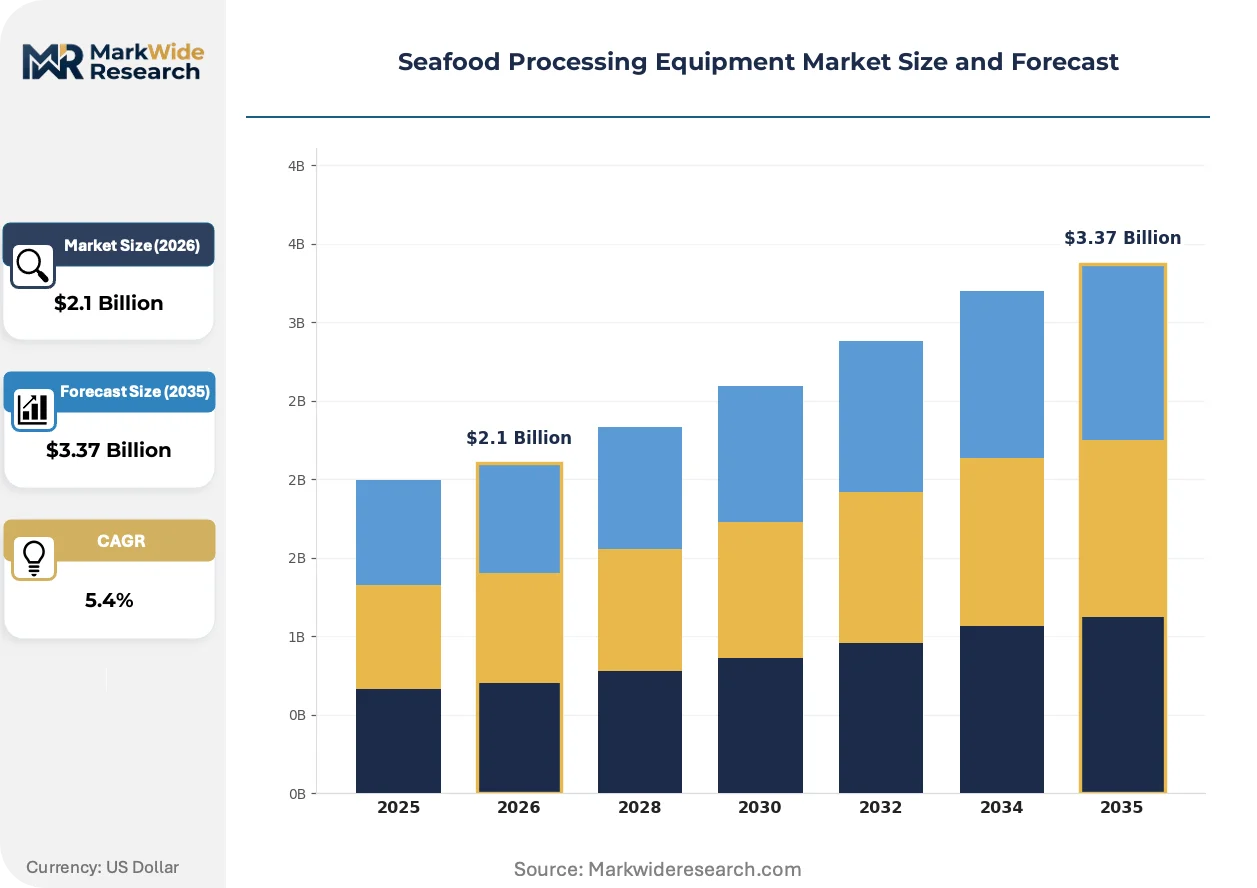
Market Dynamics
The central dynamic in the seafood processing equipment market is the strategic imperative to balance heavy capital investment in automation against the escalating risks and costs of non-compliance with global food safety regulations from bodies like the FDA and EFSA.
Growth Catalysts
- Hygienic Design Mandates:European Food Safety Authority (EFSA) guidelines on materials and cleanability are pushing demand for equipment made with stainless steel and designed for easy sanitation, reducing contamination risks in processing plants.
- Expansion of Cold Chain Logistics:The build-out of refrigerated transport and storage in developing economies enables the distribution of frozen and value-added seafood products, justifying investment in advanced freezing and packaging lines.
- Ultrasonic Cutting Technology:The adoption of ultrasonic blades for portioning high-value fish like tuna and salmon minimizes waste and provides precise, consistent cuts, improving yield and profitability for processors.
Market Restraints
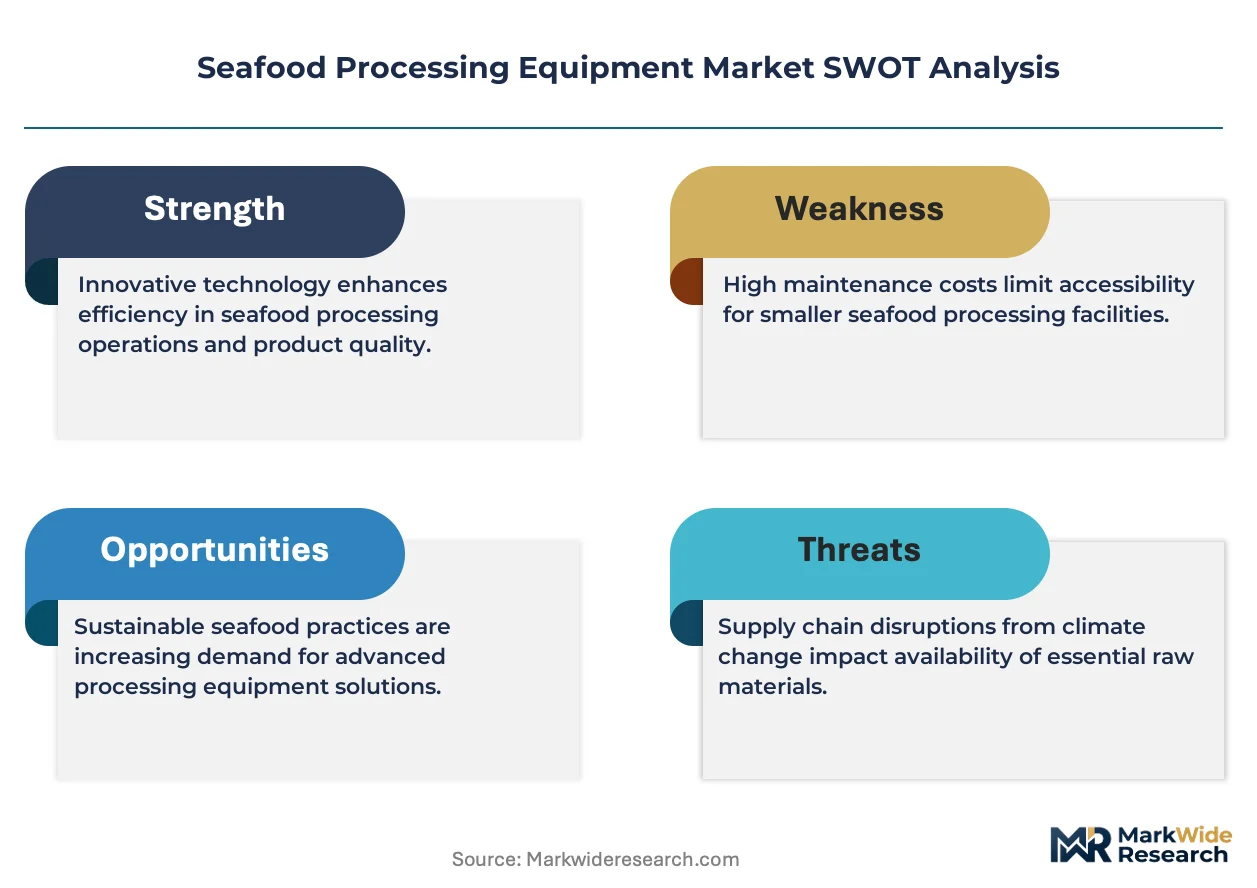
- High Capital Outlay:The significant upfront cost of fully automated processing lines, including robotic systems and advanced sensors, presents a major barrier to entry for small and medium-sized seafood processors.
- Seafood Supply Volatility:Fluctuations in fish catch volumes due to climate change, marine diseases, and stringent government-imposed fishing quotas create uncertainty in plant utilization rates, complicating ROI calculations for new equipment purchases.
- Natural Product Variability:The inherent inconsistency in the size, shape, and texture of fish and shellfish poses a significant challenge for automation, often requiring complex and expensive custom-engineered solutions.
Strategic Opportunities
- Aquaculture Growth in Southeast Asia:Rapid expansion of aquaculture in countries like Vietnam and Indonesia for shrimp and pangasius creates a new market for tailored, high-throughput processing and harvesting equipment.
- Blockchain for Traceability:Integrating equipment with blockchain platforms offers an opportunity to provide immutable, farm-to-fork traceability, meeting retailer and consumer demands for provenance and safety verification.
- Value-Added Shellfish Processing:A focus on developing automated systems for shucking, cooking, and packaging mollusks and crustaceans addresses a labor-intensive segment with significant potential for efficiency gains.
Industry Challenges
- Skilled Technician Scarcity:A persistent shortage of technicians qualified to install, operate, and maintain sophisticated mechatronic and software-driven processing equipment constrains operational efficiency and increases downtime.
- Legacy System Integration:Processors face considerable technical hurdles and costs when attempting to integrate new, data-enabled machinery with older, standalone equipment on existing production floors.
- Evolving Certification Demands:The continuous updating of food safety standards like ISO 22000 requires processors to undergo frequent and costly audits and equipment recertification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seafood Processing Equipment Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filleting Machines, Sorting Systems, Cleaning Equipment, Freezing Units, Packaging Machines Technology: Automated Control, Vision Inspection, Ultrasonic Cutting, Vacuum Packaging, Thermal Processing Application: Canning, Smoking, Breaded Products, Frozen Seafood, Ready-to-Eat Items End User: Seafood Processors, Retail Packers, Foodservice Suppliers, Exporters |
| Companies Covered | BAADER Group, Marel, GEA Group Aktiengesellschaft, JBT Corporation, CTB Inc., Pisces Fish Machinery Inc., Seafood Technology Limited, Carsoe Group A/S, Optimar AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seafood Processing Equipment Market Strategic Shifts & Innovations
Digitalization is transforming seafood processing machinery from standalone mechanical assets into interconnected, data-generating systems. This shift enables processors to optimize yield, ensure compliance, and verify sustainability claims through real-time operational intelligence gathered directly from the production line.
Advanced vision systems using AI and hyperspectral imaging provide real-time analysis of fillet quality, fat content, and bone detection. Large-scale processors in Norway and Canada are adopting these systems to optimize yield from high-value species like salmon. This technology is integrating quality control directly into the cutting process, reducing reliance on manual inspection and minimizing product waste.
Traceability mandates, such as the US FDA's Food Safety Modernization Act (FSMA) Rule 204, are becoming more stringent. This requires equipment to not only process seafood but also to capture and transmit data on its origin, batch, and handling at every stage. Processors exporting to the United States are most affected, forcing investment in network-enabled sensors and software on their equipment.
A shift towards verifiable sustainability is altering equipment procurement criteria for large seafood brands and retailers. Buyers now prioritize machinery that minimizes water and energy consumption per kilogram of processed product, moving beyond a singular focus on throughput. This trend is most pronounced in European markets, where eco-labels and corporate sustainability reports directly influence consumer choice and brand reputation.
Seafood Processing Equipment Market Segmentation
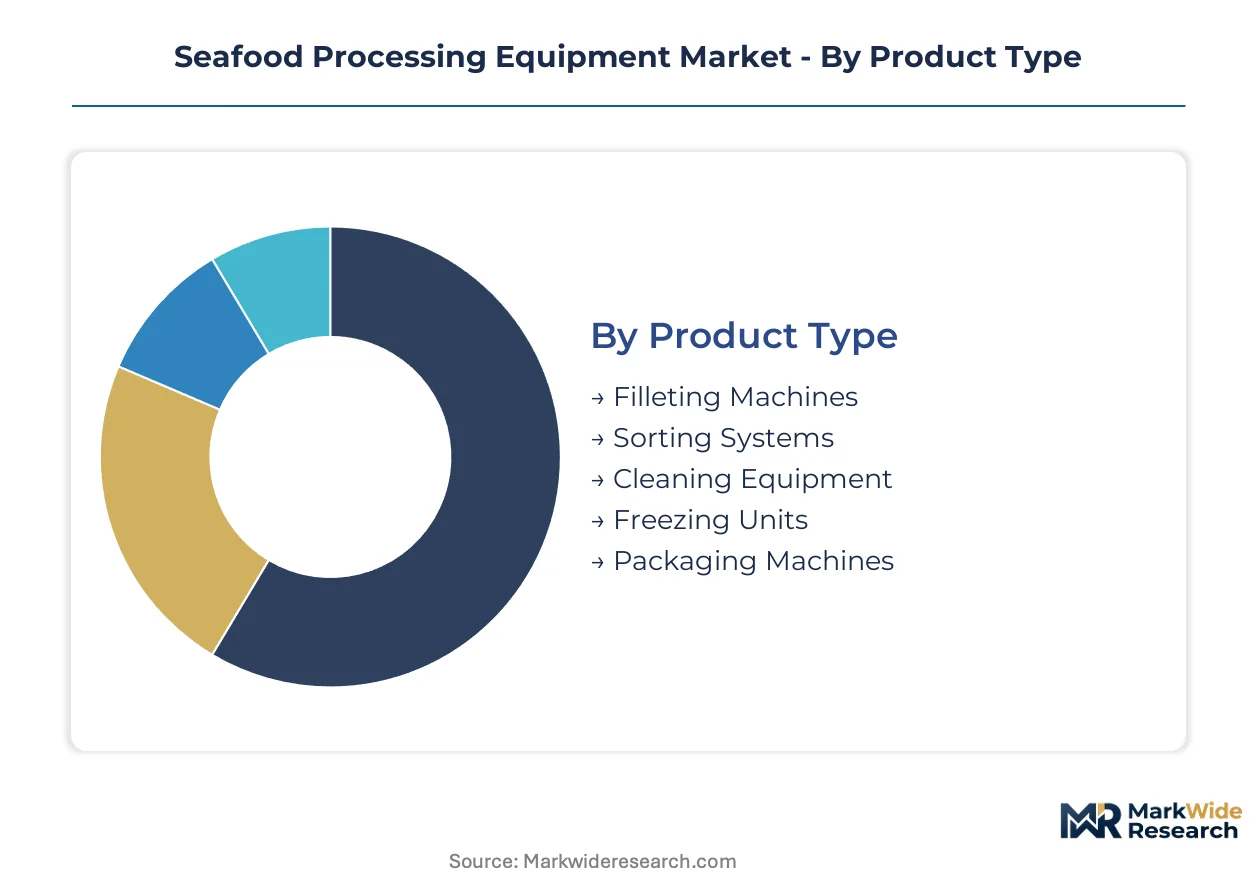
The Seafood Processing Equipment Market segmentation provides a granular view of equipment demand drivers and technological adoption patterns. Understanding these distinct segments helps manufacturers tailor offerings to specific operational requirements and evolving food safety mandates. This detailed breakdown reveals where investment is concentrating across the value chain.
Product Type:
The product type segment reflects the spectrum from highly specialized to broadly applicable machinery, illustrating the balance between customization for specific seafood types and standardized solutions for common tasks.
- Filleting Machines:These advanced systems utilize optical scanning and precise cutting mechanisms to debone and portion fish, optimizing yield from species like salmon and cod for large-scale processors. Demand concentrates in major aquaculture hubs like Norway, driven by export volume requirements.
- Packaging Machines:These units seal, label, and prepare processed seafood for distribution, crucial for extending shelf life and meeting diverse retail specifications, particularly for frozen and ready-to-eat products. Investment is significant in markets with stringent retail standards, such as the European Union.
- Sorting Systems:These machines classify seafood by size, weight, and quality using vision technology, improving consistency for subsequent processing stages.
- Cleaning Equipment:Designed for hygienic maintenance of processing lines, these systems ensure compliance with food safety regulations and reduce cross-contamination risks.
- Freezing Units:These industrial freezers rapidly lower product temperature, preserving quality and extending the shelf life of seafood for global distribution.
Most installed capacity flows through Filleting Machines. Expansion is steepest in Packaging Machines.
Technology:
The technology segment delineates the market by the level of automation and analytical sophistication integrated into processing equipment, directly impacting operational efficiency and product quality.
- Automated Control:These integrated software and hardware systems manage and optimize entire processing lines, reducing manual intervention and ensuring consistent throughput. Demand is concentrating in high-labor-cost regions like North America, driven by the need for efficiency gains.
- Vision Inspection:Utilizing AI and hyperspectral imaging, these systems detect defects, measure dimensions, and assess quality in real-time, integrating quality control directly into the production process. Large-scale processors in Canada are adopting these systems to optimize yield for high-value species.
- Ultrasonic Cutting:This technology employs high-frequency vibrations for precise, waste-minimizing portioning of delicate fish and shellfish, improving yield for premium products.
- Vacuum Packaging:This method removes air from packaging, significantly extending the shelf life of fresh and processed seafood by inhibiting bacterial growth.
- Thermal Processing:These units apply heat to cook, pasteurize, or sterilize seafood products, ensuring food safety and preparing items for canning or ready-to-eat formats.
The integration of Automated Control systems is a primary focus for new equipment purchases. This segment's evolution is heavily influenced by the drive for enhanced data capture and process optimization.
Application:
The application segment highlights how seafood processing equipment is deployed across different product categories, reflecting diverse consumer preferences and market demands.
- Frozen Seafood:This application involves equipment for rapid freezing, glazing, and packaging of fish and shellfish, essential for global cold chain logistics and long-term preservation. This segment is critical for expanding distribution networks in developing economies.
- Ready-to-Eat Items:This category encompasses machinery for cooking, seasoning, portioning, and packaging pre-prepared seafood products, catering to convenience-driven consumer lifestyles. Consumer preference for these items is restructuring equipment demand.
- Canning:This application utilizes specialized equipment for sterilizing, filling, and sealing seafood in cans, providing extended shelf life for shelf-stable products.
- Smoking:Processing equipment in this segment prepares seafood through smoking, imparting distinct flavors and preserving products like salmon and mackerel.
- Breaded Products:This application involves machinery for coating seafood portions with breadcrumbs or batter, common for retail and foodservice offerings.
Frozen Seafood applications represent a large portion of equipment deployment. Growth in this area reflects evolving consumer preferences for convenient and value-added products.
End User:
The end-user segment differentiates the market based on the primary entities utilizing seafood processing equipment, each with distinct operational scales and regulatory compliance needs.
- Seafood Processors:These are the primary industrial users, operating large-scale facilities that transform raw seafood into various products for wholesale and retail markets. Their demand is driven by the need for high-throughput and compliance with international food safety standards.
- Exporters:These entities require equipment capable of high-volume processing and packaging to meet international trade regulations and quality specifications for global distribution. Countries like Vietnam, with growing aquaculture exports, represent a significant market for this equipment.
- Retail Packers:These users focus on packaging and labeling processed seafood for direct sale to consumers, emphasizing presentation and extended shelf life.
- Foodservice Suppliers:This segment includes companies providing processed seafood to restaurants, institutions, and catering services, often requiring specific portioning and preparation capabilities.
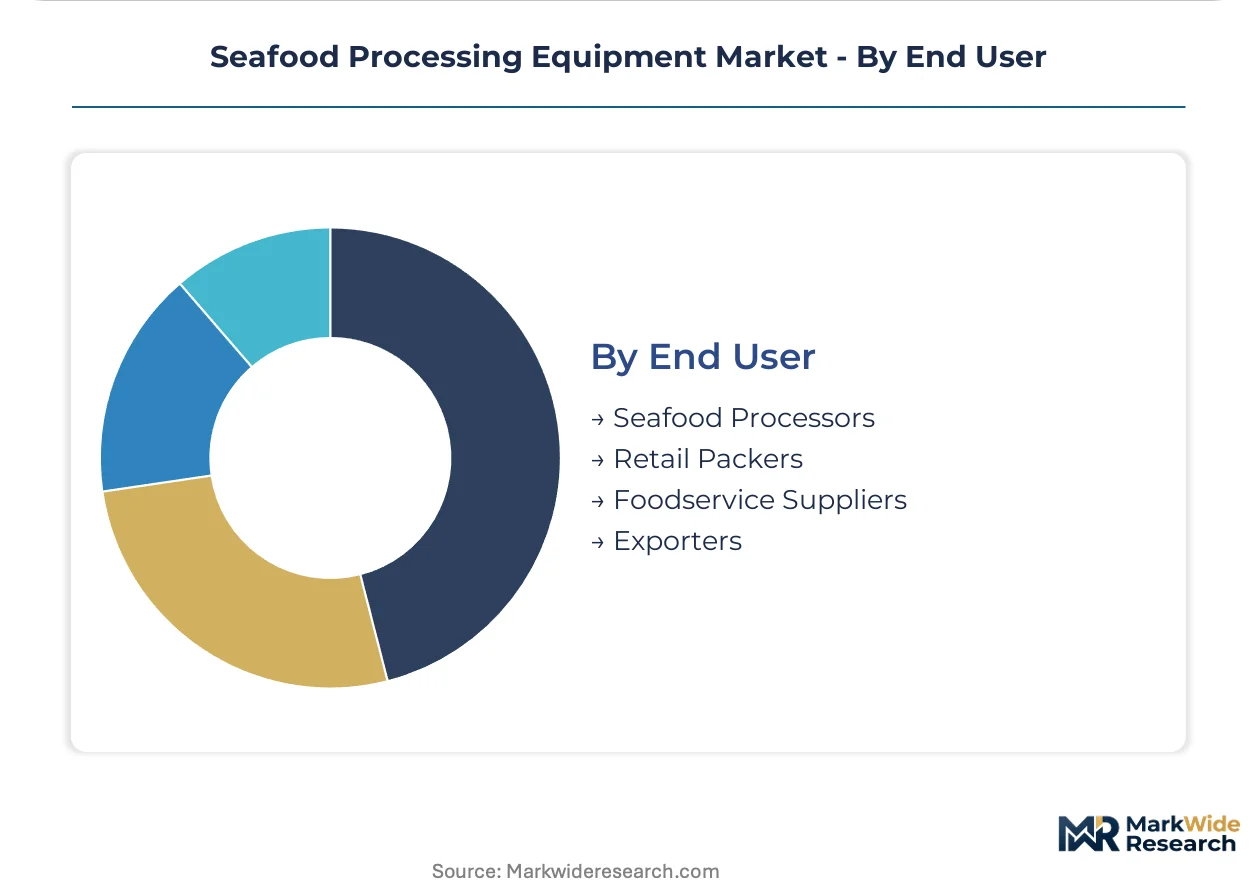
Seafood Processors represent the largest segment of equipment buyers. The demand from these users is shaped by their specific needs for scale and regulatory adherence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The disparity in regulatory enforcement and labor costs across regions drives strategic investment in seafood processing equipment. Some processors relocate or automate heavily to circumvent stringent food safety mandates, while others leverage lower operational costs. This dynamic creates distinct regional demand profiles for advanced machinery.
Norway
Demand for high-capacity filleting and gutting machinery supports Norway's export-oriented seafood industry. The European Food Safety Authority (EFSA) guidelines influence equipment design for hygienic processing. Major aquaculture hubs along the Norwegian coast, like those around Ålesund, require continuous upgrades for efficient salmon and cod processing.
United States
The US market demands advanced packaging and traceability systems to meet consumer and retail standards. The US FDA's Food Safety Modernization Act (FSMA) Rule 204 mandates comprehensive data capture throughout the supply chain. Processors in the Pacific Northwest, particularly in Alaska, invest in equipment for processing wild-caught species like pollock and salmon.
Canada
Large-scale processors in Canada seek vision inspection and automated control systems to optimize yield from high-value species. Health Canada regulations for food processing emphasize hygienic design and ease of cleaning for all new machinery. British Columbia's aquaculture sector focuses on advanced solutions for salmon processing and packaging for export markets.
Vietnam
Rapid expansion of aquaculture, especially for shrimp and pangasius, drives equipment demand for high-throughput processing. Vietnam's Directorate of Fisheries (D-FISH) promotes modernization to meet international export requirements. Processing centers in the Mekong Delta are investing in tailored equipment for automated sorting and packaging of aquatic products.
Germany
Germany's market for seafood equipment focuses on thermal processing and freezing units for value-added frozen products. CE marking and ISO 22000 standards dictate stringent quality and safety requirements for imported and locally manufactured machinery. Major food processing clusters around Hamburg integrate advanced freezing and packaging lines for diverse seafood offerings.
Seafood Processing Equipment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the seafood processing equipment market. The market exhibits a tiered structure, with established players focusing on integrated solutions and niche providers addressing specific processing needs. Strategic archetypes include comprehensive solution providers, precision machinery experts, and thermal processing specialists. Companies are increasingly pursuing technology licensing and strategic partnerships to expand their product portfolios and geographic reach.
On the premium-tier vector, Marel and BAADER Group exemplify leadership in advanced, integrated processing lines, particularly for high-volume filleting and gutting operations. These companies often anchor solutions for export-oriented industries requiring high precision and automation. GEA Group Aktiengesellschaft, a German-based company, occupies a significant position in thermal processing and freezing units, which are critical for the expanding frozen seafood segment. Their offerings address the need for quality preservation and extended shelf life. These players collectively represent the industry's drive towards higher efficiency and compliance with global food safety standards through continuous innovation.
| Leading Market Players |
|---|
| BAADER Group |
| Marel |
| GEA Group Aktiengesellschaft |
| JBT Corporation |
| CTB Inc. |
| Pisces Fish Machinery Inc. |
| Seafood Technology Limited |
| Carsoe Group A/S |
| Optimar AS |
| Others |
Cost & Logistics Intelligence
Global whitefish commodity prices, influenced by catch quotas and aquaculture yields, directly cascade into the pricing tiers for high-volume filleting machinery. These commodity fluctuations impact processor profitability, influencing their capital expenditure decisions for new equipment.
Pricing Analysis
Direct-to-OEM discounts are common for large-scale integrated processing lines, reflecting the project-based pricing model prevalent in this market. Price differentiation often stems from the level of customization required and the integration of advanced vision inspection systems. Pricing softness runs through standard equipment due to increased competition from Asia-based manufacturers. Large export-oriented processors are less price-sensitive compared to smaller, regional seafood processors.
Supply Chain Analysis
Specialized sensor and control system component supply rests heavily on manufacturers in Germany and Japan. The supply chain for seafood processing equipment sources critical stainless steel from diverse global markets. Single-source vulnerability for highly specialized mechatronic parts represents a significant structural risk. Equipment distribution runs through a mix of direct sales from OEMs and specialized regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play, leveraging lower labor costs in Southeast Asian processing hubs against the stringent food safety compliance requirements in European and North American markets. This disparity drives distinct equipment demand profiles.
For Market Incumbents:Anchor market leadership by investing in next-generation automated control systems that integrate AI for predictive maintenance. Pursue strategic acquisitions of niche software firms specializing in blockchain traceability platforms. Evolving certification demands from bodies like EFSA pose a continuous threat, requiring ongoing R&D into hygienic materials and easier-to-clean designs. This enables incumbents to maintain their premium positioning against emerging low-cost automation providers.
For New Entrants and Emerging Players:Modular, scalable automation solutions for labor-intensive shellfish processing create a technology-first wedge for new entrants. Target aquaculture expansion in Vietnam and Indonesia for pangasius and shrimp, focusing on high-throughput sorting and packaging equipment. Offering subscription-based software for integrating older machinery provides a compelling go-to-market angle for small-to-medium processors. Focus on solutions that address the natural product variability challenge.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized technology providers offering solutions for advanced data capture and process optimization. The long-term viability of this market is secured by increasing global demand for processed seafood and stricter food safety mandates. Acquisition targets should include firms with patented ultrasonic cutting technology or advanced vision inspection capabilities. A significant signal to watch is the widespread adoption of blockchain for traceability by major retailers.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of AI Vision System Developer | Enhances real-time quality control and yield optimization for high-value species like salmon. |
| Investment in Modular Automation Platforms | Addresses the need for flexible, scalable solutions for diverse seafood types and varied processing volumes. |
| Development of Blockchain-Integrated Traceability | Meets stringent regulatory requirements and consumer demand for immutable farm-to-fork provenance. |
| Expansion of After-Sales Service Networks | Ensures operational continuity and maximizes equipment uptime for large-scale export-oriented processors. |
| R&D in Sustainable Processing Technologies | Aligns with European eco-labels and corporate sustainability goals, reducing water and energy consumption. |
Research Approach
Direct dialogue with seafood processing plant managers, equipment engineers, food safety officers, and procurement heads at large retailers provided primary insights. This qualitative grounding was validated through extensive secondary research, including FAO fisheries reports, US FDA and EFSA guidelines, equipment manufacturer annual reports, and relevant trade association publications. Bottom-up market sizing was triangulated with top-down validation against industry revenue figures.
The quantitative model produced detailed volume and value projections across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and specific processing capacity tiers. Compound annual growth rates were derived from historical trends, future technological adoption curves, and expected regulatory impacts. Global seafood production volumes and aquaculture expansion rates served as key forecast inputs.
The model holds under current geopolitical stability and predictable climate patterns; deviation in global fish stock availability or sudden shifts in trade policies would shift projections. Forecasts reflect assumptions regarding technological adoption rates and regulatory enforcement. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Food Processing and Handling Equipment Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
French Fries Cutter Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Asia-Pacific Walk-In Refrigerators and Freezers Market