
 Global Non-Thermal Pasteurization Market | 2026-2036
Global Non-Thermal Pasteurization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Thermal Pasteurization Market Outlook
European equipment manufacturing is shifting toward modular, energy-efficient non-thermal systems as food processors seek lower-carbon alternatives to heat-based pasteurization. Hiperbaric leverages its Basque engineering base to dominate high-pressure processing system exports across the continent. Thyssenkrupp AG anchors industrial-scale pulsed electric field installations for German meat processors. JBT Corporation competes through integrated cold plasma and ultrasound lines for North American beverage producers.
Non-thermal pasteurization encompasses physical methods that inactivate microorganisms using pressure, electric fields, plasma, or acoustic energy rather than conventional thermal energy, typically operating below 40°C to preserve heat-sensitive bioactive compounds and sensory attributes. High Pressure Processing commands the largest installed base among technologies due to proven efficacy against vegetative pathogens in packaged juices and guacamole. Pulsed Electric Field represents the fastest-expanding technology segment as dairy processors adopt continuous-flow systems for extended liquid egg and milk shelf life without protein denaturation. Cold Plasma remains nascent in commercial meat surface decontamination, with margin pools concentrated in equipment-service contracts rather than capital sales.
The FDA evaluates non-thermal processes under its novel technology notification pathway, while the EU's General Food Law and EFSA scientific opinions on high-pressure treatment create divergent pre-market requirements on opposite sides of the Atlantic. ISO 22000 and sector-specific BRC certification standards increasingly mandate validated non-thermal critical control points for ready-to-eat meal suppliers. Stakeholders must monitor regulatory harmonization progress between FDA process authority requirements and EU implementing acts on cold plasma food contact materials.
Market Dynamics
Beverage manufacturers are accelerating capital deployment into High Pressure Processing systems as clean-label positioning becomes non-negotiable for shelf placement in premium retail channels.
Growth Catalysts
- EU Novel Food Regulation:EFSA scientific opinions on high-pressure treatment create pre-market approval pathways that validate non-thermal efficacy for dairy exporters seeking extended shelf life claims.
- Cold-pressed juice category:Raw beverage brands require HPP systems to achieve log-reduction guarantees without thermal degradation of enzyme activity and vitamin C retention.
- German engineering cluster:Basque and Ruhr industrial bases concentrate pulsed electric field and high-pressure equipment manufacturing capacity serving continental European processors.
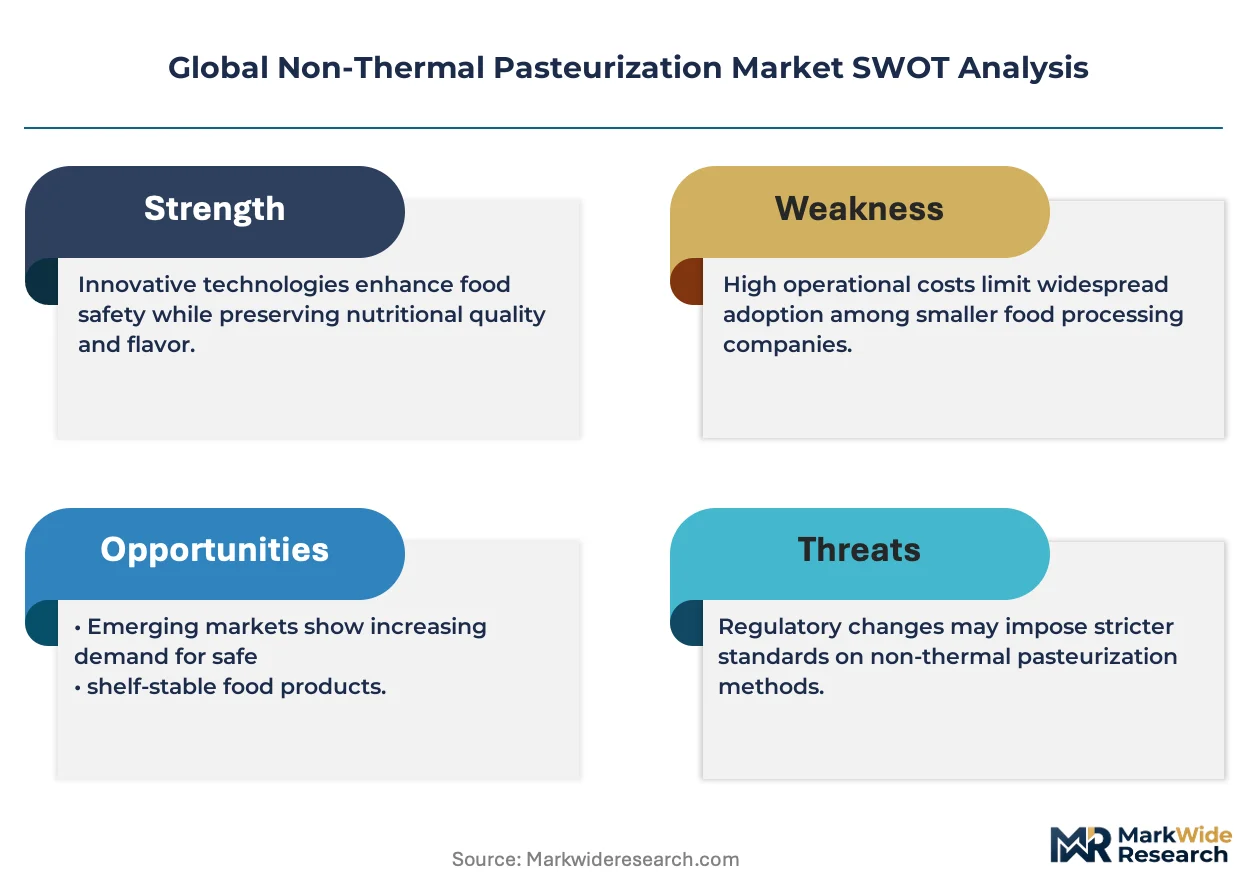
Market Restraints
- Stainless steel and high-pressure vessel alloys:Input cost volatility for 316L grade steel and specialized forging capacity constrains equipment margin structures during commodity cycles.
- Validation timeline friction:FDA process authority requirements for novel technology notification extend commissioning cycles by 12-18 months for first-of-kind installations.
- Thermal tunnel pasteurization:Mature heat-based systems retain cost advantages for low-margin commodity juices where nutritional preservation commands no price premium.
Strategic Opportunities
- India FSSAI pathway development:India's food safety regulator is drafting alternative pasteurization guidelines that would unlock HPP adoption for domestic mango pulp and lassi processors.
- Continuous-flow PEF-UV convergence:Dairy processors are piloting integrated pulsed electric field and ultraviolet systems for liquid egg pasteurization without protein aggregation.
- Equipment-as-service models:Pay-per-liter contracting structures reduce capital barriers for mid-size beverage co-packers entering clean-label contract manufacturing.
Industry Challenges
- Process authority documentation:FDA validation protocols require extensive microbial challenge studies that strain technical staffing at equipment OEMs and processor quality departments.
- Legacy thermal line retrofit:Integration of non-thermal critical control points into existing ISO 22000-certified plants demands HACCP recertification and operator retraining programs.
- Specialized technician scarcity:Maintenance of 600 MPa pressure vessels and Marx generator pulse electronics requires skill sets concentrated in Basque and Bavarian industrial regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Thermal Pasteurization Market |
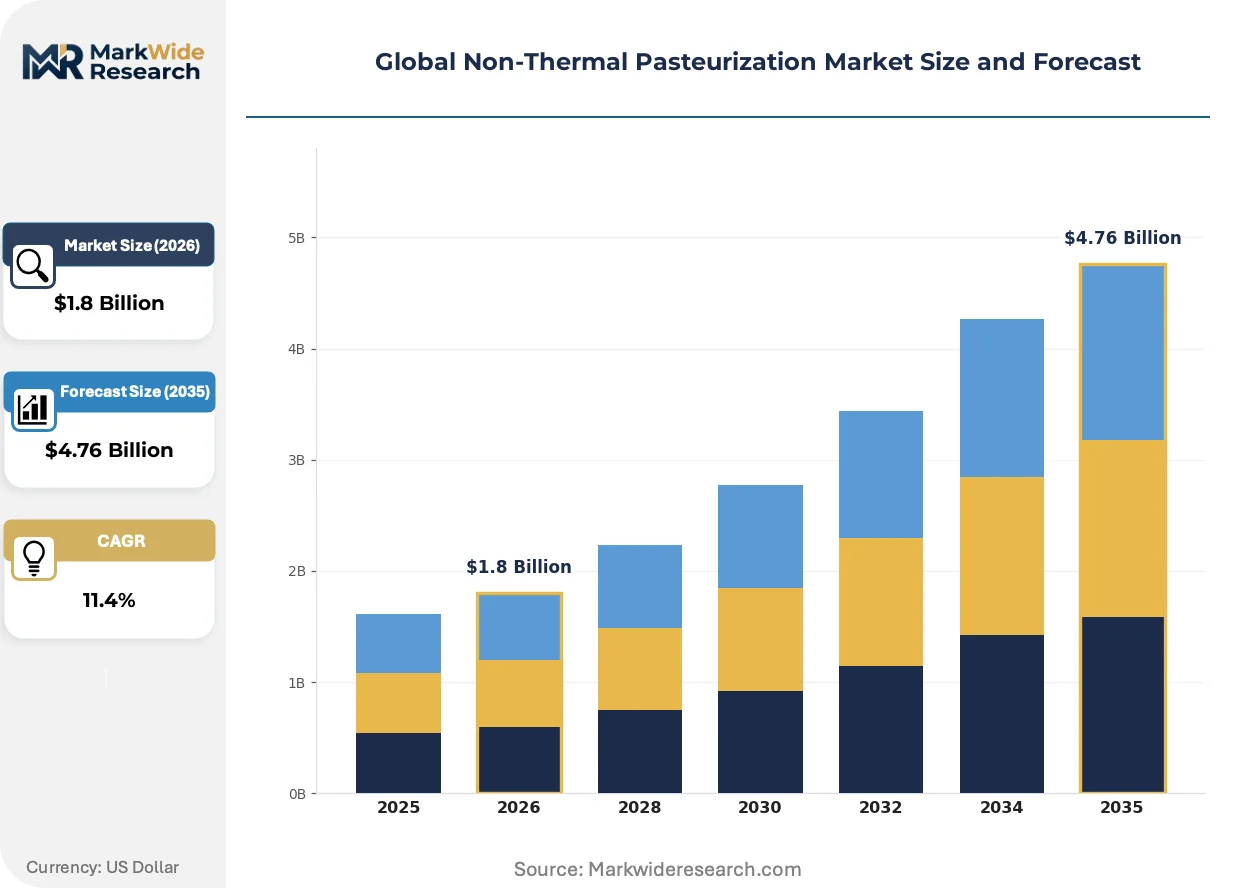
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasound, High Pressure Processing, Pulsed Electric Field, Cold Plasma Application: Fruit Juices, Dairy Products, Meat, Ready-to-Eat Meals End User: Food Manufacturers, Beverage Producers, Dairy Processors, Restaurant Chains Distribution Channel: Retail Stores, Online Platforms, Food Service, Wholesale |
| Companies Covered | JBT Corporation, Hiperbaric, Thyssenkrupp AG, Lyras, Syntegon, Nordion, Pulsemaster, Elea, Stansted Fluid Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Thermal Pasteurization Market Strategic Shifts
Equipment architecture is pivoting from monolithic industrial installations toward configurable processing modules that processors can scale with volume ramps.
High Pressure Processing skid systems is modularizing from fixed 300-600 liter batch configurations into 100-liter incremental units that beverage co-packers deploy across multiple contract manufacturing sites. Small-batch juice brands in California and New York are leasing mobile HPP units to avoid capital commitment during product trial phases. This modularity is compressing minimum efficient scale thresholds and fragmenting equipment procurement decisions toward regional operations managers rather than centralized engineering functions.
REACH regulation updates on food contact materials are compelling European OEMs to submit expanded migration testing for polymeric seals and coatings in high-pressure vessels. ECHA substance restrictions on certain phthalate plasticizers are forcing reformulation of dynamic seals that must withstand 600 MPa cyclic loading. German dairy equipment suppliers are responding by accelerating stainless-steel bellows seal development to preempt regulatory non-compliance risks in export markets.
Brand procurement teams are consolidating vendor relationships around integrated technology platforms rather than point-solution acquisitions. Beverage multinationals are awarding sole-source contracts to equipment providers capable of delivering HPP, PEF, and cold plasma validation support under unified service agreements. This consolidation pattern is most visible in North American ready-to-drink coffee and functional beverage segments where co-manufacturing networks demand standardized critical control point documentation across multiple production facilities.
Global Non-Thermal Pasteurization Market Segmentation
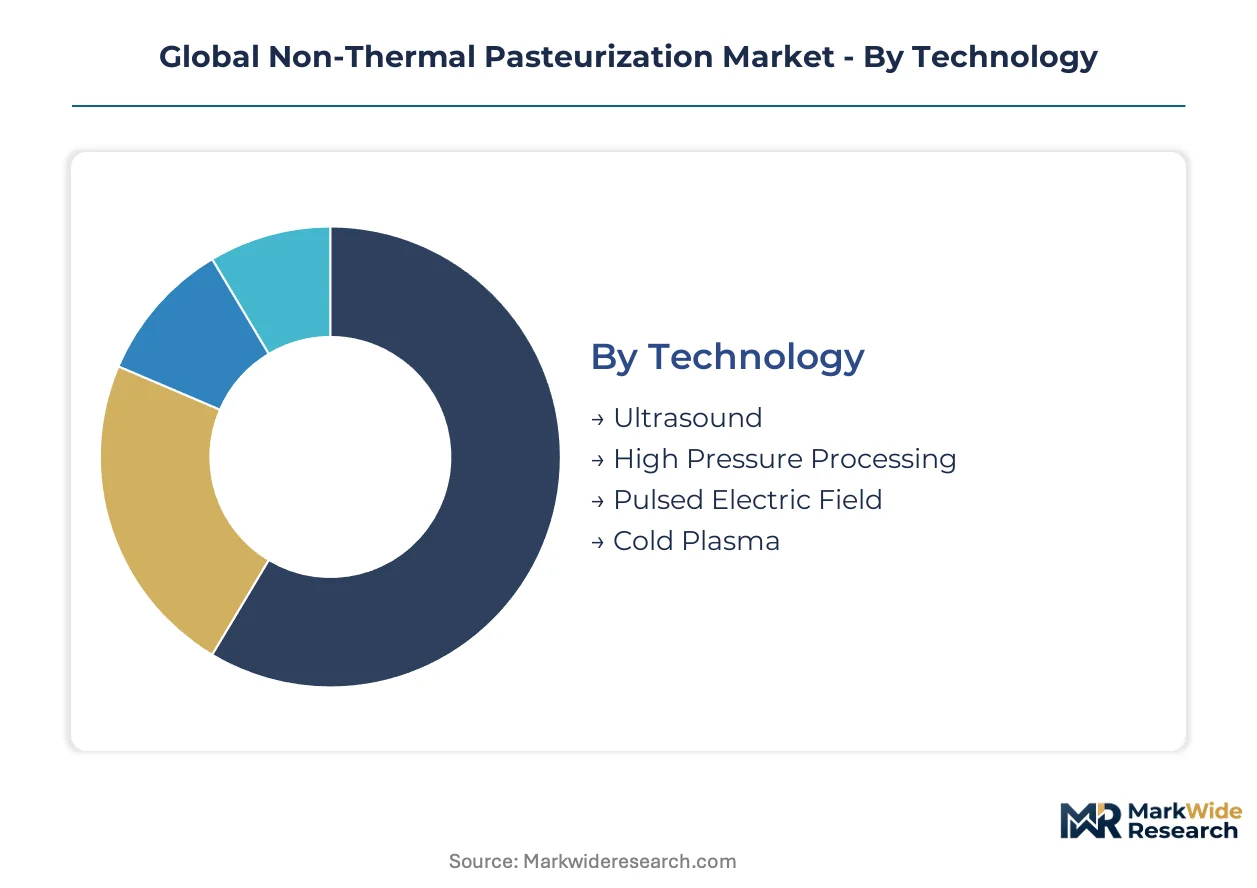
Non-thermal pasteurization equipment procurement fragments across technology readiness, application severity, and end-user scale. Understanding these intersections clarifies why German engineering clusters dominate high-pressure systems while PEF adoption concentrates in continuous-flow dairy operations.
Technology:
Standardization dominates at the high-pressure end, while emerging modalities demand bespoke integration support.
- High Pressure Processing:Batch processing at 400-600 MPa inactivates vegetative pathogens without thermal degradation. Beverage producers in California and New York deploy HPP for cold-pressed juice shelf-life extension where enzyme retention commands premium positioning.
- Pulsed Electric Field:Continuous-flow treatment applies 10-80 kV/cm electric pulses to liquid foods. German dairy processors adopt PEF for extended milk shelf life without protein denaturation, bypassing thermal tunnel infrastructure entirely.
- Cold Plasma:Atmospheric-pressure discharge generates reactive species for surface decontamination. Meat processors pilot dielectric barrier discharge systems for carcass and cut surface treatment, though commercial scale remains limited by equipment-service model economics.
- Ultrasound:Acoustic cavitation at 20-100 kHz disrupts microbial membranes. Niche applications in beverage homogenization and extraction processes serve smaller-scale operators seeking lower capital barriers.
Leading the category by volume: High Pressure Processing. Growing fastest: Pulsed Electric Field.
Application:
Regulatory stringency and spoilage risk determine technology matching across food categories.
- Fruit Juices:HPP dominates log-reduction validation for raw and cold-pressed segments. FDA process authority requirements for novel technology notification concentrate commissioning expertise among California and Florida co-packers serving national retail distribution.
- Dairy Products:PEF continuous-flow systems preserve whey protein structures in extended-shelf-life milk. EU EFSA scientific opinions on high-pressure treatment create divergent approval pathways for exporters targeting multiple regulatory jurisdictions.
- Meat:Surface decontamination demands drive cold plasma pilot installations. USDA-FSIS validation protocols for alternative processing technologies extend timeline friction for first-of-kind system deployments.
- Ready-to-Eat Meals:Combined HPP and modified atmosphere packaging address Listeria control in packaged salads and deli items. BRC certification standards increasingly mandate validated non-thermal critical control points for supplier qualification.
Most mature deployment: Fruit Juices. Steepest expansion trajectory: Dairy Products.
End User:
Capital intensity and technical staffing separate multinational adopters from regional processors.
- Food Manufacturers:Integrated HPP lines for guacamole and salsa production anchor clean-label positioning. Procurement consolidates around equipment providers capable of unified validation support across multiple facilities.
- Beverage Producers:Cold-pressed juice brands lease mobile HPP units to avoid capital commitment during product trials. Equipment-as-service models reduce barriers for mid-size co-packers entering contract manufacturing.
- Dairy Processors:Continuous-flow PEF adoption concentrates in German, Dutch, and Danish operations with technical staffing for Marx generator maintenance. Basque and Bavarian technician scarcity constrains expansion timelines.
- Restaurant Chains:Central commissary adoption of non-thermal systems remains nascent. Quality assurance departments prioritize thermal pasteurization for supply chain simplicity despite nutritional trade-offs.
Highest equipment throughput: Food Manufacturers. Fastest procurement pattern shift: Beverage Producers.
Distribution Channel:
Channel margin structures determine whether non-thermal processing costs transmit to end consumers.
- Retail Stores:Premium shelf placement for HPP-treated juices and refrigerated dips justifies processing premiums. Clean-label positioning becomes non-negotiable for placement in perimeter refrigerated cases.
- Online Platforms:Direct-to-consumer cold-pressed juice subscriptions bypass retail slotting fees. Subscription economics support higher processing costs through recurring revenue stabilization.
- Food Service:Institutional procurement prioritizes cost minimization over nutritional preservation. Thermal pasteurization retains dominance in school and hospital feeding programs.
- Wholesale:Ingredient suppliers of mango pulp and liquid egg seek non-thermal validation for export qualification. India's FSSAI pathway development would unlock HPP adoption for domestic processors targeting international markets.
Price transmission effectiveness: Retail Stores. Channel expansion potential: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basque Country engineering clusters anchor high-pressure vessel forging capacity for European equipment supply chains. German Ruhr industrial bases concentrate pulsed electric field system manufacturing. California and New York beverage co-packers drive North American HPP adoption for cold-pressed juice validation.
United States
FDA process authority requirements for novel technology notification extend commissioning cycles for first-of-kind HPP installations. Cold-pressed juice brands in California deploy mobile high-pressure units to avoid capital commitment during product trials. Florida co-packers concentrate log-reduction validation expertise serving national retail distribution networks.
Germany
Thyssenkrupp AG anchors industrial-scale pulsed electric field installations for meat and dairy processors. EU EFSA scientific opinions on high-pressure treatment create pre-market approval pathways for exporters. Bavarian technician pools maintain Marx generator pulse electronics for continuous-flow dairy systems.
Spain
Hiperbaric leverages its Basque engineering base to dominate high-pressure processing system exports across Europe. REACH regulation updates on food contact materials compel expanded migration testing for polymeric seals. Bilbao-area forging capacity supplies 316L grade steel vessels for 600 MPa cyclic loading applications.
India
FSSAI pathway development for alternative pasteurization guidelines would unlock HPP adoption for domestic mango pulp and lassi processors. Wholesale ingredient suppliers seek non-thermal validation for export qualification to multiple regulatory jurisdictions. Maharashtra and Gujarat processing clusters pilot equipment-as-service models to reduce capital barriers.
Netherlands
Dutch dairy processors adopt continuous-flow PEF systems for extended milk shelf life without protein denaturation. ECHA substance restrictions on phthalate plasticizers force reformulation of dynamic seals in high-pressure vessels. Randstad equipment integrators serve as validation intermediaries between German OEMs and Benelux food manufacturers.
Global Non-Thermal Pasteurization Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue modular equipment-as-service configurations. The vendor base stratifies across three maturity tiers: industrial-scale system integrators with unified validation support, regional specialists in single-technology deployments, and mobile unit operators serving trial-phase beverage brands. Strategic differentiation concentrates on M&A-driven technology portfolio expansion and pay-per-liter contracting structures that reduce capital barriers for mid-size co-packers.
Among Spanish and German industrial equipment fabricators, Hiperbaric and Thyssenkrupp AG exemplify the integrated-systems archetype with continental European manufacturing footprints. JBT Corporation represents the North American diversified equipment provider positioned across multiple non-thermal modalities. These three anchors collectively illustrate how geographic clustering around Basque forging capacity and Ruhr engineering bases shapes competitive positioning in high-pressure and pulsed electric field supply chains.
| Leading Market Players |
|---|
| JBT Corporation |
| Hiperbaric |
| Thyssenkrupp AG |
| Lyras |
| Syntegon |
| Nordion |
| Pulsemaster |
| Elea |
| Stansted Fluid Power |
| Others |
Value Chain & Pricing Dynamics
Beverage procurement teams demanding unified validation support across multiple facilities are compressing vendor margins and forcing OEMs to absorb service costs previously unbundled. This procurement consolidation concentrates pricing power with multinational co-manufacturers while fragmenting equipment procurement decisions toward regional operations managers.
Pricing Analysis
Warranty and validation service bundling now separates premium-tier equipment contracts from economy configurations in non-thermal pasteurization procurement. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by ISO 22000 certification depth and FDA process authority support scope. Cost compression in mid-tier systems is intensifying because Basque and Bavarian technician scarcity extends commissioning timelines. Mid-size beverage co-packers exhibit highest price sensitivity, while multinational food manufacturers prioritize validation reliability over capital expenditure minimization.
Supply Chain Analysis
India's phased manufacturing program and domestic-content mandates for food processing equipment are reshaping sourcing patterns for pressure vessel alloys and pulse electronics. Manufacturing gravity centers on Spain for high-pressure vessel forging, Germany for pulsed electric field system assembly, and the Netherlands for validation intermediary services. Supply chains draw from Swedish 316L steel mills, Japanese high-pressure seal manufacturers, and Basque forging capacity. Single-source vulnerability concentrates in specialized Marx generator component suppliers. Distribution runs through OEM-direct channels for large installations and equipment-as-service platforms for mid-scale beverage co-packers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-thermal pasteurization market is becoming a vertical-integration race, with equipment OEMs pursuing captive control over validation service capabilities to defend margin pools against modular entrants.
For Market Incumbents: Deepen backward integration into high-pressure seal manufacturing to preempt REACH-driven supply disruptions. Incumbent OEMs should consolidate regional validation service networks before mobile HPP unit operators capture mid-tier beverage co-packer relationships. Basque and Ruhr engineering bases provide defensive moats against Asian equipment competitors lacking FDA process authority expertise. For New Entrants and Emerging Players: The price-point gap between premium HPP systems with full validation support and economy-tier thermal retrofits creates entry space for modular equipment-as-service providers. New entrants should target Indian mango pulp and lassi processors awaiting FSSAI pathway finalization. Pay-per-liter contracting structures offer the most penetrable go-to-market angle for capital-constrained mid-size processors. For Investors and Strategic Acquirers: The window for entry favors equipment-as-service platform operators with technician training capabilities. Long-term viability hinges on regulatory harmonization between FDA and EU approval pathways. Investors should monitor EFSA scientific opinion publication timelines as the critical inflection signal for dairy export market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Service Network Expansion | Captures recurring revenue streams from FDA process authority maintenance contracts. |
| Mobile HPP Unit Fleet Deployment | Reduces capital barriers for California and New York cold-pressed juice trial phases. |
| Stainless-Steel Bellows Seal Development | Preempts ECHA phthalate restrictions in 600 MPa cyclic loading applications. |
| Continuous-Flow PEF-UV Integration | Addresses liquid egg pasteurization without protein aggregation for dairy processors. |
| India FSSAI Pathway Partnership | Positions equipment OEMs for mango pulp and lassi processor adoption. |
Study Parameters
Independent corroboration across equipment OEM technical directors, dairy processor quality assurance leads, beverage co-packer procurement managers, and FDA process authority consultants underwrites the qualitative findings. Primary interviews with Basque forging facility engineers and Ruhr Marx generator maintenance technicians combined with secondary validation from EFSA scientific opinions, FDA guidance documents, and EU REACH substance restriction databases. Bottom-up equipment installation tracking and top-down market sizing triangulate volume estimates.
Historical reference periods anchored the forecast window to pre-pandemic capacity expansion cycles and post-regulatory-harmonization adoption waves across the analysis window. Segmentation dimensions modeled include technology readiness tier, application severity, end-user scale, and regional regulatory cluster. CAGRs were derived from equipment shipment trajectories and processor capital expenditure surveys. Forecast inputs incorporated FSSAI pathway development timelines and ECHA substance restriction implementation schedules.
Underlying measurement precision varies by segment; high-pressure processing installation data carries tighter precision than cold plasma pilot project tracking. Forecasts reflect assumptions regarding regulatory harmonization progress and commodity alloy price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Milk Sterilizer Machine Market
Food Processing Equipment
Commercial Panini Machine Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Continuous Fryer Machine Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Fluidized Bed Dryer Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
Electric Brewing System Market
Food Processing Equipment
Portable Clean-In-Place Market