
 India Household Flour Milling Machines Market | 2026-2036
India Household Flour Milling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
India Household Flour Milling Machines Market Insights
Urban household kitchens are shifting toward in-house flour processing as consumers prioritize freshness over packaged alternatives. Natraj dominates the electric mill segment through extensive dealer networks across western India. Shreeji Fine differentiates with compact stone-grinding designs tailored for apartment spaces. Navdeep Appliances competes on after-sales service density in southern states.
India household flour milling machines are compact mechanical or electromechanical devices designed to grind wheat, millet, and pulses into flour using stone, steel, or impact grinding mechanisms with motor capacities typically ranging from 0.5 to 2 horsepower for domestic settings. These machines serve the primary purpose of enabling fresh, preservative-free flour production at the point of consumption. Electric mills lead volume sales due to convenience parity with mixer-grinders already familiar in Indian kitchens. Stone grinding technology sustains premium positioning among consumers who associate slower RPM with nutrient retention. The gluten-free application segment is expanding fastest as health-conscious households seek dedicated contamination-free units.
BIS certification under IS 302-2-14 governs electrical safety for domestic flour mills while the PLI scheme for white goods incentivizes localized component manufacturing. FSSAI guidelines on food contact materials indirectly shape stainless steel grade specifications for grinding chambers. Stakeholders must monitor evolving energy efficiency norms and state-level urban housing density patterns that determine compact product form factors.
Market Dynamics
Urban apartment density in Maharashtra, Gujarat, and Karnataka is compressing kitchen footprints and forcing manufacturers to prioritize sub-10-inch base-diameter stone mills. BIS certification timelines and PLI scheme localization requirements are simultaneously raising compliance costs and reshaping component sourcing patterns across western and southern India.
Growth Catalysts
- PLI Scheme for White Goods:Domestic component manufacturing incentives are reducing import dependence for copper windings and stainless steel grinding chambers. Localized motor production is accelerating supplier ecosystem maturation in Pune and Ahmedabad industrial clusters.
- FSSAI Food Contact Material Guidelines:Preservative-free flour preference is driving demand for dedicated home milling units with certified 304-grade stainless steel chambers. Health-conscious households in tier-2 cities view contamination control as non-negotiable.
- Electric Stone-Grinding Technology:Slower RPM mechanisms that preserve heat-sensitive nutrients are commanding premium positioning. Apartment-dwelling consumers in Bangalore and Hyderabad prioritize compact units that replicate traditional chakki output quality.
Market Restraints
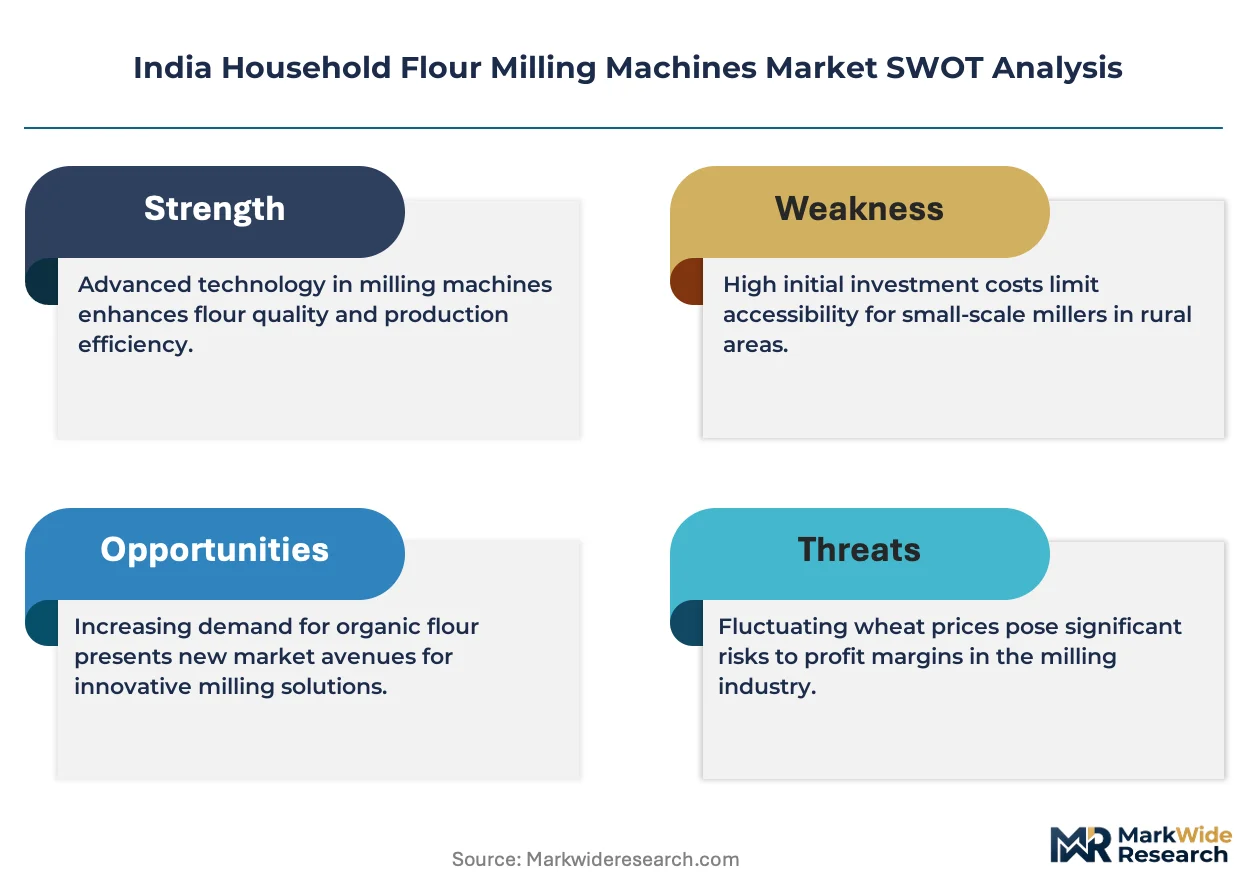
- Copper and Cold-Rolled Steel Price Volatility:Motor winding materials and grinding chamber substrates face commodity input cost swings that compress assembler margins. Price pass-through to end consumers remains constrained by mixer-grinder category price anchors.
- Western India Supply Concentration:Component stamping and motor winding capacity clusters disproportionately in Gujarat and Maharashtra, exposing supply chains to monsoon logistics disruptions and regional labor availability cycles.
- Certification Timeline Friction:BIS IS 302-2-14 testing protocols for electrical safety create 8-12 week approval bottlenecks that delay new model launches and freeze working capital in pre-certified inventory.
Strategic Opportunities
- Tamil Nadu and Kerala Underpenetration:Southern states outside Karnataka show lower electric mill penetration relative to western India. Dedicated after-sales service density investments could unlock apartment-dwelling demand in Chennai and Kochi.
- Gluten-Free Dedicated Units:Health-conscious households seeking contamination-free milling for celiac-safe atta represent an emerging application segment. Separate grinding chamber designs prevent cross-contact with wheat residues.
- Direct-to-Consumer Digital Channels:E-commerce platforms are bypassing traditional dealer networks that currently dominate western India distribution. Urban millennials in tier-2 cities demonstrate higher online purchase willingness for compact kitchen appliances.
Industry Challenges
- Skilled Motor Rewinding Technician Scarcity:After-sales service networks struggle to recruit technicians capable of repairing fractional horsepower motors in domestic flour mills. Service density gaps in southern and eastern states lengthen resolution timelines.
- Legacy Mixer-Grinder Substitution Threat:Multi-purpose appliances with milling attachments compete for countertop space and consumer wallet share. Differentiation requires demonstrating superior atta texture and lower heat generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Household Flour Milling Machines Market |
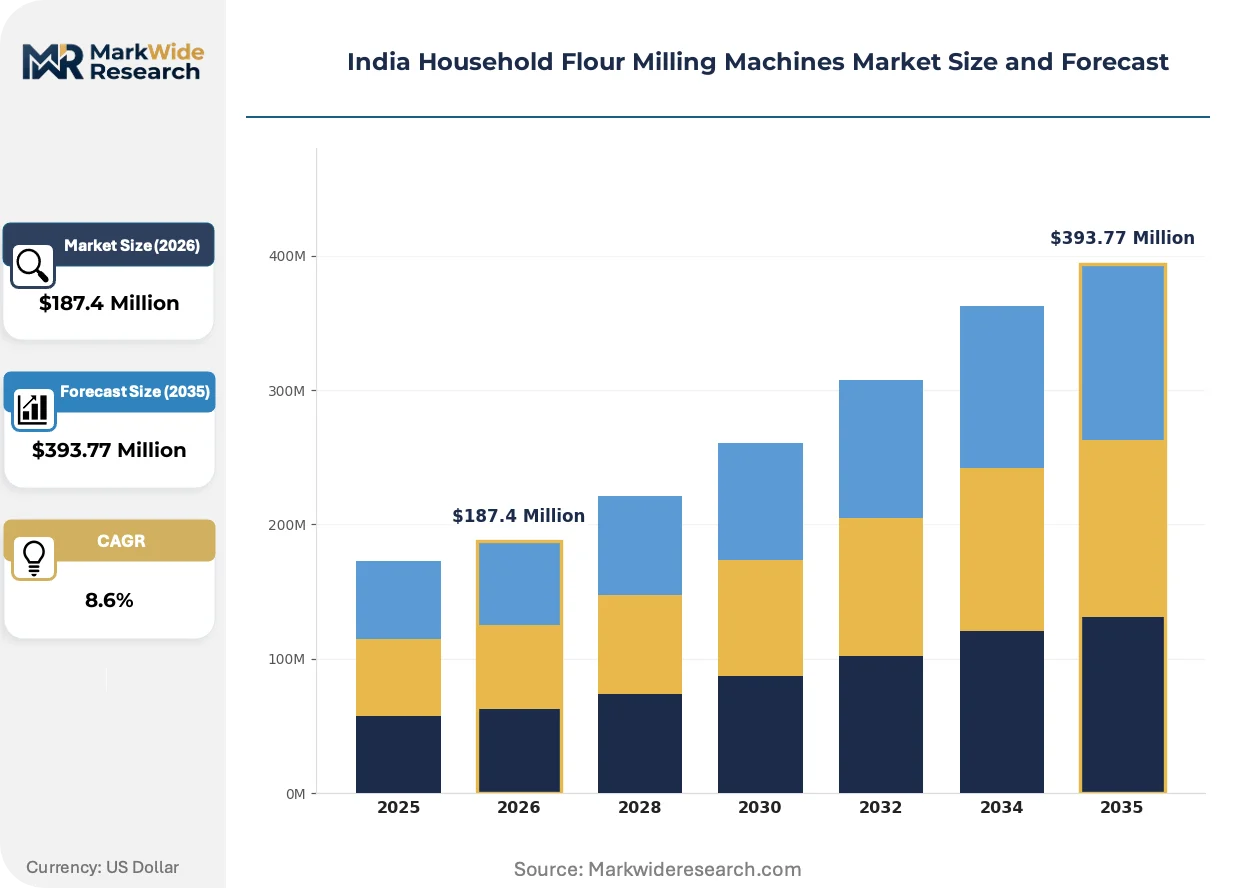
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Mill, Electric Mill, Hybrid Mill, Commercial Mill Application: Domestic Use, Small Scale Production, Organic Grinding, Gluten-Free Flour Technology: Stone Grinding, Steel Grinding, Impact Grinding, Roller Technology End User: Households, Bakeries, Small Businesses, Agricultural Producers |
| Companies Covered | Shreeji Fine, Natraj, Kenayovijay, Navdeep Appliances, Haystar, Milan, Reindeer, Classic Atta Chakki Plus, Navsukh, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Household Flour Milling Machines Market Trends and Innovations
Stone-grinding mechanisms paired with compact electric motors are displacing traditional manual chakkis in urban Indian kitchens. Regulatory pressure on food contact materials and energy efficiency is simultaneously elevating product specifications and manufacturing complexity.
Brushless DC motor technology is rewriting power efficiency benchmarks for domestic flour mills. Tier-2 city households adopting these units reduce electricity consumption per kilogram of atta ground by approximately one-third compared to universal motor designs. The technology is compressing total cost of ownership calculations and accelerating replacement cycles in Maharashtra and Gujarat.
BIS IS 302-2-14 electrical safety mandates are tightening insulation and thermal protection requirements for all domestic flour mill imports and domestic production. Testing laboratory capacity constraints in Mumbai and Delhi are extending certification timelines and freezing new entrant pipeline plans. Established assemblers with in-house compliance teams are widening their time-to-market advantage.
After-sales service unbundling is disrupting traditional dealer-margin models in Karnataka and Telangana. Urban consumers increasingly purchase mills through e-commerce platforms and separately contract local technicians for installation and maintenance. Channel fragmentation is compressing distributor profitability and forcing manufacturers to build direct service networks or certify third-party repair aggregators.
India Household Flour Milling Machines Market Segmentation
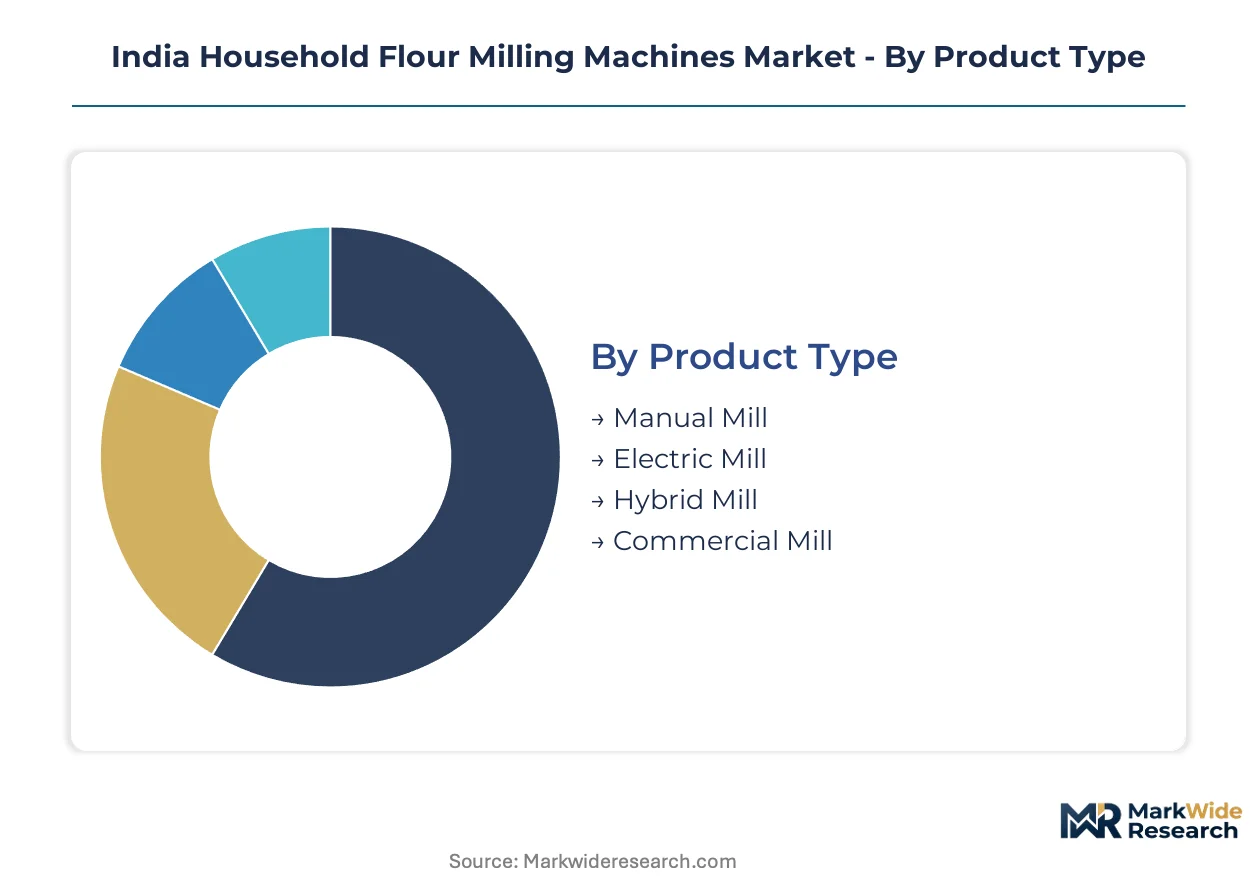
Segmentation in the India household flour milling machines market reveals how urban kitchen constraints, health preferences, and power infrastructure quality shape purchase decisions across Maharashtra, Gujarat, and Karnataka. Buyers trade off between stone-grinding authenticity and electric convenience based on apartment size and electricity reliability.
Product Type:
Households prioritize operational convenience against countertop space constraints when selecting mill configurations.
- Electric Mill:Units with 0.5 to 2 horsepower universal or brushless DC motors dominate apartment kitchens in Bangalore and Pune. FSSAI-certified 304-grade stainless steel chambers address contamination concerns in tier-2 cities where preservative-free flour preference is strongest.
- Manual Mill:Traditional hand-operated chakkis persist in semi-urban Maharashtra where electricity reliability varies seasonally. Lower acquisition cost sustains penetration among price-sensitive households outside major metropolitan corridors.
- Hybrid Mill:Dual-mode units switch between manual and electric operation. Compact designs target consumers in Gujarat seeking backup functionality during monsoon power disruptions.
- Commercial Mill:Higher-capacity units exceed domestic kitchen specifications. Limited household adoption concentrates in agricultural producer settings with dedicated utility spaces.
Volume sits with Electric Mill; growth tilts toward Hybrid Mill.
Application:
End-use purpose determines grinding chamber material certification requirements and motor duty cycle specifications.
- Domestic Use:Daily atta preparation for 4-6 member households drives baseline demand. BIS IS 302-2-14 electrical safety compliance is non-negotiable for apartment installations in Hyderabad and Chennai.
- Gluten-Free Flour:Dedicated contamination-free units with separate grinding chambers serve celiac-conscious households. Karnataka health-conscious consumers pay premium pricing for wheat-residue isolation.
- Small Scale Production:Home-based entrepreneurs in Gujarat process specialty grains for local market sale. Higher duty cycles demand enhanced thermal protection in motor windings.
- Organic Grinding:Chemical-free grain processing attracts environmentally positioned buyers. Slower RPM stone mechanisms align with nutrient retention marketing claims.
Domestic Use captures current volume; Gluten-Free Flour is climbing the fastest.
Technology:
Grinding mechanism selection reflects heat sensitivity concerns and texture quality expectations.
- Stone Grinding:Granite or synthetic stone pairs with reduced RPM electric motors to minimize heat generation. Premium positioning in Maharashtra targets consumers associating slower grinding with nutrient preservation.
- Steel Grinding:Stainless steel burr mechanisms deliver faster processing with coarser texture output. Cost-conscious households in tier-2 Gujarat cities accept texture trade-offs for price accessibility.
- Impact Grinding:High-speed blade systems pulverize grains through collision rather than abrasion. Higher noise levels and heat generation limit adoption in noise-sensitive apartment environments.
- Roller Technology:Precision gap-adjustable rollers produce consistent particle distribution. Complexity and maintenance requirements restrict penetration beyond enthusiast segments.
Steel Grinding holds installed base; Stone Grinding gains share fastest.
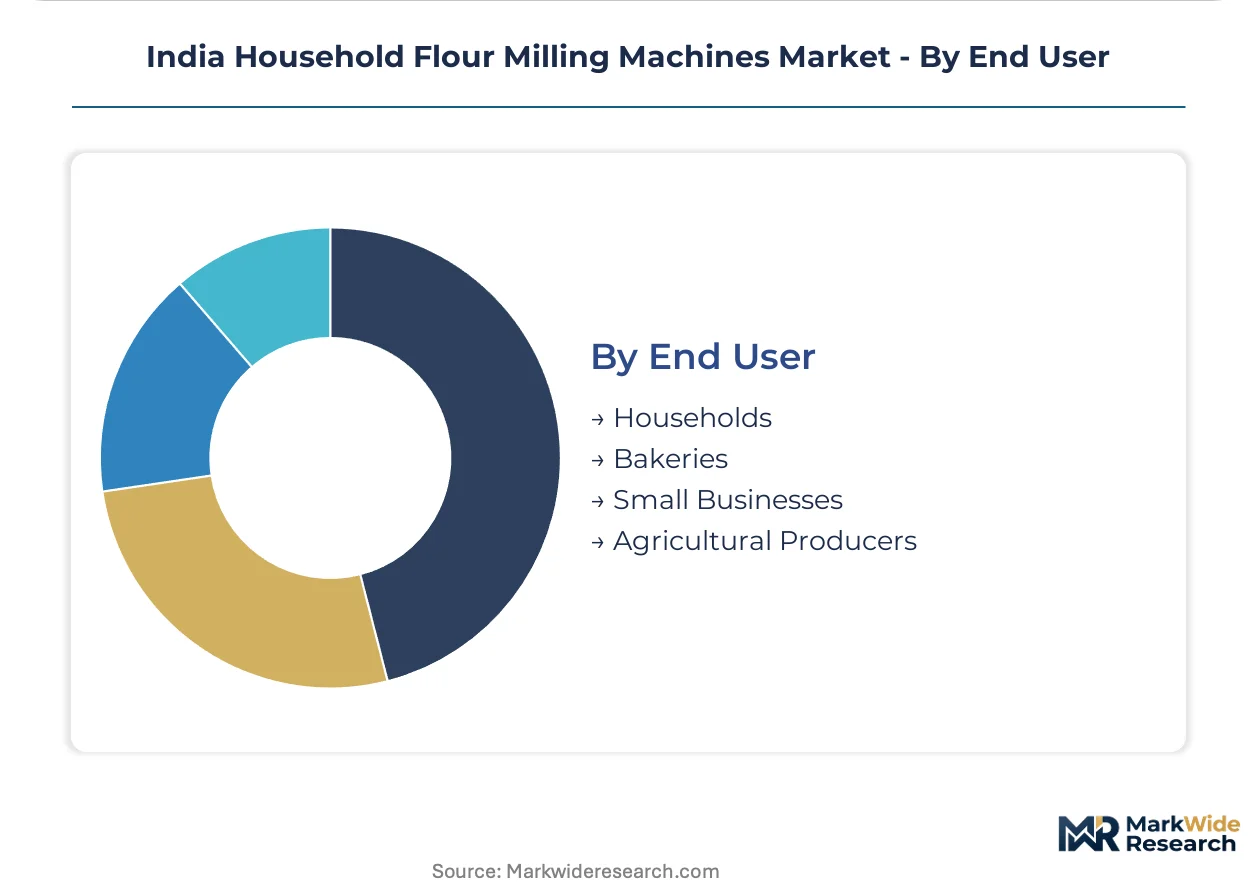
End User:
Customer type dictates service network density requirements and warranty term expectations.
- Households:Individual consumers in Karnataka and Telangana drive compact form factor prioritization. After-sales service unbundling through e-commerce channels is reshaping purchase behavior.
- Small Businesses:Home-based food entrepreneurs require higher duty cycles and extended warranty coverage. Dealer network proximity influences brand selection in western India.
- Bakeries:Commercial kitchen installations demand certified food contact materials and higher throughput capacity. FSSAI compliance documentation requirements exceed standard household specifications.
- Agricultural Producers:Farm-residence installations prioritize durability over compact dimensions. Three-phase power availability determines motor configuration feasibility.
Households anchor current demand; Small Businesses show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level PLI scheme disbursements and BIS certification infrastructure are concentrating manufacturing capacity in designated industrial corridors across western and southern India.
Maharashtra
Pune and Mumbai industrial belts host the densest cluster of motor winding and stamping facilities serving domestic flour mill assemblers. BIS testing laboratory capacity in Mumbai accelerates IS 302-2-14 certification timelines for western India vendors. Thane district suppliers specialize in fractional horsepower motor production for compact stone-grinding units.
Gujarat
Ahmedabad and Vadodara engineering clusters dominate cold-rolled steel grinding chamber fabrication. FSSAI food contact material compliance drives 304-grade stainless steel sourcing standardization across Surat-based component vendors. Monsoon logistics disruptions periodically constrain just-in-time delivery to Maharashtra assembly plants.
Karnataka
Bangalore apartment density compresses kitchen footprints and prioritizes sub-10-inch base-diameter electric mills. After-sales service unbundling through e-commerce channels reshapes traditional dealer-margin models in Hyderabad-influenced Telangana border markets. Mysuru stone-grinding mechanism suppliers partner with brushless DC motor integrators.
Tamil Nadu
Chennai metropolitan households show lower electric mill penetration relative to western India benchmarks. CDSCO medical device regulatory infrastructure indirectly supports precision manufacturing capability transferable to flour mill component production. Coimbatore motor winding technician training institutes address skilled repair personnel scarcity.
Telangana
Hyderabad's tier-2 city expansion drives demand for compact hybrid mills with manual backup functionality. State urban housing density patterns favor countertop appliances under 15 kilograms. Secunderabad industrial estates host emerging supplier ecosystems for copper winding localization.
India Household Flour Milling Machines Market Competitive Landscape
Top-tier vendors anchor western India distribution networks, while mid-tier assemblers compete on after-sales service density. The market structures around three strategic archetypes: legacy chakki brands with dealer heritage, electric appliance specialists leveraging mixer-grinder channel familiarity, and compact design innovators targeting apartment kitchens. Dominant competitive moves include geographic expansion into underpenetrated southern states and portfolio diversification into gluten-free dedicated units.
Among India-based domestic appliance fabricators, Natraj, Shreeji Fine, and Navdeep Appliances exemplify contrasting market positioning strategies. Natraj occupies the extensive dealer network archetype with western India penetration density. Shreeji Fine represents the compact stone-grinding design specialization for space-constrained urban kitchens. Navdeep Appliances sits within the after-sales service density competitive vector, particularly across southern state markets where technician availability determines brand selection.
| Leading Market Players |
|---|
| Shreeji Fine |
| Natraj |
| Kenayovijay |
| Navdeep Appliances |
| Haystar |
| Milan |
| Reindeer |
| Classic Atta Chakki Plus |
| Navsukh |
| Others |
Pricing and Supply Chain Analysis
Skilled motor rewinding technician concentration in western Maharashtra and Gujarat compresses service labor costs for domestic mill assemblers while widening pricing-tier spreads between premium BIS-certified units and economy-grade alternatives lacking certified repair networks.
Pricing Analysis
Short lead-time premiums command pricing power for BIS IS 302-2-14 pre-certified inventory held by established western India assemblers. Three-tier pricing structure across premium stone-grinding, standard steel-burr, and economy impact-blade configurations differentiates on FSSAI chamber certification and brushless DC motor inclusion. Pricing pressure stems from copper winding commodity volatility that assemblers struggle to pass through given mixer-grinder category price anchors. Tier-2 city households in Gujarat exhibit highest price sensitivity; Bangalore apartment-dwellers purchasing gluten-free dedicated units show lowest.
Supply Chain Analysis
Direct-to-dealer channels dominate western India distribution with dealer-margin models under pressure from e-commerce unbundling. Component supply concentrates in India with Pune motor winding clusters, Ahmedabad cold-rolled steel stamping, and Surat stainless steel chamber fabrication drawing from Gujarat and Maharashtra industrial belts. Raw material dependencies center on copper windings, 304-grade stainless steel, and synthetic grinding stones. Single-source vulnerability concentrates in monsoon-exposed logistics corridors linking Gujarat component vendors to Maharashtra assembly plants. Distribution runs through multi-tier dealer networks with direct-to-consumer digital channels gaining share in southern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS certification under IS 302-2-14 creates a structural cost-of-compliance barrier that entrenches incumbents with in-house testing capabilities while freezing capital for new entrants awaiting Mumbai laboratory capacity.
For Market Incumbents: Acquire certified third-party repair aggregator networks to defend service density advantages against e-commerce channel unbundling in Karnataka and Telangana. Deepen backward integration into brushless DC motor production within Pune industrial clusters to offset copper price volatility exposure. Priority rests on locking BIS testing laboratory relationships to maintain time-to-market gaps over emerging competitors awaiting certification slots. For New Entrants and Emerging Players: Capture Tamil Nadu and Kerala apartment-dwelling demand where electric mill penetration lags western India benchmarks by investing in dedicated after-sales technician training partnerships with Coimbatore institutes. Target gluten-free dedicated unit white space where contamination-free chamber designs command premium positioning among health-conscious households. Go-to-market leverage sits with direct-to-consumer digital channels bypassing entrenched dealer networks. For Investors and Strategic Acquirers: Re-rating potential sits with compact design specialists possessing FSSAI-certified 304-grade stainless steel chamber capabilities given brushless DC motor technology acceleration. Long-term viability favors assemblers with geographic diversification beyond western India supply concentration and regulatory compliance infrastructure hardened against BIS timeline friction. Signal to monitor: state-level urban housing density mandates compressing kitchen footprints below 10-inch base-diameter specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Production | Captive copper winding supply in Pune clusters insulates margins from commodity volatility. |
| Gluten-Free Dedicated Unit Launch | Separate grinding chamber designs unlock premium positioning among celiac-conscious Karnataka households. |
| Direct-to-Consumer Digital Channel Expansion | E-commerce platforms bypass dealer-margin compression in Telangana and Tamil Nadu markets. |
| After-Sales Service Network Certification | Third-party technician aggregation addresses skilled repair scarcity in southern states. |
| Compact Form Factor R&D Investment | Sub-10-inch base-diameter designs align with Bangalore apartment kitchen constraints. |
Research Methodology
Trade association filings, BIS certification registries, and FSSAI food contact material compliance databases formed the secondary backbone for market sizing and competitive mapping. Primary interviews with domestic flour mill assemblers, component suppliers in Pune and Ahmedabad industrial clusters, and aftermarket service technicians across Maharashtra and Karnataka validated production volumes and pricing dynamics. Bottom-up triangulation against top-down household penetration estimates anchored forecast reliability.
Bottom-up modeling aggregated unit shipments by product type, technology, and end-user segment across the projection horizon. Segmentation dimensions included grinding mechanism, motor configuration, application purpose, and state-level urban density patterns. CAGRs derived from fitted growth curves incorporating PLI scheme disbursement timelines and apartment household formation rates. Brushless DC motor adoption curves and BIS certification pipeline constraints shaped trajectory assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper commodity cycles, monsoon logistics disruption severity, and state-level urban housing policy shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Tube Ice Machine Market
Food Processing Equipment
Industrial Graters Market
Food Processing Equipment
Seafood Processing Equipment Market
Food Processing Equipment
Food Industry Vacuum Cooling Equipment Market
Food Processing Equipment
Tangyuan Machine Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Ice Cream Processing Equipment Market
Food Processing Equipment
Food Irradiation Equipment Market
Food Processing Equipment
Global Food Dehydrators Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Food Extrusion Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Destemmer Market