
 Global Industrial Food Blanchers Market | 2026-2036
Global Industrial Food Blanchers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Food Blanchers Market Outlook
Modular system configuration is hardening as the dominant procurement pattern among mid-scale processors. Cabinplant leverages its integrated conveyor-blancher-cooler lines to anchor European vegetable processing contracts. Lyco Manufacturing competes through specialized rotary drum designs that sustain repeat orders from North American frozen food producers.
Industrial food blanchers are thermal processing units that expose fruits, vegetables, or proteins to steam, hot water, or microwave energy at temperatures typically between 85°C and 100°C for controlled dwell times to inactivate enzymes, reduce microbial load, and preserve color prior to freezing, drying, or further processing. Automated systems now dominate new capital expenditure as labor costs rise and throughput consistency becomes non-negotiable for food processing companies operating multi-shift schedules. Hot water blanchers retain the largest installed base but face margin pressure from steam blanchers, which offer superior energy recovery and reduced leaching of water-soluble nutrients.
The FDA enforces equipment sanitation standards under 21 CFR Part 110, while the EU's Machinery Directive 2006/42/EC mandates CE-marked safety interlocks and hygienic design principles for food-contact surfaces. The EU's F-Gas Regulation additionally shapes refrigerant-linked blancher-cooler integration decisions across European installations. Stakeholders must weigh total cost of ownership against regulatory compliance timelines when selecting between retrofit paths and greenfield automated deployments.
Market Dynamics
Automated steam blanching systems are compressing capital deployment cycles as frozen vegetable processors race to meet energy-efficiency mandates and throughput guarantees in multi-shift operations.
Growth Catalysts
- EU F-Gas Regulation:Equipment replacement deadlines are accelerating upgrades to refrigerant-integrated blancher-cooler lines across German and Dutch processing facilities.
- Frozen vegetable throughput targets:Large-scale processors are retrofitting legacy hot water systems with continuous steam units to achieve consistent dwell-time precision.
- Enzyme inactivation requirements:Peroxidase and lipoxygenase deactivation standards for color retention are tightening specification sheets for thermal processing equipment.
Market Restraints
- Stainless steel input volatility:Grade 316L sheet and sanitary tubing price swings compress margin visibility for European fabricators quoting long-lead contracts.
- CE-marked component concentration:Safety interlock and hygienic-design certified parts cluster among German and Italian subsystem suppliers, creating single-source exposure.
- Water treatment burden:Hot water blancher effluent discharge regulations in California and the Netherlands impose secondary capital loads on installed base owners.
Strategic Opportunities
- India frozen food infrastructure:Cold chain expansion and quick-service restaurant supply contracts are creating first-mover openings for automated blanching line vendors.
- Microwave-steam hybrid convergence:Combination systems targeting nutrient retention are penetrating premium organic vegetable processing segments.
- US FDA Food Safety Modernization Act:Preventive controls mandates are driving preventive maintenance service contract attachment rates on new equipment sales.
Industry Challenges
- Sanitary welding certification timelines:ASME BPE and 3-A SSI qualification delays for field service technicians extend commissioning schedules.
- Legacy Allen-Bradley integration:Retrofit projects face protocol translation complexity when connecting new steam blanchers to existing SCADA architectures.
- Multi-shift maintenance staffing:Thermodynamics and controls specialization scarcity inflates service contractor rates in Midwest US processing corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Food Blanchers Market |
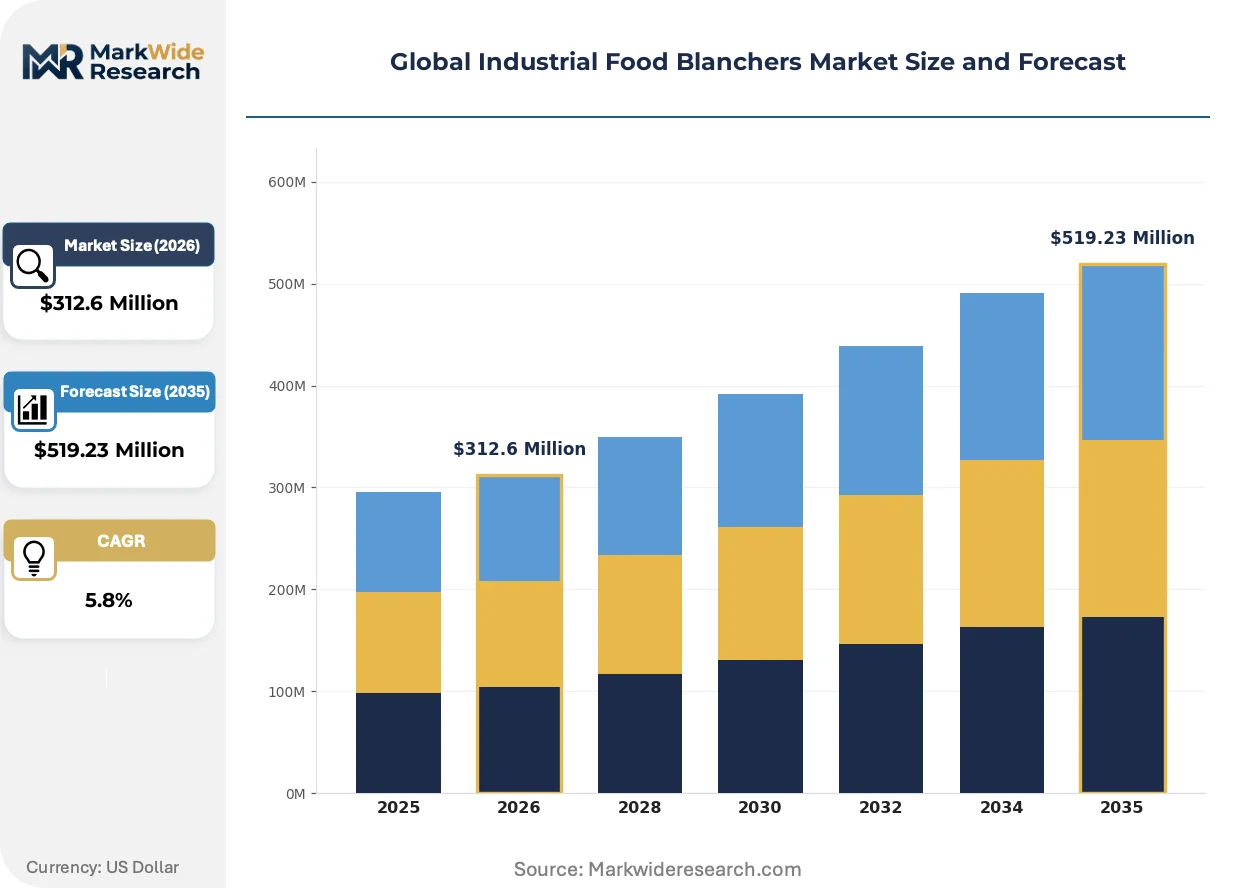
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Blanchers, Hot Water Blanchers, Microwave Blanchers, Chemical Blanchers End User: Food Processing Companies, Restaurants, Catering Services, Supermarkets Technology: Automated Systems, Semi-Automated Systems, Manual Systems, Hybrid Systems Capacity: Small Scale, Medium Scale, Large Scale, Customizable Capacity |
| Companies Covered | Cabinplant, Lyco Manufacturing, Turatti Group, DTS, ABCO Industries, Blentech, Boema, Dodman, Ezma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Food Blanchers Market Strategic Shifts
Thermal processing equipment is pivoting from commodity hardware sales toward integrated performance contracts, with automation depth and energy recovery metrics now dominating competitive bids.
Steam blanchers with closed-loop heat recovery are overtaking open hot water designs in new European installations. Frozen broccoli and spinach processors in Germany and Belgium are specifying these units to meet corporate carbon reduction pledges. The technology is overtaking conventional steam injection by capturing exhaust vapor to preheat incoming product streams, compressing per-ton energy costs by double-digit percentages.
The EU's F-Gas Regulation is banning hydrofluorocarbon refrigerants in new industrial cooling equipment from 2030. Blancher-cooler integrated lines must now specify natural refrigerant architectures or face retrofit liability. Vegetable processors in the Netherlands and Denmark are front-loading these upgrades to avoid stranded asset risk.
Performance-based service agreements are displacing traditional break-fix maintenance contracts in North American frozen food operations. Large-scale processors in Wisconsin and Washington State are unbundling equipment purchase from uptime guarantees, instead contracting thermal throughput per operating hour. This shift concentrates vendor selection on predictive analytics capability and regional spare parts inventory depth.
Global Industrial Food Blanchers Market Segmentation
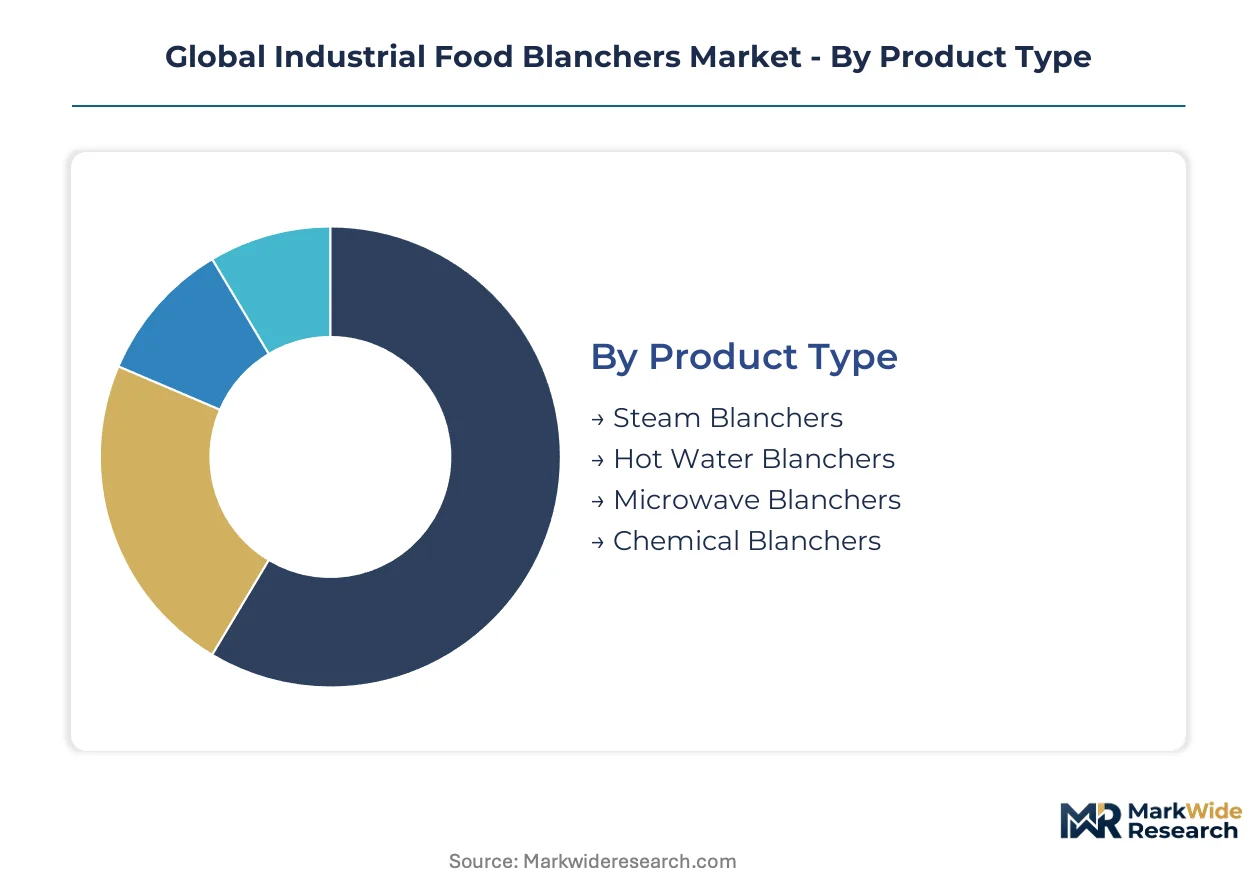
Industrial food blanchers fragment across four critical dimensions that determine capital allocation patterns and vendor selection criteria. Equipment specification varies sharply by thermal medium, operational scale, and automation depth, with each configuration carrying distinct regulatory certification burdens and total cost of ownership profiles.
Product Type:
Steam blanchers require CE marking under the EU Machinery Directive and 3-A SSI sanitary standards for food-contact surfaces, while microwave units face additional FCC emissions compliance in the US and IEC 60335-2-90 safety certifications. Hot water and chemical systems carry lighter electromagnetic regulatory loads but heavier water treatment and effluent discharge obligations.
- Steam Blanchers:Closed-loop heat recovery systems capture exhaust vapor to preheat incoming product streams, compressing per-ton energy costs. German and Belgian frozen broccoli processors specify these units to meet corporate carbon reduction pledges and EU F-Gas Regulation timelines. The technology dominates new European installations.
- Hot Water Blanchers:Open immersion designs retain the largest installed base globally but face margin pressure from steam alternatives. California and Dutch processors confront secondary capital loads from effluent discharge regulations, accelerating replacement cycles.
- Microwave Blanchers:Rapid volumetric heating reduces dwell times for delicate fruits and premium organic vegetables. Systems require shielding compliance and precise power control architectures.
- Chemical Blanchers:Lye or acid-based enzyme inactivation serves niche applications in tropical fruit processing where thermal damage risks color degradation. Handling protocols demand OSHA-process safety management integration.
Leading the category by volume: Hot Water Blanchers. Expanding most quickly: Steam Blanchers.
End User:
Procurement authority concentrates differently across customer tiers, with food processing companies commanding multi-million dollar capital budgets and centralized engineering teams while foodservice operators prioritize footprint minimization and lease financing.
- Food Processing Companies:Frozen vegetable specialists in Wisconsin and Washington State unbundle equipment purchase from uptime guarantees, contracting thermal throughput per operating hour instead. Predictive analytics capability and regional spare parts inventory depth determine vendor selection.
- Restaurants:Central kitchen operations and commissary models drive demand for compact batch units with rapid changeover between vegetable SKUs. Lease financing predominates over outright purchase.
- Catering Services:Event-scale volume fluctuations favor modular equipment configurations that scale with contract seasonality. Maintenance outsourcing rates exceed in-house staffing economics.
- Supermarkets:Private-label ready-meal programs and in-store production kitchens create mid-scale automation openings. Food safety liability concerns elevate hygienic design specifications.
Food Processing Companies command the largest equipment budgets. Catering Services show the steepest expansion trajectory from a smaller base.
Technology:
Automation depth directly correlates with labor cost exposure and throughput consistency requirements, with multi-shift operations mandating programmable logic controllers and SCADA integration while single-shift facilities tolerate simpler architectures.
- Automated Systems:Continuous rotary drum or belt designs with precise dwell-time control dominate new capital expenditure as labor costs rise. Allen-Bradley protocol integration complexity creates retrofit friction in legacy facilities.
- Semi-Automated Systems:Batch loading with automated temperature and timing control serves mid-scale processors bridging manual and fully automatic operations. Training burdens concentrate on HMI navigation.
- Manual Systems:Basket immersion with operator-controlled timing persists in developing market entry installations and specialty product microprocessors. Capital barriers remain lowest.
- Hybrid Systems:Microwave-steam combination configurations target nutrient retention in premium organic vegetable segments. Dual energy architectures multiply maintenance specialization requirements.
Automated Systems anchor current procurement volumes. Hybrid Systems are gaining share fastest among technology-forward processors.
Capacity:
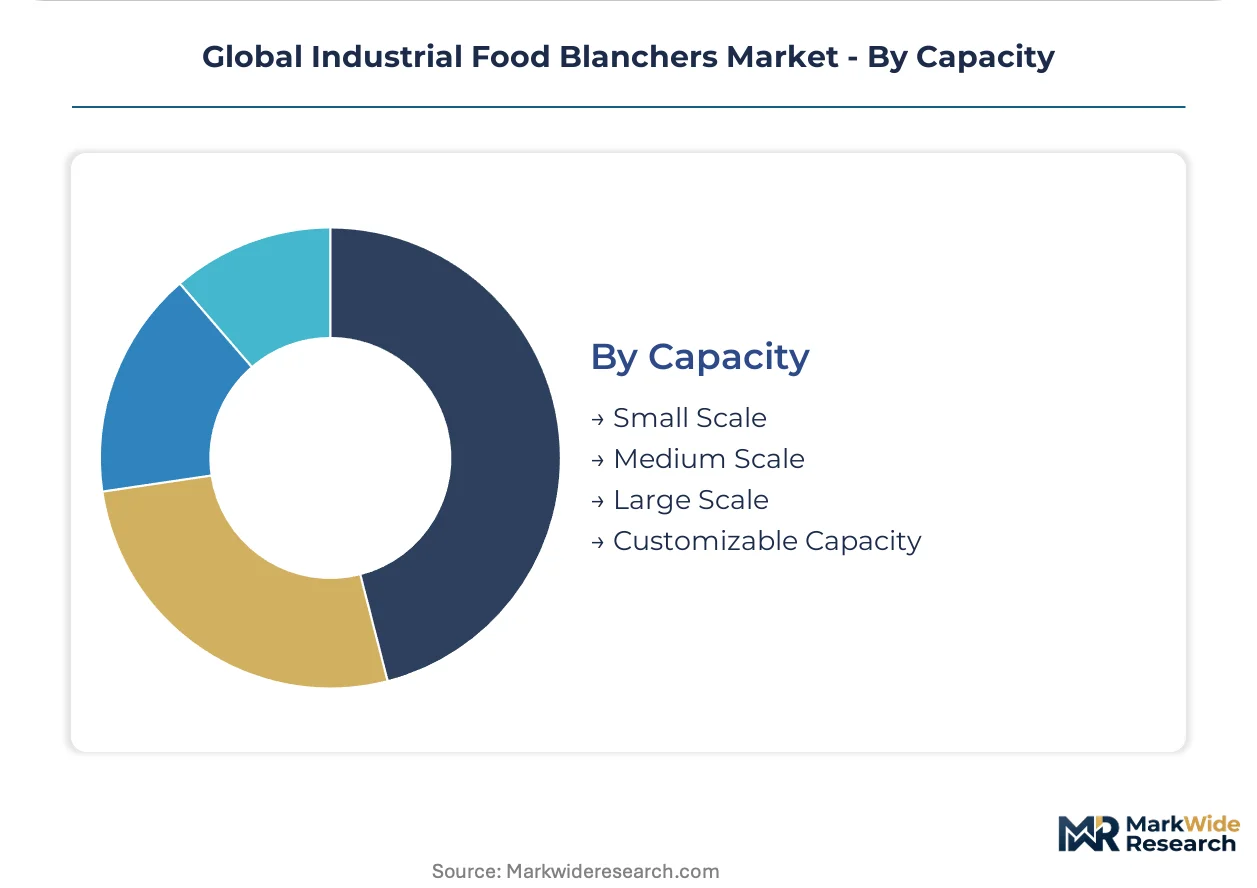
Scale selection reflects throughput guarantees, facility footprint constraints, and batch versus continuous processing economics, with modular expandable designs penetrating mid-market accounts seeking growth optionality.
- Small Scale:Batch units processing under 500 kg per hour serve specialty organic processors and pilot-scale product development kitchens. Sanitary welding certification timelines for field technicians extend commissioning schedules.
- Medium Scale:Continuous belt or rotary designs processing 500-2,000 kg per hour anchor European vegetable processing contracts through integrated conveyor-blancher-cooler lines. Modular system configuration hardens as the dominant procurement pattern.
- Large Scale:Multi-ton per hour steam injection systems with heat recovery serve German and Dutch facilities retrofitting for EU F-Gas Regulation compliance. Energy-efficiency mandates and throughput guarantees compress capital deployment cycles.
- Customizable Capacity:Expandable frame designs with field-upgradeable heating zones and belt widths preserve capital flexibility. Indian frozen food infrastructure expansion creates first-mover openings for scalable line vendors.
Large Scale equipment generates the highest revenue concentration. Customizable Capacity configurations show the steepest demand curve acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate Indian frozen food infrastructure investment, while German industrial parks anchor European equipment retrofit cycles. Tax incentives in these designated zones compress capital deployment timelines for automated blanching lines.
United States
Frozen vegetable processors in Wisconsin and Washington State drive demand for performance-based service agreements unbundled from equipment purchase. The FDA enforces preventive controls under the Food Safety Modernization Act, accelerating preventive maintenance contract attachment rates. Midwest processing corridors face thermodynamics specialist scarcity that inflates service contractor rates.
Germany
Large-scale processors in Lower Saxony and Bavaria retrofit facilities with energy-efficient steam blanchers to meet corporate carbon reduction pledges. The EU's F-Gas Regulation mandates refrigerant-integrated blancher-cooler upgrades by 2030, front-loading capital cycles. Industrial clusters around Hamburg and Stuttgart concentrate equipment fabrication and subsystem supplier networks.
Netherlands
Vegetable processors in Flevoland and Gelderland front-load blancher-cooler upgrades to avoid stranded asset risk from EU F-Gas Regulation deadlines. Dutch effluent discharge regulations impose secondary capital loads on hot water blancher operators, accelerating replacement toward steam alternatives. Wageningen-area research corridors pilot microwave-steam hybrid configurations.
India
Cold chain expansion and quick-service restaurant supply contracts in Gujarat and Maharashtra create first-mover openings for automated blanching line vendors. The FSSAI tightens food safety equipment standards under integrated food safety protocols. Mundra and JNPT special economic zones concentrate import infrastructure for European and East Asian equipment fabricators.
Belgium
Frozen broccoli and spinach processors in Flanders specify closed-loop heat recovery steam blanchers to meet EU energy-efficiency mandates. The EU Machinery Directive 2006/42/EC mandates CE-marked safety interlocks and hygienic design principles. Ghent and Leuven industrial zones anchor vegetable processing contract concentration for integrated conveyor-blancher-cooler lines.
Global Industrial Food Blanchers Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across equipment fabrication and subsystem supply tiers. Market structure tilts toward consolidation at the integrated line level while fragmenting among component suppliers. Three archetypes dominate: European turnkey system integrators, North American specialized drum fabricators, and Asian scale-oriented machinery producers. Strategic moves concentrate on geographic expansion into Indian frozen food infrastructure and technology licensing for microwave-steam hybrid architectures.
Among European turnkey specialists, Cabinplant anchors integrated conveyor-blancher-cooler contract positions, while Turatti Group occupies a comparable tier in Italian vegetable processing equipment. Lyco Manufacturing exemplifies the North American specialized fabricator archetype focused on rotary drum configurations. These three represent distinct geographic and technical positioning strategies without overlapping core market footprints.
| Leading Market Players |
|---|
| Cabinplant |
| Lyco Manufacturing |
| Turatti Group |
| DTS |
| ABCO Industries |
| Blentech |
| Boema |
| Dodman |
| Ezma |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators in northern Italy and southern Germany anchor component supply for European blancher assembly, concentrating pricing power among CE-certified subsystem specialists while compressing margin visibility for buyers negotiating long-lead stainless steel contracts.
Pricing Analysis
Margin tightening in standard-grade equipment traces to Grade 316L sheet price volatility and concentrated safety interlock sourcing from German and Italian suppliers. Three-tier pricing structure across heat-recovery premium, continuous standard, and batch economy levels stratifies by automation depth and energy-efficiency certification. Cost-down pressure on hot water blanchers accelerates because Dutch and Californian effluent regulations impose secondary capital burdens. Frozen vegetable processors in multi-shift operations show least price sensitivity; catering services and supermarket commissaries exhibit highest elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle large-scale processor demand in Germany, Belgium, and the Netherlands, while distributor networks serve mid-scale retrofit projects in India and North America. Component fabrication concentrates in Germany, Italy, and Denmark, with stainless steel raw material draws from Finnish and Swedish mills. Single-source vulnerability clusters around CE-marked hygienic-design interlocks and ASME BPE-certified sanitary welding subcontractors. Distribution runs through equipment integrators with captive service capabilities for aftermarket parts and commissioning support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial food blanchers market is consolidating around automated steam systems as EU F-Gas Regulation deadlines strand legacy refrigerant-integrated assets and compress replacement cycles for undercapitalized competitors.
For Market Incumbents: Extend predictive analytics service capabilities to capture performance-based contract expansion in Wisconsin and Washington State frozen vegetable corridors. Deepen backward integration into heat-recovery subsystem production to defend margin position against stainless steel input volatility. Prioritize ASME BPE and 3-A SSI certification investment to compress commissioning timelines and differentiate from emerging Asian competitors. For New Entrants and Emerging Players: Digital-channel routes through quick-service restaurant procurement platforms offer low-friction entry into Indian frozen food infrastructure expansion in Gujarat and Maharashtra special economic zones. Target customizable-capacity modular configurations for mid-scale processors seeking growth optionality without greenfield capital commitment. Lead with microwave-steam hybrid technology licensing to penetrate premium organic vegetable segments in Belgium and the Netherlands. For Investors and Strategic Acquirers: Distressed-cycle entries favor European turnkey specialists with stranded hot water blancher installed base exposure in the Netherlands and California. Long-term viability over the mid-decade window hinges on refrigerant-integrated line upgrade completion and regional spare parts inventory depth. Watch preventive maintenance contract attachment rates as the signal for vendor selection consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Recovery Subsystems | Captures margin from energy-efficiency mandates in German frozen vegetable processing. |
| Performance-Based Service Contract Expansion | Locks in multi-year revenue from Wisconsin and Washington State throughput guarantees. |
| CE-Marked Safety Interlock Certification Investment | Reduces single-source exposure for European fabricators quoting long-lead contracts. |
| Microwave-Steam Hybrid Technology Licensing | Penetrates premium organic segments with nutrient retention specifications in Belgium. |
| Regional Spare Parts Inventory Buildout | Supports uptime guarantees required by FDA preventive controls mandates in US Midwest. |
Study Parameters
Independent corroboration across plant engineers at frozen vegetable processors, procurement leads at equipment OEMs, aftermarket service heads, and regulatory compliance officers underwrites the qualitative findings. Primary interviews with maintenance directors and SCADA integration specialists combined with secondary validation from FDA 21 CFR Part 110 guidance documents, EU Machinery Directive 2006/42/EC technical files, FSSAI equipment standards, and customs data on stainless steel trade flows. Bottom-up equipment shipment tracking and top-down food processing capital expenditure analysis triangulate market sizing.
Comparable-period anchoring to historical blancher replacement cycles and frozen vegetable production capacity expansion underpins the projection framework. Segmentation modeling spans thermal medium, automation depth, capacity tier, and end-user procurement authority across the analysis window. CAGRs derive from regression against energy-efficiency mandate implementation timelines and throughput guarantee contract penetration. Industry-specific inputs include EU F-Gas Regulation compliance cost curves and peroxidase inactivation specification tightening trajectories.
The model holds under stable stainless steel pricing and gradual labor cost inflation; deviation in tariff exposure on Grade 316L sheet or accelerated F-Gas Regulation enforcement would shift replacement cycle timing. Forecasts reflect documented assumptions on multi-shift operation penetration and service contract unbundling rates. Periodic stress-testing of base assumptions against regulatory amendment announcements and commodity price corridors is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Hydrostatic Steam Blancher Market
Food Processing Equipment
Mill Mixer Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Non-Thermal Food Processing Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Brewing Equipment Market
Food Processing Equipment
North America Ginger Processing Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market