
 Pulp Washing Equipment Market | 2026-2036
Pulp Washing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pulp Washing Equipment Market Analytics
Packaging producers is pivoting toward higher-capacity washing lines as e-commerce corrugated demand reshapes fiber sourcing. Valmet leverages its automation-integrated washer platforms to sustain technology leadership in Nordic installations. ANDRITZ anchors its position through chemical recovery coupling with washing stages. Kadant Inc. differentiates via doctoring and cleaning accessories that extend washer runnability.
Pulp washing equipment encompasses mechanical and chemical systems designed to separate spent liquors, debris, and non-fiber constituents from cellulose fibers, typically operating at consistencies from 3% to 18% and temperatures exceeding 80°C to optimize diffusion washing efficiency. The primary purpose centers on maximizing yield while minimizing water consumption and effluent load prior to bleaching or papermaking. Continuous washers dominate capital deployment among product types due to throughput advantages in integrated mills, while modular systems within installation type categories attract greenfield projects seeking compressed commissioning timelines. Chemical treatment technology commands premium positioning where mills pursue closed-cycle operation.
EPA effluent limitation guidelines shape washer design specifications in United States pulp mills, while EU Green Deal industrial emissions frameworks drive water recycling intensity requirements across European installations. China's MEE enforces stricter COD discharge thresholds that push mills toward multi-stage washing configurations. Stakeholders must monitor regulatory divergence between jurisdictions when standardizing equipment platforms across multinational mill portfolios.
Market Dynamics
Closed-loop washing architectures are displacing open-water systems as pulp mills face mounting effluent discharge limits and water scarcity constraints in major production basins.
Growth Catalysts
- EU Green Deal industrial emissions standards:Tighter COD and AOX thresholds for pulp mill effluents are forcing equipment upgrades across Nordic and Iberian installations.
- E-commerce corrugated demand:Packaging producers in Brazil and Southeast Asia are expanding kraft pulp capacity, requiring high-throughput washing trains.
- Diffusion washing technology:Multi-stage displacement washers are capturing share from vacuum drum systems due to superior liquor removal efficiency at lower dilution factors.
Market Restraints
- Stainless steel alloy volatility:Super-austenitic grades required for chloride-rich washing environments face price swings tied to nickel and molybdenum markets.
- Specialized fabricator concentration:Heavy pressure vessel fabrication for large-scale washers concentrates among a handful of European and East Asian suppliers.
- Mechanical pulping substitution:Thermomechanical pulp processes require less intensive washing than chemical pulping, compressing addressable equipment demand in certain fiber segments.
Strategic Opportunities
- Indonesia pulp investment wave:Greenfield mill projects in Sumatra and Kalimantan present first-mover positioning for modular washing system suppliers.
- Water reuse mandates:China's MEE circular economy directives for pulp and paper are creating demand for tertiary treatment-integrated washing configurations.
- Digital twin convergence:Coupling washer simulations with distributed control systems enables predictive consistency management and chemical optimization.
Industry Challenges
- Process control engineering scarcity:Mill automation teams lack depth in model-predictive control for multi-variable washing processes.
- Legacy DCS integration:Brownfield installations face protocol mismatches between modern washer controls and aging distributed control architectures.
- Commissioning timeline compression:Compressed startup schedules for greenfield mills strain vendor field service capacity and risk performance guarantee disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulp Washing Equipment Market |
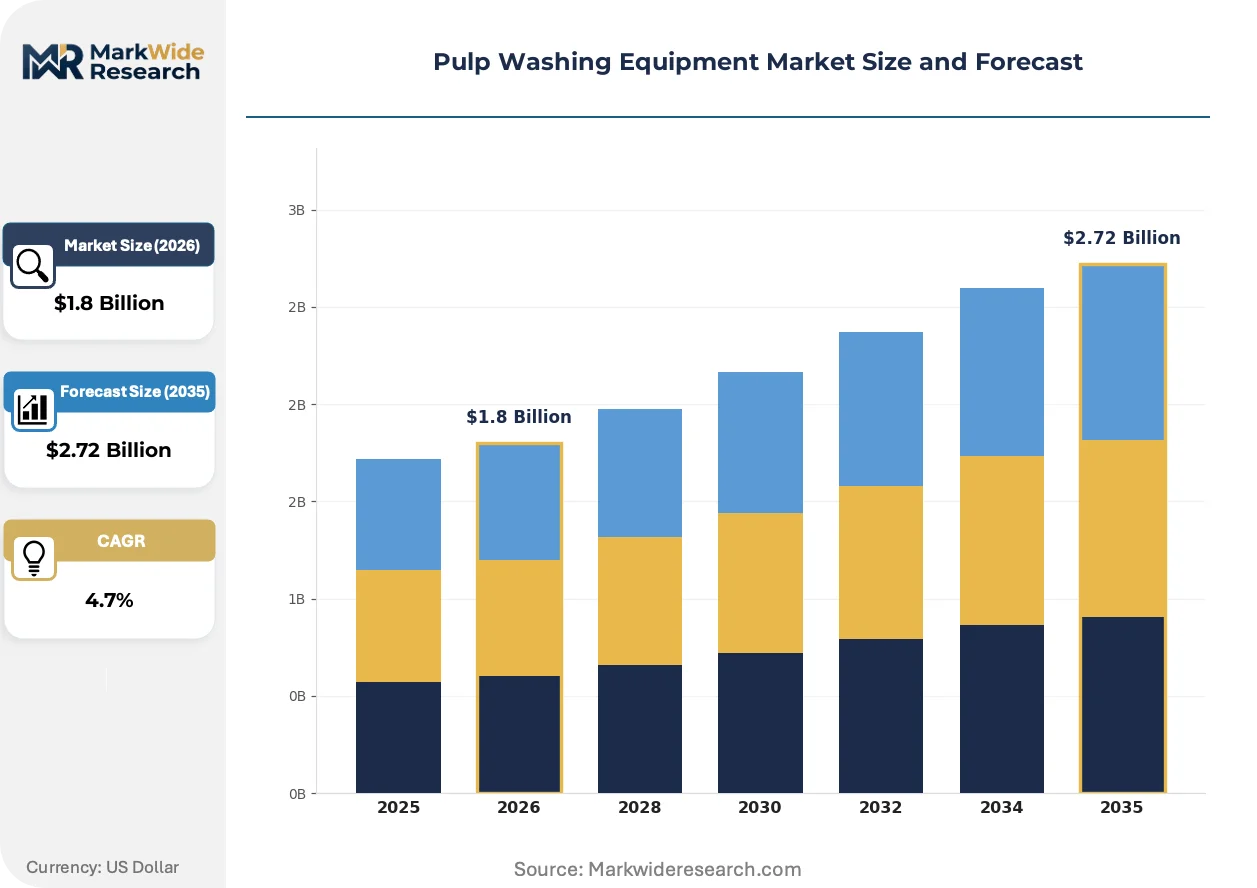
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Washers, Batch Washers, High-Consistency Washers, Vacuum Washers End User: Pulp Mills, Paper Manufacturers, Packaging Producers, Board Manufacturers Technology: Mechanical Separation, Chemical Treatment, Thermal Process, Biological Treatment Installation Type: Onsite Installation, Prefabricated Units, Modular Systems, Custom Builds |
| Companies Covered | Valmet, ANDRITZ, Kadant Inc., Voith Group, GL&V, Anyang Machinery Co., Ltd., Leizhan Paper Pulp Machinery Company, Zhengzhou Guangmao Machinery Manufacture Co. LTD, Comertek S.r.l., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulp Washing Equipment Market Evolving Landscape
Automation layer sophistication is separating competitive tiers as mills demand real-time washing efficiency optimization rather than static equipment specifications.
Advanced sensor arrays combining microwave consistency transmitters with near-infrared liquor concentration probes are integrating into closed-loop washer control strategies. Nordic kraft mills are deploying these packages fastest, with full-fiberline integration timelines compressing from 18 months to under 12 months. The technology is integrating operational technology and information technology layers, collapsing the traditional separation between process engineering and mill automation teams.
EPA effluent limitation guidelines for pulp and paper point sources are tightening thermal discharge and color parameters beyond traditional BOD and TSS metrics. US mills are responding with counter-current washing intensification and filtrate segregation systems that isolate high-heat streams for energy recovery. Bleached board producers in the Southeast face the steepest compliance ramps, driving capital allocation toward washing stage redesign ahead of biological treatment expansion.
Lifecycle service contracting is displacing transactional spare parts procurement as the dominant vendor-customer commercial arrangement. Major pulp groups are unbundling maintenance execution from equipment supply, awarding multi-year runnability contracts to specialist service providers. This restructuring concentrates most visibly in Finnish and Swedish mill clusters, where integrated producers seek to outsource non-core mechanical reliability functions.
Pulp Washing Equipment Market Segmentation
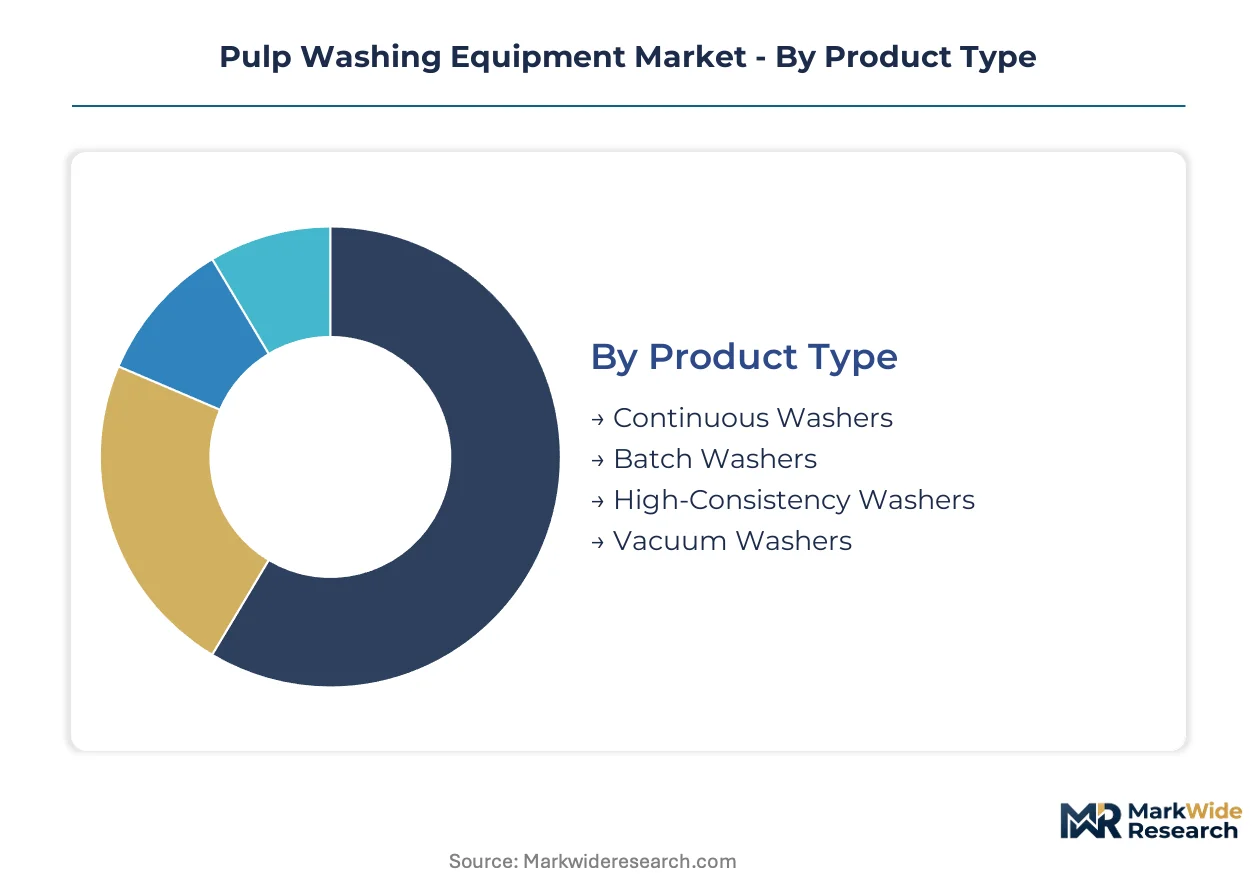
Pulp washing equipment buyers face divergent capital allocation pressures depending on mill vintage, fiberline scale, and regulatory exposure. Segment boundaries increasingly blur as suppliers bundle chemical recovery, automation, and water treatment into integrated platforms.
Product Type:
Throughput requirements and liquor removal efficiency separate buyers with integrated kraft lines from specialty pulp producers.
- Continuous Washers:These systems operate at consistencies from 3% to 18% with counter-current displacement configurations that maximize yield while minimizing dilution factors. Nordic and Brazilian integrated mills deploy these for bleached kraft expansion projects where EPA and EU Green Deal effluent limits demand minimal freshwater intake.
- High-Consistency Washers:Operating above 12% consistency, these units reduce water heating loads and downstream evaporation demands. Southeast Asian packaging producers favor them for e-commerce corrugated fiberlines where energy recovery economics outweigh higher capital outlays.
- Batch Washers:Smaller-scale dissolving pulp operations use these for specialty cellulose grades requiring precise temperature and chemical profile control.
- Vacuum Washers:Drum-based systems retain installed base in older North American mills facing brownfield automation upgrades rather than greenfield replacement.
Volume sits with Continuous Washers; growth tilts toward High-Consistency Washers.
End User:
Capital cycle timing and fiber sourcing strategy determine equipment specification intensity across buyer categories.
- Pulp Mills:Standalone chemical pulp producers specify multi-stage washing trains with closed-loop filtrate recovery and automated consistency control. Finnish and Swedish mills lead adoption of microwave transmitter arrays for real-time optimization.
- Packaging Producers:Corrugated board integrators prioritize throughput over liquor recovery sophistication, driving demand for compressed commissioning timelines and modular system architectures in Brazil and Indonesia.
- Paper Manufacturers:Fine paper mills balance washing intensity against brightness targets, often retrofitting existing lines with diffusion washing stages.
- Board Manufacturers:Containerboard producers focus on contaminant removal for recycled fiber streams rather than chemical pulp washing depth.
Pulp Mills dominate capital deployment; Packaging Producers are expanding most quickly.
Technology:
Environmental compliance stringency and water scarcity exposure push buyers toward process intensification beyond mechanical separation alone.
- Chemical Treatment:Oxidative and extractive stages integrated with washing loops enable closed-cycle operation. EU Green Deal industrial emissions standards and China's MEE circular economy directives accelerate adoption where effluent discharge faces strict COD thresholds.
- Mechanical Separation:Screening, pressing, and centrifugal systems remain baseline configurations for mills without bleaching stages or with relaxed discharge permits.
- Thermal Process:Evaporation-integrated washing recovers heat from spent liquors, appealing to mills with captive energy generation.
- Biological Treatment:Tertiary polishing of filtrate streams addresses emerging color and toxicity parameters in EPA guideline updates.
Mechanical Separation retains the largest installed base; Chemical Treatment shows the steepest expansion trajectory.
Installation Type:
Project delivery risk allocation and site constraints shape procurement preferences between standardized and engineered solutions.
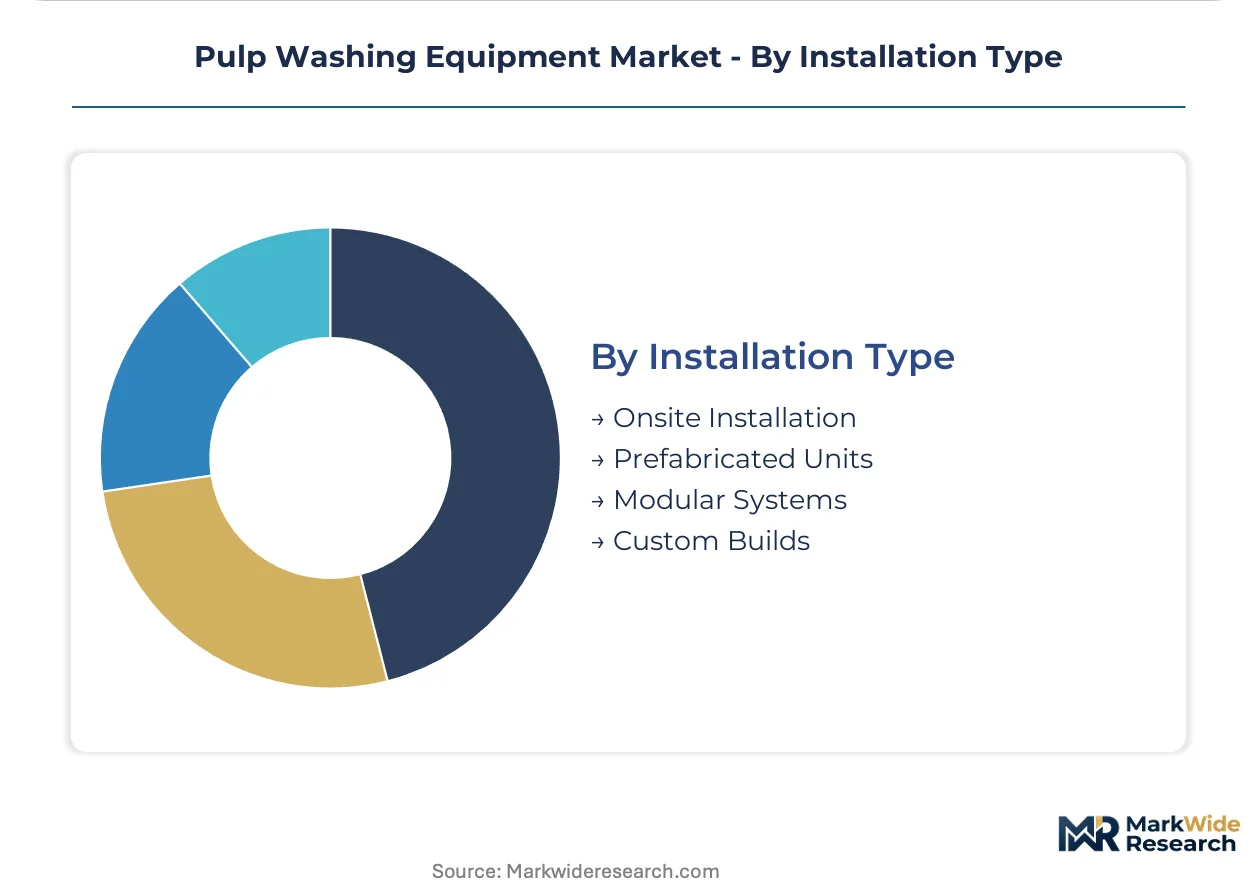
- Modular Systems:Pre-assembled skids with integrated piping and instrumentation compress field construction schedules. Greenfield mills in Indonesia and Brazil specify these to mitigate commissioning timeline risks and vendor service capacity constraints.
- Custom Builds:Brownfield European mills with legacy DCS architectures require protocol-matched controls and vessel geometries adapted to existing building envelopes.
- Prefabricated Units:Mid-scale projects balance standardization with site-specific adaptation through semi-modular approaches.
- Onsite Installation:Full stick-built construction persists where local content requirements or oversized components preclude factory assembly.
Custom Builds anchor revenue; Modular Systems gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Southeast Asia and Nordic industrial corridors concentrate greenfield pulp mill investments. Brazil's tax-advantaged manufacturing regions anchor Latin American capacity expansion. Finland, Sweden, and Indonesia each host distinct regulatory frameworks shaping equipment procurement patterns.
United States
Southeast bleached board producers drive washing stage redesigns ahead of biological treatment expansion. EPA effluent limitation guidelines tighten thermal discharge and color parameters beyond traditional BOD and TSS metrics. Georgia and Alabama containerboard clusters intensify counter-current washing configurations for energy recovery.
Finland
Integrated pulp groups outsource non-core mechanical reliability functions through multi-year runnability contracts. EU Green Deal industrial emissions standards enforce tighter COD and AOX thresholds across Nordic installations. The Kemi-Tornio industrial corridor leads adoption of microwave transmitter arrays for real-time washing optimization.
Sweden
Specialty cellulose producers specify batch washing systems for precise temperature and chemical profile control. EU Green Deal frameworks accelerate closed-cycle operation investments. The Sundsvall timber processing belt concentrates dissolving pulp operations requiring extended washing trains.
Brazil
E-commerce corrugated demand reshapes fiber sourcing strategies across packaging producers. ANVISA environmental compliance protocols align with EU-equivalent effluent standards for export-oriented mills. The São Paulo state pulp belt expands high-throughput washing trains for bleached kraft capacity additions.
Indonesia
Greenfield mill projects in Sumatra and Kalimantan present first-mover positioning opportunities for modular system suppliers. MEE circular economy directives from China create reference standards for regional water reuse mandates. The Riau Islands special economic zone compresses commissioning timelines through pre-assembled skid specifications.
Pulp Washing Equipment Market Competitive Landscape
Top-tier vendors anchor integrated automation platforms, while mid-tier fabricators compete on modular delivery speed and localized service presence. The vendor structure concentrates around three strategic archetypes: full-line system integrators coupling washing with chemical recovery, component specialists extending washer runnability through accessories, and regional machinery builders capturing greenfield projects in emerging pulp basins. Competitive moves center on lifecycle service contracting restructuring and digital twin convergence with distributed control architectures.
Among Nordic-based full-line integrators, Valmet and ANDRITZ exemplify the automation-coupled archetype, while Kadant Inc. occupies a position among runnability specialists. Chinese fabricators including Anyang Machinery Co., Ltd. and Leizhan Paper Pulp Machinery Company represent the regional machinery builder tier. Voith Group and GL&V sit within the European engineering conglomerate segment. Zhengzhou Guangmao Machinery Manufacture Co. LTD anchors the Central China supplier cluster. Comertek S.r.l. exemplifies the Italian specialist fabricator model.
| Leading Market Players |
|---|
| Valmet |
| ANDRITZ |
| Kadant Inc. |
| Voith Group |
| GL&V |
| Anyang Machinery Co., Ltd. |
| Leizhan Paper Pulp Machinery Company |
| Zhengzhou Guangmao Machinery Manufacture Co. LTD |
| Comertek S.r.l. |
| Others |
Value Network & Pricing Analysis
Pressure vessel welder concentration in Finland and Sweden creates labor-cost differentials that widen pricing-tier spreads between Nordic-engineered systems and Asian-fabricated alternatives. EU Green Deal compliance engineering premiums compound this stratification as mills prioritize certified installations.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to modular skid systems with compressed commissioning schedules, while spot inventory of standard vacuum washer components trades at discounts. Project-based contracting dominates capital sales, with price differentiation resting on automation integration depth and chemical recovery coupling. Cost compression in economy-tier drum washers intensifies due to Chinese fabricator capacity expansion. Packaging producers in Indonesia and Brazil exhibit highest price sensitivity, whereas Nordic integrated pulp mills prioritize runnability guarantees over capital outlay minimization.
Supply Chain Analysis
Refurbishment flows of legacy vacuum washer drums from North American mills feed secondary markets in Latin America, creating reverse-logistics revenue streams for specialist service providers. Super-austenitic stainless steel supply concentrates in Germany, Japan, and Sweden, with nickel and molybdenum price volatility anchoring raw material cost uncertainty. Heavy fabrication draws from specialized European and East Asian pressure vessel shops. Single-source vulnerability persists for large-diameter washer shells exceeding transportable road limits. Distribution runs through mill-direct procurement for greenfield projects and aftermarket parts distributors for brownfield maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU Green Deal compliance costs force smaller fabricators without automation integration capabilities toward exit or acquisition.
For Market Incumbents: Deepen captive control over super-austenitic alloy supply through offtake agreements with German and Japanese steel mills, insulating margin positions from nickel volatility. Expand field service density in Indonesia's Riau Islands corridor to capture lifecycle contracting restructuring as greenfield mills outsource mechanical reliability. Thermomechanical pulp substitution threatens chemical washing intensity in packaging grades; counter with diffusion washing efficiency demonstrations in kraft linerboard applications. For New Entrants and Emerging Players: Specialty dissolving pulp producers in Sweden's Sundsvall belt present an underserved buyer archetype seeking batch washer precision without full-line vendor dependency. Modular system architecture for compressed commissioning timelines offers the most penetrable entry vector against established Nordic integrators. Pursue partnership positioning with Indonesian EPC contractors to bypass direct competition with Valmet and ANDRITZ in integrated automation platforms. For Investors and Strategic Acquirers: Re-rating potential sits with regional machinery builders possessing captive fabrication capacity and emerging-market service presence given Indonesia pulp investment wave acceleration. Five-to-ten year viability favors suppliers with backward integration into pressure vessel manufacturing and forward integration into digital twin offerings. Monitor EPA effluent guideline thermal discharge parameter tightening as signal for US Southeast bleached board producer capital allocation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Service Contracting Restructuring | Multi-year runnability agreements in Finnish and Swedish mill clusters outsource non-core mechanical reliability functions to specialist providers. |
| Digital Twin Convergence | Washer simulation coupling with distributed control systems enables predictive consistency management for Nordic kraft producers. |
| Modular System Architecture | Pre-assembled skid specifications compress commissioning timelines for greenfield mills in Indonesia's Riau Islands zone. |
| Super-Austenitic Alloy Supply Securement | Captive offtake agreements with German and Japanese steel mills insulate margin positions from nickel and molybdenum volatility. |
| Chemical Recovery Coupling | Integrated washing and recovery platforms align with EU Green Deal closed-cycle operation mandates across Nordic installations. |
Research Methodology
Multi-period observation of pulp mill capital expenditure cycles, effluent regulatory enforcement intensity, and stainless steel alloy price movements anchored the trend analysis, supplemented by interviews with maintenance directors at integrated kraft mills, OEM procurement teams specifying washing trains, aftermarket service heads managing runnability contracts, and plant engineers overseeing brownfield automation upgrades. Secondary validation drew from EPA effluent limitation guideline filings, EU ETS industrial emissions framework documents, Chinese MEE circular economy directives, customs records of pressure vessel imports, and SEC 10-K disclosures from publicly traded pulp groups. Bottom-up equipment shipment tracking and top-down mill capacity expansion databases underwent triangulation.
Segment-weighting across product type, end user, technology, installation type, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from slope analysis of historical capital deployment patterns projected across the analysis window, with diffusion washing technology penetration curves and closed-loop water recycling mandate compliance timelines serving as industry-specific forecast inputs.
Revisions become necessary when EU Green Deal implementation timelines accelerate, Indonesian greenfield project financing faces disruption, or super-austenitic alloy supply concentrates further through mill consolidation. Practitioners should monitor EPA thermal discharge parameter rulemaking progress and Chinese MEE COD threshold enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Plastic Processing Equipment Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Pan Feeder Market
Food Processing Equipment
Food Processor Market
Food Processing Equipment
Food Recycling Machines Market
Food Processing Equipment
Contact and Convective Dryers Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Europe Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Global Non Thermal Processing Market
Food Processing Equipment
Beverage Processing Equipment Market