
 Clean in Place Market | 2026-2036
Clean in Place Market Size, Share, and Industry Trends Forecast 2026-2036
Clean in Place Market Intelligence
A divergence in capital intensity between providers of fully integrated systems and specialized component suppliers is reorganizing the competitive landscape. Large players like GEA Group and Alfa Laval leverage substantial engineering resources to deliver complex, turnkey solutions for major international food and beverage clients. Ecolab, by contrast, differentiates through its chemical expertise and a service-led model, often integrating its specialized cleaning agents with third-party hardware.
Clean in Place (CIP) refers to automated methods for cleaning the interior surfaces of process equipment and pipelines without disassembly. These systems use a multi-step process involving specific fluid velocities, temperatures, and chemical concentrations to ensure microbial and residue removal. Automated systems command the highest value due to their precision and validation capabilities, particularly within the pharmaceutical vertical. In the technology segment, advanced monitoring systems are gaining share, driven by the need for real-time data on cleaning efficacy and resource consumption.
Regulatory mandates from bodies like the US FDA and the European Medicines Agency enforce stringent aseptic processing standards in pharmaceuticals, directly compelling CIP system adoption. In food and beverage, regulations from authorities such as India's FSSAI are tightening hygiene requirements, pushing processors away from manual cleaning. Future system design will center on optimizing the trade-off between resource consumption and validated cleaning effectiveness.
Market Dynamics
The market's structure is defined by the convergence of stringent regulatory mandates for process validation and the economic need for higher asset utilization. This dual pressure forces a move from manual cleaning toward automated, data-driven CIP systems.
Growth Catalysts
- Regulatory Enforcement:Stricter mandates from bodies like India's FSSAI and Europe's EFSA push food processors toward automated CIP to meet hygiene standards.
- Continuous Manufacturing:The pharmaceutical sector's pivot to continuous processing requires integrated, validated CIP systems to maintain aseptic conditions without downtime.
- Bioprocessing Hub Growth:Expansion of biopharmaceutical and dairy clusters in India demands scalable, high-purity CIP installations for new large-scale production lines.
Market Restraints
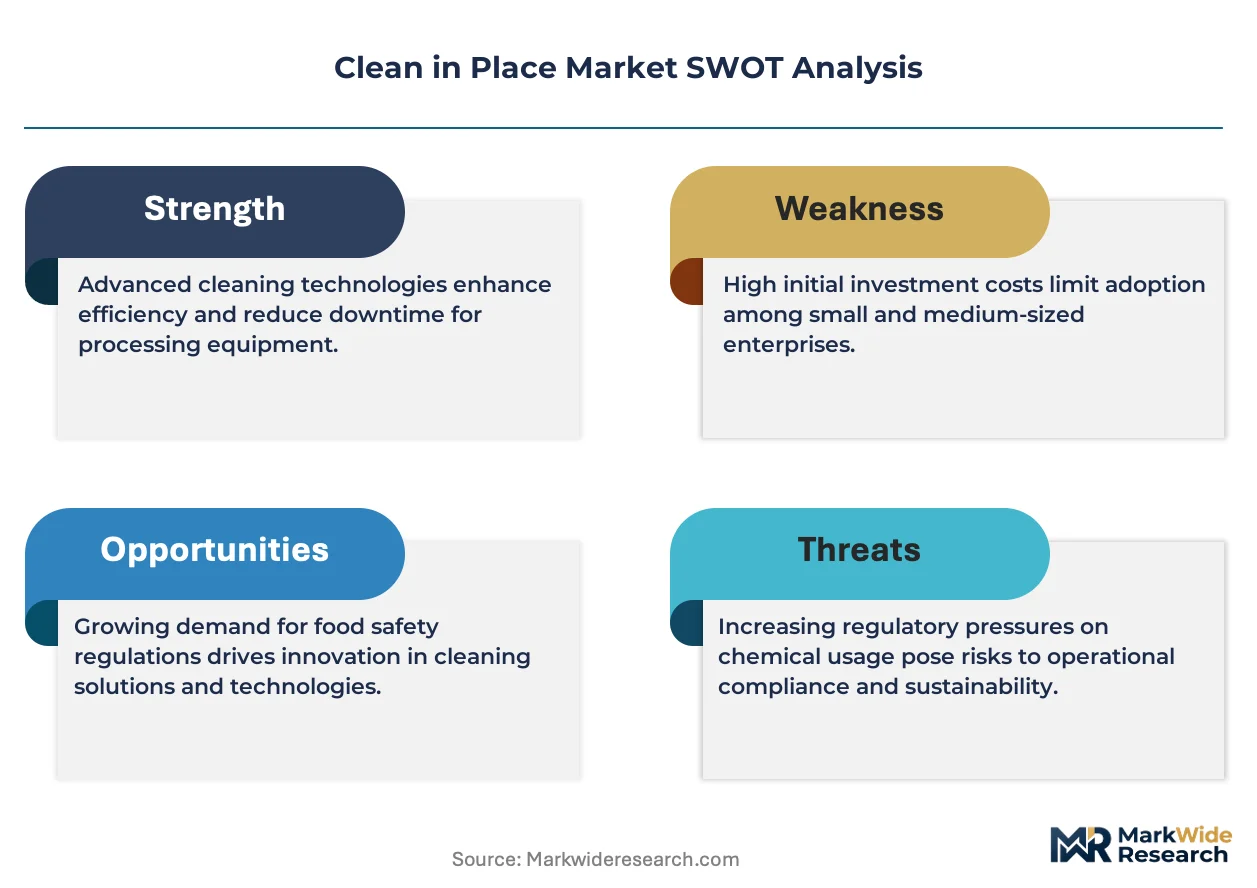
- High Capital Expenditure:The significant upfront investment for automated CIP systems is a barrier for small and medium-sized food processors.
- Resource Intensity:High consumption of water, energy, and chemicals creates operational cost pressures, limiting adoption in regions with resource scarcity.
- Viability of Manual Methods:In less-regulated segments, continued reliance on lower-cost manual cleaning and Clean-Out-of-Place (COP) methods slows automated system adoption.
Strategic Opportunities
- Smart System Integration:Integrating IoT sensors and AI analytics can optimize resource use, predict maintenance, and provide real-time validation data for pharmaceutical clients.
- Modular Systems for SMEs:Developing cost-effective, modular CIP skids for craft brewing and small-scale dairy addresses an underpenetrated market segment.
- Water Reclamation Technologies:Regulatory incentives for water conservation create a market for CIP systems with advanced water recovery and reuse features.
Industry Challenges
- Specialized Skills Gap:A shortage of technicians trained in validating, operating, and maintaining complex automated CIP systems, especially those with advanced sensor technology, constrains effective deployment.
- Legacy System Integration:Integrating new, automated CIP skids with existing, often decades-old, process equipment and control systems in brownfield facilities presents significant technical and validation challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean in Place Market |
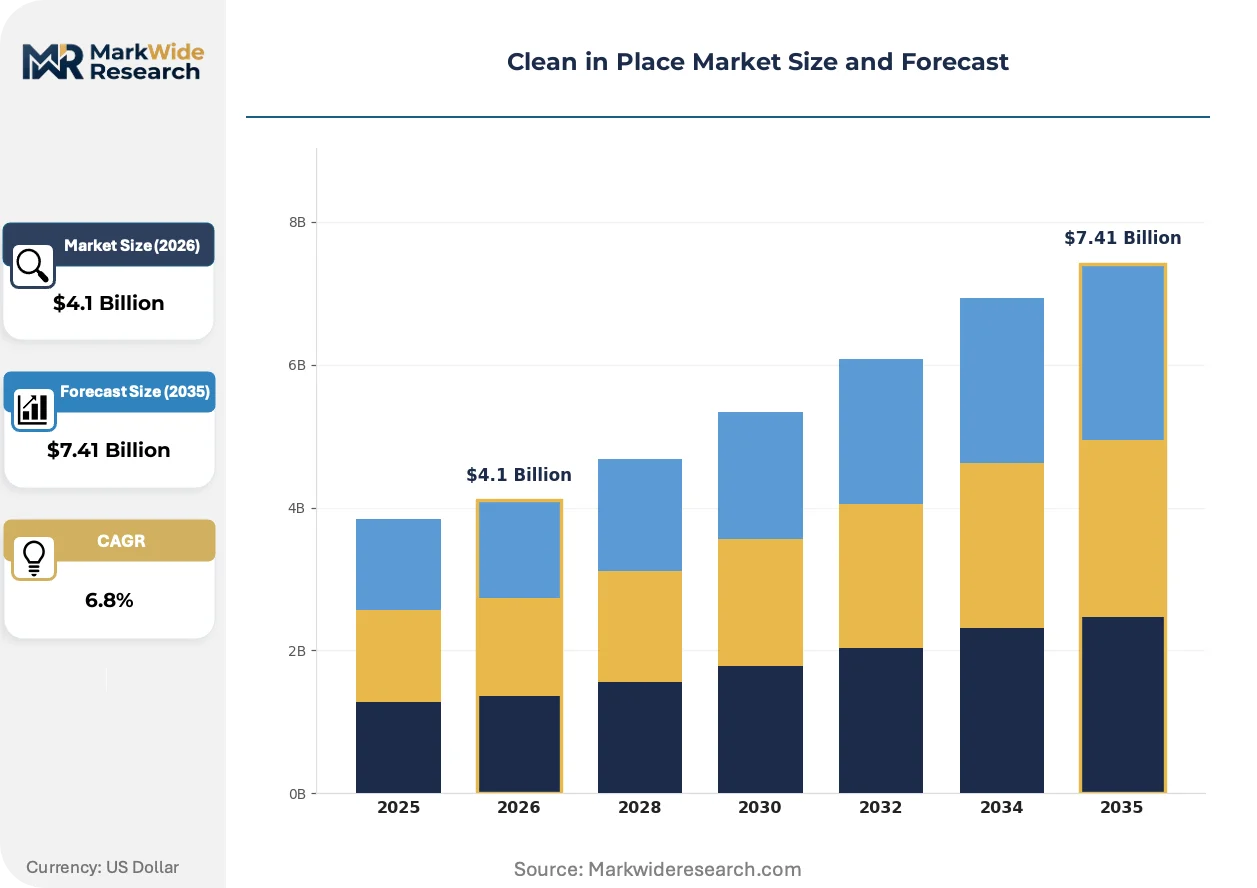
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Portable Units, Fixed Systems Industry Vertical: Food & Beverage, Pharmaceuticals, Cosmetics, Municipal Technology: Temperature Control, Chemical Dispensing, Monitoring Systems, Filtration Installation: On-site, Off-site, Modular, Integrated |
| Companies Covered | SPX Flow, GEA Group, Alfa Laval, Krones AG, Tetra Pak, Sani-Matic, Ecolab, Pentair, Millitec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean in Place Market Strategic Shifts & Innovations
The evolution of CIP technology is pivoting from a focus on chemical efficacy to a holistic approach centered on resource optimization and data-driven validation. This shift reflects pressures from both environmental sustainability goals and the stringent documentation requirements of regulated industries.
Advanced sensor technology, including turbidity, conductivity, and TOC sensors, provides real-time monitoring of cleaning cycle effectiveness. Pharmaceutical and infant formula manufacturers are primary adopters, driven by the need for precise, documented cleaning validation. This real-time data feedback is decomposing the traditional fixed-time, fixed-temperature cleaning cycle, allowing for dynamic protocols based on actual system cleanliness.
Hygienic design guidelines from bodies like Europe's EHEDG and the US-based 3-A Sanitary Standards are becoming de facto audit requirements. This trend compels equipment manufacturers and end-users to prioritize cleanability during initial design of processing lines. The beverage processing industry, in particular, must invest in certified equipment to mitigate contamination risks and satisfy inspectors.
A demand-side shift is visible as end-users move from transactional equipment purchases to service-led contracts for cleaning operations. This "Cleaning-as-a-Service" model bundles hardware with chemical supply and performance guarantees, displacing traditional component sales channels. The trend is most advanced in North American and European food processing plants where outsourcing non-core functions is a priority.
Clean in Place Market Segmentation
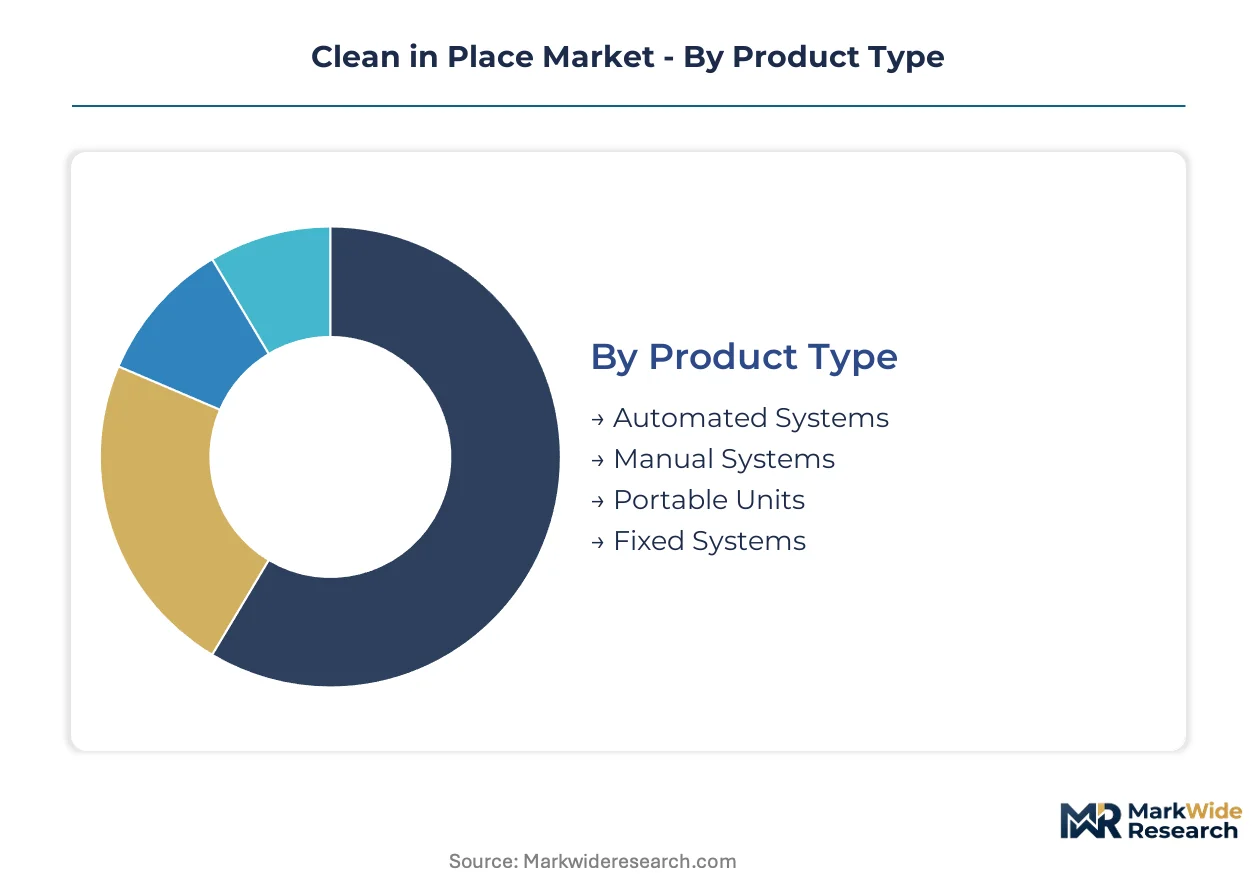
The Clean in Place (CIP) market's segmentation highlights the diverse operational requirements and technological preferences across various end-user industries. Understanding these distinct segments is crucial for manufacturers to tailor solutions effectively, addressing specific regulatory demands and resource optimization challenges inherent in different processing environments.
Product Type:
Margin pools within the product type segment are concentrated in advanced system configurations that offer high precision and validation capabilities.
- Automated Systems:These complex units integrate pumps, valves, sensors, and control logic to execute multi-step cleaning cycles without manual intervention. Demand from the pharmaceutical sector is particularly strong, driven by stringent aseptic processing standards and the need for validated cleaning protocols.
- Manual Systems:Operators physically manage cleaning fluid delivery and process parameters, often requiring significant labor input and lacking consistent validation. These systems primarily serve smaller processors in less regulated segments, where capital expenditure is a primary constraint.
- Portable Units:Self-contained CIP skids designed for mobility and use across multiple processing lines or smaller equipment. Craft breweries and small-scale dairy operations often utilize these systems due to their flexibility and lower upfront investment compared to fixed installations.
- Fixed Systems:Permanently installed CIP systems dedicated to specific processing lines or equipment within a facility. Large food and beverage manufacturers commonly deploy fixed systems for continuous, high-volume production lines.
The dominant share belongs to Automated Systems, while Portable Units are closing the gap fastest.
Industry Vertical:
The industry vertical segmentation delineates distinct application requirements across end-user operations, each with unique hygiene standards and processing complexities.
- Food & Beverage:This segment encompasses dairy, brewing, soft drinks, and processed foods, requiring robust cleaning to prevent microbial contamination and ensure product quality. Regulations from bodies like India's FSSAI and Europe's EFSA compel significant CIP adoption in this sector.
- Pharmaceuticals:Manufacturers of drugs and biologics demand the highest level of cleanliness and validation for their processing equipment to meet aseptic standards. The US FDA and European Medicines Agency mandates directly drive the adoption of sophisticated, validated CIP systems in this industry.
- Cosmetics:Production facilities for personal care products require effective cleaning to prevent cross-contamination and maintain product integrity. This vertical typically employs CIP systems to clean mixers, storage tanks, and filling lines.
- Municipal:Water treatment plants and public utility infrastructure use CIP principles for cleaning pipes and filtration systems. These applications focus on maintaining flow efficiency and preventing biofilm buildup.
Pharmaceuticals demand the most stringent system validation, while the Food & Beverage sector drives the largest volume.
Technology:
The technology segment reflects varying levels of system sophistication and cost, impacting operational efficiency and data-driven validation capabilities.
- Temperature Control:These systems precisely regulate the temperature of cleaning solutions to optimize chemical efficacy and reduce cleaning cycle times. Consistent temperature control is vital for effective sanitization in all regulated industries.
- Chemical Dispensing:Accurate and consistent delivery of cleaning agents like acids, caustics, and disinfectants is fundamental to CIP system performance. Automated chemical dosing ensures optimal concentration for microbial removal and residue breakdown.
- Monitoring Systems:Advanced sensors detect parameters such as turbidity, conductivity, and TOC (Total Organic Carbon) in real-time during cleaning cycles. Pharmaceutical and infant formula producers widely adopt these systems for precise cleaning validation and resource optimization.
- Filtration:Integrated filtration components remove particulate matter from cleaning solutions, allowing for water reclamation and reuse. This technology improves resource efficiency and reduces effluent discharge volumes.
Monitoring Systems represents the fastest-growing trajectory, driven by data-driven validation needs.
Installation:
Installation types are dictated by facility infrastructure, operational scale, and the need for either dedicated or flexible cleaning solutions.
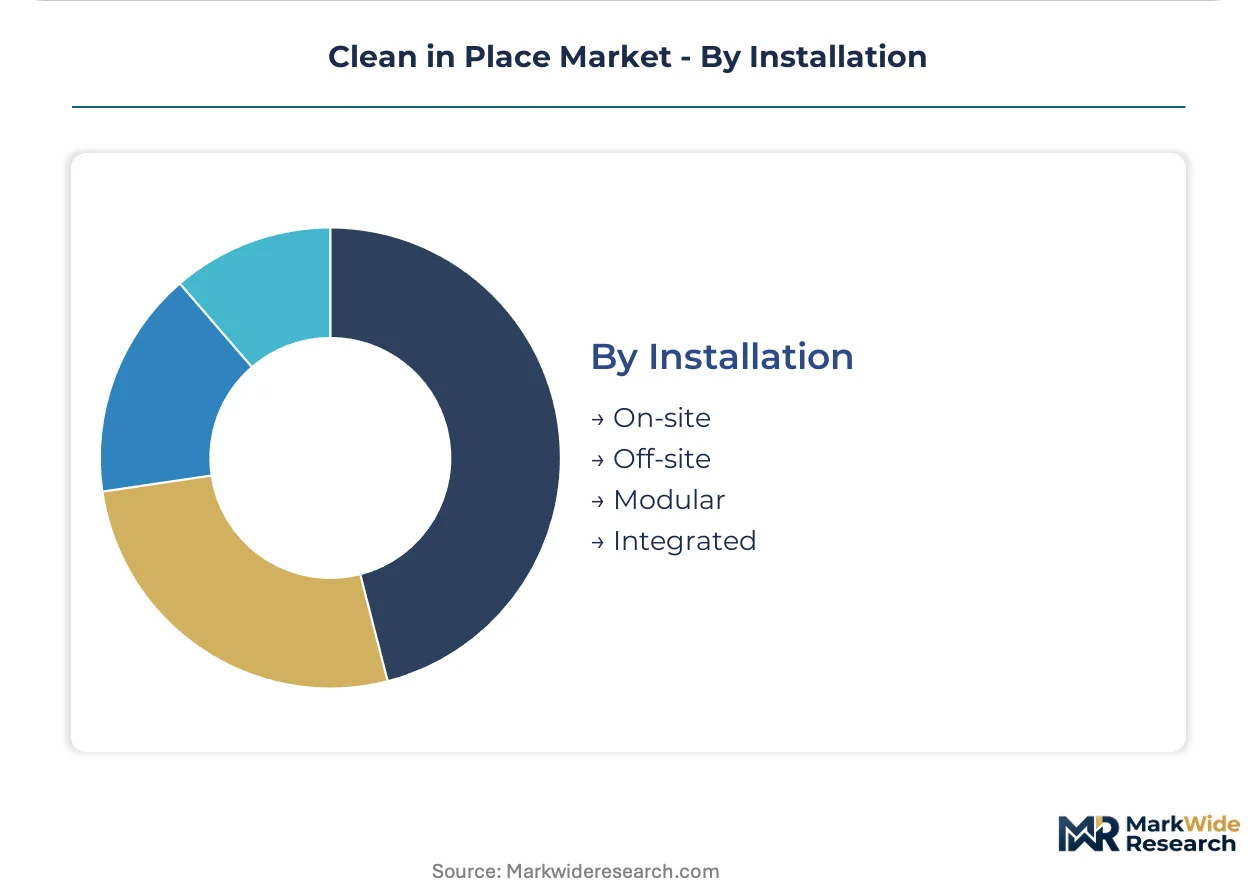
- On-site:CIP systems are built directly into the processing facility, often customized to the specific layout and equipment. This approach is common in large, established production plants with complex processing lines.
- Off-site:Cleaning solutions are prepared and sometimes partially processed away from the main production area, then delivered to the equipment. This can reduce footprint within critical processing zones.
- Modular:Pre-engineered, skid-mounted CIP units that can be easily transported and integrated into existing or new facilities. This design offers flexibility and faster deployment for operations seeking scalable solutions, particularly for smaller facilities.
- Integrated:CIP systems are seamlessly designed and installed as a complete part of the overall processing line, often controlled by a central automation platform. Large international food and beverage clients frequently opt for these turnkey solutions for optimized operational flow.
Integrated solutions address complex large-scale facilities, whereas Modular systems cater to smaller operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies significantly across the Clean in Place market, with pharmaceutical clients prioritizing validated precision over cost, while small food processors remain highly price-sensitive. This divergence influences system adoption rates and technology preferences across different geographies. Regulatory frameworks and industrial concentration further shape regional dynamics.
United States
Demand from biopharmaceutical manufacturing and dairy processing drives advanced CIP system adoption. The US FDA mandates stringent aseptic processing standards for drug production, compelling investment in validated cleaning. Major biopharma clusters in Massachusetts and California continuously upgrade facilities with sophisticated CIP solutions.
Germany
European food and beverage processors seek resource-efficient CIP solutions to optimize operational costs. Germany's EFSA regulations and EHEDG guidelines promote hygienic design and automated cleaning protocols. The Rhine-Main region, with its strong food processing and chemical industries, sees ongoing demand for integrated systems.
India
India's expanding biopharmaceutical and dairy sectors exhibit high demand for scalable CIP installations. The FSSAI's tightening hygiene requirements push food processors away from manual cleaning methods. Industrial hubs like Hyderabad and Pune are experiencing significant investment in new, high-purity production lines.
China
Rapid industrialization in China's food and beverage sector fuels demand for automated cleaning solutions. National GB standards for food safety and pharmaceutical manufacturing enforce stricter hygiene practices. The Yangtze River Delta region, a major manufacturing base, sees sustained growth in CIP system deployments.
France
French dairy and beverage industries require robust cleaning systems to maintain product quality and safety. European Union regulations and national directives enforce high standards for food processing hygiene. Brittany, a significant agricultural and food processing region, invests in advanced CIP technology for its numerous dairy plants.
Clean in Place Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the Clean in Place market's competitive structure. This tiered landscape features large engineering conglomerates offering turnkey solutions, alongside specialized chemical providers and focused component manufacturers. Companies pursue portfolio diversification to address varied end-user needs and engage in strategic partnerships to expand geographic reach. Market players also focus on technological innovation to enhance system efficiency and data validation capabilities.
Large engineering conglomerates such as GEA Group and Alfa Laval exemplify the turnkey solution providers, offering comprehensive systems for major international clients. Ecolab, by contrast, occupies a specialized niche, differentiating through its chemical expertise and service-led model. These players collectively represent the market's diverse approaches to delivering cleaning efficacy and operational value.
| Leading Market Players |
|---|
| SPX Flow |
| GEA Group |
| Alfa Laval |
| Krones AG |
| Tetra Pak |
| Sani-Matic |
| Ecolab |
| Pentair |
| Millitec |
| Others |
Cost & Logistics Intelligence
Days-of-inventory for critical CIP components like sensors and specialized valves directly influences system pricing power, particularly for integrated solutions where supply concentration dictates lead times and cost structures for end-users.
Pricing Analysis
After-sales service contracts for maintenance and validation support drive significant lifetime value for CIP system providers. The dominant pricing model is project-based for large integrated systems, transitioning to a service-led contract model for ongoing chemical supply and performance guarantees. Price differentiation stems from the level of validation certification required for specific industries, such as pharmaceutical aseptic processing, and the degree of system customization. Pricing pressure stems from the high capital expenditure for automated systems, particularly impacting smaller food processors. Pharmaceutical manufacturers exhibit the least price sensitivity due to stringent regulatory compliance.
Supply Chain Analysis
Inventory levels of advanced monitoring sensors and custom-fabricated stainless steel components remain a critical supply chain concern. Geographic supply concentration for specialized CIP components primarily rests in Germany for engineering, China for general manufacturing, and the United States for advanced sensor technology. Raw material dependencies include high-grade stainless steel for tanks and piping, specialized polymers for seals, and proprietary cleaning chemical formulations. A structural risk involves single-source vulnerability for highly specialized control valves or unique sensor technologies. Distribution runs through direct sales channels for large-scale integrated systems and a network of regional distributors for portable units and chemical supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Clean in Place market is undergoing a platform-economics inflection, driven by the emergence of integrated data ecosystems that connect cleaning efficacy with overall production line performance.
For Market Incumbents:Fortify core engineering capabilities in hygienic design and advanced system integration to counter emerging modular solution providers. Invest in developing sophisticated AI-driven analytics for predictive maintenance and real-time validation, addressing the increasing demand for data-driven cleaning efficacy. Leverage existing client relationships in the food and beverage sector to upsell service-led contracts, mitigating margin pressure from commodity component sales. Prioritize talent development programs to address the specialized skills gap in operating complex automated CIP systems.
For New Entrants and Emerging Players:Lead with cost-effective, modular CIP solutions specifically designed for the craft brewing and small-scale dairy segments, which remain underpenetrated. Target the growing demand for water reclamation technologies within CIP systems, aligning with regulatory incentives for water conservation in regions like Europe. A viable go-to-market angle involves offering bundled solutions that combine hardware with specialized chemical agents and simplified, cloud-based monitoring interfaces for ease of use by smaller operations.
For Investors and Strategic Acquirers:Carve-out targets emerge from larger engineering conglomerates seeking to divest non-core CIP component manufacturing units. Long-term viability for the market is strong, driven by persistent regulatory tightening and industrial expansion in bioprocessing. Identify acquisition targets specializing in advanced sensor technology, AI-driven analytics platforms, or water reclamation systems. The signal to watch is the increasing adoption rate of "Cleaning-as-a-Service" models by large food processors, indicating a shift towards outcome-based solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven Validation Software | Enhances cleaning efficacy documentation for pharmaceutical clients, meeting stringent US FDA requirements. |
| Launch Modular CIP Skids for SMEs | Captures underserved craft brewing and small dairy market segments in Europe and North America. |
| Acquire Water Reclamation Technology Firm | Addresses resource intensity concerns and regulatory incentives for water conservation in processing plants. |
| Expand Service-Led Contract Offerings | Shifts revenue model towards recurring income, providing greater stability for major food and beverage clients. |
| Invest in Specialized Training Programs | Mitigates the skills gap for operating complex automated CIP systems, improving deployment effectiveness. |
Research Approach
The analysis maps Clean in Place sub-sectors, each validated through primary interviews with plant engineers, validation specialists, procurement managers, and regulatory compliance officers. Secondary research involved extensive review of US FDA guidelines, European Medicines Agency mandates, India's FSSAI reports, EHEDG documentation, and corporate financial reports. This approach ensured a comprehensive understanding of market dynamics, triangulating insights from both industry practitioners and published regulatory and financial data.
All quantitative outputs were cross-referenced against external benchmarks and industry association reports to ensure consistency across the analysis window. The analytical framework modeled market segmentation across product type, industry vertical, technology, installation, and regional regulatory clusters. Compound annual growth rates were derived from historical data and projected forward based on anticipated shifts in biopharma R&D spend and dairy processing capacity expansion, reflecting market drivers and restraints.
Forecasts assume regulatory continuity in key regimes like the US, Europe, and India; material policy shifts would require re-modeling. The projections reflect current understanding of technology adoption rates and economic conditions. Revision becomes warranted when global economic slowdowns or significant technology breakthroughs cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Industrial Food Slicers Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
China Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Countertop Food Blenders Market
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Commercial Winery Equipment Market
Food Processing Equipment
Pasteuriser Market
Food Processing Equipment
Planetary Mixer Market
Food Processing Equipment
Kebab Machine Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Electric Meat Saw Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
India Household Flour Milling Machines Market