
 Food and Beverages Air Filters Market | 2026-2036
Food and Beverages Air Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverages Air Filters Market Analysis
European filter media producers is broadening output of food-grade synthetic fibers to serve cleanroom packaging lines. Donaldson Company leverages its agricultural dust control heritage to anchor filtration solutions across grain handling and milling operations. 3M Group sustains R&D intensity in pleated electret media that captures sub-micron particles without pressure-drop penalties. Camfil Group dominates Nordic markets through specialized HEPA configurations designed for cold storage humidity cycling.
Food and beverages air filters are engineered barrier systems, typically constructed from borosilicate microfibers, activated carbon granules, or electrostatically charged synthetic media, designed to remove particulates, microbes, and gaseous contaminants from intake and recirculated air in production environments. Their primary purpose is maintaining process air purity thresholds that prevent product contamination, protect worker respiratory zones, and sustain shelf-life stability across temperature-controlled supply chains. HEPA filtration occupies the largest installed base due to mandatory microbial control in dairy and meat processing, while activated carbon systems command premium positioning among beverage producers managing flavor-damaging volatile organic compounds. Ceiling mounted installations represent the fastest-growing configuration as facilities retrofit open production floors without interrupting existing equipment layouts.
EPA National Emission Standards for Hazardous Air Pollutants and FDA Current Good Manufacturing Practice regulations together mandate documented air quality monitoring in facilities handling exposed food products. ISO 14644 cleanroom classifications increasingly govern packaging zone specifications, forcing filter vendors to certify performance against standardized particle penetration protocols. Stakeholders must weigh total cost of ownership against single-stage filter replacement economics as energy codes tighten fan power allowances.
Market Dynamics
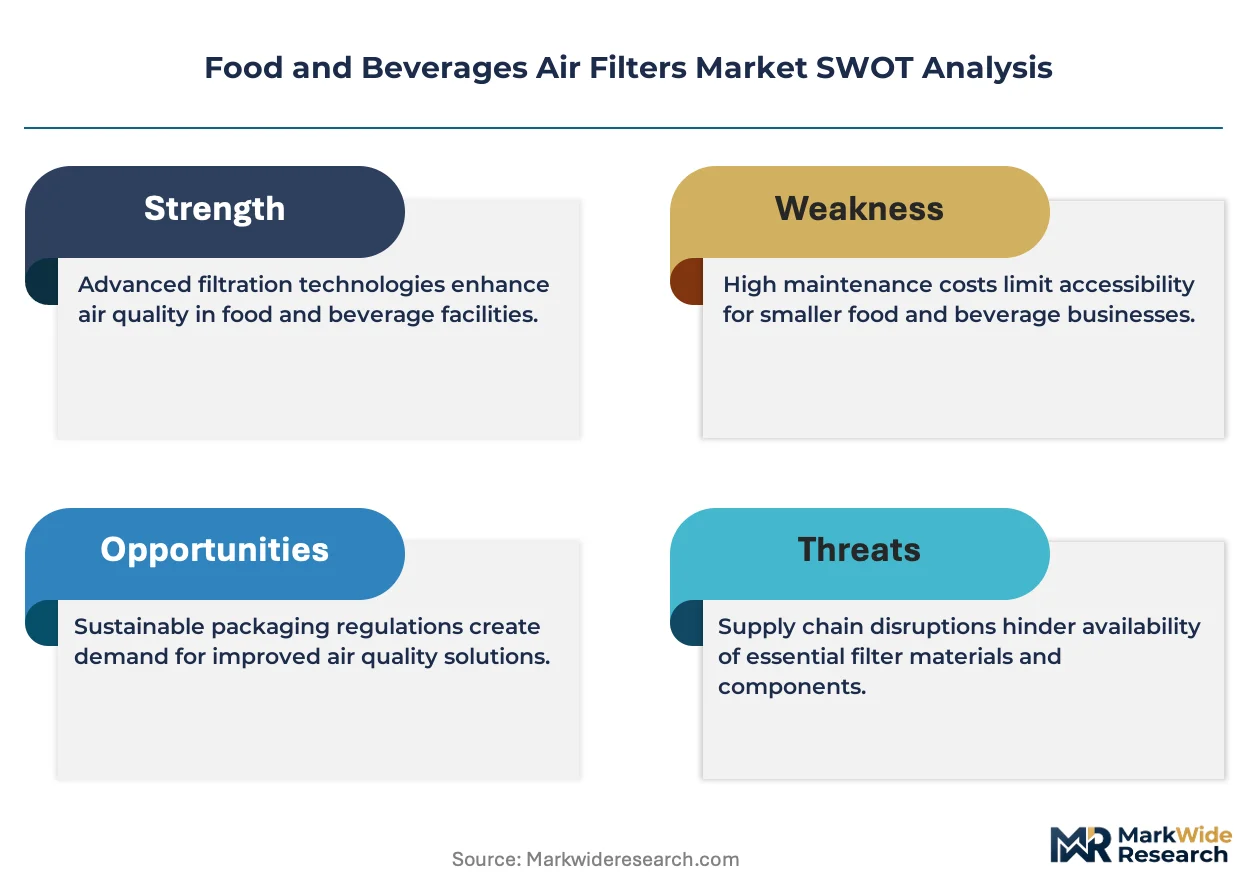
HEPA filtration is consolidating its position as the dominant technology platform across dairy and meat processing facilities, driven by FDA Food Safety Modernization Act mandates for airborne pathogen containment and the operational imperative to maintain cold chain integrity without pressure-drop penalties.
Growth Catalysts
- FSMA microbial control mandates:Dairy processors in Wisconsin and California are retrofitting facilities with HEPA ceiling configurations to satisfy FDA airborne pathogen surveillance requirements.
- Activated carbon VOC removal:Craft breweries deploy granular activated carbon systems during fermentation to eliminate flavor-damaging organic compounds from recirculated air.
- Germany equipment upgrade cycle:German food safety agencies are tightening microbiological air quality standards for ready-to-eat production environments, accelerating filter replacement demand.
Market Restraints
- Borosilicate microfiber supply concentration:Filter media production clusters in Northern Europe create vulnerability to energy cost volatility and logistics disruption.
- ISO 14644 certification friction:Cleanroom packaging zones require documented particle penetration protocols that extend vendor qualification timelines.
- Electrostatic media substitution threat:Charged synthetic fibers from 3M and competitors threaten traditional HEPA economics in lower-risk applications.
Strategic Opportunities
- Japan cold storage humidity cycling:Specialized HEPA configurations for temperature-controlled supply chains remain underpenetrated in Japanese distribution networks.
- CE marking harmonization:EFSA alignment with ISO 14644 creates unified certification pathways for filter vendors entering European cleanroom packaging markets.
- Ceiling-mounted retrofit channel:Facilities seek non-disruptive installation methods for open production floors without relocating existing equipment layouts.
Industry Challenges
- Pleated electret media integration complexity:Sub-micron capture without pressure-drop penalties requires recalibration of existing HVAC fan power allowances.
- Total cost of ownership calculation skill gap:Procurement teams struggle to model energy consumption against single-stage filter replacement economics under tightening building codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverages Air Filters Market |
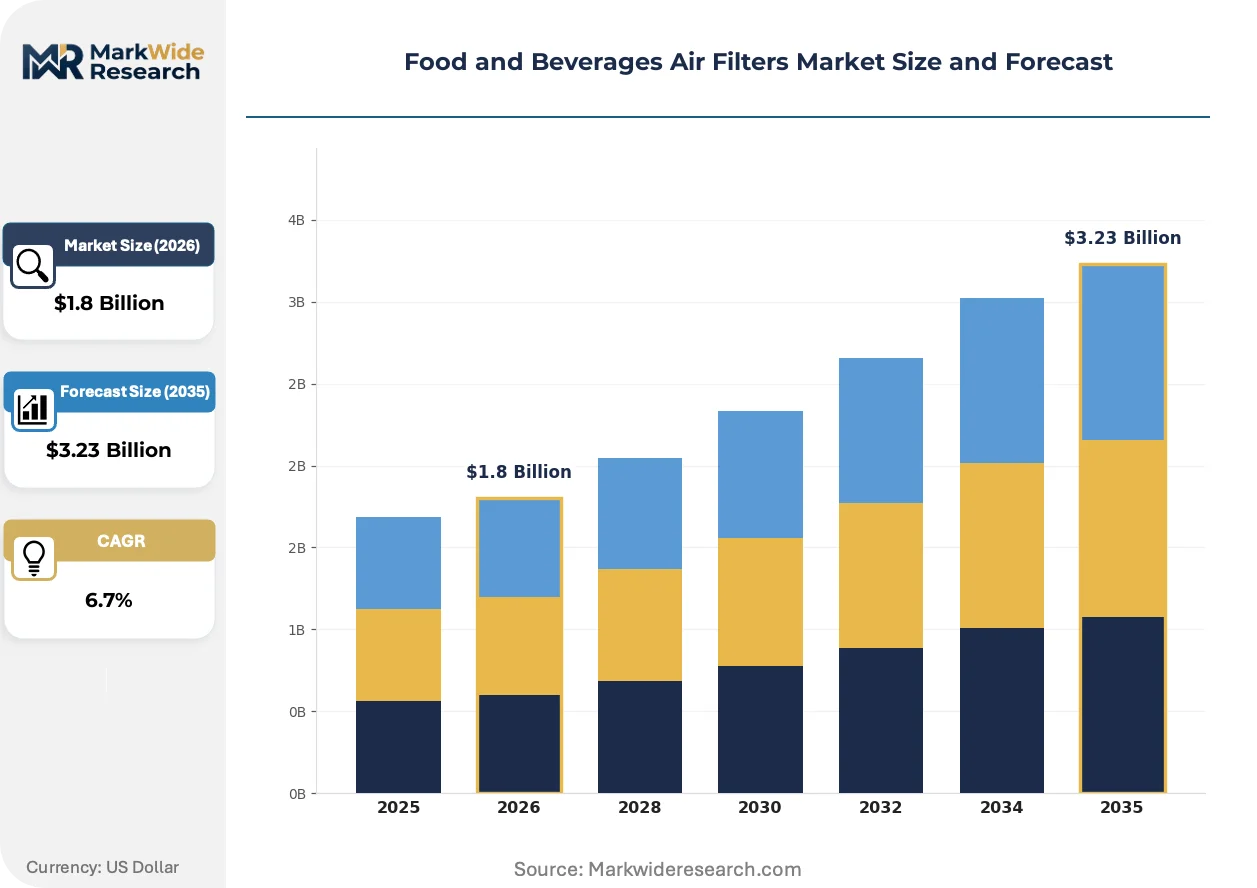
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, Electrostatic, Chemical Application: Food Processing, Beverage Production, Packaging, Storage Installation: In-line, Ceiling Mounted, Wall Mounted, Standalone End User: Food Manufacturers, Beverage Companies, Restaurants, Food Retailers |
| Companies Covered | Donaldson Company, Inc., Porvair Filtration Group Ltd., 3M Group, APC Filtration, Inc., Parker-Hannifin Corporation, Camfil Group, Freudenberg Filtration Technologies, Air Filters, Inc., Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverages Air Filters Market Emerging Trajectories
Filtration technology is converging with building automation systems to enable real-time pressure differential monitoring and predictive maintenance scheduling across temperature-controlled production environments.
Pleated electret media is consolidating its technical advantage in sub-micron particle capture. Dairy processors in high-humidity climates are adopting these synthetic fiber configurations to avoid borosilicate degradation. The technology is consolidating vendor margins by reducing filter replacement frequency while maintaining HEPA-equivalent microbial retention.
EPA National Emission Standards for Hazardous Air Pollutants are tightening documented air quality monitoring requirements for facilities handling exposed food products. Meat processors must now maintain continuous particulate surveillance records. Cold storage operators in the United States are responding by installing integrated sensor networks that trigger automated filter status alerts.
Service unbundling is fragmenting traditional filter supply relationships. Large beverage producers are separating media procurement from installation and validation services. This pattern is most visible among multinational breweries operating distributed fermentation facilities, where in-house engineering teams now specify filter performance criteria independently of vendor maintenance contracts.
Food and Beverages Air Filters Market Segmentation
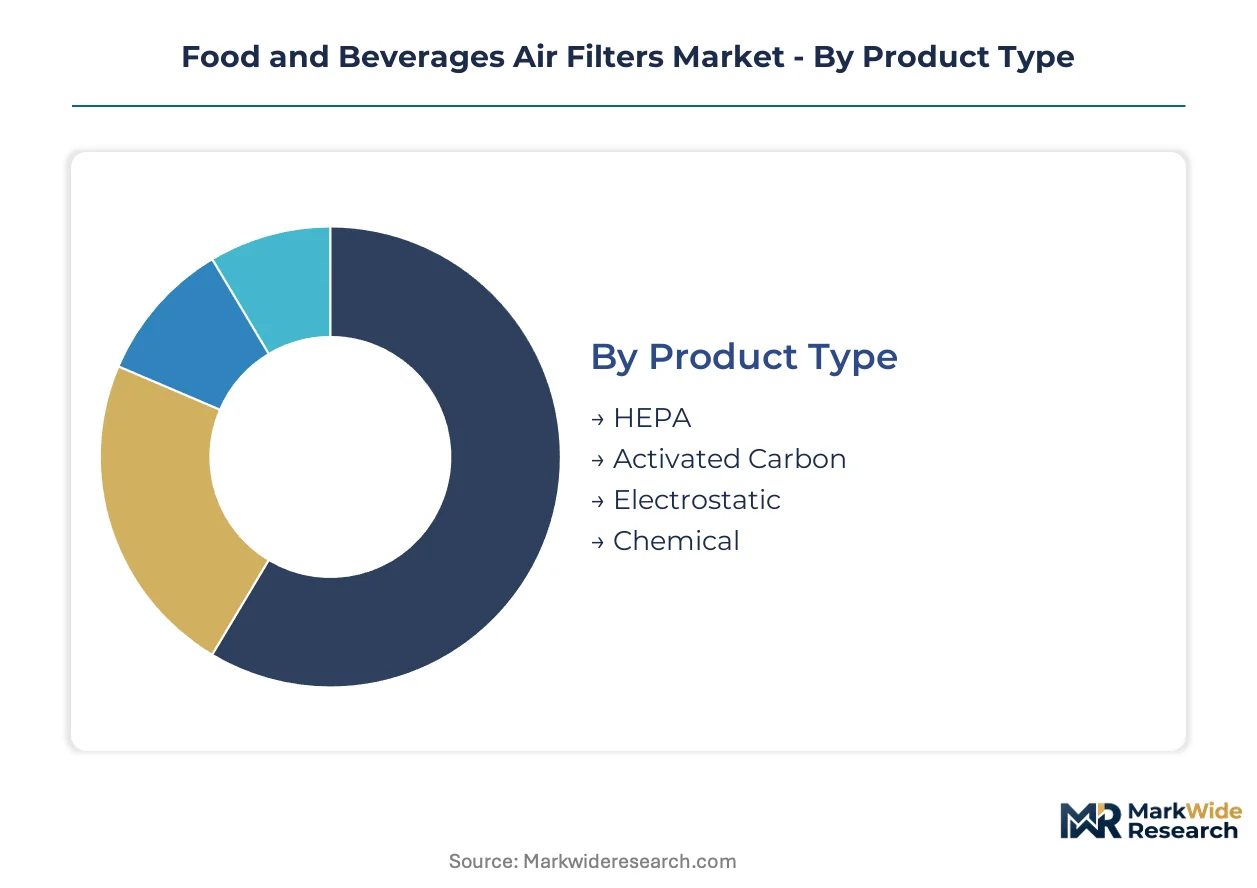
Air filtration procurement in food and beverage facilities hinges on matching certification requirements to operational risk profiles. Each segment carries distinct regulatory burdens that shape vendor selection and replacement economics across production environments.
Product Type:
HEPA and activated carbon systems demand FDA-validated microbial retention documentation, while electrostatic alternatives face lighter ISO 14644 certification thresholds in lower-risk zones.
- HEPA:Borosilicate microfiber matrices rated at 99.97% efficiency for 0.3-micron particles. Dairy processors in Wisconsin retrofit ceiling configurations to satisfy FDA Food Safety Modernization Act airborne pathogen mandates.
- Activated Carbon:Granular or bonded carbon beds engineered for VOC and odor adsorption. Craft breweries in Germany deploy these during fermentation to protect flavor profiles from organic compound contamination.
- Electrostatic:Synthetic fiber media carrying permanent electret charges for sub-micron capture without pressure-drop penalties. Gaining traction in cold storage humidity cycling applications.
- Chemical:Impregnated media targeting specific gaseous contaminants like ammonia or sulfur compounds. Specialized deployment in meat rendering and fish processing facilities.
Leading the category by volume: HEPA. Expanding most quickly: Electrostatic.
Application:
Installation location determines whether filters must withstand continuous washdown protocols or intermittent exposure cycles.
- Food Processing:High-particulate environments handling raw ingredients through finished goods. Meat and dairy operations dominate replacement demand due to FDA-mandated microbial surveillance.
- Beverage Production:Fermentation and bottling lines requiring VOC control and yeast containment. Activated carbon configurations command premium positioning here.
- Packaging:ISO 14644 cleanroom classifications govern exposed product zones. Filter vendors face extended qualification timelines for documented particle penetration protocols.
- Storage:Temperature-controlled warehouses prioritizing humidity cycling resistance. Specialized HEPA configurations from Camfil Group anchor Nordic cold chain deployments.
Dominant by installed base: Food Processing. Steepest expansion trajectory: Packaging.
Installation:
Mounting geometry shapes facility disruption during retrofit and determines integration complexity with existing HVAC infrastructure.
- Ceiling Mounted:Suspended plenum configurations enabling non-disruptive deployment across open production floors. Fastest-growing format as facilities avoid relocating existing equipment layouts.
- In-line:Duct-integrated systems for centralized air handling units. Requires coordinated shutdown windows that complicate continuous processing environments.
- Wall Mounted:Localized filtration for perimeter zones and loading docks. Common in food retail back-of-house operations with limited ceiling clearance.
- Standalone:Portable units for temporary contamination control or construction phase protection. Beverage companies deploy these during distributed fermentation facility expansions.
Highest volume: In-line. Gaining share fastest: Ceiling Mounted.
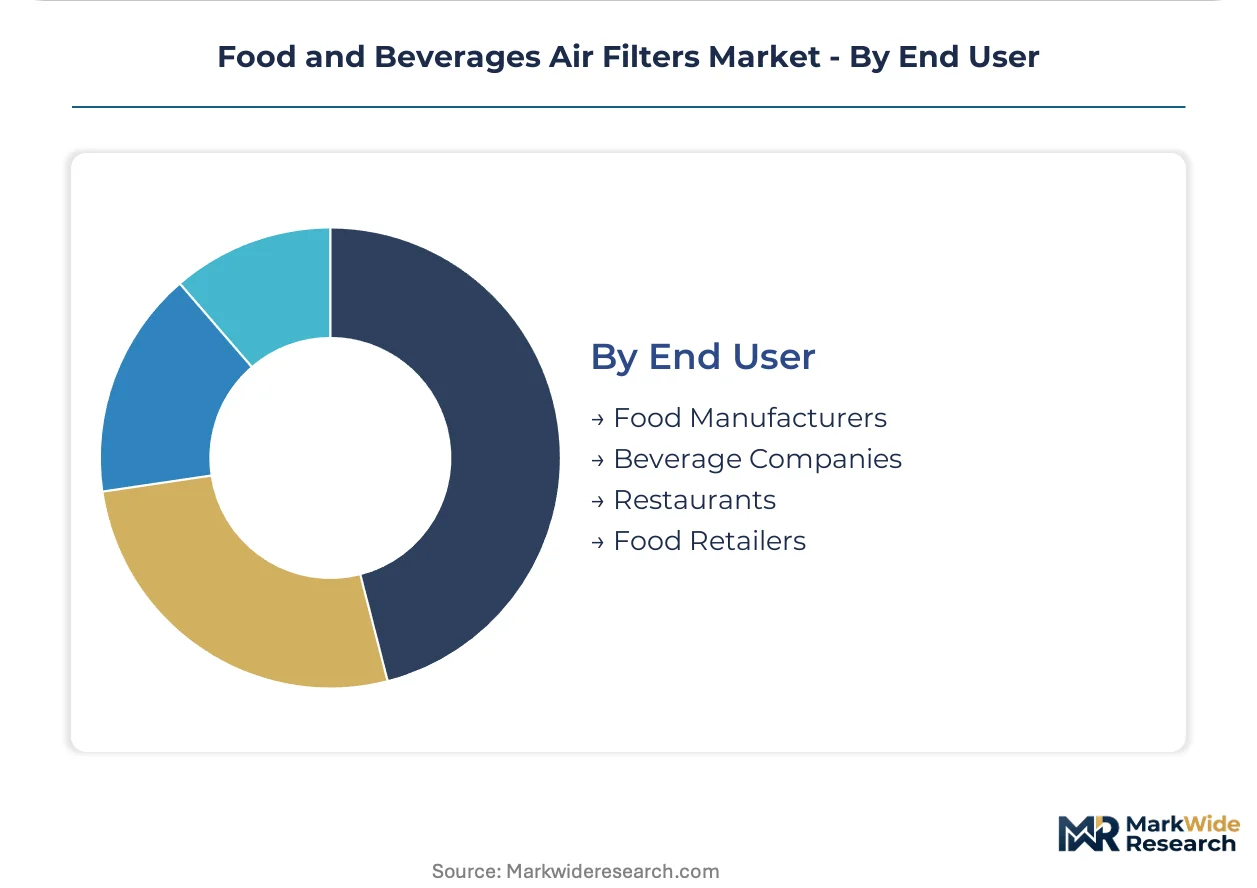
End User:
Procurement sophistication varies sharply across customer scale, with multinationals unbundling media supply from installation services.
- Food Manufacturers:Industrial-scale processors with documented air quality monitoring mandates under EPA National Emission Standards. Continuous particulate surveillance records now required for exposed product handling.
- Beverage Companies:Multinational breweries increasingly specify filter performance criteria independently of vendor maintenance contracts. Service unbundling fragments traditional supply relationships.
- Restaurants:Commercial kitchen ventilation with grease and odor control priorities. Lower certification burdens than production facilities.
- Food Retailers:Cold storage operators responding with integrated sensor networks for automated filter status alerts. Temperature-controlled supply chain integrity drives replacement scheduling.
Largest procurement volume: Food Manufacturers. Climbing the fastest: Beverage Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Borosilicate microfiber production clusters in Northern Europe shape supply security calculations for filter procurement across dairy and meat processing corridors worldwide.
United States
Dairy processors in Wisconsin and California retrofit ceiling-mounted HEPA configurations to satisfy FDA Food Safety Modernization Act airborne pathogen mandates. EPA National Emission Standards for Hazardous Air Pollutants now require continuous particulate surveillance records for exposed product handling. Cold storage operators in the Pacific Northwest deploy integrated sensor networks triggering automated filter status alerts.
Germany
German food safety agencies tighten microbiological air quality standards for ready-to-eat production environments, accelerating equipment replacement cycles. EFSA alignment with ISO 14644 creates unified certification pathways for filter vendors entering European cleanroom packaging markets. Craft breweries in Bavaria deploy granular activated carbon systems during fermentation to protect flavor profiles.
Japan
Specialized HEPA configurations for temperature-controlled supply chains remain underpenetrated in Japanese distribution networks. METI guidance on cold chain integrity drives demand for humidity-cycling resistant media. Food manufacturers in the Kanto region around Tokyo anchor equipment upgrade demand for packaging zone filtration.
China
Domestic filter media producers broaden output of food-grade synthetic fibers to serve cleanroom packaging lines serving export-oriented processors. SAMR enforcement of GB standards for food contact materials intensifies vendor qualification requirements. Yangtze River Delta dairy operations lead HEPA installation rates among Chinese processors.
India
FSSAI implementation of stricter food safety protocols drives HEPA adoption in dairy cooperatives across Maharashtra and Gujarat. The country's national food safety regulator mandates documented air quality monitoring in facilities handling exposed milk products. Bangalore-based beverage bottlers increasingly specify activated carbon configurations for VOC control.
Food and Beverages Air Filters Market Vendor Landscape
Global majors compete with regional champions across certification depth and cold chain specialization. The vendor base stratifies into three tiers: diversified industrial conglomerates with agricultural heritage, pure-play filtration specialists with cleanroom expertise, and regional fabricators serving price-sensitive retrofit channels. Two strategic archetypes dominate: technology licensors leveraging electret media patents, and integrated system providers bundling filtration with building automation. Competitive moves concentrate on capacity expansion in synthetic fiber media and strategic partnerships linking filter supply to HVAC control platforms.
Within the diversified industrial tier, Donaldson Company and Parker-Hannifin Corporation exemplify players leveraging agricultural dust control heritage to anchor solutions across grain handling corridors. 3M Group occupies a position as technology anchor through sustained intensity in pleated electret media development. Camfil Group represents the specialized configuration archetype, with Nordic market presence built around humidity-cycling HEPA designs for temperature-controlled supply chains.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| Porvair Filtration Group Ltd. |
| 3M Group |
| APC Filtration, Inc. |
| Parker-Hannifin Corporation |
| Camfil Group |
| Freudenberg Filtration Technologies |
| Air Filters, Inc. |
| Pall Corporation |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of borosilicate microfiber media anchors pricing power for Nordic and German filter specialists while forcing tier-two competitors toward outsourced synthetic fiber sourcing. This integration choice separates vendors who certify against FDA Food Safety Modernization Act microbial retention protocols from those locked into lower-margin ISO 14644 cleanroom packaging segments.
Pricing Analysis
Warranty and validation service bundling separates premium HEPA configurations from unbundled media-only transactions. Three-tier pricing structure across certified-premium, documented-standard, and uncertified-economy levels reflects FDA validation depth and pressure-drop performance guarantees. Cost compression in the economy tier intensifies as electrostatic media from 3M and competitors displace traditional borosilicate HEPA in lower-risk cold storage applications. Craft breweries and distributed beverage facilities exhibit highest price sensitivity due to fragmented procurement authority, while multinational dairy processors in Wisconsin and California prioritize total cost-of-ownership models over unit filter economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale food manufacturer demand while distributor networks serve retrofit contractors and regional beverage facilities. Borosilicate microfiber production clusters in Germany, Sweden, and Finland create geographic concentration risk for premium HEPA media. Synthetic fiber electret media draws from petrochemical feedstocks in the United States and South Korea, creating dual-source flexibility against European energy cost volatility. Single-source vulnerability runs through specialized humidity-cycling HEPA configurations for Japanese cold chain networks. Distribution runs through HVAC controls integrators who bundle filtration with building automation platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA Food Safety Modernization Act microbial control mandates erect barrier-to-entry moats for validated HEPA vendors while fragmenting price competition in uncertified segments.
For Market Incumbents: To counter electrostatic media substitution in lower-risk cold storage applications, Camfil Group and Donaldson Company should deepen captive supply of food-grade synthetic fibers through backward integration into Nordic polymer processing. Certification investment against evolving EFSA-ISO 14644 harmonized standards anchors premium positioning in European cleanroom packaging corridors. For New Entrants and Emerging Players: The price-point gap between validated-premium HEPA and uncertified-economy alternatives opens white-space targeting of mid-tier beverage producers seeking documented VOC control without full FDA validation burden. Japan's underpenetrated cold storage humidity-cycling segment offers the most penetrable geography. A specification-selling go-to-market angle targeting in-house engineering teams at multinational breweries bypasses incumbent vendor maintenance contract lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by HVAC controls platforms seeking filtration integration capabilities. Long-term viability favors vendors with demonstrated FDA validation dossiers and synthetic fiber media R&D pipelines over pure-play borosilicate HEPA fabricators facing feedstock cost volatility. Monitor EFSA alignment completion with ISO 14644 as inflection signal for European cleanroom packaging certification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Fiber Media | Reduces borosilicate feedstock dependency for vendors facing European energy cost volatility. |
| Ceiling-Mounted Retrofit Channel Expansion | Captures non-disruptive installation demand from Wisconsin and California dairy processors. |
| FDA Validation Dossier Investment | Erects compliance moats against electrostatic media substitution in microbial-critical zones. |
| Building Automation Platform Partnership | Links filter supply to predictive maintenance scheduling in Pacific Northwest cold storage networks. |
| EFSA-ISO 14644 Harmonization Certification | Unlocks unified pathway into European cleanroom packaging markets for qualified vendors. |
Methodological Framework
Trade publications, FDA enforcement action databases, and EFSA technical guidance documents formed the secondary backbone, supplemented by customs records tracking borosilicate microfiber and synthetic fiber media shipments. Primary interviews with plant engineers at dairy and meat processing facilities, HVAC controls procurement managers, filter vendor technical sales directors, and regulatory affairs specialists at multinational beverage companies enabled bottom-up validation of installation trends and replacement economics. Triangulation against top-down market sizing from equipment manufacturer disclosures and industry association production statistics refined volume estimates across the projection horizon.
Bottom-up modeling anchored forecasts in facility-level HEPA and activated carbon installation rates, segmented by product type, application risk tier, and installation geometry. Top-down cross-checks validated aggregate spending patterns against EPA National Emission Standards compliance cost studies and FDA Food Safety Modernization Act implementation surveys. CAGRs were derived from fitted growth curves across the modeling period, with sensitivity analysis around electrostatic media penetration rates and European energy cost scenarios. Forecast inputs included dairy processing capacity expansion in Wisconsin and California, German ready-to-eat production equipment upgrade cycles, and Japanese cold chain integrity investment trends.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time filter replacement frequency data from independent cold storage operators introduce uncertainty bands around aftermarket revenue projections. Forecasts reflect documented assumptions regarding EFSA-ISO harmonization timing and electrostatic media technical performance maturation. Practitioners should monitor FDA enforcement action intensity and German BfR microbiological standard revisions for early signals of compliance cost trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Industrial Steam Peeler Market
Food Processing Equipment
Commercial Oven Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Dehydrators Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Global Nutating Mixers Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Milk Sterilizer Machine Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Beverage Processing Equipment Market