
 Portioning Machines Market | 2026-2036
Portioning Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Portioning Machines Market Outlook
Vision-guided robotic cutting is rewriting how portioning machines achieve weight consistency in high-speed protein lines. Marel leverages its integrated software-hardware stack to dominate salmon and poultry portioning workflows. JBT Corporation anchors its position through thermal processing and slicing technology synergies. GEA Group specializes in hygienic design standards for dairy and meat applications, extending its reach into clean-label ready-meal production.
Portioning machines are electromechanical systems that cut, divide, or dispense food products to preset weight or volume targets using servo motors, load cells, and programmable logic controllers with accuracy typically within one to two percent of target mass. Their primary purpose is to standardize output while minimizing giveaway in commercial food production environments. Automatic portioners now capture the dominant share of capital expenditure as labor costs rise and throughput requirements tighten across European protein plants. Electric technology is displacing pneumatic drives in new installations because servo systems deliver superior repeatability and reduced compressed air infrastructure. Meat processing remains the largest application category, though bakery production is gaining traction as artisan scaling demands precise dough division.
EU MDR and CE marking requirements shape machine design by mandating hygienic welding standards, clean-in-place compatibility, and traceable control system documentation for food contact equipment. EFSA guidelines on mechanical processing of raw animal products further constrain blade materials, lubricant specifications, and surface roughness thresholds. REACH compliance adds pressure on manufacturers to eliminate certain coatings and hydraulic fluids from equipment destined for European plants. Stakeholders must monitor how the EU AI Act's risk classification framework applies to autonomous vision-based cutting systems before committing to next-generation platform investments.
Market Dynamics
Electric servo-driven architectures are systematically displacing pneumatic systems across European protein processing facilities, compressing capital deployment timelines while tightening weight consistency tolerances in automated portioning lines.
Growth Catalysts
- EU MDR hygiene mandates:Food processing plants in Germany are scaling automated portioning lines to meet CE marking-aligned welding standards and clean-in-place compatibility requirements.
- Protein automation investment:Denmark and the Netherlands are channeling capital into high-throughput portioning infrastructure as labor costs rise in concentrated meatpacking regions.
- Vision-guided cutting adoption:Load cell and PLC integration with robotic blade systems is enabling real-time weight feedback loops that minimize giveaway in commercial production environments.
Market Restraints
- Compressed air infrastructure lock-in:Existing pneumatic system investments in legacy facilities create switching friction and stranded asset risk during electric retrofits.
- Stainless steel supply concentration:Hygienic welding-grade material sourcing clusters in specialized European foundries, exposing equipment manufacturers to input cost volatility.
- EFSA surface roughness thresholds:Blade material and lubricant specifications for raw animal product contact impose technical limitations on coating alternatives under REACH constraints.
Strategic Opportunities
- Bakery dough scaling automation:Artisan bakery production lines present underpenetrated demand for precise volumetric division as craft producers industrialize.
- EU AI Act risk classification:Autonomous vision-based cutting systems face emerging regulatory tailwinds that favor early platform certification in protein processing.
- Clean-label ready-meal production:Dairy and meat applications are converging with prepared food manufacturing, opening channel expansion into retail private-label supply chains.
Industry Challenges
- Servo technician scarcity:Electric drive commissioning and maintenance require specialized electromechanical skills that outpace vocational training pipeline output.
- Legacy PLC integration complexity:Retrofitting programmable logic controllers into existing line architectures demands custom protocol bridging and extended downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portioning Machines Market |
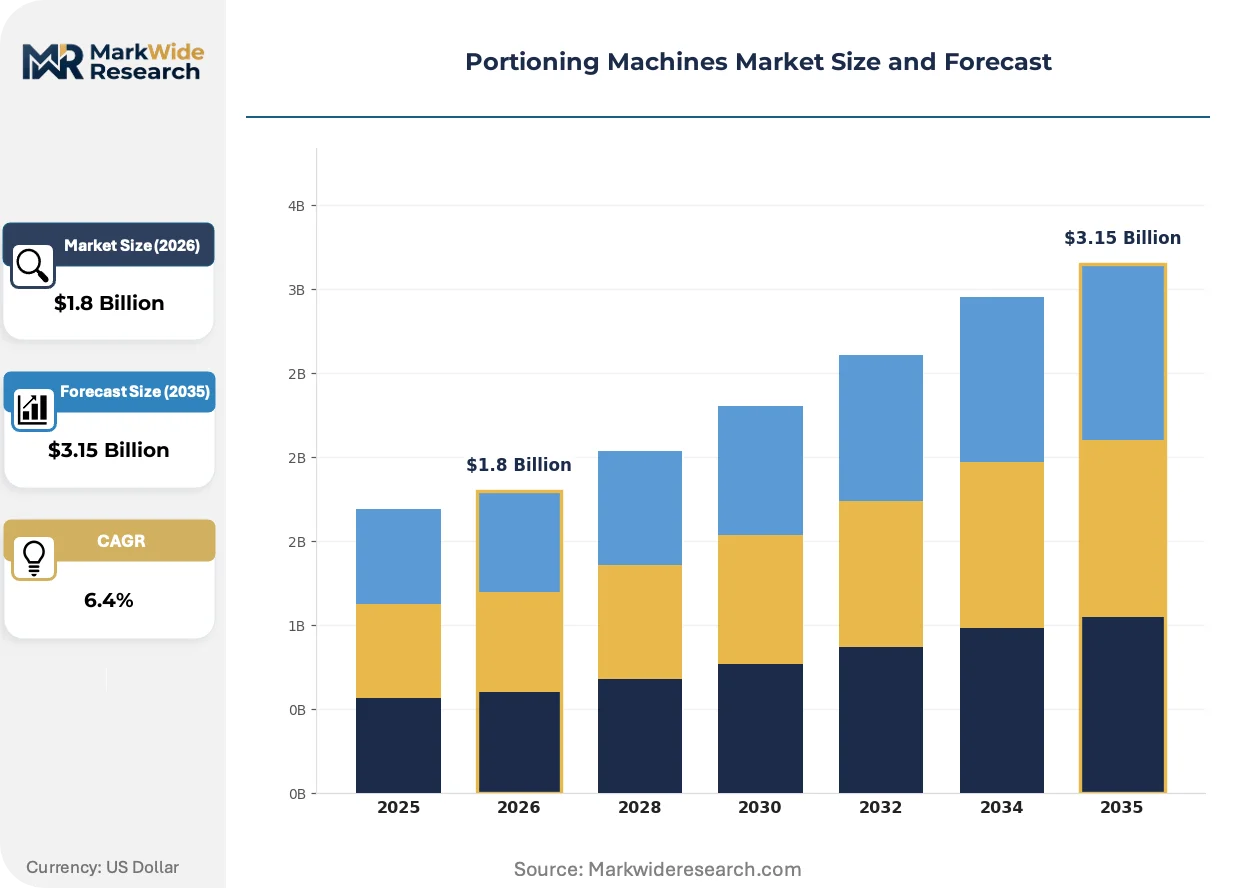
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Portioners, Automatic Portioners, Semi-Automatic Portioners, Handheld Portioners Technology: Pneumatic, Electric, Hydraulic, Mechanical End User: Restaurants, Catering Services, Food Processing Plants, Bakeries Application: Meat Processing, Bakery Production, Vegetable Portioning, Ice Cream Dispensing |
| Companies Covered | Marel, JBT Corporation, Multivac, Handtmann, Bizerba, Formax, GEA Group, Baader Group, Reiser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portioning Machines Market Strategic Shifts
Portioning technology is converging around electromechanical precision, regulatory-driven hygienic design, and service model restructuring that unbundles hardware from operational support.
Servo motor and load cell integration is hybridizing pneumatic and electric architectures in transitional installations. Mid-sized protein processors in the Netherlands are adopting this approach to preserve compressed air investments while upgrading cutting accuracy. The hybrid configuration is compressing the replacement cycle for legacy equipment by extending functional life rather than full line reconstruction.
REACH compliance is forcing coating and hydraulic fluid reformulation across equipment destined for European plants. ECHA substance restrictions are eliminating certain lubricant chemistries from food contact applications. Dairy portioning lines face the most acute substitution pressure as clean-label positioning demands eliminate synthetic additives from production environments.
After-sales service unbundling is fragmenting traditional bundled maintenance contracts in automated protein lines. German processing cooperatives are purchasing cutting hardware separately from software updates and blade resupply. This behavioral shift is most visible in Denmark's vertically integrated pork sector, where captive technical teams absorb routine calibration tasks previously outsourced to OEM service networks.
Portioning Machines Market Segmentation
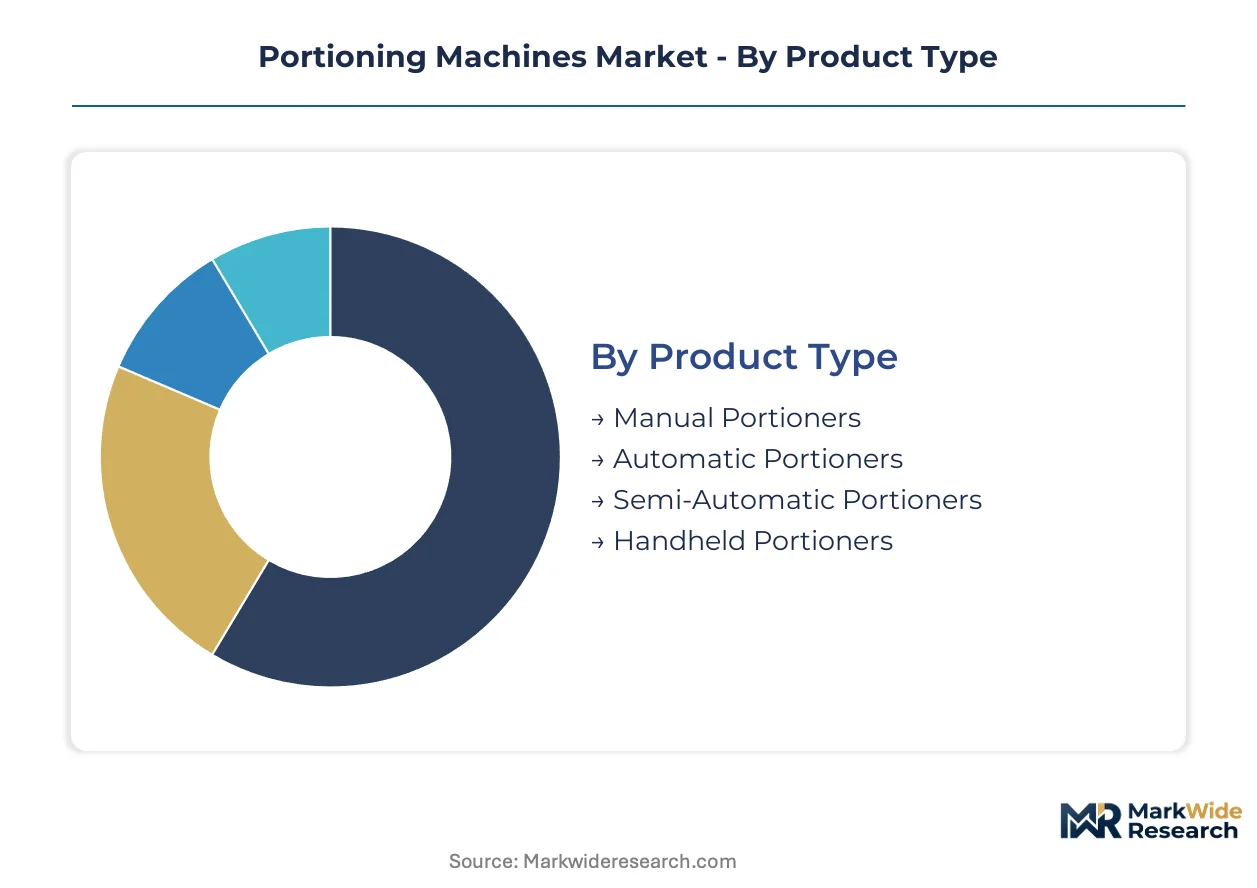
Portioning machine segmentation reveals how equipment specifications align with operational scale and regulatory exposure across protein, bakery, and prepared food environments. Each dimension carries distinct service intensity, capital deployment, and compliance implications for equipment buyers.
Product Type:
After-sales service intensity varies sharply across manual, automatic, and semi-automatic architectures, with fully automated lines demanding captive technical teams or multi-year OEM service contracts.
- Automatic Portioners:Servo-driven systems integrate load cells, PLCs, and vision-guidance hardware to achieve sub-2% weight deviation in high-throughput protein lines. Demand concentrates in German and Danish food processing plants scaling to meet EU MDR hygiene mandates and CE marking requirements for clean-in-place compatibility.
- Semi-Automatic Portioners:Hybrid pneumatic-electric configurations preserve compressed air infrastructure while upgrading cutting precision. Netherlands-based mid-sized processors favor this transitional approach to extend legacy equipment functional life without full line reconstruction.
- Manual Portioners:Hand-crank or lever-actuated devices serve small-scale catering and artisan bakery operations with minimal maintenance overhead.
- Handheld Portioners:Portable dispensers address mobile catering and food truck applications requiring rapid redeployment between service locations.
Automatic portioners hold the largest share; momentum sits with semi-automatic systems bridging pneumatic legacy and electric precision.
Technology:
Technology selection directly determines maintenance cadence, technician skill requirements, and energy infrastructure investment across European protein facilities.
- Electric:Servo motor architectures deliver superior repeatability and eliminate compressed air infrastructure dependency. REACH compliance pressures are accelerating lubricant reformulation for food contact applications in dairy portioning lines.
- Pneumatic:Compressed air systems retain installed base in legacy facilities but face stranded asset risk during electric retrofits due to switching friction and infrastructure lock-in.
- Hydraulic:Fluid power systems persist in high-force cutting applications where actuator density requirements exceed electric motor torque density.
- Mechanical:Cam-driven and linkage-based mechanisms serve cost-sensitive segments with minimal electronic complexity and field-repairable components.
Electric systems command the dominant capital flow; pneumatic retains residual presence in facilities deferring full infrastructure replacement.
End User:
End-user scale dictates equipment specification tier, with food processing plants driving precision requirements and bakeries emerging as a volume growth vector.
- Food Processing Plants:Automated protein lines in Germany, Denmark, and the Netherlands deploy vision-guided robotic cutting to minimize giveaway and standardize output for retail private-label supply chains.
- Bakeries:Artisan scaling demands precise dough division as craft producers industrialize, creating underpenetrated demand for volumetric portioning automation.
- Restaurants:Central kitchen and commissary operations deploy compact automatic units to standardize prep consistency across multi-location chains.
- Catering Services:High-volume event and institutional feeding operations prioritize throughput over precision, favoring semi-automatic or manual configurations.
Food processing plants anchor equipment revenue; bakeries are expanding most quickly as craft-to-industrial transitions accelerate.
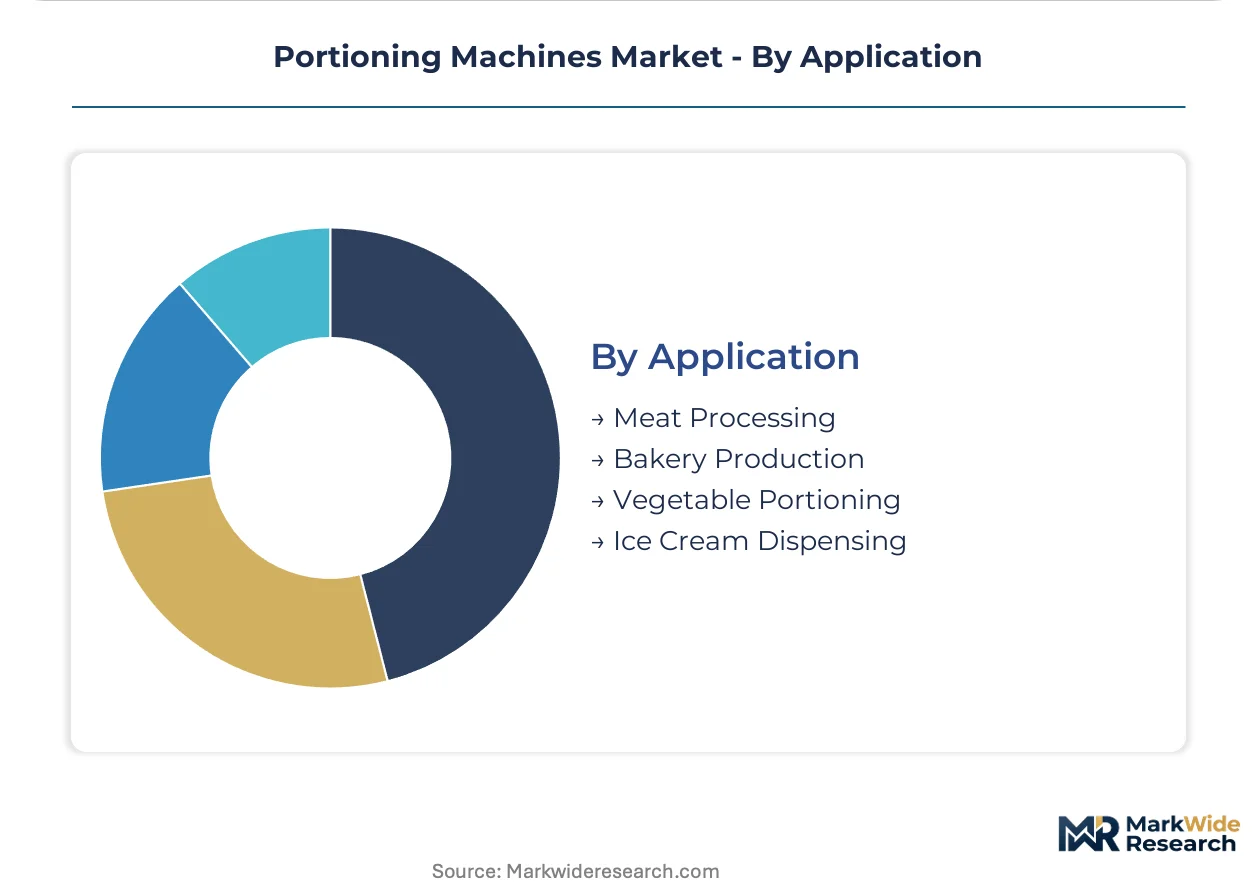
Application:
Application-specific blade materials, surface roughness thresholds, and lubricant specifications face EFSA constraints on raw animal product contact equipment.
- Meat Processing:Raw protein cutting demands hygienic welding-grade stainless steel, traceable control documentation, and REACH-compliant coatings. German facilities lead investment in EU MDR-aligned automated portioning lines.
- Bakery Production:Dough division requires volumetric precision without temperature degradation, driving adoption of servo-controlled extrusion and wire-cutting systems.
- Vegetable Portioning:Produce cutting applications prioritize washdown compatibility and rapid changeover between product SKUs in prepared salad and ready-meal manufacturing.
- Ice Cream Dispensing:Frozen dessert portioning integrates thermal management with volumetric accuracy for foodservice and retail scooping operations.
Meat processing retains the largest application footprint; bakery production claims the steepest expansion trajectory as clean-label ready-meal manufacturing converges with protein automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German portioning machine manufacturers export precision-engineered protein processing equipment to food plants across Denmark, the Netherlands, and broader European markets, establishing a dominant trade-flow corridor in automated cutting technology.
Germany
Food processing plants in Bavaria and North Rhine-Westphalia are scaling automated portioning lines to meet EU MDR hygiene mandates and CE marking requirements for clean-in-place compatibility. The country's central bank, the Bundesbank, tracks capital goods export performance as a macroeconomic indicator. Stuttgart-based equipment fabricators are expanding servo-driven system output to serve protein automation demand across northern Europe.
Denmark
Vertically integrated pork processors are channeling capital into high-throughput portioning infrastructure as labor costs rise in concentrated meatpacking regions. EFSA guidelines on mechanical processing of raw animal products constrain blade materials and lubricant specifications for equipment deployed in Danish facilities. Copenhagen-Aarhus corridor processors are absorbing routine calibration tasks previously outsourced to OEM service networks.
Netherlands
Mid-sized protein processors favor hybrid pneumatic-electric configurations to preserve compressed air investments while upgrading cutting precision. REACH compliance pressures are accelerating lubricant reformulation for food contact applications in dairy portioning lines. Eindhoven-region equipment buyers are extending legacy equipment functional life through transitional architectures rather than full line reconstruction.
United States
Central kitchen and commissary operations deploy compact automatic units to standardize prep consistency across multi-location restaurant chains. FDA food contact substance regulations shape equipment material specifications for domestic protein processing facilities. Chicago-metro meatpacking clusters are retrofitting programmable logic controllers into existing line architectures with custom protocol bridging.
China
Domestic equipment fabricators are capturing share in cost-sensitive segments with minimal electronic complexity and field-repairable mechanical components. SAMR market supervision and GB standards compliance requirements shape hygienic design specifications for food contact equipment. Yangtze River Delta protein processors are adopting vision-guided robotic cutting to minimize giveaway in high-speed production environments.
Portioning Machines Market Competitive Environment
On the supply side, the industry is consolidating around integrated software-hardware stacks and specialized hygienic design capabilities, with tiered competitive positioning separating precision-engineered systems from cost-optimized mechanical alternatives. Strategic archetypes include integrated solution providers bundling cutting hardware with proprietary control systems, regional specialists dominating national protein processing sectors through service proximity, and component suppliers feeding modular equipment architectures. Dominant competitive moves span strategic partnerships between cutting technology developers and vision system providers, plus geographic expansion through localized assembly operations to circumvent logistics cost escalation.
Among European-anchored integrated solution providers, Marel and GEA Group exemplify the software-hardware convergence archetype, while JBT Corporation occupies a position representing North American thermal processing and slicing technology synergies. These three companies anchor the premium-tier competitive vector where proprietary control system integration and regulatory certification depth create defensive positioning against commoditized mechanical alternatives. Danish and German regional specialists such as Handtmann and Bizerba sit within the mid-tier service-intensive segment, leveraging proximity to concentrated protein processing clusters to capture maintenance and blade resupply revenue streams that multinational players struggle to match.
| Leading Market Players |
|---|
| Marel |
| JBT Corporation |
| Multivac |
| Handtmann |
| Bizerba |
| Formax |
| GEA Group |
| Baader Group |
| Reiser |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp port corridor freight rates transmit stainless steel input volatility directly into German equipment pricing, compressing margins for mid-tier fabricators while amplifying differentiation between CE-certified premium systems and standard mechanical alternatives.
Pricing Analysis
Technology-generation pricing gaps separate servo-electric next-generation systems from pneumatic legacy installations and mechanical economy-tier alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, after-sales bundling intensity, and geographic delivery cost. Pricing pressure stems from REACH-compliant lubricant reformulation and stainless steel supply concentration, squeezing mid-tier producers most acutely. Small-scale bakeries and catering operations exhibit highest price sensitivity, while vertically integrated protein processors absorb premium tiers for regulatory alignment.
Supply Chain Analysis
Extended payment terms from specialized European foundries now stretch 90-120 days for hygienic welding-grade stainless steel, tightening working capital for equipment fabricators. Supply concentrates in Germany, Denmark, and Italy for precision-engineered components, with servo motors and load cells drawing from Japanese and German source bases. Single-source vulnerability sits with specialized hygienic welding-grade material suppliers clustered in northern European foundries. Distribution runs through OEM direct sales for large protein processors and regional equipment distributors serving mid-sized bakery and catering segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from blade resupply, software updates, and calibration contracts is expanding faster than hardware sales as Danish and German processing cooperatives unbundle traditional maintenance packages.
For Market Incumbents: Build certification-depth moats by accelerating EU AI Act risk classification compliance for autonomous vision-based cutting systems before regulatory deadlines harden competitive barriers. Deepen backward integration into hygienic welding-grade stainless steel sourcing to offset foundry supply concentration, while capturing stranded asset retrofit demand from pneumatic legacy facilities facing electric displacement pressure. For New Entrants and Emerging Players: Mid-sized artisan bakery producers in the Netherlands and Belgium represent the most penetrable entry point, with precise dough division demand outpacing incumbent service coverage. Hybrid pneumatic-electric transitional architectures offer a technical wedge for facilities deferring full infrastructure replacement. Channel partnerships with regional dairy equipment distributors provide established service proximity without captive technical team investment. For Investors and Strategic Acquirers: Regional specialists with captive maintenance networks in concentrated protein processing clusters offer durable revenue visibility through multi-year blade resupply and calibration contracts. Long-term viability centers on software-hardware integration depth and regulatory certification velocity rather than pure manufacturing scale. Watch for EU AI Act implementation timelines as inflection indicator for autonomous cutting system valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Hardware Integration | Marel and GEA Group leverage proprietary control stacks to defend against commoditized mechanical alternatives in salmon portioning. |
| Regulatory Pre-Certification | Early EU AI Act risk classification for vision-based cutting systems creates defensive positioning before compliance deadlines. |
| Service Model Unbundling | German cooperatives purchasing hardware separately from blade resupply fragments traditional bundled maintenance contracts. |
| Hybrid Architecture Development | Netherlands-based processors adopt pneumatic-electric configurations to extend legacy equipment functional life. |
| Geographic Assembly Localization | Danish and German fabricators establish regional assembly to circumvent logistics cost escalation in equipment export. |
Study Parameters
Cross-validation between equipment procurement databases and regulatory filing records anchors the qualitative findings in documented capital deployment patterns. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across German, Danish, and Dutch protein processing facilities combined with secondary validation from EFSA guidance documents, ECHA substance restriction updates, and CE marking technical files. Bottom-up triangulation across individual facility investment records and top-down analysis of capital goods export flows from the Bundesbank complete the data architecture.
Calibration against historical automation adoption curves in comparable food processing equipment categories shapes the projection framework. Segmentation dimensions span product type, technology generation, end-user scale, and application-specific regulatory exposure across the analysis window. CAGRs derive from installed base replacement cycles, labor cost trajectories, and hygiene mandate implementation timelines. Servo motor cost curves and stainless steel price volatility feed directly into equipment demand elasticity modeling.
Macroeconomic conditions sit as an overlay; deviation in protein commodity prices, eurozone capital goods investment cycles, or vocational training pipeline output for servo technicians would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation pace and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Microbrewery Equipment Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Canning Equipment Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Cookers and Ovens Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Dual-Ovenable Cook Trays Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Walk-In Refrigerators & Freezers Market
Food Processing Equipment
Commercial Food Refrigeration Equipment Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
Defrosting & Thawing Equipment for Food Market
Food Processing Equipment
Commercial Kettles and Braising Pans Market