
 Global Industrial Bakery Processing Equipment Market | 2026-2036
Global Industrial Bakery Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Bakery Processing Equipment Market Intelligence
Demand from large-scale commercial bakeries requiring integrated, automated lines is unwinding the historical market dominance of smaller, standalone equipment sales to baking SMEs. GEA Group leverages its process engineering expertise to offer complete production line solutions. Bühler specializes in grain processing and dough handling technologies, anchoring a significant portion of the high-capacity segment. The Middleby Corporation competes through a diversified portfolio of brands covering various baking and cooking processes.
Industrial bakery processing equipment encompasses automated and semi-automated machinery designed for high-volume production of baked goods. This equipment, typically constructed from food-grade stainless steel, handles specific stages from mixing to baking, with capacities often measured in thousands of units per hour. Tunnel ovens and continuous mixers represent the highest capital expenditure within the equipment portfolio, driven by demand for bread production lines. While the depositor and moulder segments are more fragmented, they offer higher margins on customized solutions for pastry and cookie manufacturing.
Compliance with food contact material regulations, such as those from the US FDA and European CE marking requirements, dictates material selection and design. In China, GB standards for machinery safety and energy efficiency are increasingly influencing equipment specifications for market access. Vendor selection will increasingly hinge on the ability to provide equipment that not only meets these diverse regulatory hurdles but also integrates seamlessly into data-driven production environments.
Market Dynamics
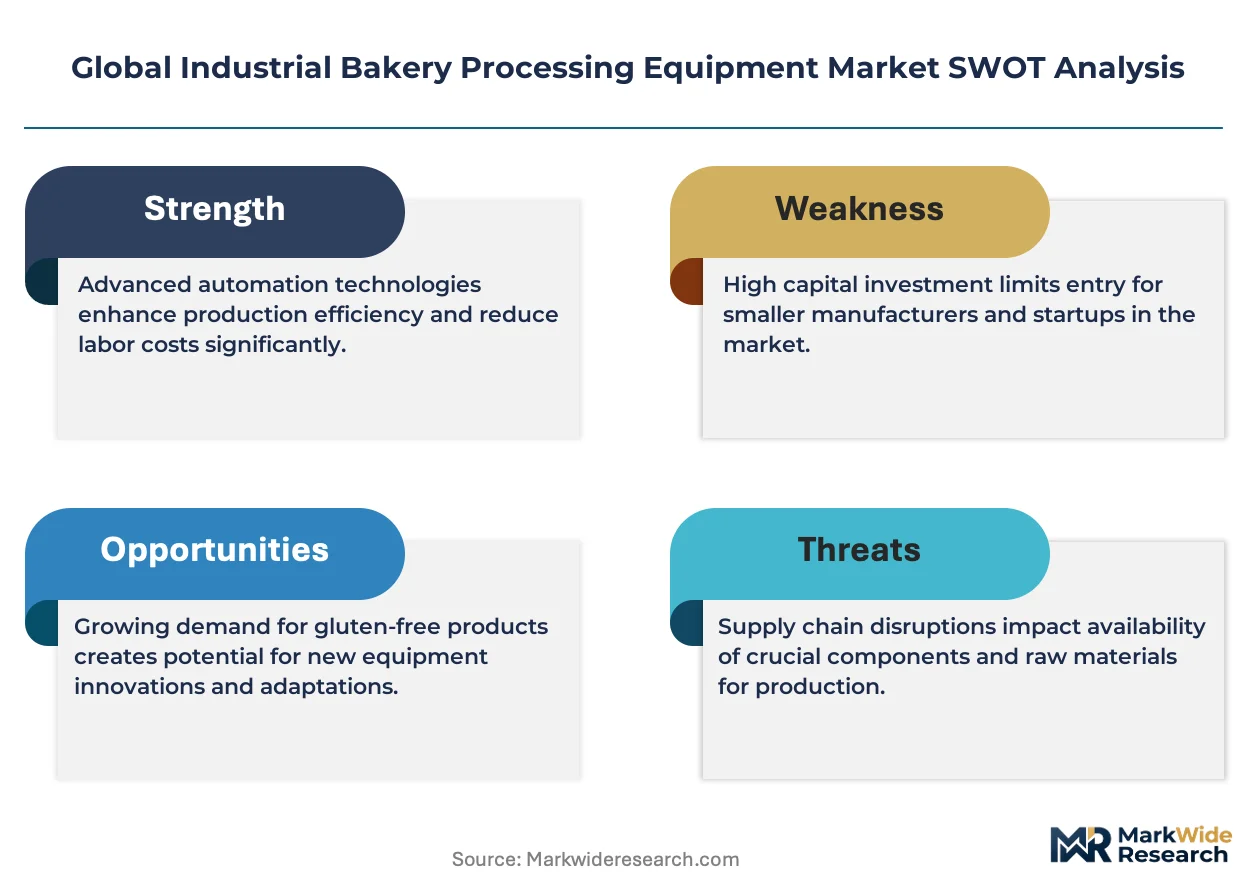
The primary structural force is the market's bifurcation, where demand from large-scale bakeries for integrated, automated lines is eroding the historical dominance of standalone equipment sales to smaller enterprises. This shift favors vendors with deep process engineering capabilities.
Growth Catalysts
- Robotics and Automation:The integration of robotics for repetitive tasks like product handling and depositing is increasing throughput and consistency, a key requirement for frozen food manufacturers.
- Frozen Goods Sector Expansion:Growth in the frozen baked goods category necessitates high-capacity, reliable processing lines, directly spurring investment in continuous mixers and tunnel ovens.
- Demand Concentration in China:The rapid expansion of large-scale commercial bakeries across China creates concentrated pockets of demand for complete, high-volume production systems.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for core components like industrial tunnel ovens and continuous mixers acts as a major barrier for new entrants and smaller bakeries.
- Regulatory Fragmentation:Navigating disparate food contact and safety standards, such as US FDA rules, European CE marking, and China's GB standards, increases design complexity and cost.
- Customization Dependency:While the depositor and moulder segments offer high margins, their reliance on customized, non-standardized solutions limits economies of scale and creates supply chain bottlenecks.
Strategic Opportunities
- Data Integration Services:Offering equipment that integrates seamlessly into data-driven, IIoT-enabled production environments presents a significant value-add for bakeries focused on process optimization.
- Specialized Pastry Solutions:Developing modular and flexible systems for high-margin, niche applications like artisanal pastries and cookies can capture value from less commoditized segments.
- Emerging Market Entry:Targeting bakery modernization projects in Southeast Asia and Latin America, where industrial-scale production is expanding, offers new growth avenues.
Industry Challenges
- Systems Integration Complexity:Ensuring new automated equipment can interface effectively with bakeries' existing legacy systems without causing significant downtime is a primary operational hurdle.
- Skilled Labor Scarcity:A shortage of technicians and engineers with the dual expertise in food science and automation engineering hinders the effective operation and maintenance of advanced lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Bakery Processing Equipment Market |
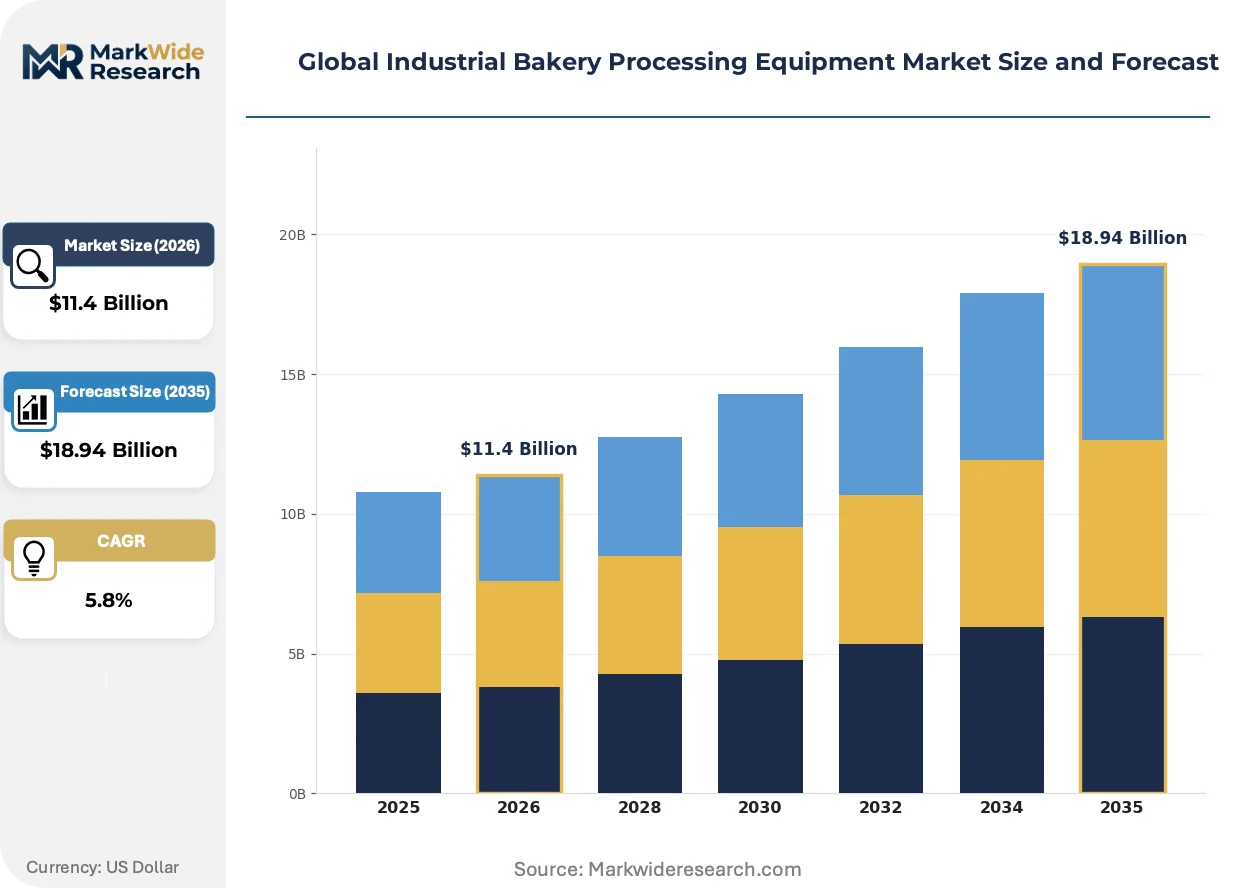
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mixer, Divider, Moulder, Oven, Proofer, Depositor Technology: Steam Injection, Radiant Heat, Convection, Rotary, Tunnel, Impingement Application: Bread Production, Pastry Manufacturing, Cookie Preparation, Cake Baking, Biscuit Processing, Bagel Making End User: Commercial Bakeries, Food Service Providers, Baking SMEs, Frozen Food Manufacturers, Ingredient Suppliers |
| Companies Covered | GEA Group, Bühler, The Middleby Corporation, JBT Corporation, Ali Group, Heat and Control, Rheon Automatic Machinery, Baker Perkins, Markel Food Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Bakery Processing Equipment Market Strategic Shifts & Innovations
The convergence of automation with data analytics is fundamentally altering equipment design and operational strategy. This transformation prioritizes seamless line integration and real-time process control over the performance of individual machines, moving bakeries toward smart factory models.
Robotic systems and automated guided vehicles provide precise handling, depositing, and end-of-line palletizing functions. Large-scale commercial bakeries, especially those supplying quick-service restaurants, are rapidly adopting this technology. This advanced automation is displacing traditional fixed conveyor systems and manual labor, enabling greater production flexibility and hygiene.
Increasingly stringent energy efficiency regulations, such as China's GB standards and the EU's Ecodesign Directive, are influencing equipment specifications. This pressure compels manufacturers to innovate in oven insulation, heat recovery systems, and motor efficiency to reduce operational costs for end-users. The tunnel oven and proofer segments are most affected, with vendors redesigning heating elements and airflow management.
A shift in buying behavior sees large bakery conglomerates favoring single-source procurement for entire production lines. This model sidelines smaller, specialized equipment suppliers in favor of large engineering firms that can deliver and service a fully integrated, turnkey solution. The trend is most pronounced in the North American market for high-volume bread production lines.
Global Industrial Bakery Processing Equipment Market Segmentation
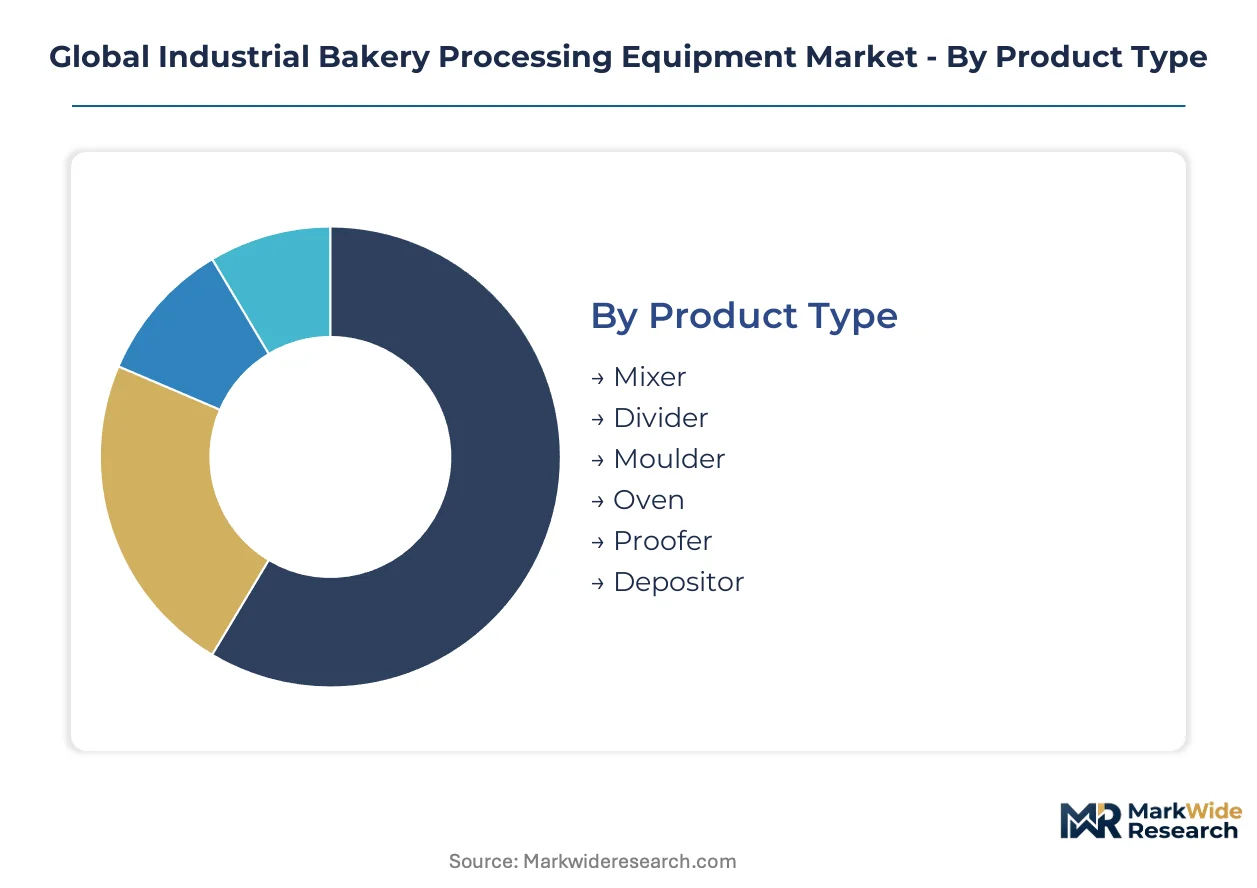
The industrial bakery processing equipment market segments across critical dimensions, reflecting diverse operational needs and production scales. Understanding these classifications reveals distinct demand drivers and technological preferences shaping vendor strategies and market evolution. This granular analysis illuminates where value concentrates and where innovation delivers competitive advantage for manufacturers.
Product Type:
Equipment types exhibit varying geographic demand, with foundational machinery seeing widespread adoption and specialized units finding concentrated demand in specific export markets.
- Mixer:Automated industrial mixers combine ingredients with precision, ensuring consistent dough texture and quality across large batches. Demand for high-capacity continuous mixers is strong in China's expanding commercial bakeries, driven by bread production lines.
- Oven:Industrial ovens, including tunnel and deck variants, provide controlled heat for baking, crucial for product consistency and throughput. Tunnel ovens dominate capital expenditure in North America for high-volume bread production, demanding energy-efficient designs.
- Divider:Dough dividers portion bulk dough into uniform pieces, critical for standardized product weights in automated lines for global markets.
- Moulder:Dough moulders shape divided dough into specific forms, supporting diverse product offerings for pastry and bread manufacturing in Europe.
- Proofer:Proofers control temperature and humidity for dough fermentation, optimizing texture and volume before baking in various climates.
- Depositor:Depositors accurately dispense batter or fillings, essential for precise pastry and cookie manufacturing solutions, particularly in Asia.
Mixer commands the established base. The steepest expansion runs through Oven.
Technology:
Equipment technologies vary significantly in initial capital outlay and operational costs, influencing adoption rates among bakeries of different scales.
- Tunnel:Tunnel oven technology features a continuous conveyor system, enabling high-volume, uninterrupted baking for industrial-scale operations. This technology dominates large-scale bread production lines in Europe, focused on maximizing throughput and energy efficiency.
- Convection:Convection baking utilizes circulating hot air for even heat distribution, reducing baking times and improving product consistency. This technology sees broad adoption among frozen food manufacturers requiring rapid, uniform cooking across diverse product ranges.
- Steam Injection:Steam injection systems introduce moisture during baking, enhancing crust development and texture in specialty bread products for discerning consumers.
- Radiant Heat:Radiant heat ovens deliver direct heat transfer, suitable for specific baking applications requiring surface browning and crispness in high-temperature processes.
- Rotary:Rotary rack ovens offer versatile baking for various products, often found in mid-sized commercial bakery operations seeking flexibility.
- Impingement:Impingement ovens use high-velocity hot air jets, providing rapid and efficient baking for flatbreads and snack items with tight production schedules.
Advanced automation drives the adoption of Tunnel technology. Efficiency gains prioritize Convection systems across diverse applications.
Application:
Market applications are differentiated by the production volumes required, from mass-produced staples to specialized, lower-volume items.
- Bread Production:This application involves high-volume processing lines for various bread types, from mixing to baking and cooling. Demand for automated bread lines is particularly concentrated in China, driven by expanding commercial bakeries and urbanization.
- Pastry Manufacturing:Pastry production requires specialized equipment for dough lamination, filling, and shaping, often demanding customized solutions. This segment offers higher margins for suppliers due to the need for flexible and precise depositor and moulder systems.
- Cookie Preparation:Cookie preparation utilizes depositors and ovens tailored for precise portioning and consistent baking of diverse cookie varieties for global distribution.
- Cake Baking:Cake baking applications require specialized mixers, depositors, and ovens for consistent batter aeration and uniform baking results.
- Biscuit Processing:Biscuit processing involves high-speed lines for mixing, sheeting, cutting, and baking, catering to large-scale snack production.
- Bagel Making:Bagel making equipment includes specialized moulders and boiling/baking systems, serving niche but growing market demand in North America.
Bread Production represents a mature, high-volume application. Pastry Manufacturing demonstrates significant growth potential through customization.
End User:
Different end-user segments exhibit distinct procurement behaviors and equipment requirements, from integrated solutions to standalone units.
- Commercial Bakeries:Large-scale commercial bakeries drive demand for fully integrated, automated production lines capable of high throughput. These entities seek single-source procurement for complete, turnkey solutions, especially in North America.
- Frozen Food Manufacturers:This segment requires high-capacity, reliable processing lines for frozen baked goods, necessitating robust continuous mixers and tunnel ovens. Expansion in the frozen goods sector necessitates systems for product handling and consistency.
- Food Service Providers:Food service providers utilize equipment for on-site baking and finishing, often requiring versatile and compact machinery for diverse menus.
- Baking SMEs:Small and medium-sized enterprises typically purchase standalone equipment, focusing on cost-effectiveness and operational flexibility for local markets.
- Ingredient Suppliers:Ingredient suppliers may use specialized processing equipment for quality control, blending, or pre-treatment of raw materials before distribution.
Commercial Bakeries remain strategically important for high-capital equipment sales. Frozen Food Manufacturers are rapidly gaining importance for continuous line investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive global shipping infrastructure, particularly major port networks, underwrites the international trade and distribution of baked goods, directly influencing demand for industrial bakery processing equipment. This infrastructure facilitates the export of processed foods and the import of raw materials, driving investment in high-throughput production capacities. Efficient logistics support the expansion of large-scale commercial bakeries worldwide.
China
Rapid urbanization and a rising middle class drive significant demand for industrial bakery equipment across China. The country's GB standards for machinery safety and energy efficiency influence equipment specifications for market access. Major industrial zones like the Yangtze River Delta concentrate large-scale commercial bakeries, requiring complete, high-volume production systems.
United States
High-volume bread production and frozen food manufacturers necessitate substantial investment in advanced bakery processing equipment in the United States. US FDA regulations dictate stringent material selection and design for food contact surfaces. Large bakery conglomerates in North American markets, particularly around Chicago and Los Angeles, favor single-source procurement for entire production lines.
Germany
Advanced process engineering expertise drives demand for high-capacity industrial bakery equipment in Germany, especially for dough handling and grain processing. European CE marking requirements ensure equipment compliance with safety and environmental standards. Industrial clusters in regions like Bavaria and North Rhine-Westphalia focus on developing energy-efficient tunnel ovens and continuous mixers.
Brazil
Bakery modernization projects and the expansion of industrial-scale production underpin equipment demand across Brazil. ANVISA regulations govern food contact materials and hygiene standards for processing machinery. Emerging industrial hubs in states like São Paulo and Minas Gerais are adopting automated lines to meet rising consumer demand for processed baked goods.
Global Industrial Bakery Processing Equipment Market Key Industry Players
Listed leaders compete with private specialists across the industrial bakery processing equipment market, creating a tiered competitive structure. The market exhibits consolidation in high-capital segments like tunnel ovens and continuous mixers, while fragmentation characterizes depositor and moulder segments. Strategic archetypes include integrated solution providers, specialized technology firms, and diversified equipment conglomerates. Companies pursue strategic partnerships and portfolio diversification to enhance market reach.
On the integrated solutions vector, GEA Group and Bühler exemplify firms leveraging deep process engineering capabilities to offer complete production line solutions. GEA Group, a German AG, provides comprehensive systems from mixing to baking. Bühler, a Swiss-based company, anchors a significant portion of the high-capacity segment with its advanced grain processing and dough handling technologies. The Middleby Corporation, an American Inc., represents a diversified portfolio approach, covering various baking and cooking processes across its numerous brands.
| Leading Market Players |
|---|
| GEA Group |
| Bühler |
| The Middleby Corporation |
| JBT Corporation |
| Ali Group |
| Heat and Control |
| Rheon Automatic Machinery |
| Baker Perkins |
| Markel Food Group |
| Others |
Cost & Logistics Intelligence
Extended lead times for core components like industrial tunnel ovens directly influence pricing power, favoring suppliers with robust manufacturing capabilities and efficient logistics networks. This structural reality allows established vendors to command premium pricing for high-throughput, integrated solutions, while smaller, specialized equipment often faces more competitive pricing pressures.
Pricing Analysis
Volume-based tiering structures characterize equipment sales, with substantial discounts for large commercial bakeries purchasing complete production lines. Price differentiation stems from the level of customization required for specialized solutions and the integration of advanced automation features. Brand premium also plays a role, with established firms like GEA Group commanding higher prices. Pricing softness runs through commoditized segments, while specialized depositor and moulder solutions maintain higher margins. Baking SMEs exhibit higher price sensitivity compared to large bakery conglomerates seeking turnkey systems.
Supply Chain Analysis
Global maritime shipping lanes underwrite the distribution of industrial bakery processing equipment, creating logistics chokepoints for large machinery. Supply concentration for advanced components draws from Germany for process engineering and the United States for diversified baking technologies. Key raw material dependencies include food-grade stainless steel and specialized automation components like robotics. Regulatory fragmentation, particularly differing food contact and safety standards such as US FDA rules, European CE marking, and China's GB standards, introduces a structural risk. Distribution runs through direct sales channels for large integrated systems and specialized distributors for smaller, standalone units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a high-growth disruption, driven by the accelerating integration of robotics and automation into high-volume bakery operations. This technological inflection is fundamentally altering production paradigms and equipment requirements across the sector.
For Market Incumbents: Fortify core market position by expanding full-service, integrated production line offerings, particularly for the frozen food sector. Invest in advanced IIoT platforms to enable data-driven process optimization, mitigating the threat of operational inefficiencies. Develop specialized expertise in energy-efficient designs for tunnel ovens and continuous mixers to meet evolving regulatory mandates and reduce end-user operational costs. Deepen after-sales service and technical support networks in emerging markets like Southeast Asia to capture new growth.
For New Entrants and Emerging Players: Lead with modular and flexible solutions targeting the high-margin artisanal pastry and cookie manufacturing segments. Focus on developing specialized depositor and moulder systems that offer unique customization capabilities for diverse product ranges. The less commoditized pastry manufacturing application in Europe presents a penetrable segment for specialized technology firms. A go-to-market angle emphasizing rapid deployment and seamless integration with existing legacy systems can reduce customer friction.
For Investors and Strategic Acquirers: Long-term, this sits as a technology consolidation play because the market is bifurcating into integrated solution providers and specialized component manufacturers. Target acquisition profiles should include firms with proprietary robotics and automation expertise or those offering highly customized depositor and moulder technologies. A key signal to watch is the rate of adoption of IIoT-enabled equipment in large commercial bakeries, indicating a broader shift towards smart factory models.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Extension | Introduces new energy-efficient tunnel ovens, reducing operational costs for large bakeries. |
| Platform Integration | Embeds IIoT capabilities into equipment, enabling real-time data analytics for process optimization. |
| Acquisition of Specialist Firm | Secures advanced robotics or specialized moulder technology, enhancing portfolio differentiation. |
| Geographic Expansion | Establishes local manufacturing or service hubs in Southeast Asia, tapping new demand. |
| R&D Investment | Develops next-generation automation for product handling, increasing throughput and hygiene standards. |
Research Approach
The analysis maps industrial bakery processing equipment across product types, technologies, applications, and end-user segments, each validated through extensive interviews with bakery operations managers, equipment engineers, and procurement leads. Secondary data sources included national food safety standards from US FDA, European CE marking, and China's GB standards, alongside industrial association reports and trade statistics. This approach allowed for robust bottom-up and top-down triangulation of market size and growth drivers.
Outputs were cross-referenced against external benchmarks and industry publications to ensure consistency over the projection horizon. The analytical framework integrated segmentation dimensions including specific product type, technology, application, end-user profile, and regional regulatory environment. CAGRs were derived from historical trends and future demand drivers such as the expansion of the frozen food sector and commercial bakery modernization plans, providing a comprehensive forecast.
Forecasts assume regulatory continuity in key regimes like the US, Europe, and China; material policy shifts would require re-modeling. The analysis reflects assumptions regarding raw material price stability and technology development trajectories. Practitioners should keep alternative scenarios live as geopolitical trade dynamics and automation adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Water Pod Soluble Machines Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Sorbitol Production Equipment Market
Food Processing Equipment
Flake Ice Machines Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Food Waste Disposal Equipment Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
Food Preservation Equipment Market