
 Built-In Wine Coolers Market | 2026-2036
Built-In Wine Coolers Market Size, Share, and Industry Trends Forecast 2026-2036
Built-In Wine Coolers Market Analytics
Energy-efficiency mandates from the US Department of Energy is shifting the cost-of-entry calculus for built-in wine cooler manufacturers, forcing redesigns of insulation systems and compressor architectures. Haier Group leverages its compressor manufacturing scale to absorb compliance costs across multiple appliance categories. Electrolux AB differentiates through dual-zone temperature precision that meets stricter standby power thresholds. Liebherr specializes in premium custom-panel integration that commands specification in architect-driven residential projects.
Built-in wine coolers are refrigerated appliances designed for permanent installation within cabinetry, typically operating between 45°F and 65°F with vibration-dampened compressor mounts to preserve wine sediment stability. Their primary commercial purpose centers on protecting varietal integrity through humidity control and UV-resistant glass doors in residential kitchens, hospitality venues, and retail display environments. Dual-zone configurations now lead residential specification due to simultaneous red and white service requirements, while thermoelectric cooling remains fastest-growing in compact undercounter segments where acoustic performance drives purchase decisions. Compressor-based systems still anchor commercial hospitality installations where capacity demands override noise sensitivity.
US DOE appliance standards, California Title 24 building codes, and ENERGY STAR certification thresholds collectively shape product development priorities and retail channel access across North American and European markets. The EU F-Gas Regulation further constrains refrigerant selection for manufacturers serving European hospitality chains, pushing adoption of hydrocarbon alternatives. Stakeholders must monitor evolving minimum efficiency performance standards in key states and the pace of refrigerant transition timelines to align R&D roadmaps with compliance windows.
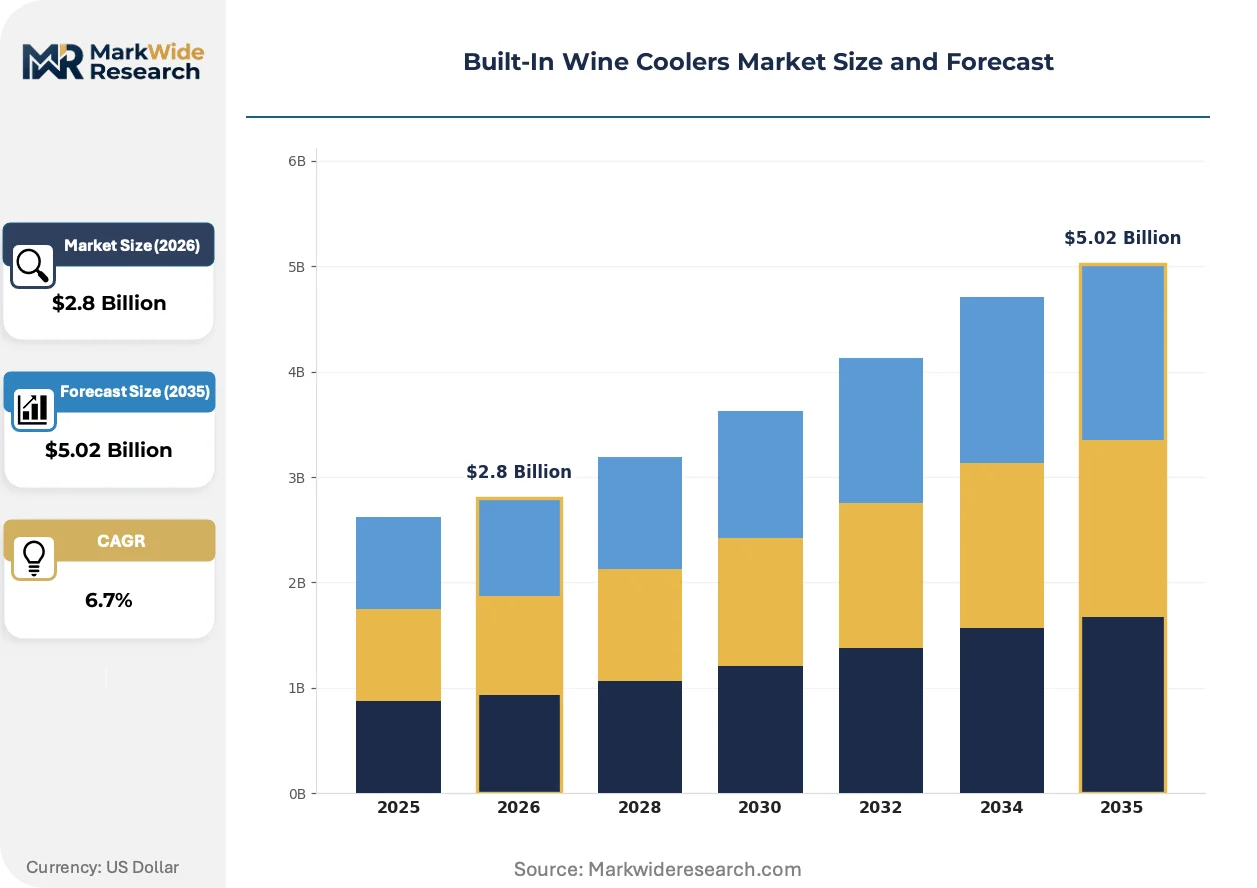
Market Dynamics
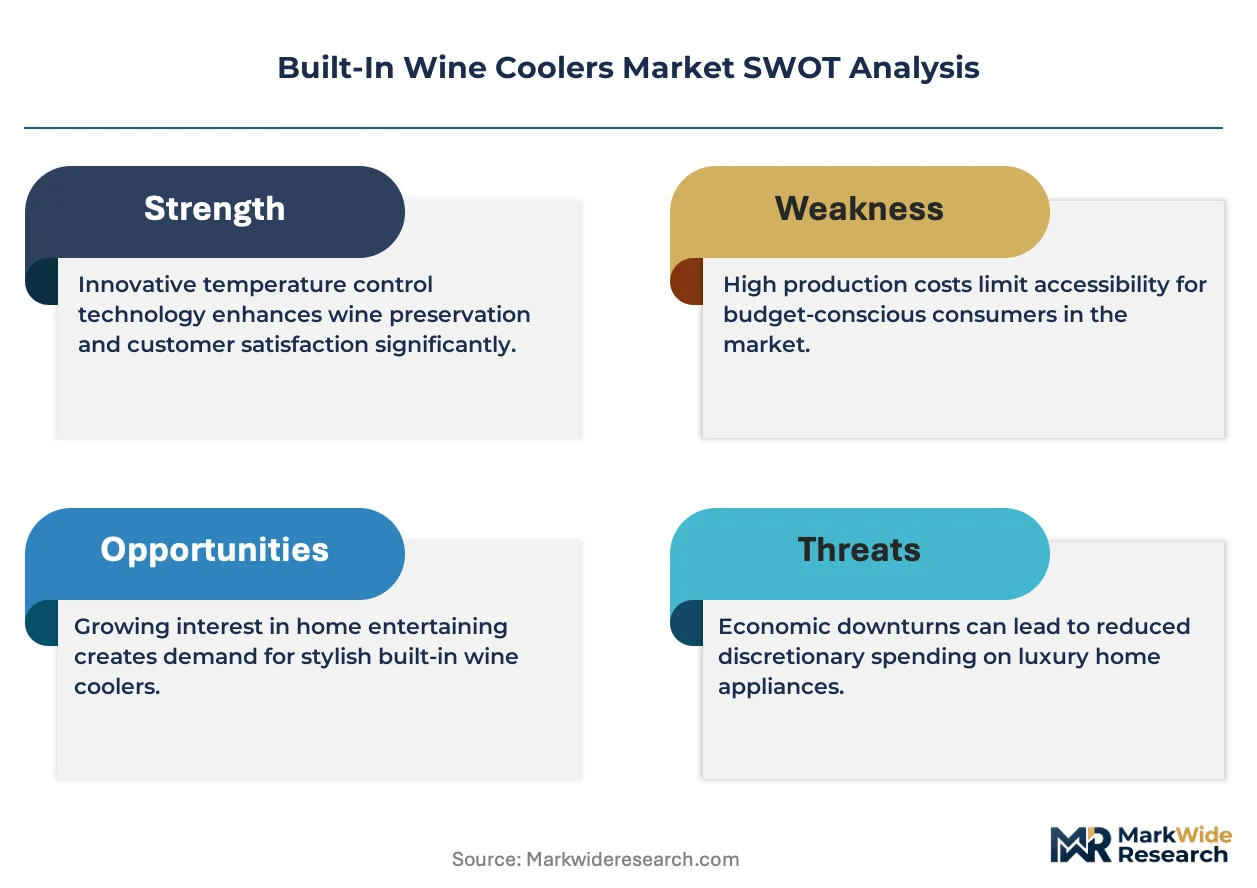
US Department of Energy appliance efficiency standards are compressing margins for entry-level manufacturers while rewarding variable-speed compressor designs that absorb compliance costs across multiple product categories.
Growth Catalysts
- California Title 24 building codes:Mandate high-efficiency appliance specifications in residential renovations, accelerating replacement cycles for undercounter wine cooler installations in luxury kitchen projects.
- Outdoor kitchen integration:Metropolitan Texas markets exhibit accelerating demand for weatherized built-in units that withstand humidity and temperature fluctuations in alfresco entertainment spaces.
- Dual-zone temperature precision:Simultaneous red and white wine service requirements in hospitality venues drive specification of compressor-based systems with independent climate chambers.
Market Restraints
- Copper and aluminum input volatility:Compressor manufacturing and heat exchange coil production face margin pressure from commodity price swings in raw materials procurement.
- EU F-Gas Regulation constraints:Refrigerant selection for European-bound products narrows to hydrocarbon alternatives, forcing R&D retooling and certification delays.
- Thermoelectric cooling limitations:Peltier-based systems face capacity ceilings that exclude them from commercial hospitality installations above 50-bottle storage requirements.
Strategic Opportunities
- Custom-panel integration:Architect-driven residential projects in California's wine corridor reward premium suppliers capable of seamless cabinetry matching.
- ENERGY STAR certification thresholds:Retail channel access advantages accrue to manufacturers achieving standby power benchmarks that entry-level competitors cannot meet.
- UV-resistant glass door technology:Convergence with smart home control systems enables remote humidity monitoring and alert functionality for high-value collections.
Industry Challenges
- Vibration-dampened compressor mount engineering:Talent scarcity in mechanical isolation design constrains product development timelines for sediment-sensitive wine preservation.
- Multi-jurisdiction certification overlap:Simultaneous US DOE, California Title 24, and ENERGY STAR compliance creates testing bottlenecks and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Built-In Wine Coolers Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Zone, Dual Zone, Multi Zone, Undercounter Cooling Technology: Compressor, Thermoelectric, Hybrid, Absorption Size: Compact, Standard, Large, Custom End User: Residential, Commercial, Hospitality, Retail |
| Companies Covered | Whirlpool Corporation, Haier Group, LG Electronics Inc, Electrolux AB, Samsung Electronics Co. Ltd., Bosch, Danby, Dunavox, Liebherr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Built-In Wine Coolers Market Evolving Landscape
Variable-speed compressor architectures and hydrocarbon refrigerant transitions are actively reshaping product development priorities, while smart home integration creates new specification criteria for premium residential channels.
Variable-speed inverter compressors is converging with IoT-enabled temperature logging to enable precise humidity control in dual-zone configurations. Luxury residential buyers in architect-driven projects specify these systems for cellar-quality preservation in kitchen-adjacent installations. The technology is converging with predictive maintenance algorithms that alert owners to door seal degradation or compressor strain before wine integrity suffers.
REACH substance restrictions and the EU F-Gas Regulation are jointly constraining refrigerant selection and insulation material composition for manufacturers serving European hospitality chains. Industrial consequence includes accelerated R&D investment in propane-based cooling circuits and vacuum panel insulation. Premium undercounter segments in Germany and France respond fastest, compressing time-to-market for compliant product lines.
Specification decisions in California's wine corridor now prioritize ENERGY STAR thresholds as a non-negotiable filter for contractor bidding. Traditional distributor relationships face displacement from direct-to-designer platforms that bundle appliance selection with kitchen visualization software. This pattern concentrates most visibly in Napa and Sonoma county renovation markets where sustainability credentials influence project financing.
Built-In Wine Coolers Market Segmentation
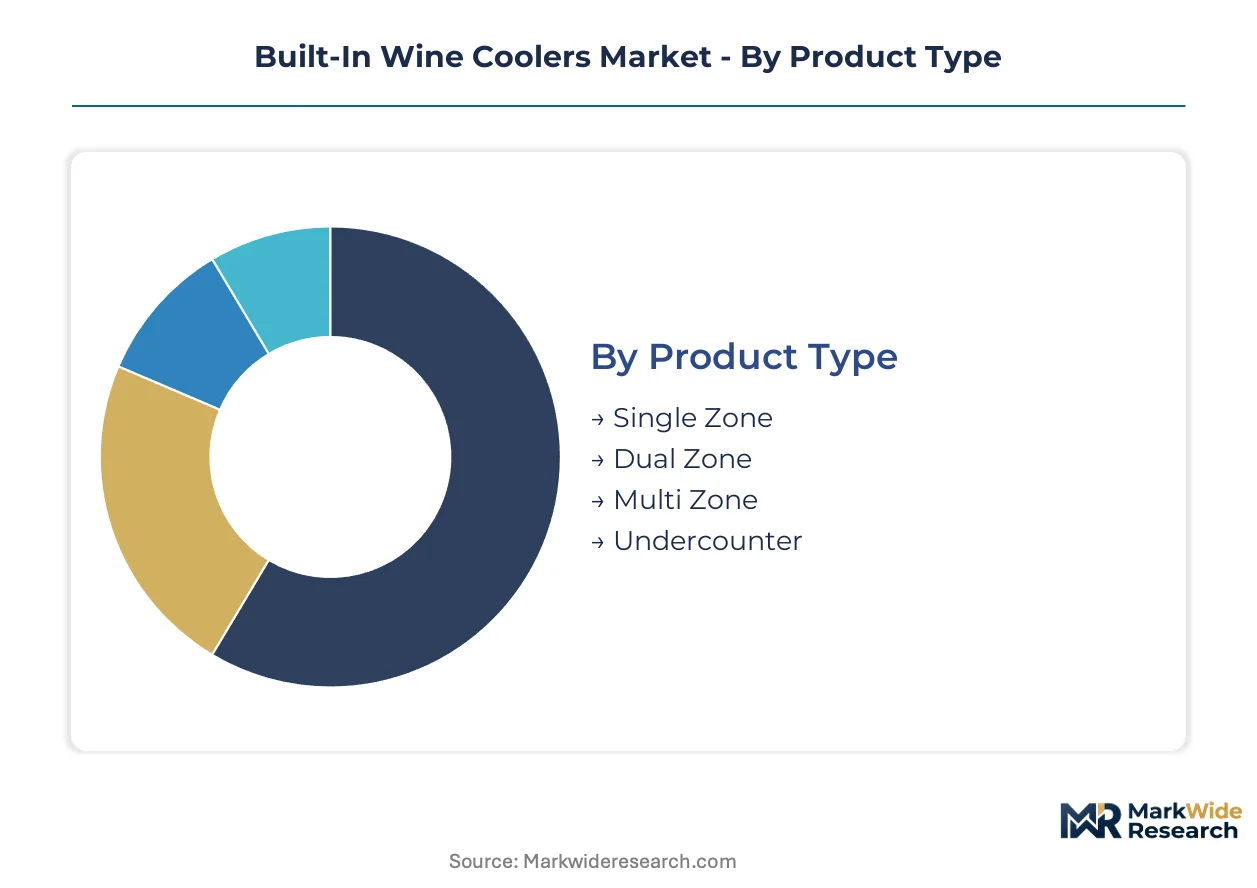
Segmentation in built-in wine coolers reveals how specification criteria diverge between residential renovation projects and commercial hospitality installations. Understanding these divides enables manufacturers to align compressor engineering investments with the channels where margin structures differ most sharply.
Product Type:
Replacement cycles accelerate where kitchen renovation activity concentrates, with upgrade decisions pivoting on zone configuration and service flexibility.
- Dual Zone:Independent climate chambers maintain simultaneous red and white service temperatures between 45°F and 65°F. Demand concentrates in California's wine corridor where architect-driven residential projects specify these units for kitchen-adjacent preservation. California Title 24 building codes reward variable-speed compressor designs that meet standby power thresholds.
- Undercounter:These units integrate permanently within cabinetry at standard counter height, typically housing 24-46 bottles. Metropolitan Texas markets exhibit accelerating specification for weatherized variants that withstand humidity fluctuations in outdoor kitchen installations. ENERGY STAR certification thresholds filter contractor bidding in luxury renovation segments.
- Single Zone:Uniform temperature maintenance suits dedicated red or white collections in compact residential installations.
- Multi Zone:Three or more independent chambers serve high-value hospitality collections requiring precise varietal separation.
Volume placements concentrate in Undercounter configurations; the faster expansion belongs to Dual Zone as simultaneous service requirements spread beyond hospitality into affluent residential kitchens.
Cooling Technology:
Cost tier differentiation separates premium compressor systems from entry-level alternatives, with compliance costs reshaping competitive position at each level.
- Compressor:Vibration-dampened mounts and variable-speed inverter architectures deliver capacity for 50+ bottle installations. US Department of Energy appliance efficiency standards compress margins for entry-level manufacturers while rewarding designs that absorb compliance costs across multiple product categories. REACH substance restrictions and EU F-Gas Regulation constrain refrigerant selection for European-bound products.
- Thermoelectric:Peltier-based cooling operates without moving parts, eliminating acoustic disturbance in compact undercounter segments. Capacity ceilings exclude these systems from commercial hospitality installations above 50-bottle requirements. Demand concentrates where noise sensitivity overrides preservation capacity in bedroom-adjacent or open-plan residential layouts.
- Hybrid:Combined compressor-thermoelectric architectures optimize efficiency across load conditions in mid-tier residential specifications.
- Absorption:Silent operation without mechanical compression serves niche applications in noise-restricted hospitality environments.
Compressor systems dominate commercial channel volume; Thermoelectric configurations are climbing the fastest in compact residential segments where acoustic performance drives purchase decisions.
Size:
Application requirements dictate dimensional constraints, with custom integration commanding premium positioning in architect-specified projects.
- Standard:24-inch width alignment with residential cabinetry modules supports replacement-driven demand in kitchen renovation cycles. Volume concentration in California's wine corridor and metropolitan Texas markets reflects outdoor kitchen integration trends accelerating replacement timing.
- Custom:Bespoke dimensions and panel-ready fronts enable seamless cabinetry matching in luxury residential projects. Napa and Sonoma county renovation markets prioritize sustainability credentials that influence project financing and appliance specification.
- Compact:Sub-18-inch widths serve space-constrained urban installations and secondary service locations.
- Large:30+ inch widths and 100+ bottle capacity anchor commercial hospitality and retail display environments.
Standard sizes capture replacement cycle volume; Custom configurations are expanding most quickly in architect-driven premium residential channels.
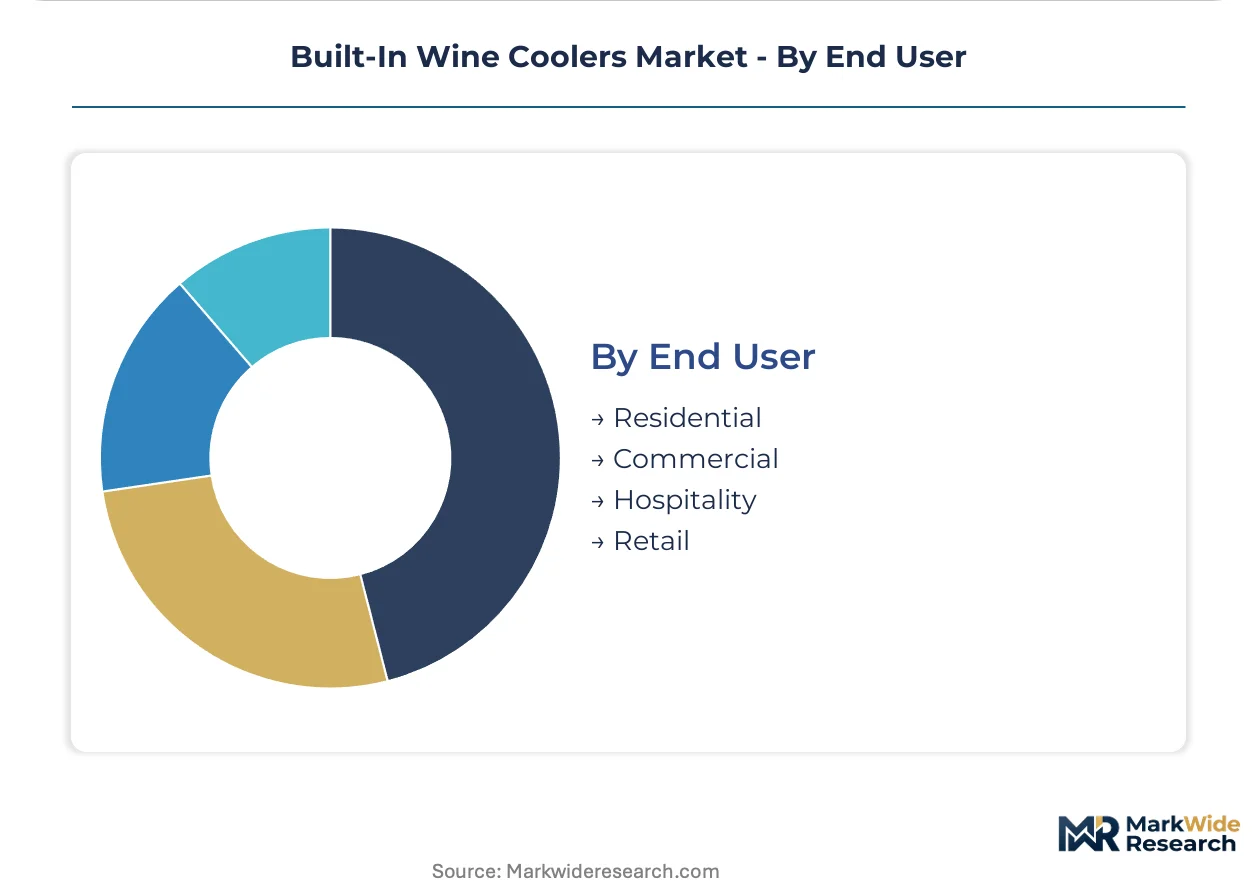
End User:
Customer type determines specification complexity, with hospitality buyers prioritizing capacity and durability over the aesthetic integration valued in residential segments.
- Residential:Kitchen-adjacent installations demand UV-resistant glass doors and humidity control for cellar-quality preservation. ENERGY STAR certification thresholds operate as non-negotiable filters in California Title 24 jurisdictions. Direct-to-designer platforms displace traditional distributor relationships in Napa and Sonoma markets.
- Hospitality:Hotels and restaurants require compressor-based systems with independent climate chambers for simultaneous red and white service. EU F-Gas Regulation pushes adoption of hydrocarbon refrigerant alternatives, forcing R&D retooling for manufacturers serving European hospitality chains.
- Commercial:Corporate and institutional installations balance preservation requirements with procurement standardization.
- Retail:Display-oriented units prioritize visibility and access for customer-facing wine merchandising.
Residential channels dominate unit placements; Hospitality represents the steepest expansion trajectory as foodservice recovery drives renovation investment in premium beverage programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential kitchen renovation intensity concentrates demand in affluent coastal and metropolitan corridors where appliance specification filters through building codes and sustainability financing.
United States
California's wine corridor drives dual-zone specification for simultaneous red and white service in architect-driven residential projects. US Department of Energy appliance efficiency standards compress margins for entry-level manufacturers while rewarding variable-speed compressor designs. Napa and Sonoma county renovation markets prioritize ENERGY STAR certification thresholds that influence project financing access.
Germany
REACH substance restrictions and the EU F-Gas Regulation jointly constrain refrigerant selection and insulation material composition for manufacturers serving hospitality chains. Premium undercounter segments in Bavaria and Baden-Württemberg respond fastest to hydrocarbon cooling circuit adoption. Stuttgart and Munich metropolitan areas concentrate specification of custom-panel integration for luxury residential renovations.
France
EU F-Gas Regulation timelines accelerate R&D investment in propane-based cooling circuits among manufacturers targeting hospitality renovation cycles. Île-de-France and Provence-Alpes-Côte d'Azur anchor demand for UV-resistant glass door technology in high-value residential collections. Parisian design studios increasingly specify ENERGY STAR-equivalent efficiency benchmarks for kitchen-adjacent wine preservation.
Italy
Lombardy and Piedmont wine regions generate concentrated specification of dual-zone undercounter units for residential cellar-quality preservation. CE marking and EU energy labeling requirements filter retail channel access for imported compressor systems. Milan's luxury renovation market rewards seamless cabinetry matching through bespoke panel-ready configurations.
United Kingdom
London and Southeast England renovation activity accelerates replacement cycles for compact undercounter installations in space-constrained urban kitchens. Post-Brexit regulatory divergence from EU F-Gas timelines creates certification documentation burdens for continental manufacturers. Direct-to-designer platforms displace traditional distributor relationships in premium residential specification channels.
Built-In Wine Coolers Market Competitive Landscape
North American producers anchor one tier; European specialists hold premium custom-integration positioning. The vendor base separates into three tiers: diversified appliance conglomerates with compressor manufacturing scale, mid-tier specialists with dual-zone engineering focus, and boutique fabricators serving architect-specified residential projects. Consolidation pressure concentrates among entry-level manufacturers facing US DOE compliance cost absorption, while premium tiers fragment around customization capability. M&A activity targets thermoelectric cooling technology for compact residential segments, and strategic partnerships link appliance manufacturers with kitchen visualization software platforms.
Among diversified conglomerates, Whirlpool Corporation and Haier Group exemplify scale-driven archetypes with cross-category compressor manufacturing integration. Electrolux AB occupies a position within the precision-engineering tier, while Liebherr represents the premium custom-panel specialist segment serving architect-driven specification channels.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Haier Group |
| LG Electronics Inc |
| Electrolux AB |
| Samsung Electronics Co. Ltd. |
| Bosch |
| Danby |
| Dunavox |
| Liebherr |
| Others |
Value Network & Pricing Analysis
Compressor engineering talent scarcity in Baden-Württemberg and Stuttgart metropolitan corridors widens labor-cost differentials between premium custom-panel fabricators and mass-market manufacturers, directly amplifying pricing-tier spreads across ENERGY STAR-certified and entry-level product lines.
Pricing Analysis
Volume placements concentrate in standard undercounter configurations where per-unit margins compress under US DOE efficiency mandates, while custom-panel integration commands three-tier pricing structure across premium, standard, and economy levels based on certification grade and cabinetry-matching complexity. Price differentiation hinges on ENERGY STAR achievement and variable-speed compressor architecture, with California Title 24 compliance operating as a non-negotiable threshold. Cost compression in entry-tier thermoelectric segments is intensifying because copper and aluminum input volatility feeds through heat exchange coil production. Hospitality buyers exhibit lowest price sensitivity given capacity and durability requirements, whereas residential renovation contractors in metropolitan Texas markets show highest sensitivity to weatherized unit premiums.
Supply Chain Analysis
Workforce availability constraints in China's compressor manufacturing zones and Mexico's appliance assembly corridors tether production scheduling to mechanical engineering graduate pipeline fluctuations. Component sourcing draws from Taiwan for inverter control modules, Germany for precision vibration-dampened mounts, and South Korea for UV-resistant glass door assemblies. Raw material dependencies center on copper refrigerant tubing, aluminum heat exchange coils, and hydrocarbon refrigerant alternatives constrained by EU F-Gas Regulation timelines. Single-source vulnerability concentrates in variable-speed compressor inverter chipsets. Distribution runs through kitchen design studios in California's wine corridor and hospitality equipment dealers serving European restaurant renovation cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where US DOE appliance efficiency standards force weaker manufacturers into distressed exit or acquisition scenarios.
For Market Incumbents: Acquire thermoelectric cooling engineering capabilities to secure acoustic-performance positioning in compact residential segments. Absorb compliance costs across multiple product categories through captive compressor manufacturing scale. Deepen backward integration into hydrocarbon refrigerant supply chains ahead of EU F-Gas Regulation enforcement windows. For New Entrants and Emerging Players: Outdoor kitchen renovation contractors in metropolitan Texas markets represent an underserved buyer archetype with accelerating specification demand for weatherized undercounter units. Penetrate this segment through direct-to-designer platform partnerships that bundle appliance selection with kitchen visualization software. Target hospitality renovation cycles in France and Italy where dual-zone precision requirements outpace incumbent R&D velocity. For Investors and Strategic Acquirers: Re-rating potential sits with boutique custom-panel specialists given ENERGY STAR certification thresholds filtering contractor bidding in Napa and Sonoma county renovation markets. Long-term viability favors manufacturers with hydrocarbon refrigerant compliance readiness and architect-driven specification relationships. Watch California Title 24 amendment pace as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Speed Compressor Platform Standardization | Haier Group and Electrolux AB absorb US DOE compliance costs across multiple appliance categories. |
| Hydrocarbon Refrigerant Transition Partnership | Liebherr secures EU F-Gas Regulation readiness through propane-based cooling circuit R&D alliances. |
| Direct-to-Designer Channel Expansion | Premium suppliers displace traditional distributor relationships in California wine corridor renovation markets. |
| Smart Home Integration Development | UV-resistant glass door technology converges with IoT-enabled humidity monitoring for high-value collections. |
| Custom-Panel Fabrication Capacity Addition | Architect-driven residential projects in Germany and Italy reward seamless cabinetry matching capability. |
Research Methodology
Multi-period observation of ENERGY STAR certification thresholds, California Title 24 amendment timelines, and EU F-Gas Regulation compliance windows anchored the trend analysis, supplemented by interviews with appliance engineering directors, hospitality procurement managers, kitchen design studio principals, and compressor manufacturing plant managers. Secondary validation drew from US DOE appliance standard filings, ECHA REACH substance restriction updates, customs records for refrigeration compressor trade flows, and SEC 10-K disclosures from diversified appliance conglomerates. Bottom-up shipment data triangulated against top-down renovation spending estimates across the analysis window.
Segment-weighting applied differential growth assumptions to dual-zone versus single-zone configurations, compressor versus thermoelectric cooling technologies, and residential versus hospitality end-use channels throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycles correlated with kitchen renovation permit data and hospitality renovation investment indicators. Industry-specific inputs included hydrocarbon refrigerant adoption curves, variable-speed compressor penetration rates, and smart home integration specification trends.
Revisions become necessary when US DOE efficiency standard amendments accelerate, EU F-Gas Regulation timelines shift, or copper and aluminum commodity volatility disrupts compressor manufacturing cost structures. Forecasts reflect documented assumptions regarding regulatory compliance windows and renovation cycle intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Mushroom Beer Market
Alcoholic Beverages
Wine Filling Machine Market
Alcoholic Beverages
Canada Alcohol E-Commerce Market
Alcoholic Beverages
Fermented Beverages Market
Alcoholic Beverages
Hopped Malt Extract Market
Alcoholic Beverages
Brazil Alcohol E-Commerce Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Whiskey Market
Alcoholic Beverages
Beer Glass Chillers Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Ready to Serve Cocktails Market
Alcoholic Beverages
Premium Wine Cooler Market
Alcoholic Beverages
Middle East and Africa Wine Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
Wine Glass Market
Alcoholic Beverages
N-Hexyl Alcohol Market