
 Countertop Food Blenders Market | 2026-2036
Countertop Food Blenders Market Size, Share, and Industry Trends Forecast 2026-2036
Countertop Food Blenders Market Insights
The EU Ecodesign Directive is shifting demand toward energy-efficient countertop food blenders with reduced standby power consumption. Vitamix Corporation anchors its position through in-house motor manufacturing and direct-to-consumer channel control. SharkNinja Operating LLC competes aggressively on price-positioned personal blender lines with rapid product refresh cycles. Hamilton Beach Brands, Inc. leverages broad retail distribution across mass-market channels to sustain volume leadership in North America.
Countertop food blenders are electric kitchen appliances with rotating blade assemblies powered by universal or brushless DC motors, typically operating at 10,000 to 30,000 RPM to liquefy, emulsify, or pulverize food ingredients. Units incorporate thermal protection circuits, stainless steel or titanium blade alloys, and Tritan or glass pitcher materials to withstand repeated thermal cycling and mechanical stress. High-performance blenders with 1500W and 1800W power ratings dominate commercial end-use among restaurants and catering services where throughput and ice-crushing capability determine equipment selection. Personal blenders with single-serve vessels are gaining fastest in household segments where convenience and space constraints override raw power requirements. Pre-programmed functions and self-cleaning features concentrate margin pools in premium price tiers where consumers trade up for operational simplicity.
The US Department of Energy enforces appliance efficiency standards under the Energy Policy and Conservation Act, directly affecting motor specifications and standby power limits for blenders sold in American markets. The EU F-Gas Regulation and REACH compliance requirements constrain refrigerant-based cooling systems and material compositions in European-sold units, while China's GB standards and MIIT circular economy directives shape export manufacturing protocols for brands with Asian supply chains. Stakeholders must monitor evolving efficiency mandates and material restriction frameworks to anticipate redesign costs and certification timelines.
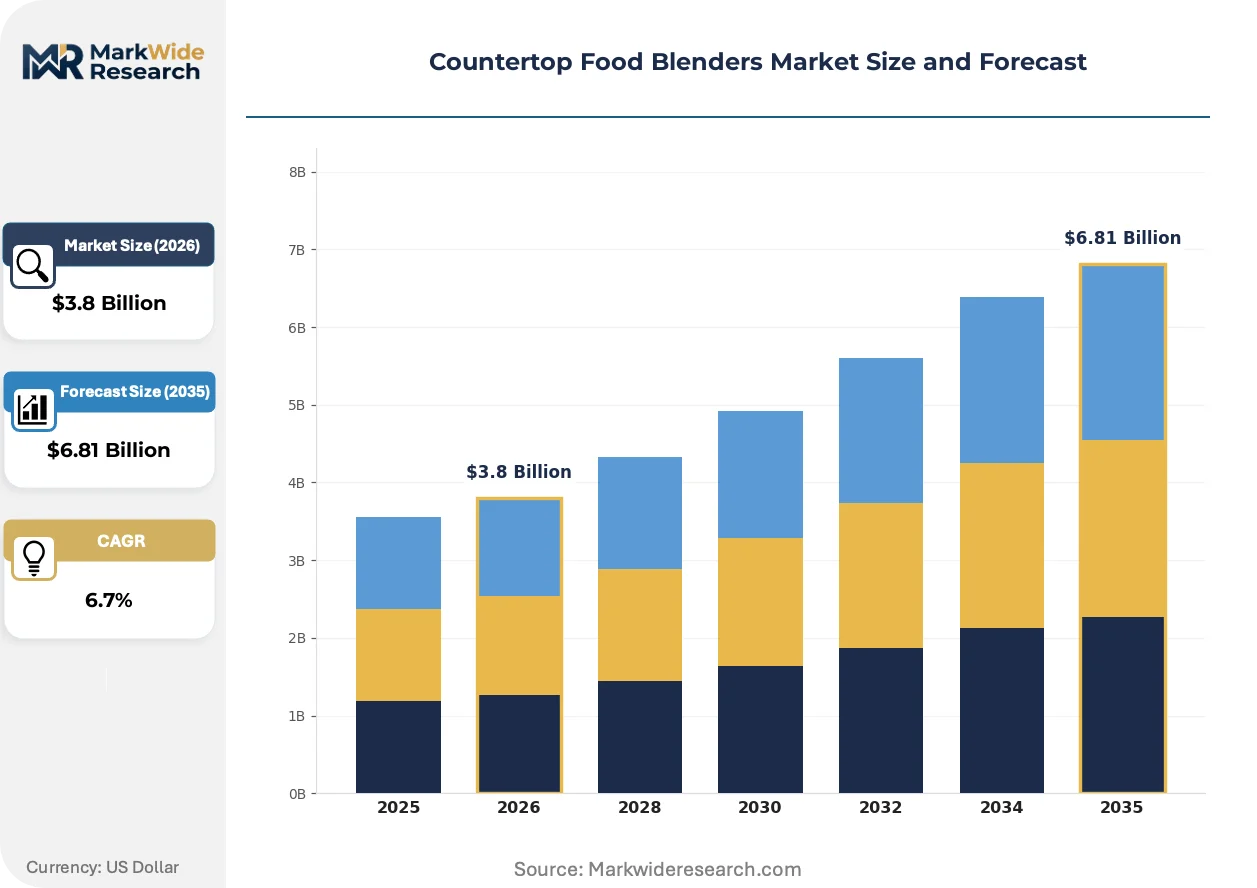
Market Dynamics
The EU Ecodesign Directive and parallel US Department of Energy efficiency standards are forcing motor redesigns across the countertop food blender supply base, compressing development cycles and elevating brushless DC motor adoption rates.
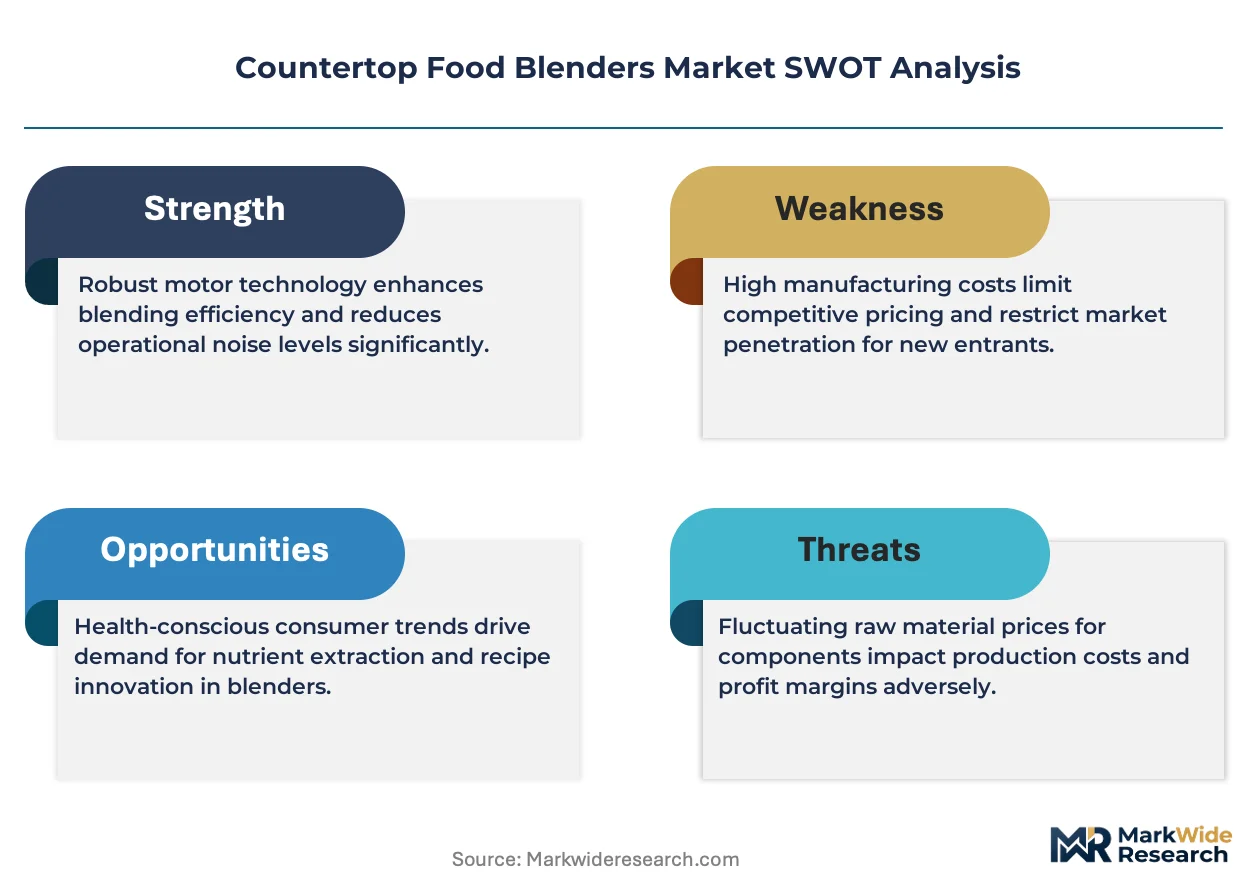
Growth Catalysts
- Household Health Consciousness:Consumers in Germany, the United Kingdom, and Japan are trading up to high-performance models with 1500W+ motors and smart connectivity features.
- REACH Compliance Pressures:Material restriction frameworks in Europe are accelerating substitution of polycarbonate housings with Tritan copolyester and glass alternatives.
- Commercial Kitchen Modernization:Restaurants and catering services are replacing legacy equipment with thermal-protected units capable of sustained ice-crushing throughput.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings inflate brushless motor costs and squeeze mid-tier manufacturer margins.
- Single-Source Concentration:Precision blade forging capacity clusters in Guangdong province, exposing brands to logistics disruptions and tariff exposure.
- Technical Ceiling on RPM:Cavitation limits and thermal degradation constrain maximum sustained operating speeds below 35,000 RPM for consumer-grade units.
Strategic Opportunities
- Underpenetrated Indian Households:BIS certification alignment and localized 230V motor platforms open access to tier-two cities with nascent appliance penetration.
- Smart Home Integration:Voice-control APIs and IoT-enabled recipe synchronization are expanding into premium personal blender segments.
- EU Circular Economy Mandates:Modular repairable designs and take-back schemes qualify manufacturers for green public procurement preferences.
Industry Challenges
- Brushless Motor Engineering Talent:Embedded firmware and power electronics expertise shortages delay product validation timelines.
- Multi-Jurisdiction Certification Burden:Parallel UL, CE, and GB standard testing extends time-to-market by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Countertop Food Blenders Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Blenders, High-Performance Blenders, Food Processor Blenders, Immersion Blenders End User: Households, Restaurants, Cafés, Catering Services Power Rating: 500W, 1000W, 1500W, 1800W Feature: Multiple Speed Settings, Auto Shut-Off, Pre-Programmed Functions, Self-Cleaning |
| Companies Covered | Vitamix Corporation, Hamilton Beach Brands, Inc., SharkNinja Operating LLC, Cuisinart, Breville Group Limited, nutribullet, LLC, Blendtec Inc., KitchenAid, Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Countertop Food Blenders Market Trends and Innovations
Active motor control algorithms and material science advances are redefining performance benchmarks and durability expectations across residential and commercial blender categories.
Brushless DC motor platforms with field-oriented control are expanding into mid-tier household segments previously dominated by universal motors. Manufacturers in Japan and South Korea are integrating these systems into sub-200 USD price points. The technology is expanding into noise-sensitive urban apartments where reduced electromagnetic interference and acoustic dampening command purchase premiums.
The EU F-Gas Regulation and associated Ecodesign standby power limits are compelling firmware updates that cut idle consumption below 0.5 watts. Motor controller suppliers are redesigning gate drivers and power management ICs to meet these thresholds. Premium product lines in Germany and France now lead with sub-0.3 watt standby ratings as competitive differentiators.
Direct-to-consumer subscription models for blade replacement and pitcher refresh are displacing traditional retail attachment sales. Younger households in the United States and United Kingdom prefer automated replenishment tied to usage-cycle algorithms. This shift concentrates customer lifetime value data with brands owning the digital relationship rather than mass-market retailers.
Countertop Food Blenders Market Segmentation
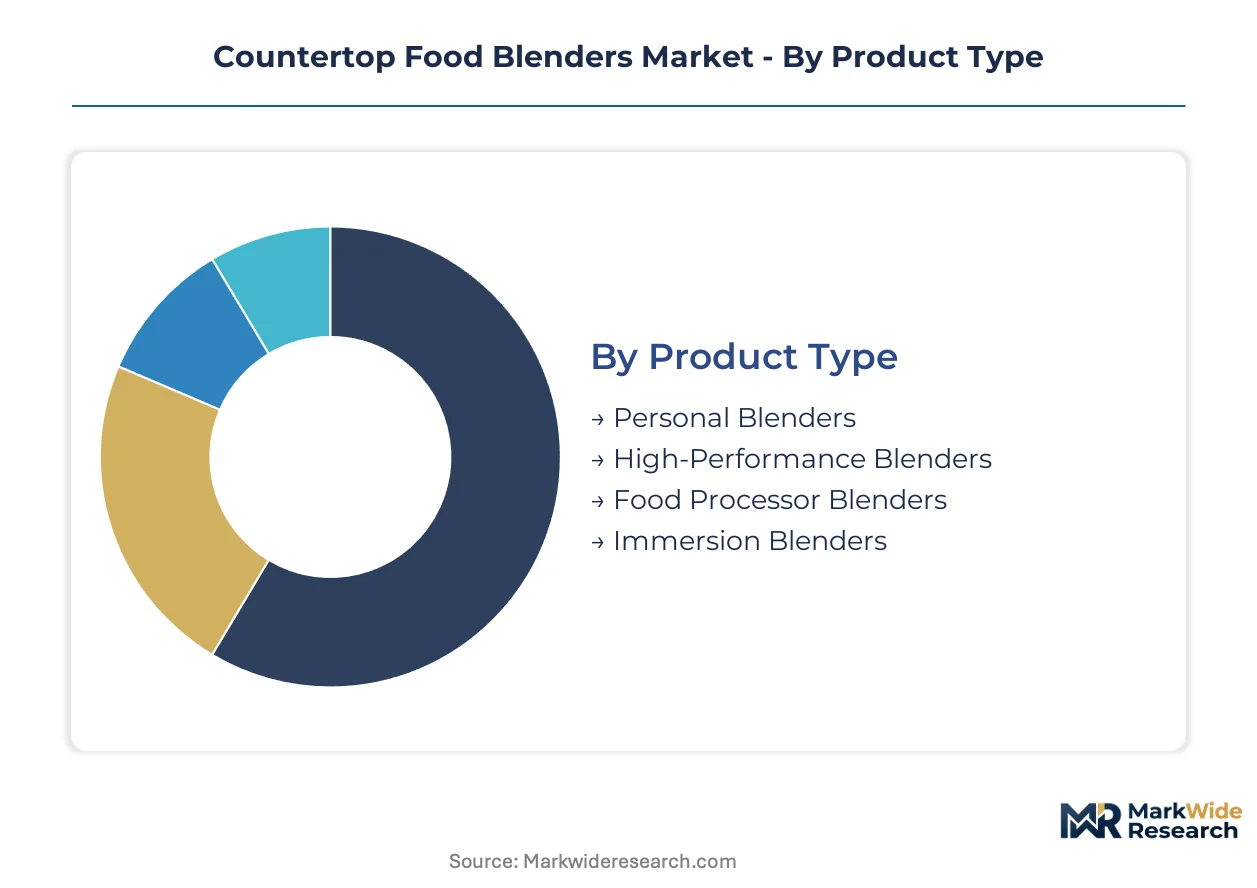
Countertop food blender segmentation reveals how certification burdens, power regulations, and end-use durability requirements fragment manufacturing priorities across price tiers. Each dimension carries distinct UL, CE, and GB testing protocols that reshape R&D allocation and channel strategy.
Product Type:
Personal blenders demand UL 982 safety certification for North American household use, while high-performance units face additional NSF/ANSI commercial sanitation standards. CE marking under the EU Machinery Directive applies universally, though brushless motor variants trigger electromagnetic compatibility testing that universal motor designs avoid.
- Personal Blenders:Compact units with single-serve vessels (typically 300-600ml) integrate directly with portable drinking containers. Demand clusters in urban apartments across Germany, the United Kingdom, and Japan where space constraints and convenience override raw power requirements.
- High-Performance Blenders:1500W-1800W units with thermal protection circuits and hardened blade alloys dominate commercial kitchens. Restaurants in the United States and catering services across France prioritize sustained ice-crushing throughput and extended duty cycles over first-cost savings.
- Food Processor Blenders:Hybrid systems combine blade assemblies with slicing and shredding attachments. These units face dual certification under IEC 60335-2-14 for food processors and IEC 60335-2-14 for blenders, extending validation timelines.
- Immersion Blenders:Handheld stick designs with detachable shafts serve specialized emulsification tasks. Commercial kitchens in Italy and Spain favor these for soup preparation where pitcher immersion is impractical.
High-Performance Blenders sit at the top of the volume ranking, with Personal Blenders climbing the fastest.
End User:
Cost tier alignment determines procurement channel and warranty structure across end-user categories. Household segments prioritize retail availability and aesthetic finish, while commercial buyers negotiate service contracts and replacement part availability.
- Households:Residential purchasers drive volume through mass-market channels, selecting units based on countertop footprint and noise levels. Health-conscious consumers in Japan and Germany trade up to premium personal formats with smart connectivity features.
- Restaurants:Full-service establishments demand NSF-certified units with sealed ball bearings and dishwasher-safe components. Kitchen managers in the United States specify thermal-protected motors capable of 50+ daily cycles without cooldown intervals.
- Cafés:Beverage-focused operations require dedicated ice-crushing capability and rapid pitcher exchange systems. Specialty coffee chains in France and the United Kingdom standardize on 1500W platforms with noise dampening for front-of-house placement.
- Catering Services:Mobile food operations prioritize transport durability and generator compatibility. Caterers across Italy and Spain favor 1000W mid-power units balancing performance against portable power constraints.
Households anchor absolute unit shipments, though Restaurants deliver the steepest expansion trajectory for high-margin commercial configurations.
Power Rating:
Margin structure scales non-linearly with wattage as motor technology shifts from universal to brushless DC platforms above 1000W. Supply concentration in precision magnet manufacturing concentrates cost pressure at the top tier.
- 500W:Entry-level universal motor designs serve basic liquefaction tasks with minimal thermal protection. These units dominate price-sensitive household penetration in tier-two Indian cities where BIS certification alignment is accelerating.
- 1000W:Mid-tier segment bridging residential convenience and light commercial use. Cafés in the United Kingdom and Germany favor this power band for smoothie preparation where ice crushing is intermittent rather than continuous.
- 1500W:Commercial threshold where brushless DC adoption becomes economically justified. Restaurants across the United States specify this rating as the minimum for sustained frozen beverage production without motor degradation.
- 1800W:Peak-performance tier with field-oriented control algorithms and active thermal management. High-volume catering operations in France and industrial test kitchens in Japan deploy these for recipe development requiring maximum particle reduction.
1000W configurations hold the largest installed base, with 1500W platforms gaining share fastest as commercial kitchen modernization accelerates.
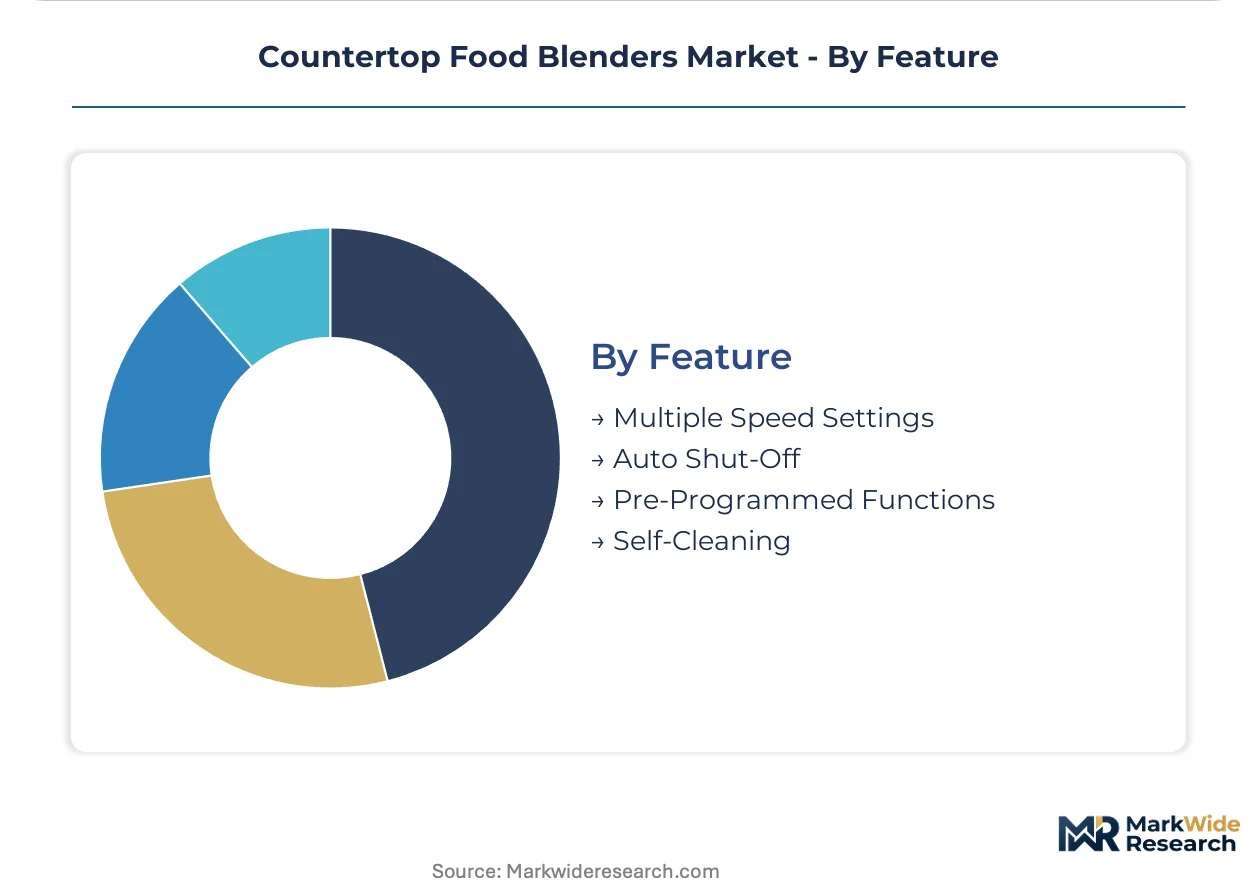
Feature:
Customer type differentiation drives feature bundling, with younger households prioritizing automation and commercial operators emphasizing safety compliance. Firmware development costs concentrate margin pools in pre-programmed and self-cleaning variants.
- Multiple Speed Settings:Analog or digital variable control enabling texture precision from coarse chop to smooth purée. Culinary enthusiasts in Germany and Japan pay premiums for tactile dial interfaces with precise RPM feedback.
- Auto Shut-Off:Thermal and overload protection circuits mandatory for UL and CE compliance. This baseline feature carries minimal differentiation value but eliminates liability exposure for manufacturers.
- Pre-Programmed Functions:Microcontroller-driven cycles for smoothies, soups, and nut butters with automatic speed ramping. Younger households in the United States and United Kingdom favor these for operational simplicity and consistent results.
- Self-Cleaning:High-speed water-and-soap cycles that reduce manual scrubbing. Premium personal blender lines in Japan and South Korea integrate this as standard, displacing traditional pitcher designs in urban apartment segments.
Multiple Speed Settings remains the most specified baseline, with Pre-Programmed Functions expanding most quickly as smart home integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in southern Germany and western Japan anchor precision motor development for high-wattage blender platforms. Appliance design expertise concentrates in US industrial hubs and Italian manufacturing districts.
United States
Health-conscious households in California and New York trade up to 1500W+ smart-connected models. The Department of Energy enforces standby power limits under the Energy Policy and Conservation Act. Cleveland, Ohio hosts mass-market distribution centers serving big-box retail channels.
Germany
Consumers in Bavaria and North Rhine-Westphalia prioritize energy-efficient brushless motor designs. The EU Ecodesign Directive mandates reduced standby consumption below 0.5 watts. Stuttgart engineering firms develop field-oriented control algorithms for premium-tier manufacturers.
Japan
Urban apartments in Tokyo and Osaka drive compact personal blender demand with noise-dampening features. METI oversees appliance efficiency standards and circular economy directives. Nagoya manufacturing clusters produce precision blade forgings for regional brands.
United Kingdom
London and Manchester households favor pre-programmed function sets for operational simplicity. REACH compliance pressures accelerate polycarbonate-to-Tritan material substitution. Birmingham distribution hubs coordinate pan-European logistics for mid-tier brands.
India
Tier-two cities in Maharashtra and Gujarat show nascent appliance penetration for 500W entry-level units. BIS certification alignment accelerates localized 230V motor platform launches. Tamil Nadu assembly plants scale production for price-sensitive household segments.
Countertop Food Blenders Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across motor technology and channel control. The vendor base splits between vertically integrated motor manufacturers and assembly-focused brands sourcing components from Guangdong precision forgers. Three archetypes dominate: premium performance specialists with captive motor production, mass-market assemblers leveraging retail scale, and direct-to-consumer disruptors with rapid refresh cycles. Consolidation pressure intensifies through strategic partnerships for brushless DC controller supply and geographic licensing arrangements.
Within the premium-tier vector, Vitamix Corporation anchors positions through in-house manufacturing control. Hamilton Beach Brands, Inc. exemplifies mass-market scale players dependent on broad retail distribution. SharkNinja Operating LLC occupies the agile disruptor archetype with compressed product development timelines.
| Leading Market Players |
|---|
| Vitamix Corporation |
| Hamilton Beach Brands, Inc. |
| SharkNinja Operating LLC |
| Cuisinart |
| Breville Group Limited |
| nutribullet, LLC |
| Blendtec Inc. |
| KitchenAid |
| Philips |
| Others |
Pricing and Supply Chain Analysis
The EU Ecodesign Directive gates qualified supply and premium-tier pricing access by mandating sub-0.5 watt standby consumption and brushless DC motor platforms. Manufacturers meeting these thresholds command pricing premiums in Germany and France, while non-compliant assemblers face margin compression in mass-market channels.
Pricing Analysis
Subscription blade-replenishment services versus unbundled transactional sales split the pricing landscape. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified commercial units from basic household models. Price differentiation hinges on certification grade and after-sales bundling. Pricing pressure stems from rare earth magnet volatility squeezing brushless motor costs. Mass-market households exhibit highest price sensitivity, while commercial kitchens prioritize thermal protection over first-cost savings.
Supply Chain Analysis
CE and UL certification requirements gate component sourcing and final assembly location decisions. Precision blade forging concentrates in China, motor controller production centers in Japan and South Korea, and final assembly distributes across Vietnam and Mexico. Supply chains draw from neodymium magnets, Tritan copolyester housings, and field-oriented control ICs. Single-source concentration in Guangdong province exposes brands to tariff exposure. Distribution runs through mass-market retailers, direct-to-consumer platforms, and commercial foodservice dealers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The countertop food blender market operates as a regulatory compounder where successive efficiency mandates from the EU Ecodesign Directive and US Department of Energy continuously upgrade replacement demand.
For Market Incumbents: Cement market position through in-house brushless motor production and direct-to-consumer channel control. Acquire precision forging capacity in alternative geographies to reduce Guangdong concentration risk. Invest in firmware development teams to meet tightening standby power thresholds ahead of competitors. For New Entrants and Emerging Players: BIS certification in India opens a window for localized 230V motor platforms targeting tier-two cities with nascent appliance penetration. Exploit modular repairable designs qualifying for EU green public procurement preferences. Pursue voice-control API partnerships to differentiate in premium personal blender segments. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier assemblers with established retail relationships because channel access barriers exceed manufacturing scale requirements. Target firms with captive brushless DC controller supply agreements. Watch rare earth magnet price stabilization as the inflection indicator for margin recovery timing.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Platform Migration | EU Ecodesign Directive compliance enables premium-tier pricing access in Germany and France. |
| Direct-to-Consumer Channel Expansion | Subscription blade replenishment concentrates customer lifetime value data away from retailers. |
| Precision Forging Geographic Diversification | Tariff exposure reduction through secondary supplier qualification in Vietnam and Mexico. |
| Smart Home API Integration | Voice-control partnerships differentiate premium personal blenders in Japanese urban apartments. |
| Modular Repairable Design Adoption | EU circular economy mandates qualify manufacturers for green public procurement preferences. |
Research Methodology
Multiple input streams — primary interviews with motor engineering directors, retail category buyers, and commercial kitchen procurement managers; secondary validation through customs records, SEC filings, and EU regulatory databases; plus technical specification analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations covered supply chain planners at component manufacturers, brand managers at mass-market assemblers, and aftermarket service heads at commercial foodservice dealers.
Data-stream reconciliation produced volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-user category, power rating tier, and feature bundling. CAGRs were derived from installed base turnover rates and replacement cycle compression. Forecast inputs incorporated brushless DC motor adoption curves and evolving efficiency mandate compliance timelines.
Revisions become necessary when rare earth magnet price volatility exceeds historical bands or when standby power thresholds tighten beyond current firmware capabilities. Forecasts reflect assumptions about certification timeline stability and supply chain relocation feasibility. A model refresh is warranted upon material change in EU Ecodesign Directive implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Food Processing Market
Food Processing Equipment
Countertop Convection Oven Market
Food Processing Equipment
Freeze-Drying Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Mixer Settler Market
Food Processing Equipment
Food Waste Disposal Equipment Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Air Cooled Cube Ice Machines Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
Cold Storage Equipment Market
Food Processing Equipment
Double Stack Oven Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market