
 Multi Cooker Market | 2026-2036
Multi Cooker Market Size, Share, and Industry Trends Forecast 2026-2036
Multi Cooker Market Intelligence
Commercial kitchen adoption is broadening beyond traditional restaurants into catering services and food trucks, reshaping the end-use vertical mix for multi cooker manufacturers. Instant Pot leverages its brand strength in North American retail channels to sustain household loyalty. Breville anchors the premium segment through product specialization in precision temperature control. Ninja competes aggressively on manufacturing scale across mid-tier electric and pressure cooker lines.
A multi cooker is an automated, programmable countertop appliance that combines pressure cooking, slow cooking, sautéing, steaming, and warming functions within a single sealed vessel typically rated between 700 and 1,500 watts, designed to reduce meal preparation time and consolidate kitchen equipment for residential and commercial users. Electric models dominate volume shipments due to plug-and-play convenience, while smart technology variants embedding Wi-Fi connectivity and app-based recipe programming capture the fastest expansion as consumers trade up from non-smart predecessors. The six-to-ten-liter capacity band occupies the core margin pool, balancing family-sized utility against countertop footprint constraints.
The U.S. Consumer Product Safety Commission and Underwriters Laboratories shape electrical safety and pressure vessel certification requirements that govern market access for imported units. The European Union's Ecodesign Directive and CE marking obligations enforce standby power limits and material traceability standards that elevate compliance costs for non-European suppliers. Stakeholders must monitor how diverging energy-labeling regimes between the EPA's ENERGY STAR program and EU tiered efficiency scales fragment product platform strategies across Atlantic markets.
Market Dynamics
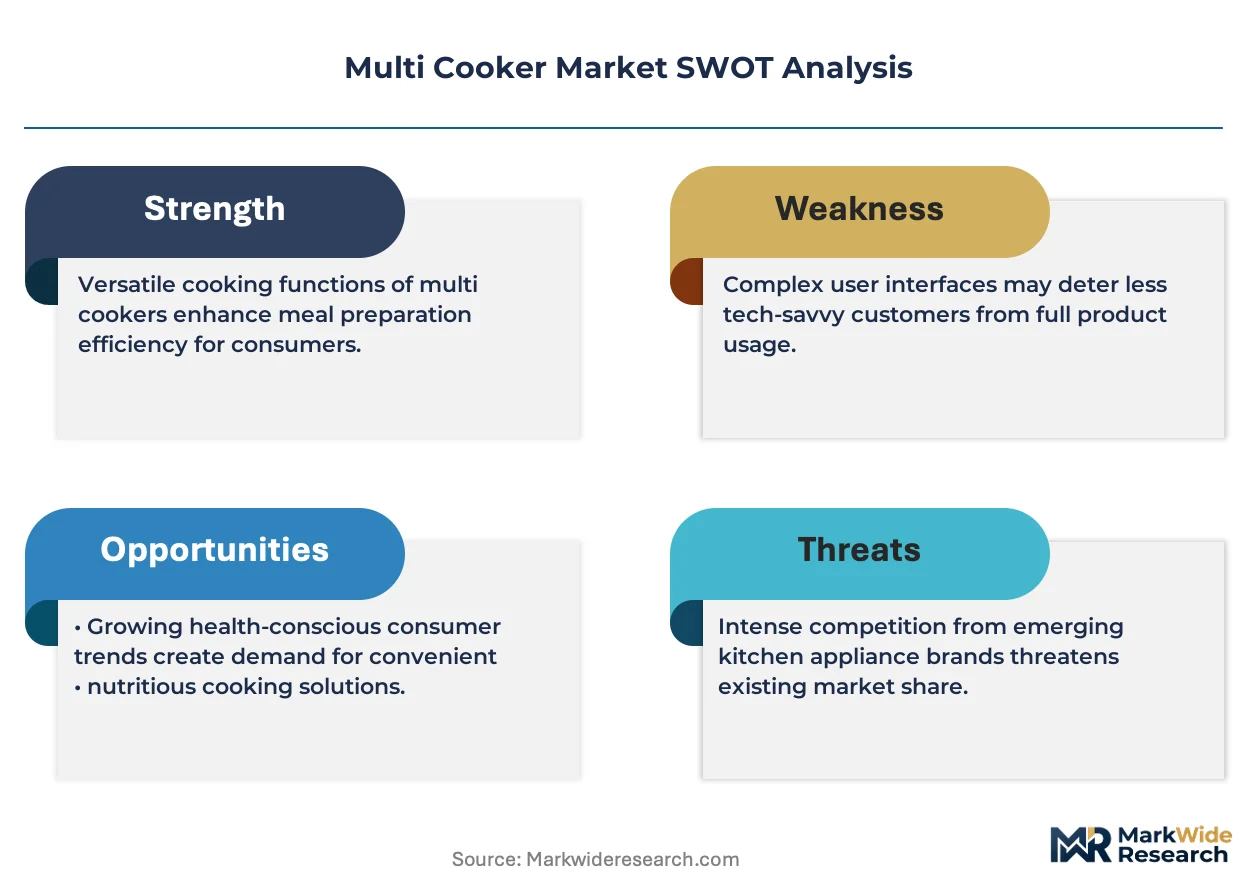
Smart home integration requirements are forcing appliance manufacturers to rearchitect product platforms around embedded connectivity stacks and cloud API interoperability, compressing development cycles and elevating firmware complexity beyond traditional hardware engineering competencies.
Growth Catalysts
- EU Ecodesign standby power limits:Manufacturers redesigning power management circuits to meet the European Commission's 0.5-watt standby ceilings are simultaneously unlocking battery-backup compatibility for emerging off-grid residential segments.
- Cloud kitchen proliferation:Delivery-optimized ghost kitchens in urban India and Brazil are consolidating equipment footprints, driving commercial procurement of multi-function appliances that replace discrete pressure cookers, rice cookers, and warming stations.
- Induction heating modules:Adoption of precision induction elements replacing resistive coils is cutting preheat latency by half, addressing the primary friction point in consumer satisfaction surveys for electric multi cookers.
Market Restraints
- Stainless steel price volatility:Surcharges on 304-grade sheet metal from Chinese and Indonesian mills are compressing gross margins for mid-tier manufacturers lacking forward purchase agreements with Korean or Japanese steel suppliers.
- Pressure vessel certification backlog:Underwriters Laboratories' expanded testing protocols for lid-locking mechanisms have extended UL certification timelines from 12 to 22 weeks, delaying seasonal product launches.
- Single-function appliance substitution:Dedicated air fryers and sous vide immersion circulators priced below $60 are capturing countertop space from entry-level multi cookers in North American big-box retail.
Strategic Opportunities
- Indonesia's electrification push:PLN's rural grid expansion and government appliance subsidy programs are opening first-time buyer segments in Java and Sumatra previously dependent on LPG stoves.
- Voice assistant integration:Native Alexa and Google Home compatibility is creating premium pricing power among smart home ecosystem participants, with recipe-to-appliance command pipelines reducing user interface friction.
- Commercial leasing models:Equipment-as-a-service arrangements for catering fleets and food trucks are shifting revenue from unit sales to recurring service contracts with predictive maintenance attachments.
Industry Challenges
- Firmware engineering scarcity:Embedded Linux and RTOS expertise required for OTA update architectures is concentrated among semiconductor vendors and automotive suppliers, forcing appliance OEMs into bidding wars for talent.
- Cross-border compliance fragmentation:Divergent pressure-cooking safety thresholds between the U.S. Consumer Product Safety Commission and Japan's Consumer Affairs Agency are necessitating region-specific mechanical designs rather than global platform standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi Cooker Market |
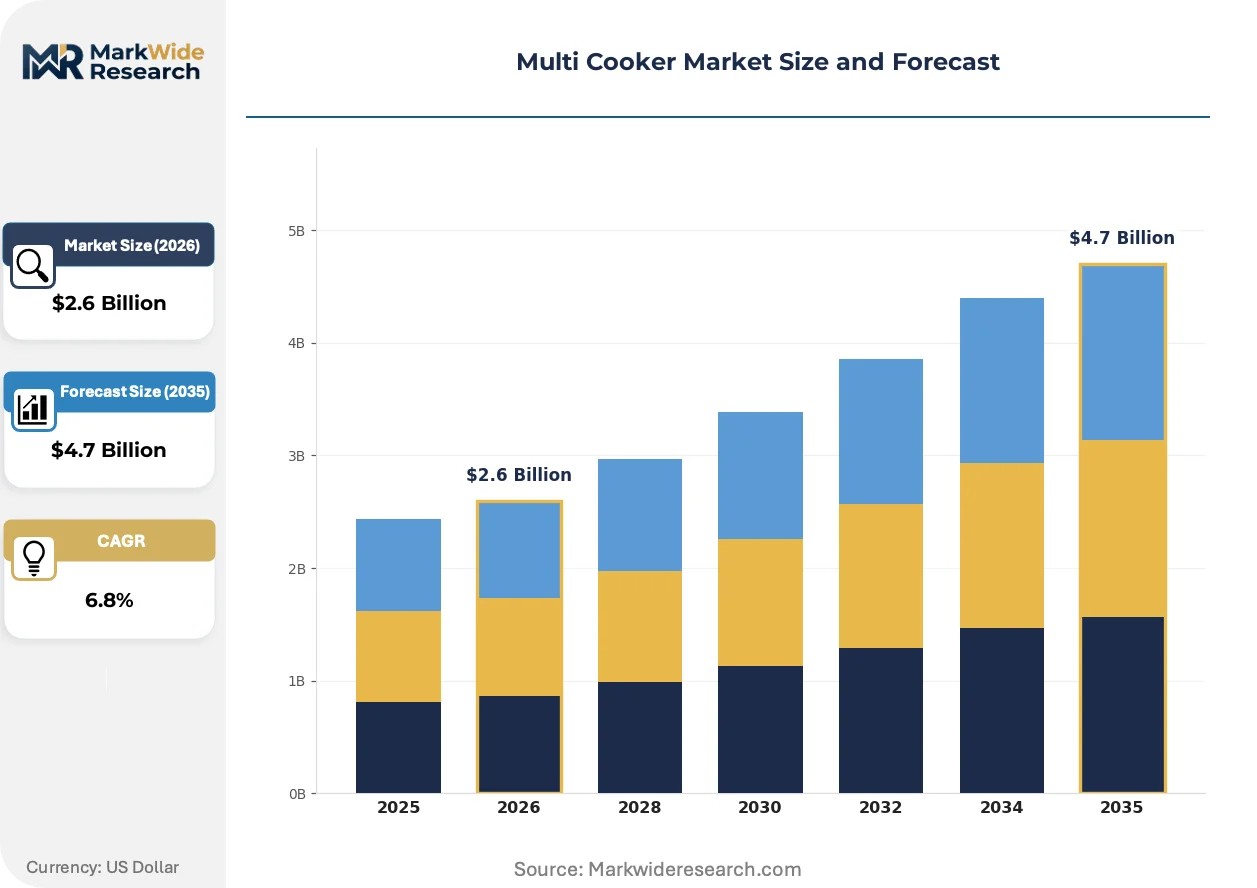
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Stovetop, Pressure Cooker, Slow Cooker Capacity: 1-5 Liters, 6-10 Liters, 11-15 Liters, Over 15 Liters Technology: Smart Technology, Non-Smart Technology, Induction Heating, Conventional Heating End User: Households, Restaurants, Catering Services, Food Trucks |
| Companies Covered | Zavor, Cosori, Instant Pot, Our Place, Chef iQ, Ninja, Sage, DeLonghi, Breville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi Cooker Market Strategic Shifts & Innovations
Connectivity architectures are migrating from Wi-Fi-only to multi-protocol stacks integrating Matter and Thread, enabling seamless interoperability across fragmented smart home ecosystems and reducing consumer onboarding friction.
Sensor fusion combining pressure transducers, temperature probes, and humidity detectors is decentralizing cooking control from pre-programmed recipes to real-time adaptive algorithms. Mid-tier manufacturers in Shenzhen and Dongguan are licensing these IC packages from semiconductor foundries, collapsing the feature gap with premium brands. The result is compressing price premiums previously commanded by precision-cooking specialists.
The European Union's F-Gas Regulation and accompanying Ecodesign requirements for refrigerant-containing appliances are pressuring manufacturers to eliminate cooling circuits from warming functions. Industrial consequence includes accelerated R&D into vacuum-insulated retention vessels that maintain safe serving temperatures without active compression. Korean and German appliance divisions are most affected, with product roadmaps now prioritizing passive thermal management over mechanical refrigeration.
Direct-to-consumer subscription models bundling appliances with ingredient delivery are displacing traditional retail attachment strategies. Meal-kit providers in California and Texas are piloting hardware-software bundles where recipe data feeds back to optimize appliance firmware. Food truck operators represent the most visible adopters, using these arrangements to reduce upfront capital deployment and align equipment costs with revenue cycles.
Multi Cooker Market Segmentation
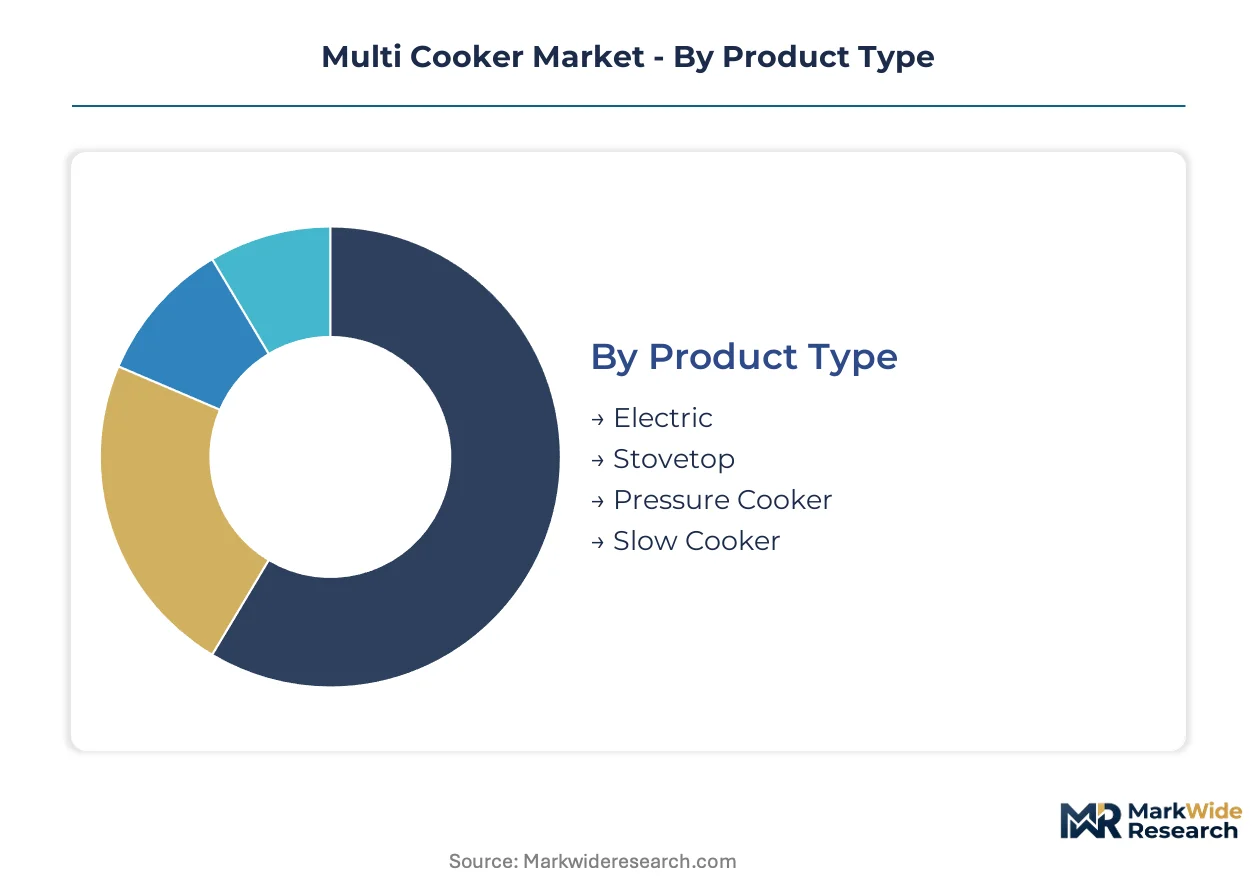
Segmentation in the multi cooker market reveals how capital allocation, technical complexity, and end-use requirements fragment manufacturing strategies. Equipment specifications diverge sharply between residential convenience buyers and commercial operators optimizing throughput per square foot.
Product Type:
Electric multi cookers demand the heaviest upfront tooling investment due to embedded control systems and safety certification requirements for pressure vessel integration.
- Electric:Programmable countertop units rated 700-1,500 watts integrate pressure, slow-cook, sauté, and warming functions within sealed vessels. Demand clusters in U.S. suburban households seeking consolidation of single-purpose appliances, with smart home integration commanding premium positioning. U.S. Department of Energy efficiency mandates are accelerating power management circuit redesigns.
- Pressure Cooker:Sealed-vessel designs utilizing steam pressure to elevate boiling points and reduce cooking duration by 70%. Commercial kitchens in India's cloud kitchen sector are standardizing on these units to compress meal preparation cycles during peak delivery windows. BIS certification requirements govern mechanical lid-locking specifications.
- Stovetop:Manual pressure vessels requiring external heat sources, traditionally constructed from aluminum or stainless steel. Remains prevalent in Indonesian rural markets where PLN grid expansion is incomplete and LPG substitution drives first-time appliance purchases.
- Slow Cooker:Low-wattage ceramic or metal vessels maintaining 80-90°C for extended durations without pressure sealing. Retains niche positioning in North American meal-prep subscription bundles where unattended daytime operation aligns with work-from-home schedules.
Most installed capacity flows through Electric. Expansion is steepest in Pressure Cooker.
Capacity:
Manufacturing cost curves steepen nonlinearly above 10 liters due to reinforced vessel walls and extended heating element specifications.
- 6-10 Liters:The core margin pool balancing family-sized utility against countertop footprint constraints. U.S. big-box retail channels concentrate promotional activity here, with voice-assistant integration creating pricing power differentiation. EPA ENERGY STAR thresholds are tightening standby power limits for this volume band.
- 1-5 Liters:Compact vessels targeting single-person households and dormitory environments. Japanese manufacturers dominate this specification tier through precision temperature control algorithms originally developed for rice cooker platforms. METI efficiency labeling requirements shape regional product roadmaps.
- 11-15 Liters:Commercial-grade vessels for small catering operations and ghost kitchen stations. Brazilian food truck fleets are adopting these units to replace discrete rice cookers and warming stations, reducing equipment capital deployment.
- Over 15 Liters:Industrial-scale vessels requiring dedicated electrical circuits and reinforced mounting structures. European commercial leasing models are emerging here, shifting revenue from unit sales to predictive maintenance contracts.
Volume shipments peak at 6-10 Liters. Climbing the fastest is 11-15 Liters.
Technology:
Smart capability deployment fragments engineering resources between connectivity stack integration and core thermal management.
- Smart Technology:Wi-Fi-enabled units with app-based recipe programming and OTA firmware update architectures. U.S. smart home ecosystem participants command premium pricing through native Alexa and Google Home compatibility. FCC Part 15 certification requirements govern radio frequency emissions.
- Induction Heating:Precision electromagnetic elements replacing resistive coils, cutting preheat latency by half. Korean appliance divisions are prioritizing this technology to address consumer satisfaction friction points identified in post-purchase surveys. MFDS electrical safety standards apply.
- Non-Smart Technology:Microcontroller-based units without cloud connectivity, retaining cost advantage in price-sensitive Southeast Asian markets. Shenzhen manufacturing clusters dominate component sourcing for this tier.
- Conventional Heating:Resistive coil elements with bimetallic thermostat control, simplest architecture with lowest failure rates. Indonesian government subsidy programs favor this specification tier for rural electrification households.
Production volume concentrates in Non-Smart Technology. Gaining share fastest is Smart Technology.
End User:
Commercial applications require divergent durability specifications and warranty structures compared to residential deployment.
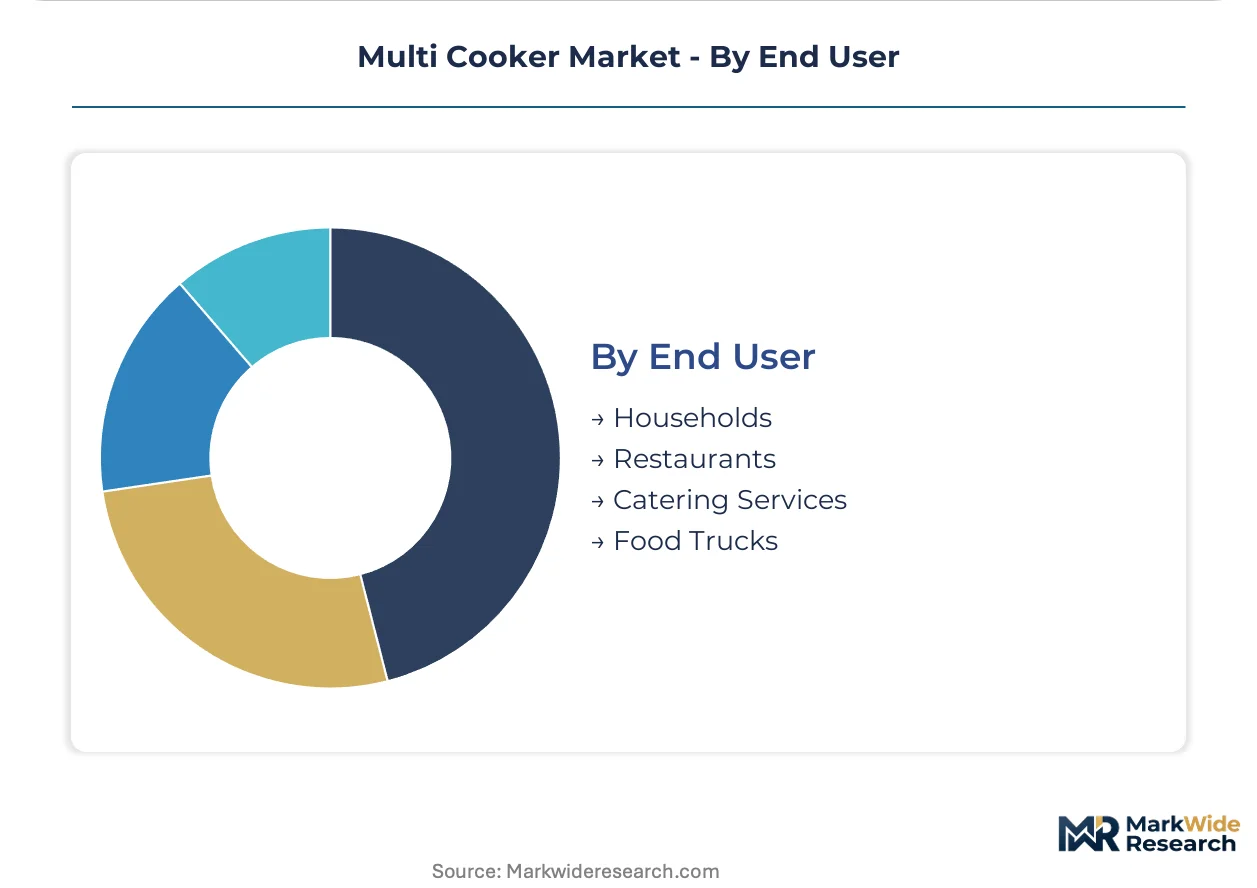
- Households:Residential purchasers prioritizing countertop consolidation and programmable convenience. U.S. premium kitchen appliance spending outpaces other national markets, with direct-to-consumer subscription bundles displacing traditional retail attachment strategies.
- Restaurants:Full-service operators requiring NSF-certified construction and rapid cycle times. European cloud kitchen proliferation is reshaping procurement patterns toward multi-function equipment replacing discrete warming stations.
- Catering Services:Mobile food preparation operations demanding portable vessels with generator compatibility. Equipment-as-a-service leasing arrangements are emerging here to align capital expenditure with event revenue cycles.
- Food Trucks:Severely space-constrained operators optimizing throughput per square foot. California and Texas meal-kit providers are piloting hardware-software bundles with recipe feedback loops optimizing appliance firmware.
Revenue concentration sits with Households. Steepest expansion trajectory belongs to Food Trucks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting multi cooker assembly toward jurisdictions with streamlined pressure vessel certification pathways, while energy-efficiency mandates in high-income markets force product redesigns that elevate unit costs.
United States
Smart home integration and premium kitchen appliance spending outpace other national markets. The U.S. Consumer Product Safety Commission and Underwriters Laboratories govern lid-locking mechanism standards, extending certification timelines. California and Texas meal-kit providers pilot hardware-software bundles with recipe feedback loops optimizing appliance firmware.
China
Shenzhen and Dongguan manufacturing clusters dominate component sourcing for non-smart technology tiers. MIIT electrical safety standards and GB standards for household appliances shape export-ready product configurations. Zhengzhou-based fabricators supply stovetop vessels for Indonesian rural electrification programs.
Germany
Commercial leasing models for industrial-scale vessels are shifting revenue from unit sales to predictive maintenance contracts. The EU Ecodesign Directive and F-Gas Regulation enforce standby power limits and passive thermal management requirements. Bavarian appliance divisions accelerate R&D into vacuum-insulated retention vessels.
India
Cloud kitchen proliferation in urban centers drives commercial procurement of multi-function appliances replacing discrete warming stations. BIS certification requirements govern mechanical lid-locking specifications for pressure cookers. Maharashtra and Karnataka host delivery-optimized ghost kitchen clusters standardizing on sealed-vessel designs.
Indonesia
PLN's rural grid expansion and government appliance subsidy programs open first-time buyer segments in Java and Sumatra. The country's national energy regulator shapes electrification timelines affecting appliance adoption curves. Surabaya and Bandung distribution hubs channel conventional heating units into subsidy-eligible households.
Multi Cooker Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with household purchasers responding to brand equity while commercial operators prioritize equipment durability and service contracts. The vendor base concentrates around three tiers: premium precision-cooking specialists, mid-tier scale manufacturers, and value-oriented OEM suppliers. Strategic moves center on smart technology licensing partnerships and backward integration into heating element supply chains.
Within the premium-tier vector, Breville and Sage exemplify precision temperature control positioning, while Instant Pot anchors brand loyalty in North American retail channels. Ninja occupies a scale-driven position across mid-tier electric and pressure cooker lines. Zavor and Cosori represent specialized entrants competing on feature density at accessible price points. Chef iQ and Our Place sit within the connected-appliance archetype pursuing direct-to-consumer subscription bundling strategies.
| Leading Market Players |
|---|
| Zavor |
| Cosori |
| Instant Pot |
| Our Place |
| Chef iQ |
| Ninja |
| Sage |
| DeLonghi |
| Breville |
| Others |
Cost & Logistics Intelligence
EU Ecodesign standby power mandates and UL certification backlogs are compressing procurement timelines for U.S. and European buyers, forcing manufacturers to absorb compliance costs or sacrifice margin on mid-tier electric multi cookers while redirecting assembly toward Southeast Asian jurisdictions with streamlined pressure vessel pathways.
Pricing Analysis
Retailer markup layers in U.S. big-box channels capture the dominant margin extraction, with three-tier pricing structure across premium, standard, and economy levels stratifying by smart connectivity certification and voice-assistant integration. Price differentiation hinges on UL/CE tier and after-sales service bundling. Pricing pressure stems from stainless steel surcharges and single-function appliance substitution in entry tiers. Food truck operators show highest price sensitivity; premium smart-home households show least.
Supply Chain Analysis
Firmware engineering scarcity in Shenzhen and Dongguan clusters is elevating labor costs for smart-enabled production lines, with assembly drawing from Chinese component foundries, Korean steel mills, and Taiwanese semiconductor packaging. Raw material dependencies center on 304-grade stainless sheet, induction heating ICs, and pressure vessel gaskets. Single-source vulnerability concentrates in lid-locking mechanism suppliers. Distribution runs through Indonesian rural subsidy programs, Indian cloud kitchen procurement, and European commercial leasing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU regulatory compliance costs and Southeast Asian manufacturing scale defines viable entry strategies, with Indonesia's PLN electrification subsidies offering 40-60% cost absorption against German vacuum-insulation R&D requirements.
For Market Incumbents: Deepen backward integration into heating element supply chains to offset Korean steel price volatility, while accelerating Matter/Thread protocol certification to defend against Shenzhen sensor-fusion licensors collapsing precision-cooking premiums. Prioritize captive induction coil production. For New Entrants and Emerging Players: The mid-tier price-point gap between Breville precision units and Indonesian subsidy-eligible conventional models offers white-space targeting. Penetrate Brazilian food truck fleets and Indian cloud kitchen clusters through equipment-as-a-service leasing with predictive maintenance attachments. For Investors and Strategic Acquirers: Asymmetric upside sits with connected-appliance firmware platforms possessing OTA update architectures, as meal-kit hardware-software bundles shift revenue from transactional unit sales to recurring recipe-data subscriptions. Watch cloud kitchen standardization rates as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Protocol Certification | Matter/Thread interoperability unlocks premium pricing among Alexa and Google Home ecosystem participants. |
| Induction Heating Module Integration | Precision electromagnetic elements from Korean suppliers cut preheat latency and elevate consumer satisfaction scores. |
| Commercial Leasing Model Deployment | Equipment-as-a-service arrangements align food truck capital expenditure with event revenue cycles. |
| Vacuum-Insulated Retention Vessel R&D | Passive thermal management satisfies EU F-Gas Regulation without mechanical refrigeration circuits. |
| Direct-to-Consumer Subscription Bundling | California meal-kit providers feed recipe data back to optimize appliance firmware performance. |
Research Approach
Bottom-up household and commercial end-use modeling reconciled against top-down manufacturing capacity tracking forms the analytical core. Primary interviews with appliance OEM procurement directors, cloud kitchen operators, food truck fleet managers, and retail category buyers combined with secondary validation from U.S. CPSC recall databases, EU Ecodesign compliance filings, BIS certification registries, and customs trade records. Triangulation across supply-side bill-of-materials analysis and demand-side sell-through data ensures coverage integrity.
Historical trendline analysis of electric multi cooker shipments, pressure cooker adoption curves, and smart technology penetration rates anchored projection frameworks across the analysis window. Segmentation dimensions modeled include product architecture, capacity band, heating technology tier, and end-user procurement pattern. CAGRs derived from fitted growth curves adjusted for regulatory phase-in schedules and subsidy program timelines. Forecast inputs incorporated PLN electrification rollout pace and UL certification backlog durations.
Caveats apply where EU F-Gas Regulation enforcement intensity or Indonesian subsidy program renewal could materially shift the outlook. Forecasts reflect assumptions about stainless steel price stabilization and cloud kitchen proliferation sustaining equipment consolidation trends. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Global Commercial Dishwashers Market
Food Service Equipment
Food Display Counter Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
Food Serving Equipment Market
Food Service Equipment
Countertop Griddle Market
Food Service Equipment
North America Commercial Dishwashers Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Commercial Stainless Steel Cooking Equipment Market
Food Service Equipment
Commercial Food Warming and Holding Equipment Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Portable Cooler Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
North America Fountain Dispenser Equipment Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Slow Cooker and Sous Vide Market