
 Nugget Ice Machines Market | 2026-2036
Nugget Ice Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Nugget Ice Machines Market Analytics
Energy Star certification and NSF sanitation standards are redrawing competitive tiers in the nugget ice machine category. Scotsman leverages its vertical integration in compressor technology to sustain premium positioning across healthcare and foodservice channels. Hoshizaki anchors its market presence through specialized water-cooled systems that dominate high-humidity coastal installations. Follett differentiates via compact under-counter designs that control space-constrained segments in hospitals and quick-service restaurants.
Nugget ice machines produce compressed flaked ice with a chewable texture, operating through auger-driven extrusion at output temperatures near 22°F for optimal beverage displacement and rapid cooling. Commercial kitchens, bars, and healthcare facilities deploy these units for their high surface-area-to-mass ratio that chills drinks without dilution. Modular machines lead volume shipments due to scalable output configurations, while countertop units capture the fastest expansion as small cafes and boutique bars prioritize footprint efficiency. Air-cooled technology occupies the dominant share in dry climates, though hybrid systems are gaining traction where water restrictions and energy costs create dual-optimization pressure.
The US Department of Energy enforces minimum efficiency standards that shape compressor and heat exchanger specifications, while NSF International mandates sanitation protocols for ice contact surfaces in commercial settings. The EU F-Gas Regulation restricts refrigerant selections, pushing manufacturers toward lower-GWP alternatives that redesign system architectures. Japan's METI efficiency labeling program creates tiered market access conditions that favor technology leaders. Stakeholders must monitor refrigerant transition timelines and regional efficiency tier migrations to align product portfolios with tightening compliance thresholds.
Market Dynamics
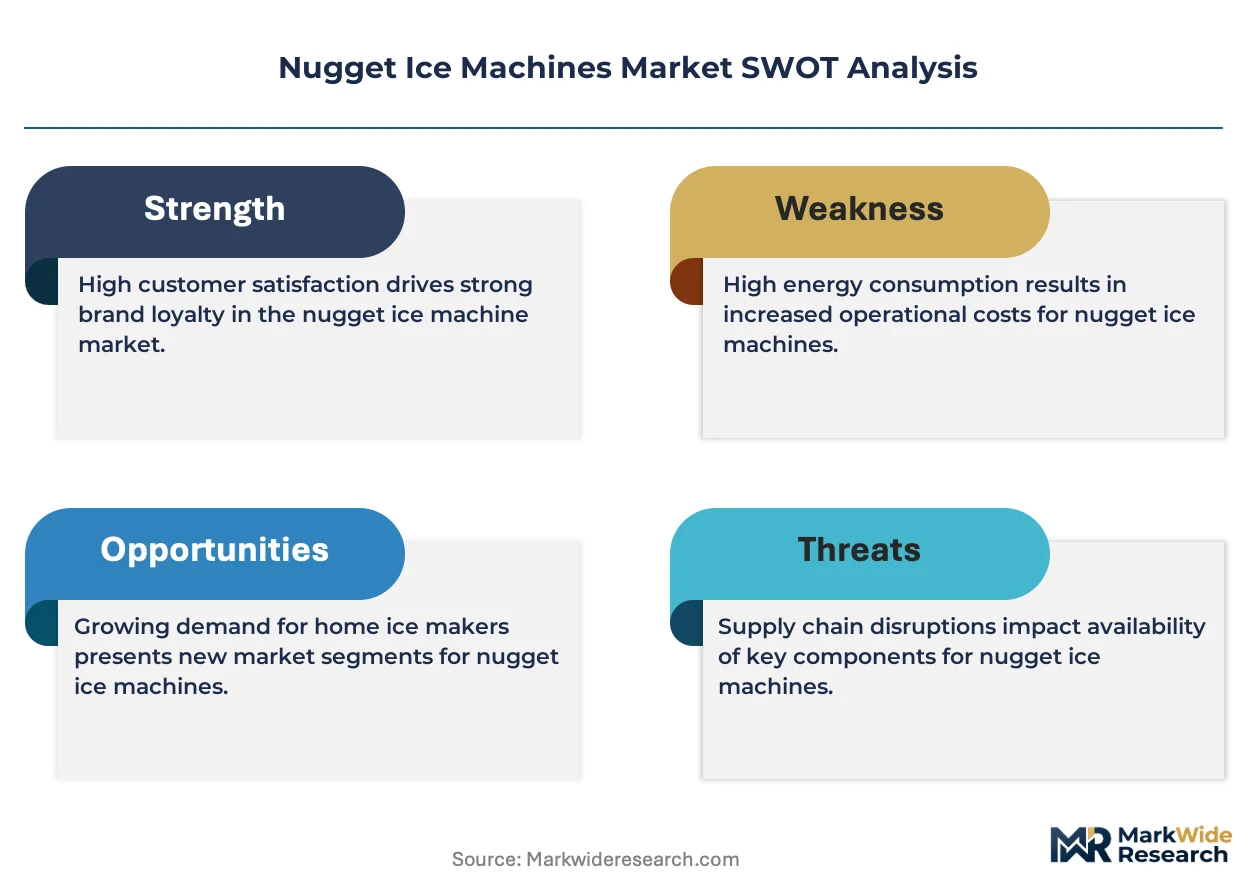
Energy efficiency mandates from the US Department of Energy and Japan's METI are compressing product lifecycles and forcing redesigns of compressor architectures and heat exchanger specifications across the nugget ice machine category.
Growth Catalysts
- Healthcare hydration protocols:Patient care facilities in the United States are standardizing chewable ice for dysphagia management and post-operative recovery, expanding institutional procurement volumes.
- F-Gas Regulation transition:The European Union's refrigerant phase-down is accelerating adoption of lower-GWP alternatives that favor air-cooled and hybrid system architectures over legacy water-cooled designs.
- Quick-service beverage programs:Coffee chains and fast-casual restaurants in China are retrofitting front-of-house stations with under-counter nugget ice units to support carbonated and frozen drink menus.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger materials face input cost swings that compress margin structures for mid-tier equipment manufacturers.
- Compressor supply concentration:Sourcing dependency on specialized refrigeration compressor suppliers in Germany and Japan creates bottleneck risk during demand surges.
- Water-cooled system restrictions:Municipal water use ordinances in drought-prone US states are constraining deployment of traditional water-cooled machines in high-output commercial settings.
Strategic Opportunities
- India foodservice modernization:Organized restaurant chains in Mumbai and Delhi are upgrading from flake to nugget ice for beverage presentation, creating first-mover positioning for compact modular systems.
- Remote monitoring convergence:Integration of IoT sensors with predictive maintenance platforms is enabling outcome-based service models that lock in long-term customer relationships.
- US Inflation Reduction Act incentives:Commercial kitchen equipment efficiency rebates are subsidizing replacement cycles for aging ice machines in institutional foodservice operations.
Industry Challenges
- Refrigerant technician scarcity:The transition to lower-GWP chemistries requires specialized handling certifications that the HVAC workforce has not yet scaled to match equipment deployment timelines.
- NSF/ANSI 7 compliance timelines:Sanitation certification for ice contact surfaces involves extended laboratory testing that delays product launches by six to twelve months.
- Legacy control system integration:New energy-optimized machines must interface with existing building management protocols in retrofit installations, adding commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nugget Ice Machines Market |
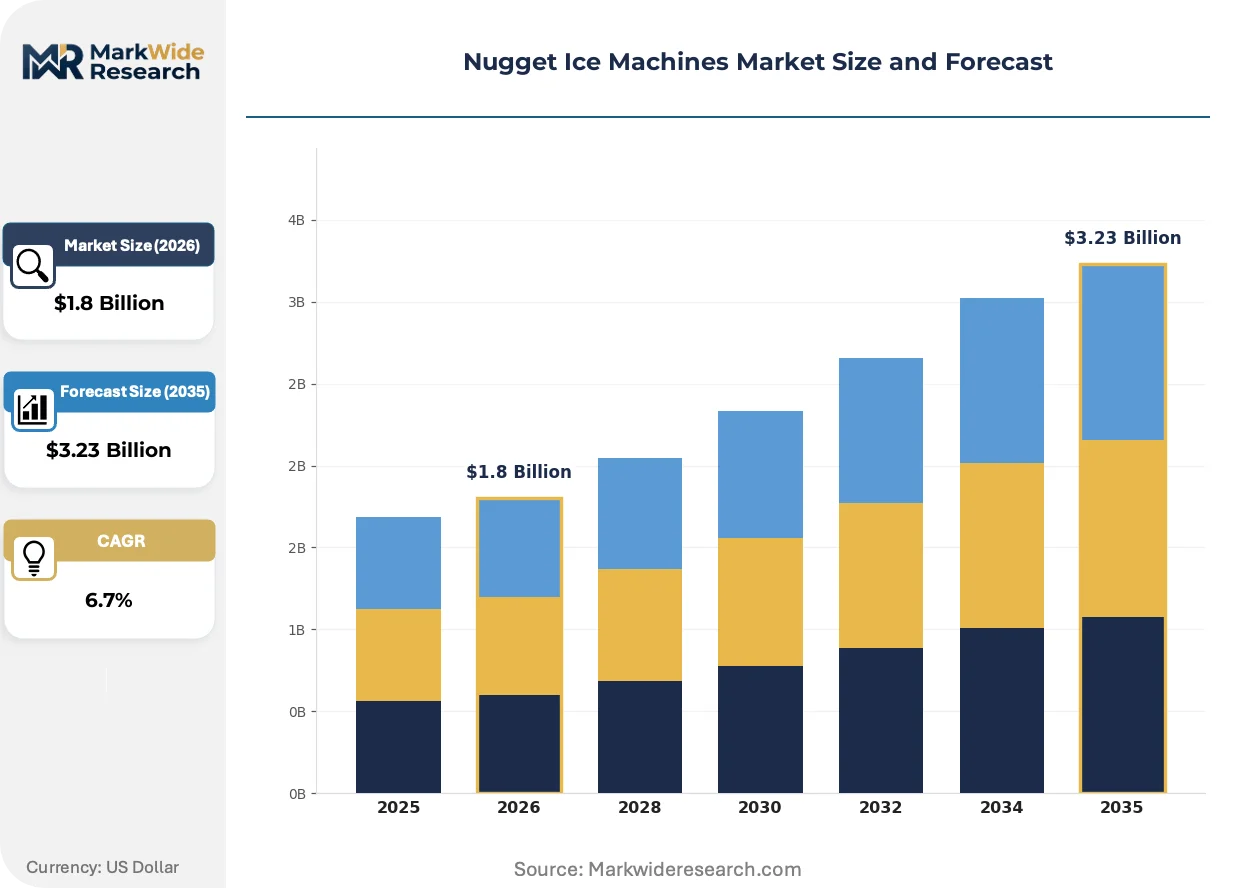
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Machines, Modular Machines, Built-in Machines, Under-counter Machines End User: Restaurants, Bars, Cafes, Healthcare Facilities Technology: Air-Cooled, Water-Cooled, Remote-Cooled, Hybrid Systems Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Scotsman, Manitowoc, Hoshizaki, Ice-O-Matic, Follett, Cornelius, Frigidaire, GE, GoveeLife, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nugget Ice Machines Market Evolving Landscape
Equipment architecture is pivoting toward intelligent thermal management and connected service models that redefine how operators procure, maintain, and upgrade ice production capacity.
Variable-speed compressor technology is supplanting fixed-speed designs in premium nugget ice machines. Hospital cafeterias and high-volume bars in Texas and Florida are specifying these units for load-matched output that trims electricity consumption during off-peak hours. The shift is compressing demand for conventional single-speed compressors and rewarding suppliers with in-house inverter control capabilities.
The EU F-Gas Regulation is forcing refrigerant portfolio transitions across European supply chains. Manufacturers must redesign system architectures around R290 (propane) and R744 (CO2) alternatives that demand smaller charge sizes and redesigned safety protocols. German and Italian commercial kitchen distributors are prioritizing air-cooled nugget ice machines that sidestep water-cooled regulatory complexity entirely.
After-sales service unbundling is fragmenting traditional distribution relationships. Large US foodservice management companies are contracting directly with national service networks for parts and labor, bypassing equipment dealers who previously captured recurring revenue. This pattern is most visible in contract feeding operations for corporate campuses and university dining halls, where procurement teams negotiate multi-site maintenance agreements separate from capital purchases.
Nugget Ice Machines Market Segmentation
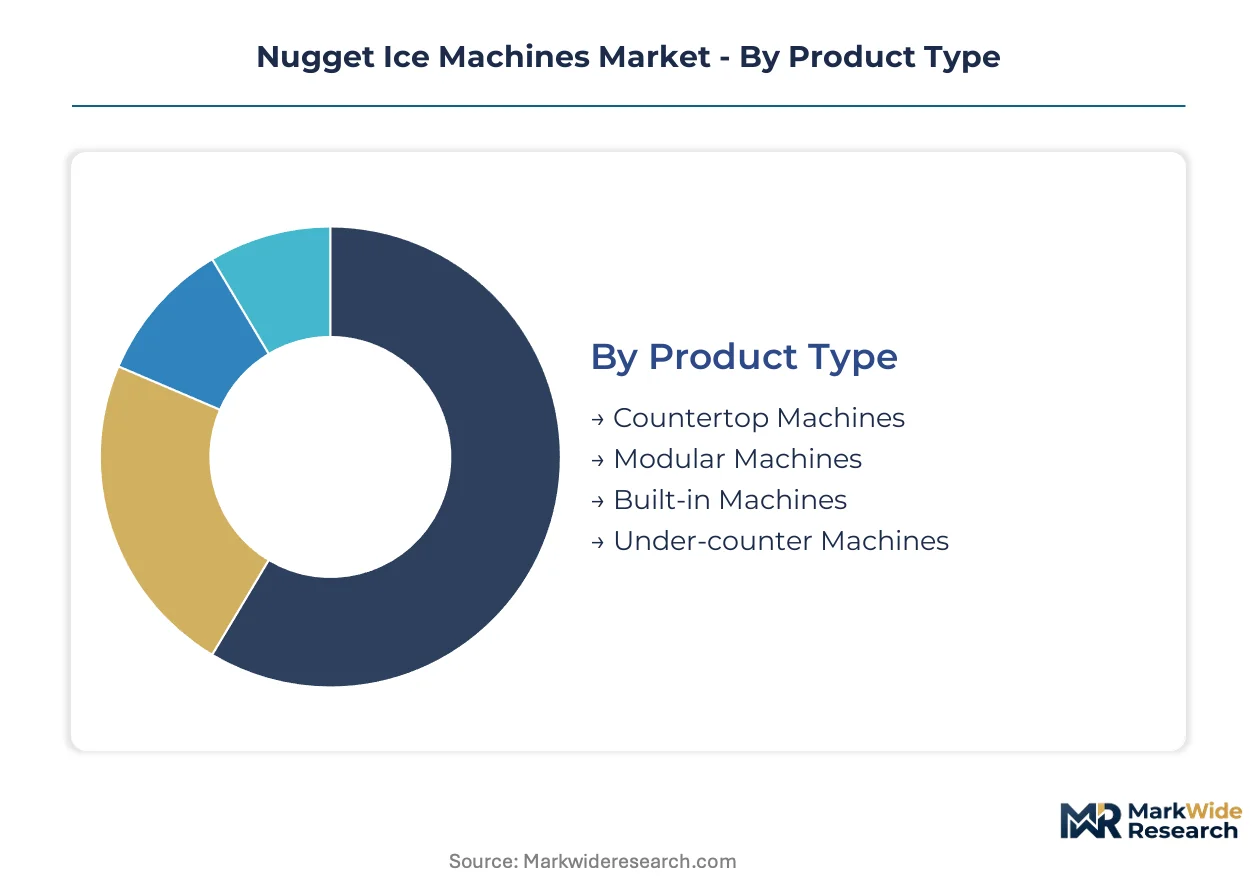
Segmentation in nugget ice machines reveals how regulatory pressure and operational constraints reshape procurement patterns across foodservice and healthcare verticals. Equipment specifications diverge sharply based on climate zone, sanitation mandates, and facility infrastructure.
Product Type:
NSF sanitation certification and DOE efficiency tiers create divergent compliance burdens across form factors.
- Modular Machines:Scalable output configurations mount on top of storage bins or dispensers, enabling hospitals in Texas and Florida to match ice production to patient census fluctuations. These units dominate institutional procurement volumes where NSF/ANSI 7 compliance is mandatory for ice contact surfaces.
- Countertop Machines:Compact self-contained designs with integrated storage occupy front-of-house positions in quick-service restaurants across China. Their footprint efficiency accelerates retrofit adoption as beverage programs expand carbonated and frozen drink menus.
- Built-in Machines:Flush-mount integration with cabinetry serves premium residential and corporate hospitality installations requiring aesthetic concealment.
- Under-counter Machines:Space-optimized dimensions fit beneath standard bar heights, controlling deployment in boutique bars and compact hospital cafeterias where floor space commands premium valuation.
Established volume favors Modular Machines; emerging adoption favors Countertop Machines.
End User:
Application-specific hydration protocols and beverage presentation standards drive specification divergence.
- Healthcare Facilities:Dysphagia management protocols in US patient care facilities standardize chewable ice for post-operative recovery and swallowing disorder treatment. Medicare reimbursement patterns and Joint Commission standards institutionalize procurement at scale.
- Restaurants:Organized chains in Mumbai and Delhi upgrade from flake to nugget ice for beverage presentation, creating first-mover positioning for compact modular systems in India's modernizing foodservice sector.
- Bars:High-volume cocktail operations in coastal markets prioritize rapid chilling with minimal dilution, favoring machines with 22°F output temperatures.
- Cafes:Coffee chains deploy under-counter units for iced espresso and cold brew programs where equipment visibility conflicts with interior design.
Procurement scale concentrates in Healthcare Facilities; menu innovation propels Restaurants.
Technology:
Water restrictions and energy cost structures determine cooling architecture selection.
- Air-Cooled:Ambient heat rejection through finned coils dominates dry climate installations, avoiding water consumption that triggers municipal use ordinances in drought-prone US states. DOE minimum efficiency standards shape compressor and heat exchanger specifications.
- Hybrid Systems:Dual-mode operation switches between air and water cooling based on load and ambient conditions, gaining traction where water restrictions and energy costs create optimization pressure in coastal and desert markets simultaneously.
- Water-Cooled:Refrigerant condensing via water loops persists in high-humidity coastal installations where air-cooled efficiency degrades, though deployment faces tightening municipal constraints.
- Remote-Cooled:Condenser units mounted externally reduce heat and noise in interior spaces, serving high-end hospitality where guest experience prioritizes acoustic control.
Climate adaptation favors Air-Cooled; regulatory hedging favors Hybrid Systems.
Distribution Channel:
After-sales service unbundling fragments traditional dealer relationships across procurement models.
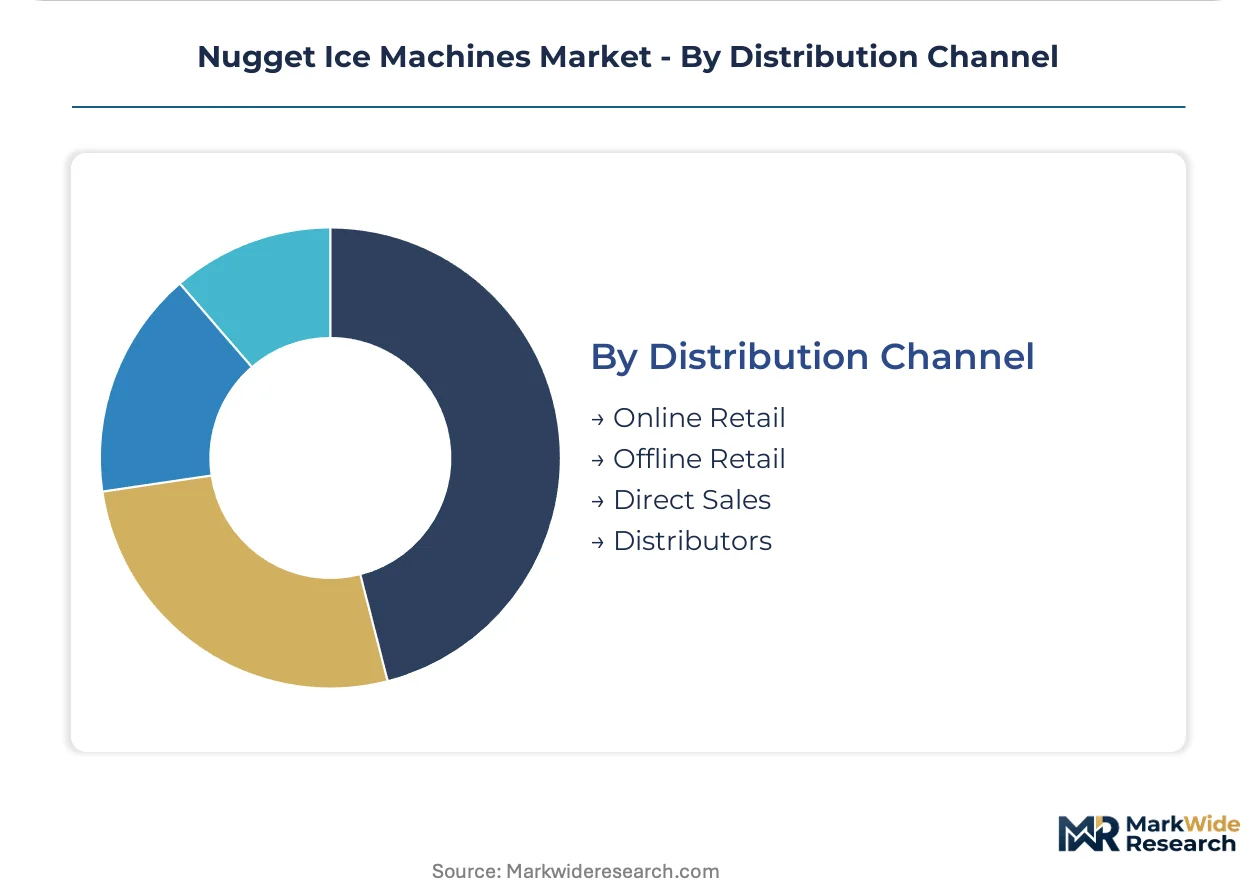
- Direct Sales:National foodservice management companies contract directly with manufacturers for multi-site deployments, bypassing distributors to negotiate separate maintenance agreements for corporate campuses and university dining halls.
- Distributors:Regional equipment dealers maintain local inventory and installation capability, capturing replacement cycles in independent restaurants and standalone healthcare facilities.
- Online Retail:E-commerce platforms serve small cafes and residential buyers with standardized configurations, though NSF certification requirements limit commercial-grade transactions.
- Offline Retail:Brick-and-mortar showrooms enable hands-on evaluation for premium built-in and under-counter selections in residential and boutique commercial segments.
Relationship control favors Direct Sales; service proximity favors Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US manufacturers export nugget ice machines to healthcare networks across Canada and Mexico, while Japanese and German producers supply precision cooling systems to Southeast Asian foodservice chains. Trade corridors concentrate equipment flows from established industrial clusters to institutional buyers upgrading commercial kitchen infrastructure.
United States
Hospital systems in Texas and Florida standardize chewable ice protocols for dysphagia patients, driving replacement cycles in patient care facilities. The US Department of Energy enforces minimum efficiency standards that reshape compressor and heat exchanger specifications. Equipment procurement concentrates in Dallas-Fort Worth and Houston, where foodservice management companies negotiate multi-site maintenance agreements for corporate campus dining operations.
China
Coffee chains and fast-casual restaurants retrofit front-of-house stations with under-counter units to support carbonated and frozen drink menus. The country's national efficiency labeling program creates tiered market access conditions that favor technology leaders. Manufacturing clusters in the Yangtze River Delta supply compact modular systems to modernizing restaurant chains in Mumbai and Delhi through export channels.
Japan
METI efficiency labeling programs compress product lifecycles and force redesigns of refrigeration architectures. Specialized water-cooled systems dominate high-humidity coastal installations from Osaka to Fukuoka. Domestic producers anchor supply relationships with healthcare facilities across East Asia, leveraging proximity to institutional buyers in Seoul and Singapore.
Germany
The EU F-Gas Regulation restricts refrigerant selections, pushing manufacturers toward lower-GWP alternatives that redesign system architectures. Industrial distributors in Bavaria and North Rhine-Westphalia prioritize air-cooled machines that sidestep water-cooled regulatory complexity. German compressor suppliers face sourcing dependency risks as demand surges strain specialized component availability.
India
Organized restaurant chains in Mumbai and Delhi upgrade from flake to nugget ice for beverage presentation, creating first-mover positioning for compact modular systems. The country's national standards body regulates commercial kitchen equipment safety and energy performance. Procurement volumes concentrate in Maharashtra and Karnataka, where international hotel chains specify built-in machines for premium hospitality installations.
Nugget Ice Machines Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and geographic coverage dimensions. The vendor base spans three tiers: diversified refrigeration conglomerates with captive compressor production, specialized ice equipment fabricators with regional service networks, and appliance brands leveraging consumer distribution for commercial crossover. Strategic moves concentrate on M&A for service network expansion and portfolio diversification into connected monitoring platforms.
Within the diversified refrigeration tier, Scotsman and Hoshizaki exemplify archetypes that anchor premium positioning through vertical control over critical components. Follett occupies a specialist position exemplifying compact design optimization for space-constrained segments. Among appliance-sector entrants, GE and Frigidaire represent commercial crossover strategies that leverage consumer brand recognition for institutional procurement channels.
| Leading Market Players |
|---|
| Scotsman |
| Manitowoc |
| Hoshizaki |
| Ice-O-Matic |
| Follett |
| Cornelius |
| Frigidaire |
| GE |
| GoveeLife |
| Others |
Value Network & Pricing Analysis
Propane refrigerant substitution for legacy hydrofluorocarbons is redrawing manufacturing footprints toward German and Italian assembly plants while compressing margin structures for equipment manufacturers absorbing safety-protocol redesign costs. This chemistry transition simultaneously elevates air-cooled system premiums and erodes water-cooled price positioning across European distribution channels.
Pricing Analysis
Next-generation variable-speed compressor machines command 25-40% premiums over fixed-speed legacy units, while prior-generation water-cooled designs face accelerating price erosion in drought-prone US states. Three-tier pricing structure across premium inverter-controlled, standard fixed-speed, and economy remanufactured levels stratifies procurement decisions. Price differentiation hinges on DOE efficiency tier certification and NSF/ANSI 7 sanitation compliance grade. Pricing pressure stems from copper and aluminum heat exchanger input volatility that compresses mid-tier manufacturer margins. Independent restaurants and small cafes exhibit highest price sensitivity, while hospital systems purchasing through GPO contracts demonstrate lowest sensitivity due to bundled service agreements.
Supply Chain Analysis
Specialized refrigeration compressor sourcing from Germany and Japan creates a chokepoint that constrains output scaling during demand surges in Texas and Florida healthcare markets. Manufacturing concentration centers on China, the United States, and Italy for finished machine assembly, with component sourcing drawing from Japanese inverter control suppliers and German heat exchanger fabricators. Raw material dependencies span copper tubing, aluminum fins, and specialized refrigerant-grade steel. Single-source vulnerability in compressor supply creates bottleneck risk when institutional procurement cycles synchronize. Distribution runs through regional equipment dealers for independent facilities and direct manufacturer contracts for multi-site foodservice management companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against flake ice and pellet ice alternatives that threaten nugget ice positioning in beverage programs and patient hydration protocols.
For Market Incumbents: Consolidate service network density in Texas and Florida hospital corridors to lock in replacement cycle capture before efficiency mandate redesigns disrupt installed base loyalty. Deepen backward integration into compressor inverter controls to offset German and Japanese supplier concentration risk. Prioritize NSF/ANSI 7 certification maintenance as a barrier against emerging Asian competitors lacking laboratory testing infrastructure. For New Entrants and Emerging Players: NSF certification fast-track through third-party laboratory partnerships in the United States opens procurement access to Medicare-reimbursed healthcare facilities. Target India's modernizing restaurant chains in Mumbai and Delhi with compact modular systems sized for kitchen retrofit constraints. Lead with remote monitoring integration as a service differentiator against legacy equipment lacking IoT connectivity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed foodservice equipment rollups holding fragmented regional service networks across the US Sun Belt. Five-to-ten year viability hinges on refrigerant transition execution and connected platform monetization rather than hardware margin sustainability. Watch for METI efficiency tier migration announcements in Japan as signal for technology-refresh inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Portfolio Transition | R290 and R744 adoption satisfies EU F-Gas Regulation while forcing safety-protocol redesigns. |
| IoT-Enabled Predictive Maintenance | Sensor integration locks in recurring revenue through outcome-based service contracts with hospital systems. |
| Compact Modular System Launch | Footprint-optimized designs penetrate India's upgrading restaurant chains and space-constrained cafes. |
| Direct Service Network Expansion | Bypassing regional dealers captures multi-site maintenance agreements from foodservice management companies. |
| Variable-Speed Compressor Integration | Inverter-controlled systems command premium positioning under DOE efficiency tier structures. |
Research Methodology
Initial hypotheses were tested against primary input from commercial kitchen equipment procurement directors, hospital biomedical engineering managers, foodservice chain operations executives, and regional equipment dealer principals and refined through secondary validation against DOE efficiency standard filings, NSF certification registries, EU F-Gas Regulation implementation reports, and METI labeling program documentation. Bottom-up shipment data from compressor suppliers and heat exchanger fabricators was triangulated against top-down procurement surveys across healthcare and foodservice verticals.
Variance decomposition across product type, cooling technology, end-user vertical, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by efficiency tier adoption curves and refrigerant transition timelines. Forecast inputs incorporated hospital patient census projections, quick-service beverage menu expansion rates, and municipal water restriction ordinance propagation patterns.
Underlying assumptions cover stable copper and aluminum commodity price bands, with deviation risk concentrated in compressor supply disruption and refrigerant technician certification scaling shortfalls. Forecasts reflect these documented conditions. Revision becomes warranted when EU F-Gas phase-down acceleration or US DOE tier advancement crosses implementation thresholds ahead of modeled timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Food Waste Disposers Market
Food Processing Equipment
Multi Ovens Market
Food Processing Equipment
Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
Europe Household Food Waste Composting Machine Market
Food Processing Equipment
Global Carbonated Beverage Processing Equipment Market
Food Processing Equipment
Electric Kebab Machine Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Fish Cutting Machine Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Pet Food Processing Market
Food Processing Equipment
US Cold Storage Market