
 Electric Meat Saw Market | 2026-2036
Electric Meat Saw Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Meat Saw Market Foresight
Butcher trade school enrollment shortfalls across industrialized meat-processing regions is redrawing equipment procurement priorities toward semi-automatic and robotic operation modes. Hobart leverages its century-long brand strength in North American foodservice channels to sustain dealer loyalty. Marel anchors its position through upstream control over sensor-integrated cutting software. Bizerba differentiates via precision weighing-blade integration that occupies a narrow premium niche in European supermarket chains.
An electric meat saw is a motorized cutting machine employing a continuous band blade or reciprocating blade, typically powered by a 1.5 to 5 horsepower motor, designed to section carcasses and primal cuts with clean bone separation in commercial protein-processing environments. Band saws dominate installed bases due to blade economy and deep-throat cutting geometry, though robotic operation modes represent the fastest-growing configuration as processors automate breakdown lines to offset labor scarcity. Stainless steel construction leads material specifications because regulatory auditors mandate non-porous, corrosion-resistant surfaces that withstand caustic washdown cycles.
USDA inspection protocols and NSF/ANSI sanitation standards govern blade-guard design and clean-in-place accessibility in the United States, while EU hygiene regulations and CE marking requirements shape motor-housing sealing and emergency-stop placement across European installations. The divergence between OSHA machine-guarding mandates and EU Machinery Directive safety categories forces multinationals to maintain dual certification portfolios. Stakeholders must weigh capital allocation between robotic retrofit kits and full line replacements as sanitation standards tighten and skilled maintenance technician availability narrows further.
Market Dynamics
Butcher trade school enrollment shortfalls across industrialized meat-processing regions are redrawing equipment procurement priorities toward semi-automatic and robotic operation modes, compressing replacement cycles and elevating total cost-of-ownership calculations in purchasing committees.
Growth Catalysts
- EU hygiene regulations:Tightening blade-material requirements under EU hygiene regulations and CE marking mandates are accelerating stainless steel specification upgrades across German, Dutch, and Danish processor fleets.
- Robotic operation modes:Automated cutting lines are capturing procurement attention as North American commercial butcher shops confront rising labor costs and shrinking skilled-operator pools.
- Mid-sized processor modernization:Germany's aging band saw installed base is driving concentrated demand for NSF/ANSI-compliant replacement units with integrated clean-in-place systems.
Market Restraints
- High-grade stainless steel input costs:Volatility in nickel and chromium prices compresses margin structures for manufacturers committed to regulatory-grade construction.
- Skilled maintenance technician scarcity:Narrowing availability of technicians certified in both mechanical band systems and programmable logic controllers extends downtime exposure for automated installations.
- Manual cleaver substitution:Small-scale processors in emerging markets retain traditional breakdown methods where capital constraints and intermittent electricity supply limit electrification.
Strategic Opportunities
- Robotic retrofit kits:Sensor-integrated blade guidance packages offer an intermediate automation path for processors unwilling to commit to full line replacement.
- Precision weighing-blade integration:European supermarket chains are creating a premium niche for equipment combining real-time portion control with cutting operations.
- OSHA machine-guarding mandates:Compliance deadlines for enhanced blade-guard design are opening replacement windows across US federally inspected facilities.
Industry Challenges
- Dual certification portfolio maintenance:Multinationals must simultaneously satisfy OSHA machine-guarding mandates and EU Machinery Directive safety categories, fragmenting engineering resources.
- Legacy system integration complexity:Retrofitting robotic control modules onto existing band saw frames requires custom mechanical interfaces that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Meat Saw Market |
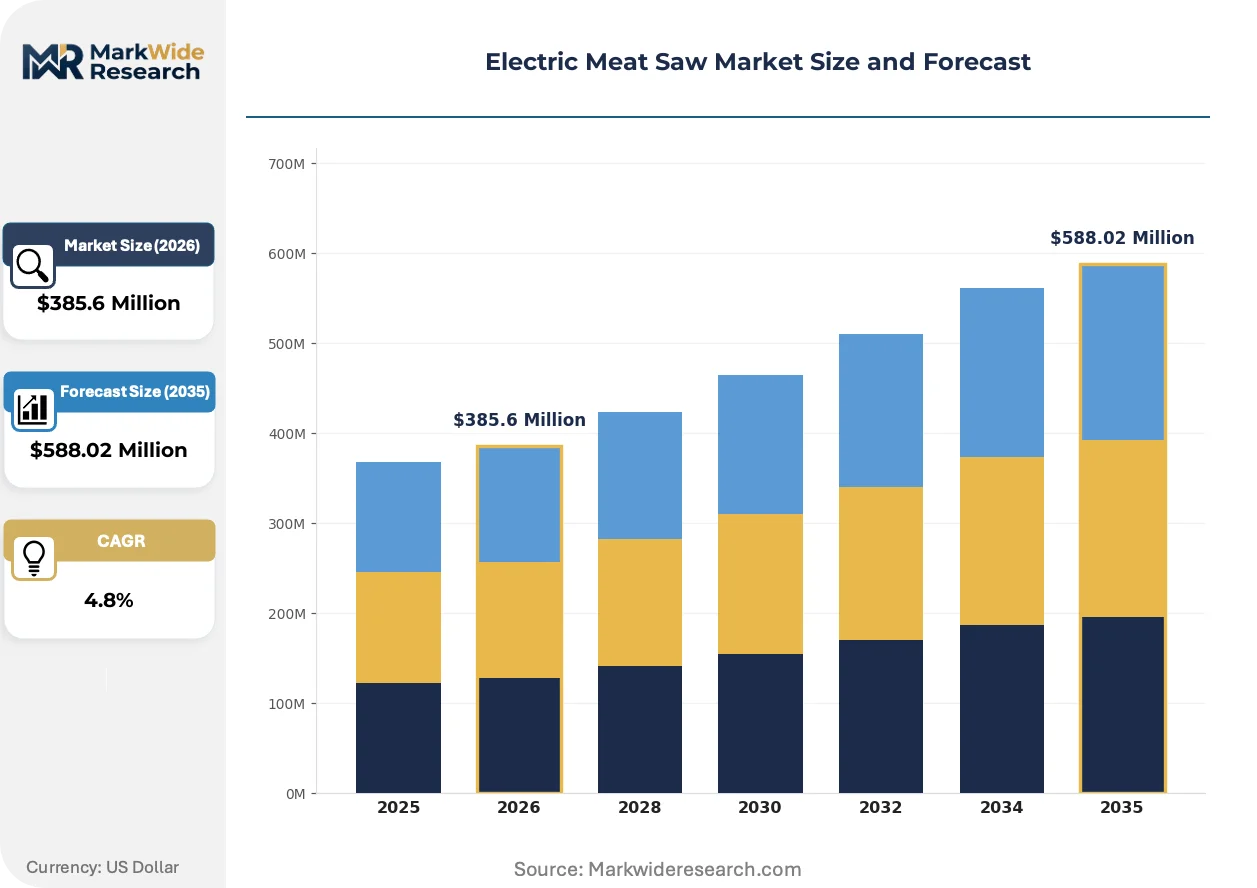
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Saws, Band Saws, Circular Saws, Table Saws End User: Butcher Shops, Supermarkets, Restaurants, Meat Processing Plants Material: Stainless Steel, Aluminum, Plastic, High Carbon Steel Operation Mode: Manual, Semi-Automatic, Fully Automatic, Robotic |
| Companies Covered | BIRO Manufacturing, Butcher Boy Machines International, Hobart, Marel, Bizerba, Kolbe, Skyfood Equipment, ProCut, Dongqing Kitchen Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Meat Saw Market Shifts & Advancements
Sensor-integrated cutting software is actively reshaping competitive positioning, compressing the boundary between mechanical precision and data-driven yield optimization while forcing traditional manufacturers into capability acquisitions.
Continuous band blade systems with embedded load-cell feedback are displacing conventional fixed-speed drives in high-volume breakdown operations. Large North American beef processors are adopting these configurations fastest, lured by real-time bone-density compensation that reduces blade drift and extends service intervals. The technology is displacing manual operator judgment in primal separation tasks, compressing training requirements while elevating throughput consistency.
EU Machinery Directive safety category upgrades are mandating redundant emergency-stop circuits and sealed motor housings across European installations. These requirements are elevating capital costs for entry-tier equipment while creating compliance-driven replacement cycles in facilities with pre-2017 installed bases. German mid-sized processors are responding fastest, bundling sanitation audits with equipment procurement to secure financing.
Leasing structures with bundled preventive maintenance are displacing outright purchase models among capital-constrained regional processors. Independent distributor networks in the US Great Plains are pioneering this shift, replacing traditional equipment sales with per-cut fee arrangements that transfer blade-wear risk. The model is most visible in Nebraska and Kansas cattle-processing clusters, where processor liquidity constraints meet distributor inventory financing capabilities.
Electric Meat Saw Market Segmentation
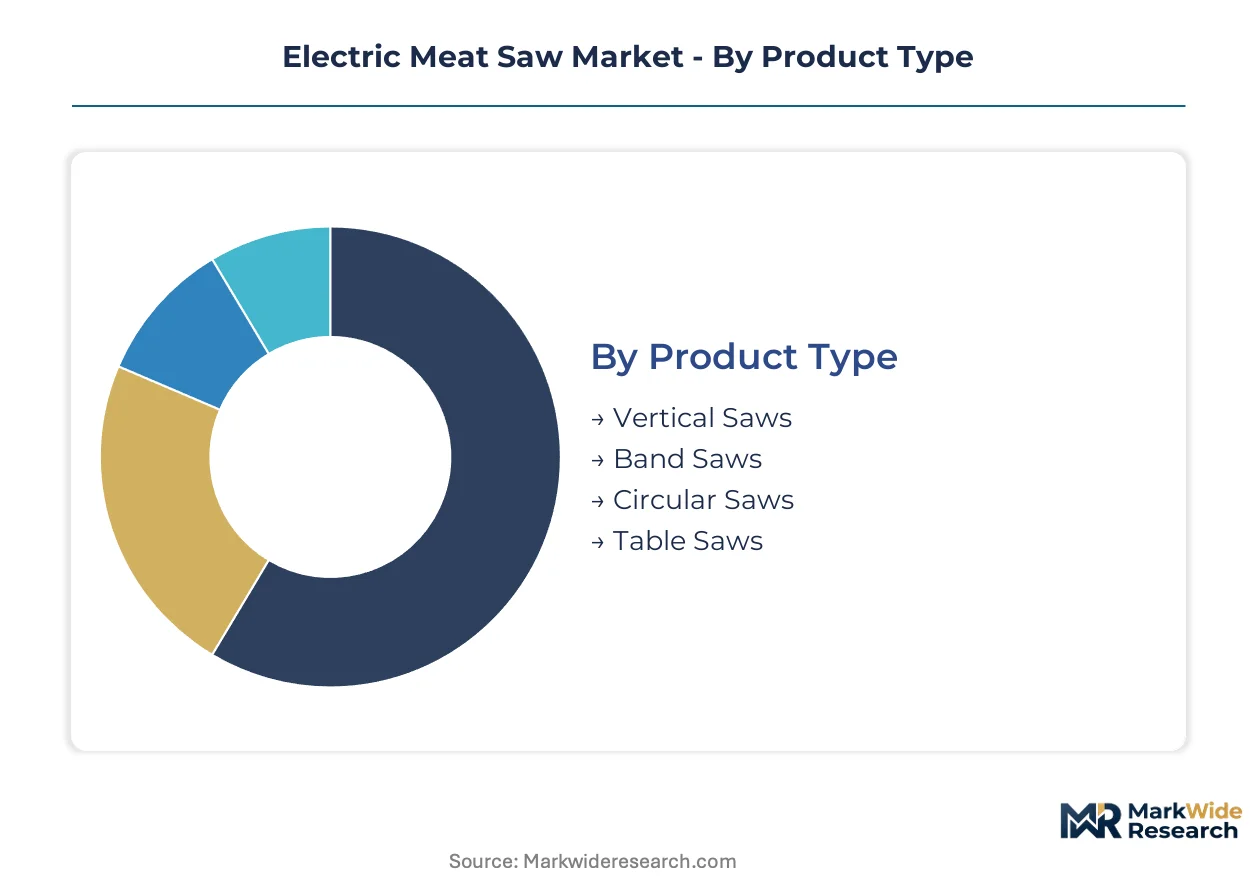
Equipment procurement committees segment purchases across blade geometry, operational automation, and regulatory-grade materials. Channel mix varies sharply: butcher shops favor semi-automatic band configurations, while meat processing plants drive robotic adoption.
Product Type:
Channel distribution splits sharply between independent dealer networks serving small-scale operators and direct OEM sales penetrating high-volume processing chains.
- Band Saws:Continuous loop blades running 1.5 to 5 horsepower motors dominate commercial breakdown operations for primal cuts and bone separation. German mid-sized processors are modernizing aging fleets here, driven by EU hygiene regulation tightening on blade-material specifications and clean-in-place accessibility.
- Vertical Saws:Upright blade orientation with gravity-fed carcass positioning suits high-throughput beef and pork breakdown lines. North American commercial butcher shops expanding automated cutting lines are concentrating demand in this configuration as labor costs rise and skilled-operator pools shrink.
- Circular Saws:Rotary blade systems handle specialized portioning tasks in smaller footprint operations.
- Table Saws:Bench-mounted reciprocating configurations serve low-volume specialty processors and training facilities.
Band saws dominate installed base. Vertical saws are where expansion concentrates.
End User:
Margin structures diverge across customer tiers, with capital-constrained independents prioritizing lease arrangements and bundled maintenance over outright purchase.
- Meat Processing Plants:High-volume federated facilities operating USDA-inspected lines require NSF/ANSI-compliant configurations with redundant safety circuits and sealed motor housings. These operators are capturing procurement attention for robotic operation modes as they automate breakdown lines to offset labor scarcity and compress training requirements.
- Butcher Shops:Independent and small-chain operators favor semi-automatic band saw configurations with stainless steel construction meeting caustic washdown cycles. Trade school enrollment shortfalls across industrialized regions are redrawing equipment priorities toward simpler operator interfaces here.
- Supermarkets:European chains are creating premium niches for precision weighing-blade integration combining real-time portion control with cutting operations.
- Restaurants:Commercial kitchens and central commissaries select compact table-mounted units for intermittent breakdown tasks.
Meat processing plants command the highest automation specification. Butcher shops represent the broadest volume base.
Material:
Regulatory auditors mandate non-porous, corrosion-resistant surfaces that withstand aggressive sanitation protocols, elevating premium-grade specifications.
- Stainless Steel:Austenitic grades with elevated chromium and nickel content provide non-porous surfaces that withstand caustic washdown cycles and satisfy NSF/ANSI sanitation standards. Regulatory mandates from USDA inspection protocols and EU hygiene regulations are accelerating specification upgrades across German, Dutch, and Danish processor fleets.
- High Carbon Steel:Blade-grade alloys with superior edge retention suit cutting surfaces subject to abrasive bone contact.
- Aluminum:Lightweight housings reduce transport and installation burdens for mobile or seasonal operations.
- Plastic:Polymer guards and non-structural components lower capital costs for entry-tier equipment in emerging markets.
Stainless steel leads material specifications. High carbon steel concentrates in blade components where edge geometry dominates performance.
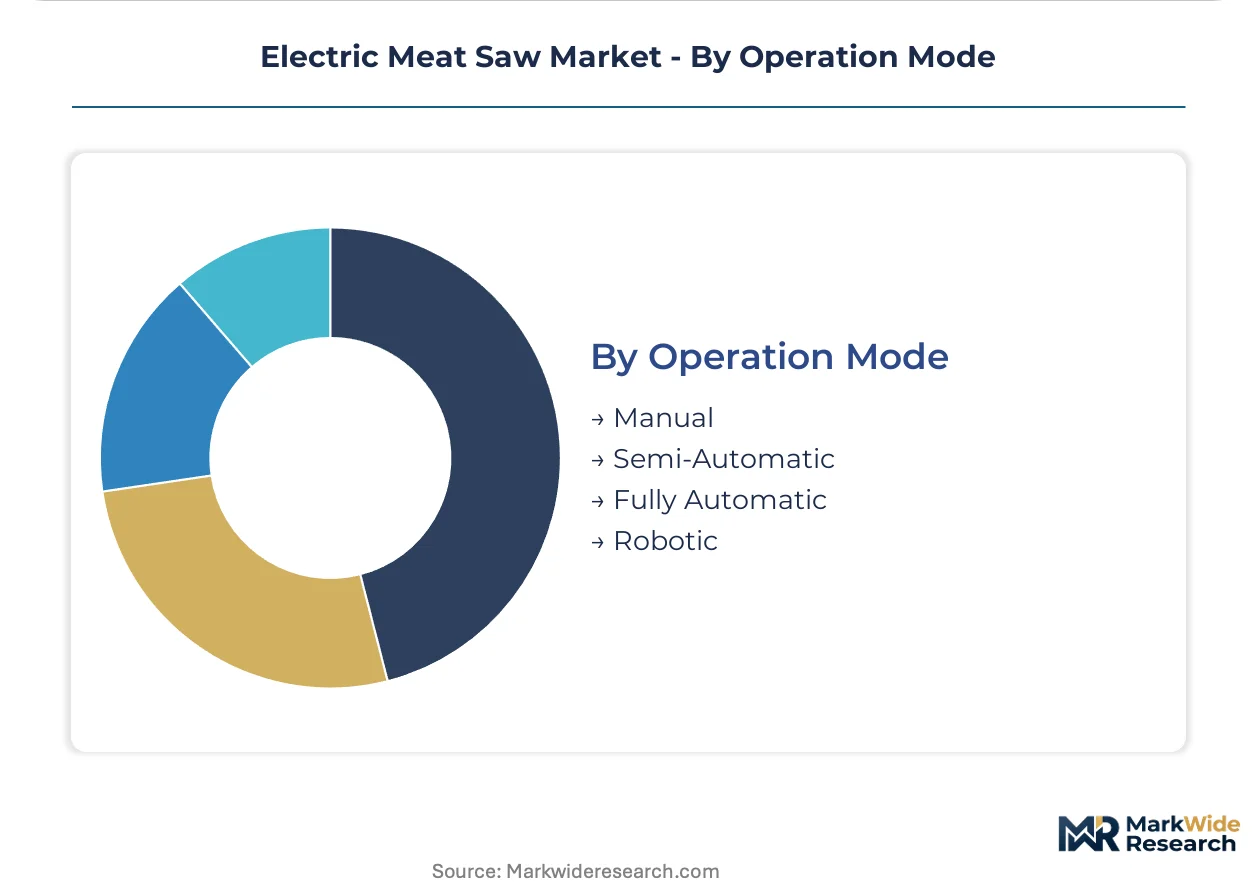
Operation Mode:
Capital allocation decisions weigh retrofit feasibility against full line replacement as sanitation standards tighten and skilled maintenance technician availability narrows.
- Robotic:Sensor-integrated blade guidance with programmable logic controllers and real-time bone-density compensation reduces blade drift and extends service intervals. Large North American beef processors are adopting these configurations fastest, lured by throughput consistency and compressed training requirements.
- Semi-Automatic:Operator-supervised cutting with automated feed mechanisms and emergency-stop integration balances labor reduction with capital constraint. Independent distributor networks in the US Great Plains are pioneering lease structures with bundled preventive maintenance here, replacing traditional equipment sales with per-cut fee arrangements.
- Fully Automatic:Unattended operation sequences suit dedicated high-volume lines with standardized product mixes.
- Manual:Hand-fed configurations persist in small-scale emerging market operations where capital constraints and intermittent electricity supply limit electrification.
Semi-automatic configurations dominate current installed base. Robotic operation modes are climbing the fastest as processors automate breakdown lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German processors command pricing premiums for NSF/ANSI-compliant stainless steel configurations, while Brazilian operators absorb cost disadvantages from import duties on high-grade nickel alloys. This asymmetry shapes procurement patterns across both mature and emerging protein-processing corridors.
United States
USDA-inspected beef processors in Nebraska and Kansas are consolidating automated cutting lines as labor scarcity intensifies. OSHA machine-guarding mandates for enhanced blade-guard design are accelerating replacement windows across federally inspected facilities. The Great Plains cattle-processing cluster is pioneering lease structures with bundled preventive maintenance that transfer blade-wear risk from operators to distributors.
Germany
Mid-sized processors in Lower Saxony and Bavaria are modernizing aging band saw fleets installed before 2017. EU Machinery Directive safety category upgrades mandate redundant emergency-stop circuits and sealed motor housings, elevating capital costs for entry-tier equipment. The Ruhr industrial corridor is bundling sanitation audits with equipment procurement to secure financing for stainless steel specification upgrades.
Netherlands
Dutch pork processors in Gelderland are adopting sensor-integrated blade guidance with real-time bone-density compensation to reduce blade drift. EU hygiene regulations are tightening blade-material requirements and clean-in-place accessibility standards. The Eindhoven food technology cluster is supplying programmable logic controllers to automated breakdown lines serving export-oriented slaughterhouses.
China
Domestic beef processors in Shandong and Henan provinces are expanding electrified cutting capacity as cold chain infrastructure penetrates inland markets. GB standards for food machinery hygiene are converging with international sanitation protocols, though intermittent electricity supply in western regions limits full automation. The Yangtze River Delta meatpacking corridor is absorbing surplus stainless steel fabrication capacity from adjacent industrial machinery sectors.
Brazil
Beef exporters in São Paulo and Mato Grosso are retrofitting semi-automatic configurations to maintain throughput amid skilled-operator shortages. ANVISA sanitary regulations for industrial food equipment are elevating documentation burdens for imported machinery. The southern Brazil protein-processing belt is balancing capital constraints against EU export compliance requirements that mandate specific blade-material certifications.
Electric Meat Saw Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The vendor base spans century-old foodservice equipment specialists, integrated processing technology conglomerates, and regional fabrication houses serving price-sensitive emerging markets. Three archetypes dominate: sensor-integrated automation providers, precision weighing-blade integrators, and stainless steel construction specialists. Competitive moves concentrate on robotic retrofit kit development and dual certification portfolio maintenance for simultaneous OSHA and EU Machinery Directive compliance.
Within the integrated automation tier, Marel and Bizerba exemplify divergent specialization paths—Marel anchoring upstream control over cutting software, Bizerba occupying precision weighing-blade integration for European supermarket chains. Hobart represents the established foodservice channel archetype, leveraging century-long dealer network loyalty in North American commercial butcher shops. Among regional fabricators, Dongqing Kitchen Equipment sits within the cost-optimized construction segment serving capital-constrained operators in Asia-Pacific protein-processing corridors.
| Leading Market Players |
|---|
| BIRO Manufacturing |
| Butcher Boy Machines International |
| Hobart |
| Marel |
| Bizerba |
| Kolbe |
| Skyfood Equipment |
| ProCut |
| Dongqing Kitchen Equipment |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for NSF/ANSI-certified stainless steel band saw frames concentrate pricing power with German and Dutch fabricators possessing pre-qualified component inventories, while spot-market nickel volatility feeds back into procurement committees favoring long-term supply agreements over transactional purchasing.
Pricing Analysis
German processors absorb fifteen-to-twenty percent premiums over Brazilian operators for identical NSF/ANSI-compliant configurations, reflecting EU Machinery Directive certification costs and sealed-motor-housing specifications. Pricing stratifies across robotic, semi-automatic, and manual tiers, with sensor-integrated blade guidance commanding substantial premiums over conventional fixed-speed drives. Cost compression in entry-tier equipment is intensifying because nickel and chromium price volatility squeezes margin structures for manufacturers committed to regulatory-grade austenitic construction. Capital-constrained regional processors in the US Great Plains exhibit highest price sensitivity, leasing equipment with per-cut fee arrangements, while large North American beef processors show lowest sensitivity when robotic operation modes deliver throughput consistency.
Supply Chain Analysis
Strategic stockpiling of high-grade stainless steel dominates procurement strategy among German and Dutch OEMs, insulating against nickel price spikes, while just-in-time component flows persist for programmable logic controllers sourced from the Eindhoven food technology cluster. Supply concentrates in Germany, the Netherlands, and China, with the Yangtze River Delta meatpacking corridor absorbing surplus stainless steel fabrication capacity from adjacent industrial machinery sectors. Raw material dependencies rest on nickel and chromium alloys for corrosion-resistant construction, high-carbon steel for blade edge retention, and specialized polymers for guard assemblies. Single-source vulnerability concentrates in sensor-integrated cutting software modules controlled by integrated processing technology conglomerates. Distribution runs through independent dealer networks serving small-scale operators and direct OEM sales penetrating high-volume processing chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from manual cleaver retention in emerging markets and robotic portioning systems displacing traditional breakdown lines, requiring defensive capability investments to preserve installed base relationships.
For Market Incumbents: Compound dealer loyalty through bundled preventive maintenance contracts that transfer blade-wear risk, while securing upstream control over sensor-integrated cutting software to block modular retrofit kit competitors from fragmenting the automation tier.
For New Entrants and Emerging Players: Aftermarket service capacity shortages in the US Great Plains cattle-processing cluster offer immediate white-space penetration, targeting capital-constrained regional processors with lease structures and per-cut fee arrangements rather than competing for direct OEM sales at large federated facilities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic operation mode configurations, favoring asset-light software specialists over stainless steel fabrication houses over the coming decade. Acquisition targets should display dual certification portfolio maintenance capabilities for simultaneous OSHA and EU Machinery Directive compliance. The signal to watch is bundling penetration rates of sanitation audits with equipment procurement in German mid-sized processor financing structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Retrofit Kit Development | Sensor-integrated blade guidance packages capture processors unwilling to commit to full line replacement. |
| Dual Certification Portfolio Maintenance | Simultaneous OSHA machine-guarding and EU Machinery Directive compliance fragments engineering resources but secures multinational procurement access. |
| Backward Integration into Cutting Software | Upstream control over programmable logic controller algorithms blocks modular competitors from displacing mechanical precision advantages. |
| Lease Structure with Bundled Maintenance | Per-cut fee arrangements in Nebraska and Kansas transfer blade-wear risk while capturing processor liquidity constraints. |
| Precision Weighing-Blade Integration | Real-time portion control combined with cutting operations occupies premium niches in European supermarket chains. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with equipment procurement committees, maintenance directors at meat processing plants, aftermarket service heads, and distribution channel partners; and secondary validation through USDA inspection protocol documentation, EU Machinery Directive safety category filings, SEC 10-K disclosures from listed processing technology conglomerates, and customs records tracking stainless steel band saw frame imports. Bottom-up triangulation across facility-level procurement patterns and top-down reconciliation against manufacturer shipment data anchored volume and value estimates.
Across the modeling period, projections incorporate blade geometry segmentation, operational automation tiers, regulatory-grade material specifications, and end-user facility scale. CAGRs were derived from segment-level growth rate reconciliation against macro protein-processing capacity expansion indicators, incorporating skilled maintenance technician availability indices and butcher trade school enrollment trajectories as demand-side constraints.
Underlying assumptions cover nickel price stabilization, EU hygiene regulation enforcement continuity, and cold chain infrastructure penetration rates in inland Chinese markets, with deviation risk concentrated in commodity input volatility and intermittent electricity supply limitations in western Chinese provinces. Revision becomes warranted when robotic retrofit kit adoption rates cross thresholds that fragment replacement cycle timing across installed base cohorts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Commercial Kettles and Braising Pans Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Granular Ice Machine Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Frozen Food Processing Machinery Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
Food Sterilization Equipment Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Food Processing Blades Market
Food Processing Equipment
Ice Cream Equipment Market
Food Processing Equipment
Oven Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Decanter Centrifuge Market